




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Release | Feb 7, 2024

Image by Freepik
WonderFi's latest update highlights significant user growth, strategic acquisitions, and partnerships that broaden its service offerings and market reach. These milestones are not just numbers; they represent a strategic positioning that could redefine competitive dynamics in the fintech sector.
By analyzing the synergies between WonderFi and its acquisitions, we can better understand the strategic foresight behind these decisions.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Research | Feb 7, 2024

Image: BoE Staff Working Paper No. 1,059
The Bank of England recently published Staff Working Paper No. 1,059 titled "Customer data access and fintech entry: early evidence from open banking" The research on Open Banking (OB) policies provides substantial evidence that implementing OB can indeed improve competition and productivity within a country and offers valuable insights into its impact on fintech entry, consumer benefits, and SME outcomes.
One of the most striking outcomes of OB policies is the substantial increase in fintech entry and innovation. The study reveals that the adoption of OB policies has led to a one-third increase in venture capital-backed fintech financings and a doubling in the investment amounts. This surge in fintech activity is indicative of a more competitive environment driven by the availability of customer financial data, spanning a wide array of financial products, including financial advice applications, credit services, payments, and regulatory technology (regtech), underscoring the versatility and utility of OB data across the financial ecosystem. This innovation is not limited to fintech startups but extends to existing financial institutions that adapt to the new competitive landscape by offering more tailored and efficient services.
Countries with OB policies have about twice as many banks offering APIs compared to those without such policies. This increase in API offerings is a direct indicator of OB's role in enhancing data sharing in the financial services industry, thereby promoting competition among banks and fintech companies.
The research finds a strong positive association between OB policies and economic characteristics such as GDP per capita and population, suggesting that countries adopting OB are likely to see enhanced economic activity and productivity as a result of increased competition and innovation in the financial sector.
For consumers, the benefits of OB are twofold: enhanced financial knowledge and improved access to credit products. These findings underscore OB's potential to empower consumers with the tools and information necessary to make informed financial decisions.
OB is shown to enhance utility, entry, and competition in business-to-business products and SME credit markets. This indicates an improvement in the overall productivity of the financial sector, as SMEs benefit from better access to financial services and advice.
Eligibility for OB has been linked to a higher likelihood of SMEs forming new lending relationships, especially with non-bank lenders, facilitating increased access to finance. This is particularly significant for SMEs with prior lending relationships, who are more likely to secure new loans and benefit from lower interest rates.
The findings are clear: countries embracing OB witness a remarkable uptick in fintech innovation and entry, backed by an increase in venture capital investments. This innovation extends beyond new market entrants, encouraging traditional financial institutions to adapt and thrive in a rejuvenated competitive landscape. The doubling of banks offering APIs in OB-adopting countries further cements OB's role in fostering a more open, competitive, and innovative financial services industry.
Moreover, the positive correlation between OB policies and key economic indicators underscores the broader economic upliftment potential of OB, promising enhanced productivity and economic activity. For consumers and SMEs alike, the advent of OB heralds a new era of financial well-being and inclusion, offering improved access to credit, enhanced financial knowledge, and greater opportunities for growth and development.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Consultation | Feb 1, 2024

Image by storyset on Freepik
The Canadian government is consulting on strengthening competition in the financial sector. This consultation seeks input on potential reforms to improve competition, consumer choice, and access to financial services in Canada. It aims to address the evolving financial landscape and ensure a competitive, innovative, and consumer-focused financial sector. Stakeholders are encouraged to contribute their views and ideas.
The process for bank mergers and acquisitions in Canada involves the Minister of Finance's approval under the Bank Act. This act allows the Minister to consider various factors, including the interests of the Canadian financial system.
Decisions are guided by assessments from the Office of the Superintendent of Financial Institutions (OSFI) and reviews by the Competition Bureau. The Department of Finance is now exploring how to improve this process to enhance competition, considering additional factors for decision-making and measures to address market concentration and entry barriers.
The Canadian government is seeking input on key questions to enhance competition in the financial sector.
These questions focus on:
All submissions for this consultation will be open until March 1, 2024. Email them your comments and feedback at legreview-examenleg@fin.gc.ca with "Consultation on Concentration in the Banking Sector" in the subject line.
Comments and feedback may also be sent by mail to:
Manuel Dussault
Director General
Financial Institutions Division
Financial Sector Policy Branch
Department of Finance Canada
90 Elgin Street
Ottawa ON K1A 0G5
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Report | Feb 1, 2024

While the 163 page PDF report covers a plethora of innovations and emerging and converging technologies, this article will look at specific projections providing a roadmap for how innovations in public blockchains, digital wallets, smart contracts, and artificial intelligence (AI) could transform industries and economies over the next decades.
Public blockchains are set to redefine financial ecosystems by facilitating the migration of all money and contracts onto platforms that ensure digital scarcity and proof of ownership. This shift anticipates a significant reconfiguration of financial systems to accommodate cryptocurrencies and smart contracts, marking a transition towards a digital-first economy.
By 2030: Cryptocurrencies are anticipated to account for about 10% of the global money supply, driven by institutional and high net worth individual investments, nation-state treasuries, and adoption in emerging markets for remittances and global settlements. Cryptocurrencies, particularly Bitcoin, are expected to continue displacing gold as a store of value, capturing 40% of the market. With a projected market value scaling to $5.2 trillion by 2030 for decentralized applications, the economic impact and investment opportunities within this domain are vast and ripe for exploration by fintech innovators and investors alike.
By 2040: Cryptocurrencies could largely replace permission-based, centrally controlled monetary systems, reformulating financial ecosystems around digital assets that facilitate transaction flows without counterparty risk. This transformation could begin at the fringes of the financial system, particularly in geographies with inefficient banking systems, and gradually extend to developed markets.
By 2030: Digital wallets are likely to become primary financial interfaces for the majority of smartphone users, facilitating more than half of all meaningful financial functions. These platforms are projected to disrupt traditional banking relationships by offering wholesale pricing of financial services and becoming pivotal in e-commerce and other digital services.
By 2040: Digital wallets are projected to close the loop with two-sided networks, offering a suite of financial services tailored to the needs of specific industries. They could enable fully closed payment ecosystems, with platforms like Block, Shopify, and Toast potentially leveraging digital wallets to facilitate transactions and monetize deposits. Vertical software platforms serving merchants with financial services through digital wallets are expected to disintermediate merchant banking, significantly enhancing convenience and reducing the number of steps from payment authorization to merchant settlement.
Smart contracts present an automated, global, and auditable alternative to traditional financial intermediaries, offering a transparent and efficient way to manage contracts and transactions on the blockchain.
By 2030: Smart contracts are projected to secure less than 5% of global financial assets by GDP through decentralized protocols, a rate consistent with the early adoption curve of the internet. These protocols, along with application protocols, are expected to significantly reduce the fees extracted by traditional financial institutions, fostering a more efficient and transparent financial ecosystem.
By 2040: Most contracts might migrate to open-source protocols that enable and verify digital scarcity and proof of ownership, diminishing the role of traditional financial intermediaries. This shift could lead to more transparent risk-sharing arrangements, easier asset securitization, and a substantial decrease in counterparty risks.
AI technology has rapidly evolved, transitioning from simple machine learning algorithms to complex neural networks capable of deep learning and reasoning. This evolution is marked by the development of models like GPT-3 and GPT-4, which have demonstrated capabilities close to human-level language understanding and generation. GPT-3, released by OpenAI, contains 175 billion parameters, making it one of the largest and most sophisticated language models ever created.
AI is already enhancing productivity across various sectors. Tools like GitHub Copilot and AI-driven analytics platforms are automating routine tasks, allowing humans to focus on more complex and creative endeavors. GitHub Copilot has been shown to improve programmer productivity by assisting in code generation and debugging, significantly reducing development time.
By 2030, AI is expected to dramatically increase the productivity of knowledge workers. As AI becomes more integrated into business processes, tasks that currently take hours will be accomplished in minutes. ARK Invest predicts that knowledge worker productivity will quadruple leading to unprecedented growth in GDP and innovation, fostering new industries and reshaping existing ones.
AI in healthcare is set to revolutionize diagnosis, treatment, and patient care by enabling precision medicine and reducing human error. Multiomic data analysis and AI-driven diagnostic tools will offer personalized treatment plans with higher efficacy. AI algorithms are already outperforming human radiologists in detecting certain types of cancer in imaging scans, promising more accurate and earlier diagnoses.
By 2040, AI could become a universal personal assistant, deeply integrated into daily life. From managing schedules to making informed decisions on behalf of users, AI assistants will offer a level of personalization and efficiency previously unimaginable. The integration of AI in smart devices and home systems will make smart homes truly autonomous, adjusting to individual preferences for comfort, security, and energy efficiency without human input.
Future AI systems will not only optimize tasks but also engage in creative processes, contributing to art, literature, and science. AI-driven creativity tools could collaborate with humans to produce novel works and solve complex scientific problems. AI-generated art and music are already blurring the lines between human and machine creativity, suggesting a future where AI partnerships could lead to new artistic movements and scientific breakthroughs.
As AI becomes more pervasive, ethical considerations and governance will take center stage. The development of transparent, fair, and accountable AI systems will be critical to addressing concerns around privacy, bias, and autonomy. Ensuring AI systems make decisions in a way that aligns with human values and ethics requires ongoing research, regulation, and dialogue between technologists, policymakers, and the public.
The concept of the singularity—where AI surpasses human intelligence in all aspects—remains a potent idea for the future. The path toward such an event will be marked by incremental advances, each expanding the boundary of what's possible with AI. The journey toward superintelligent AI poses profound questions about identity, consciousness, and the future of humanity itself, inviting us to reimagine our place in a world where intelligence is no longer uniquely human.
By 2040, these technologies are expected to reshape not just industries and economies, but also the very fabric of daily life, presenting both unparalleled opportunities and challenges.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Report | Jan 31, 2024

INTERPOL recently published a whitepaper providing an insightful analysis of the Metaverse from a law enforcement perspective, focusing on the unique challenges and opportunities it presents from use cases, crimes, forensics, investigations, and governance. The Metaverse, a blend of augmented, virtual, and physical realities, offers a new realm where digital transformation in policing can greatly enhance operational efficiency and public safety. However, it also opens doors to novel criminal activities, termed "Metacrime," requiring new strategies for law enforcement and judicial systems to adapt to this evolving digital landscape.
Metacrime refers to a range of criminal activities that emerge within the Metaverse, a digital realm that blends augmented, virtual, and physical realities. These crimes exploit the unique features and capabilities of the Metaverse, extending beyond traditional cybercrimes to include new, unprecedented forms of illegal activity.
Metacrimes encompass various illegal activities such as:
+ The Metaverse enables advanced training and simulation for law enforcement, creating immersive environments for practicing crisis management and tactics without real-world risks.
+ It also facilitates virtual meetings and operational coordination, offering platforms for information sharing, training, and reconstructing crime scenes virtually for better situational awareness.
- Metacrime includes various illegal activities like NFT frauds, cyber-physical attacks, impersonation by theft of digital identities, theft of virtual assets, grooming of children, and more. INTERPOL's white paper stresses the necessity for a standardized approach to address these challenges, as the Metaverse encompasses multiple jurisdictions and legal ambiguities.
- The Metaverse also presents unique challenges for evidence collection and crime investigation. Traditional physical evidence is replaced by digital interactions, necessitating law enforcement to adapt to new methods for collecting and analyzing digital evidence, such as endpoint forensics, server investigations, and blockchain analytics.
The collaborative effort between INTERPOL, government bodies, and private sectors is essential in shaping a secure Metaverse. This pioneering effort by INTERPOL is a significant step towards tackling the complexities of Metacrime, ensuring a safer and more secure digital world.
Despite its challenges, the Metaverse offers significant opportunities for law enforcement, including advanced simulation for training, virtual crime scene preservation, and immersive training platforms. These advancements can potentially transform law enforcement practices and improve efficiency and effectiveness.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
.
Payments Research | Jan 31, 2024

Image by storyset on Freepik
The 2022 Methods-of-Payment Survey by the Bank of Canada shines light on evolving payment preferences in Canada, spanning over a decade looking at data from 2009 to 2022. The research shows a shift from traditional cash handling to an increasingly digital-centric payment culture through the backdrop of new payment methods like digital currencies and the unprecedented impact of the COVID-19 pandemic.
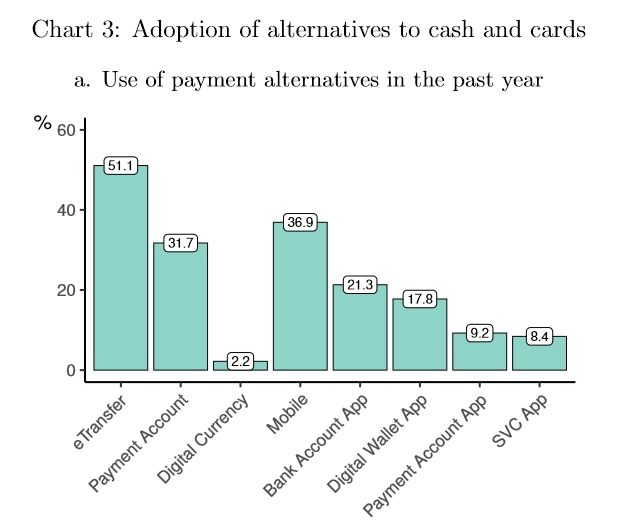
Image: Bank of Canada Payments Landscape 2022 Survey, Chart 3
While digital and contactless payments are on the rise, the enduring role of cash underscores the need for a multi-pronged approach to payment options to ensure inclusivity and accessibility in Canada's financial services, catering to all segments of the population.
As the country progresses further into the digital age, continuous monitoring and adaptable strategies will be essential for financial institutions and policymakers. This approach will ensure alignment with evolving consumer trends and technological advancements.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Innovation | Jan 30, 2024

Image: Unsplash/Max Harlynking
While the fintech industry has long catered to the millennial demographic, it is now recognizing the untapped potential in addressing the unique financial needs of baby boomers. This shift is crucial as boomers represent a substantial portion of the population, with significant economic impact. In the United States alone, boomers make up a large segment of retirees, with numbers expected to reach 72 million by 2035. They control a considerable portion of the country's wealth, with estimates suggesting they own 83 percent of all investable assets, nearly $35 trillion.
Fintech solutions for boomers need to be tailored to their specific life stages and financial challenges. This includes offering support for managing healthcare costs, pensions, and retirement savings, as well as providing avenues for supplemental income. Home equity, which for many boomers is a significant asset, presents opportunities for financial planning and security in retirement.
Given the skepticism and loyalty characteristic of this demographic, fintechs may prefer to collaborate with trusted incumbents rather than positioning themselves as market disruptors.

Image: Bessemer Venture Partners
Fintech for the aging boomer market is about creating user-friendly, efficient, and secure financial solutions that address the unique challenges faced by this demographic. With their substantial wealth and specific needs, boomers represent a significant opportunity for fintech innovation. Note however there is significant competition from incumbent banks and near bank institutions all chasing after this demographic so consider yourself forewarned.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016