




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Canada | January 20, 2026
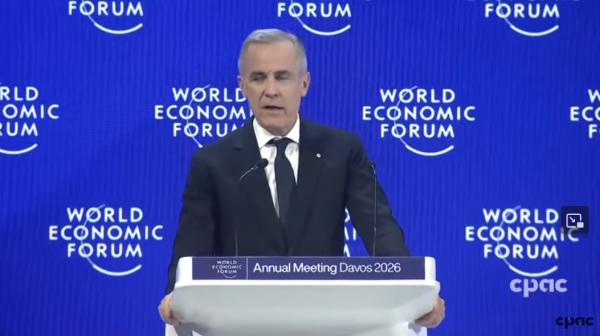
Image: PM Mark Carney, WEF 2026 at Davos
Some speeches try to calm markets. Others try to project confidence. Prime Minister Mark Carney’s special address at the 2026 World Economic Form in Davos does neither. Instead, it speaks plainly about where the world actually is, and Canada's place in it.
Carney doesn't describe today’s global system as temporarily strained or waiting to reset. He treats fragmentation, pressure, and mistrust as conditions we are already living with. Economic openness no longer guarantees cooperation. Integration no longer guarantees stability. For countries like Canada, assuming otherwise is not optimism. It is exposure.
That is why this speech lands with unusual weight. It is not aspirational. It is not dressed up. It is grounded in reality.
A central message running through the address is uncomfortable but clear. The idea that a neutral, rules based international order reliably protects middle powers no longer holds in practice.
Trade becomes leverage. Markets get weaponized. Finance turns into a geopolitical arena. In that environment, scale matters, and countries without it cannot rely on habit or goodwill.
Carney does not try to soften this. He acknowledges directly that economic integration itself can be used as a tool of pressure. That recognition marks a break from the language Canada has leaned on for decades.
For Canadians, the message touches jobs, prices, housing, supply chains, energy, investment, and long term growth. For fintechs and financial institutions, it goes even deeper.
Payments infrastructure, capital markets, data flows, compliance frameworks, and cross border operations all depend on trust based systems. When those systems weaken, risk shows up in cost, friction, and constraint.
Ignoring geopolitics does not insulate innovation. It makes it more fragile.
Another core message in PM Carney's address is that in a fractured world, drift is a decision. It means allowing outcomes to be set by external forces through inaction, habit, or default choices rather than deliberate strategy.
Canada cannot assume that openness will persist by default or that others will protect shared systems out of principle. It has to participate actively in building coalitions, standards, and partnerships that still value predictability and accountability.
That kind of leadership is less comforting than the past. It requires clarity, coordination, and follow through rather than rhetoric.
The delivery matters. Carney speaks without inflated promises. No slogans. Just a steady assessment of risk, responsibility, and constraint shaped by experience inside global financial systems.
PM Mark Carney's speech is candid acknowledgement of a new phase of Canadian engagement with the world. One that names limits, acknowledges pressure, and treats resilience as something that must be designed rather than assumed. That is the work ahead, to modernize Canada’s financial systems and infrastructure with purpose and impact, at scale and with urgency.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
RPAA | January 20, 2026
Image: Freepik
On September 8 2025, the Bank of Canada published a letter to PSPs on a trust tax issue, that said safeguarding end-user funds in “trust” accounts, a requirement under the Retail Payment Activities Act (RPAA), could create unintended tax obligations under the Income Tax Act. The impact threatened to burden PSPs with additional tax filings and compliance complexity for simply holding user funds.
For fintech founders, investors and advisors building or backing PSPs, safeguarding end-user funds is a core requirement of the RPAA. If standard trust arrangements triggered full trust tax treatment, PSPs could end up doing extra tax filings simply to meet payments rules. That would force teams to spend time and money on tax compliance instead of building products, serving customers, or growing the business.
On December 23 2025, the Bank of Canada issued an update that confirmed the Department of Finance proposed changes to the Income Tax Act so that RPAA safeguarding trust arrangements would not be treated as formal trusts for tax purposes. Instead, qualifying arrangements would be treated as deemed loans from end users to PSPs, removing the risk that PSPs would face extra trust tax filings requirements.
The change is intended to apply retroactively to September 8 2025, subject to legislative approval.
The lesson here is that staying engaged with regulators, raising issues early, and participating in public comment or industry groups can help outcomes that materially affect operations and capital efficiency.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Bank of Canada | Speech | December 17, 2025

Image: Freepik/rawpixel.com
On December 16, 2025, Bank of Canada Governor Tiff Macklem delivered a year end speech at the Chamber of Commerce of Metropolitan Montreal called, “Good money and your central bank.” This time instead of focusing on rates or short term market conditions, Macklem spoke about something more foundational. Trust. As money becomes faster, more digital, and more complex, the Bank of Canada is expanding its role to make sure every form of money Canadians use remains safe, convertible, and stable in value.
“At its core, the role of the Bank of Canada is to maintain trust in our monetary system.”
Macklem is clear about where everything starts. Money only works when people trust it to behave the same way tomorrow as it does today. He defines good money as money that trades at par, moves reliably, and holds its purchasing power.
For founders and investors, it explains how the Bank evaluates new ideas. Innovation that makes money easier to use while keeping it predictable fits inside this system. Innovation that introduces uncertainty around access, value, or redemption runs into resistance. Trust is the gate that determines which ideas scale and which ones stall.
“Cash has undeniable benefits. It’s simple, widely accepted, inexpensive to use and reliable.”
Macklem talks about cash because it sets the standard. It works during outages, power failures, and cyber incidents. It does not depend on networks or intermediaries behaving perfectly.
By committing to new bank notes and upgraded security features, the Bank is reinforcing a simple idea. Money must keep working when systems fail. For builders, this is a reminder that how a system behaves under stress matters. For investors, it highlights why resilience is still the core cash test, even as products move further into the digital realm.
“This year, the Bank began overseeing retail payments.”
This changes who sets the rules for payments. Payment service providers now operate inside the same trust framework as banks and other core financial infrastructure. Digital wallets, point of sale platforms, and cross border payment services are no longer treated as peripheral technology layers.
The scale and growth of payments makes the change unavoidable. Canadian payments reached $12.2 trillion in 2024, with digital methods representing the majority of how Canadians move money day to day. Payments are not a niche function. They are the system.
Nearly 1,500 payment service providers must now register under the Retail Payment Activities Act. This aligns with NCFA’s analysis in Canada’s payments innovation push gains speed, which explains how broader access to payment rails comes with higher expectations around safeguarding funds and managing operational risk.
Real Time Rail sits at the center of this change. Instant settlement creates opportunity, but it also removes buffers. When money moves faster, mistakes and failures propagate faster too. That is why oversight and discipline rise alongside speed.
“It is important for Canada to have its own regulatory framework for stablecoins.”
Macklem treats stablecoins as money that must earn trust before it earns scale. Any stablecoin used in Canada must trade at par, be backed by high quality liquid assets, and provide clear redemption terms. It's not about blocking innovation but about making sure innovation behaves like money.
This approach builds on Canadian dollar stablecoin testing with institutional partners, where testing is actively taking place in live environments. All sounds exciting but adoption remains limited. Stablecoin insights from FCAC’s 2025 national survey show that only a small share of Canadians currently hold or use stablecoins. The Bank is clearly designing rules before use expands, not after problems emerge (plus they are playing catch-up on a number of files that have spanned years of industry advocacy).
Open banking follows the same logic. Today, millions of Canadians still share banking credentials through insecure screen scraping. That creates real exposure to fraud and misuse. The consumer-driven open banking framework aims to replace this with secure, permission based data sharing.
Consumer understanding remains uneven. An FCAC survey on Canadian consumer perspectives on open banking shows many Canadians are unclear about how their financial data is accessed and protected. NCFA’s open banking commercialization roadmap for Canada outlines how trust, education, and competition need to advance together for the model to work.
Stablecoins and open banking are treated the same as payment modernization. Innovation is welcome, but only when it strengthens confidence instead than testing it.
“Structural shifts… make global economies increasingly vulnerable to shocks and uncertainty.”
Macklem is describing a reality founders and investors already recognize. Trade relationships change quickly. Technology fails in unexpected ways. Geopolitical risk shows up in supply chains, costs, and access overnight.
In this environment, faster payments and digital money create upside, but they also raise the cost of failure. Systems need to work under pressure, not just in steady conditions. That's why the Bank keeps returning to trust and why it continues to treat inflation control as foundational.
“Good money in all its forms is only as good as its purchasing power.”
Macklem closes with a reminder that no amount of innovation matters if money loses value. Payments, data sharing, and digital instruments all sit downstream from price stability. The Bank remains committed to the 2% inflation target and will review its framework in 2026 to make sure it still works in a more volatile environment. For reference, the Bank of Canada held interest rates steady at 2.25% last Wednesday with no timeline for increases.
For consumers, builders and investors alike, Canada's inflation rate sets the outer boundary. Per Macklem's speech, innovation is scaled inside stability, not outside of it.
What emerges from Macklem’s speech is a Bank of Canada that is now impacting the conditions under which change can scale. By pulling payments, digital money, and data access into a single trust framework, the Bank is defining how money must behave before innovation reaches mass adoption. For Canada’s fintech ecosystem, the most durable opportunities will belong to those who build inside that reality rather than trying to outrun it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulation | December 15, 2025

AI generated image
On December 11, 2025, the Canadian Securities Administrators (CSA) and the Canadian Investment Regulatory Organization (CIRO) released new guidance for finfluencers, investment firms, and issuers on how securities laws apply to online investing activity (Download CSA and CIRO Staff Notice 31-369 13 page PDF). Social media now plays a real role in how Canadians make investment decisions, and regulators expect existing securities law to apply when online influence impacts behaviour. The guidance clarifies when creators must register, how disclosure must work in short-form content, what counts as advice or trading activity, and where firms and issuers remain responsible when they work with finfluencers. Keep reading to learn about the practical implications, including some use case examples covered in the report.
Regulators are responding to what they see in the market today. Social media is no longer a side channel for financial education. It is where many investors first encounter investment ideas, products, and promotions, often without realizing when education turns into influence.
As NCFA previously reported, based on the CSA's 2024 Investor Index, 53% of Canadian investors now use social media as a source of investment information. Among younger investors aged 18 to 24, reliance on social platforms is even higher. Those investors face materially higher risk.
The OSC also tests causation, not just correlation. In a controlled experiment involving 1,465 Canadians managing a simulated $10,000 portfolio, 38% of participants exposed to finfluencer style promotional posts purchased the promoted asset, compared with 8% in the control group. Exposure alone drives different investment choices, even without personalized advice.
Canadian securities regulators examined 87 finfluencers and 9 issuers and repeatedly found undisclosed compensation, promotional framing that functions as recommendations, and content drifting into advising or trading activity without registration.
The CSA and CIRO aren't introducing new rules. They are making it clear how existing securities law already applies when online content influences investment decisions. There's a clear message that Finfluencers should take seriously:
Labels and intent matter less than impact. What counts is how a reasonable investor experiences the content, not how the creator describes it.
Finfluencers need to register when they provide investment advice or help facilitate securities trading for a business purpose, unless a specific exemption applies.
A business purpose doesn't require a formal firm, a full-time role, or a registered brand. Regulators look at how the activity actually operates. Repetition, promotion, compensation, solicitation, and continuity over time all matter. Paid courses, subscription communities, affiliate arrangements, and recurring sponsored content often meet this threshold.
The guidance is explicit that finfluencers cannot avoid registration by saying their content is not advice. Disclaimers do not change how regulators assess the activity.
Investment advice includes opinions about the merits of investing in a specific business or security, as well as recommendations to buy or sell. The guidance notes that even promotional language or emojis that imply opportunity can be interpreted as recommendations.
Trading activity is defined broadly. It includes not only executing trades, but any act done in furtherance of a trade. The guidance specifically points to copycat trading enablement, such as linking followers who pay a subscription fee to replicate trades in a self-directed account. These lines are crossed more often than many creators realize.
Some finfluencers rely on the general advice exemption when providing broad and non-personalized commentary, however the regulator's guidance makes clear that this exemption is narrow and conditional.
If a finfluencer relies on it, they must clearly disclose any financial or other interest in the securities discussed. Financial or other interest is interpreted broadly and includes indirect incentives, compensation arrangements, and related party interests.
The exemption does not apply to trading activity. This distinction becomes critical when education is paired with transaction pathways.
Disclosure needs to be clear, prominent, and specific enough for an audience to understand the security involved, the incentive, who paid it, and who received it.
The guidance is direct about what fails. Statements like “I may have a financial interest” are not enough. Disclosure also fails when it is buried at the end of a video, hidden behind extra clicks, or written in a way viewers are unlikely to notice.
A simple acid test applies. If a viewer has to look for the disclosure, it likely does not meet expectations.
The example scenarios below highlight when creators drift into regulated activity without intending to. These aren't rare cases but common growth paths.
In one example, a creator starts with general investing education. That activity stays outside registration. When the creator adds buy and sell signals in a paid course, the activity becomes advising. When the creator begins answering personalized questions through comments and direct messages, charges fees, and scales tailored advice, registration becomes necessary or the activity needs to stop.
In a second example, a crypto-focused creator promotes a token without compensation. When that creator later joins an airdrop program tied to promotional tasks, the activity becomes compensated promotion. Disclosure obligations arise immediately and need to stay current. Linking to trading platforms and receiving payments from followers or platforms can also push the activity into trading facilitation.
In a third example, a creator promotes issuer securities for payment but hides the sponsorship because disclosure reduces engagement. Disclosure is buried behind “show more” links. Regulators treat this as a breach and move to enforcement. Not knowing the rules does not change the outcome.
Registered firms that work with finfluencers are expected to govern those relationships. That includes due diligence, written agreements, training, ongoing monitoring, and corrective action when content becomes misleading or non-compliant.
Order-execution-only dealers face added sensitivity. Because they cannot provide advice, regulators caution against indirectly enabling recommendations or registerable activity through referral arrangements, hosted content, outbound links, or copycat trading features.
For fintech platforms, this brings compliance into product design. Referral flows, creator landing pages, and trading enablement features all carry regulatory weight.
When issuers work with finfluencers, social media content counts as public disclosure. Issuers remain responsible for statements made on their behalf.
Regulators expect issuers to ensure content stays factual, balanced, consistent with filed disclosure, and clear about paid relationships. Issuers need to provide guidance and controls rather than leaving disclosure discipline to third parties.
Promotional shortcuts can surface later during diligence and capital raising.
Securities law applies regardless of whether content is created by a human, a digital avatar, or an AI system. Anyone deploying AI to generate investment related content remains responsible for that content as if they created it themselves.
For platforms experimenting with automated education or AI powered engagement, note that technology does not reduce accountability.
Finfluencer activity now sits firmly inside the regulatory perimeter. Data shows that influence impacts behaviour, and behaviour drives investment decisions. This new guidance gives founders, platforms, creators and issuers clarity. Teams that design content, monetization, referral flows, and product features with these expectations in mind can move faster with fewer surprises.
Teams that treat finfluencer activity as casual marketing often discover where the line sits only after they cross it. That is the practical message regulators are sending, and it is one the market needs to take seriously now.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
December 10, 2025
Image: Freepik/DC Studio
On December 9 2025, Microsoft Canada announced, 'the most important commitment in Microsoft Canada's history" or a total of $19 billion CAD to be invested into artificial intelligence (AI), including more than $7.5 billion CAD in the next two years inside Canada Central near Toronto and Canada East in Quebec. This anchors Canada inside Microsoft’s global AI buildout at a scale the country has never seen, one not of a secondary cloud market but as a strategic production region where infrastructure, talent and sovereignty all matter.
New capacity begins coming online in the second half of 2026. Microsoft aligned the buildout with a five point digital sovereignty plan for Canada that includes a (1) Threat Intelligence Hub in Ottawa, (2) confidential computing, (3) expanded data residency, (4) sovereign landing zones for AI deployment and (5) contractual protections designed to keep Canadian customer data under Canadian legal authority.
For Canada’s innovation economy, it accelerates product velocity for companies that rely on domestic compute, it may also impact how investors evaluate technical risk and strengthens (or weakens) Canada’s bargaining position at a time when the country is rewriting its AI and Buy Canadian strategies. It also raises a wider question: if Microsoft is prepared to make a commitment at this scale, what might other global AI giants like Google now offer Canada, and what terms should Canada set to ensure digital sovereignty instead of deepening dependence?
The federal government launched an AI Strategy Task Force and consultation in September 2025 to define the next national AI strategy. This consultation covers research, compute, governance, commercialization and public sector adoption. Also, Budget 2025 outlines a sovereign AI compute plan that includes a Sovereign Canadian Cloud and large scale public infrastructure investments, including $925.6 million commitment over five years.
AI Minister Evan Solomon recently spoke at a 111 event indicating that the feds are considering buy Canadian AI strategies to launch in 2026, linking federal funding and procurement to domestic infrastructure and model options.
The timing of Microsoft's investment may be linked to the federal government's buy Canadian strategy push, which gives policymakers a bit of leverage. Regardless with the new investment, Canada can now write a strategy that strengthens domestic options instead of reinforcing long term dependence on external providers without their long term commitment.
While Microsoft’s expansion strengthens Azure Canada Central and Canada East, with new capacity starting in 2026, it's important to point out that more compute doesn't eliminate all constraints. Provinces decide how quickly companies can expand existing datacentres because they control power availability, grid upgrades and the local approvals needed to support more energy use. Newfoundland utility as an example shows how provincial decisions can limit digital infrastructure growth, as it recently decided not to provide additional power to Blockchain Labrador Corporation. Ottawa can design rules for sovereign compute, but delivery depends on power systems and local permitting in Ontario, Quebec and any province that hosts future datacentres.
Digital sovereignty concerns were well established before Microsoft’s announcement. CIGI’s analysis of Canada’s digital dependence warns that foreign controlled cloud and platform infrastructure creates structural exposure across data, security, competition and resilience. Open Media outlined similar risks in an open letter on digital sovereignty to Prime Minister Carney that calls for domestic control over digital infrastructure and cautions against deepening dependence on foreign platform operators. The Broadbent Institute’s digital sovereignty briefing highlights how Canada’s information infrastructure is dominated by United States firms and stresses the importance of Canadian control over critical digital systems. NCFA added a fintech and digital identity angle in its Digital Public Infrastructure red flags analysis, providing a real case how outsourcing identity and authentication layers can narrow competitive space and weaken democratic oversight.
Microsoft’s announcement responds to these pressures with it's 5 point sovereignty plan for Canada which includes data residency commitments, confidential computing, in country processing for Copilot interactions, sovereign landing zones and a Threat Intelligence Hub in Ottawa.
The sovereignty debate is no longer theoretical. It is now a negotiation between public strategy, foreign capital, regulatory expectations and domestic ecosystem needs.
Microsoft’s investment changes how Canadian teams get the compute they need and how they plan products that must work inside regulated markets. With this level of commitment, Canada gains more domestic compute capacity and better tools to support sovereignty goals, but this infrastructure still sits inside foreign owned systems. The real impact is that Canadian teams now have a clearer path to scale at home while policymakers work to ensure these services strengthen, rather than weaken, Canada’s digital sovereignty.
For founders and investors, this creates room to build products that rely on local residency, stronger governance and efficient reasoning models suitable for regulated markets. Banks, fintechs, insurers and public institutions increasingly expect AI systems that can be audited and explained. Founders who anchor their products in these expectations will move faster across procurement and face fewer barriers in international markets that value trust and oversight. Companies that design for portability, auditability and resilience will avoid dependency traps and scale on terms that align with Canada’s sovereignty goals.
Public reporting shows that Microsoft is partnering with Cohere to offer its AI models on Azure, giving firms access to a domestic model supplier with global reach.
Canada now has conditions to build globally competitive AI companies that remain Canadian-controlled but the challenge is execution, governance and choosing business models that turn this new leverage into lasting advantage rather than repeating old patterns of dependence.
Microsoft’s investment places Canada inside a global race where compute, data control and strategic partnerships now determine who leads the next decade of AI. Canada’s advantage won't come from capacity alone, but from how Canada uses the moment to set clear rules for trustworthy AI, support efficient model development and give Canadian companies a stable foundation to scale without leaving the country for infrastructure or capital.
The next step is about deciding what Canada expects from any global partner. If Microsoft is prepared to invest at this scale, other AI giants may come forward with their own proposals. Canada’s job is to ensure that any future deal strengthens domestic capability, expands Canadian control over critical technology and avoids locking in long term partnerships that limit competitiveness across sectors.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Privacy | Dec 4, 2025
On December 2 2025, the Office of the Privacy Commissioner of Canada (OPC) launched a guidance modernization consultation to gather feedback on how it should create future guidance for organizations under PIPEDA. The announcement links to the Draft Policy on PIPEDA Guidance Consultations, which sets out the proposed structure for selecting topics, engaging stakeholders and updating guidance.
This consultation is important to fintechs and financial institutions alike because OPC guidance influences how teams design onboarding, identity flows, cross-border data use, fraud controls and AI supported systems.
The OPC has worked on several major guidance projects over the past decade. Some produced clear final documents. Others exposed pressure points where guidance needed stronger processes, clearer wording or more predictable updates. The timeline below isn't exhaustive but shows past steps that now impact the need for modernization.
| Year | Event | Notes |
|---|---|---|
| 2016 | OPC consultation on consent under PIPEDA | OPC reviews whether the consent model still works as data practices become more complex, including issues such as unclear notices and bundled consent. |
| 2018 | Guidelines for obtaining meaningful consent | OPC publishes final consent guidelines with clear expectations for transparency, user understanding and risk disclosure. These guidelines impact how organizations explain data practices. |
| 2019 | Consultation on transfers for processing and OPC announcement concluding the consultation | OPC tests possible changes to cross border processing guidance. After significant feedback, OPC confirms it will maintain the existing model for consent and accountability. |
| 2023 | Request for input on draft biometrics guidance and biometrics consultation notice | OPC seeks views on how organizations should handle biometric information, including expectations for assessments, safeguards and governance. |
| 2023–24 | OPC Departmental Plan reference to a guidance modernization project | OPC confirms it is building a structured and scalable approach to guidance development. |
| 2025 May | Exploratory consultation on a children’s privacy code | OPC explores principles for a possible children’s privacy code and gathers feedback from a wide range of stakeholders. |
| 2025 Aug | Final biometrics guidance for organizations | OPC publishes final biometrics guidance with expectations for sensitivity, safeguards, retention and governance. |
| 2025 Dec | Consultation on guidance modernization and Draft Policy on PIPEDA Guidance Consultations | OPC launches a public consultation on how it will plan and run future guidance consultations. |
The OPC launched this consultation to create a predictable structure for guidance development that follows clear steps from topic selection to final publication. The Draft Policy on PIPEDA Guidance Consultations sets out the proposed framework, which covers how the OPC will choose topics, engage stakeholders, review submissions and update guidance over time. The policy confirms that the OPC will provide discussion papers or draft text during consultations, outline the scope of each consultation and publish summaries that explain how input influenced the final document.
The draft policy describes the types of guidance it aims to improve, including interpretation documents, practical expectations for organizations and updates to guidance when law or technology changes. It also explains that the OPC may prioritize topics based on new risks, trends in complaints or changes in legislation, such areas as consent, cross border data use, artificial intelligence and children’s privacy that may require future guidance work. Biometrics already has final guidance but the OPC may revisit that topic if new risks or technologies emerge.
The OPC invites comments by email at cpvp-opcconsultation1@priv.gc.ca until deadline March 13, 2026. Submissions can respond to the draft policy or request updates to current guidance. The OPC welcomes input from any organization that operates under PIPEDA and wants a more consistent and transparent consultation process.
Fintech firms work with sensitive data across complex vendor chains. They rely on predictable regulatory expectations to design products and manage risk. This consultation matters because it affects several core fintech operations, for example:
Onboarding and identity verification. Clear guidance influences how fintech teams design consent flows, collect identity documents, use biometrics for fraud controls and explain risks to users.
Cross border data transfers. Fintechs depend on cloud services, payment networks and global providers. The 2019 transfers consultation showed how uncertainty about these transfers can raise operational and legal risk. A structured guidance process helps firms plan ahead.
AI and risk models. As firms use AI for underwriting, fraud detection or identity screening, they need dependable guidance on transparency, fairness and data use.
Open banking and partnerships. Banks, aggregators and fintech platforms need consistent interpretations of consent, accountability and data sharing. Modernized guidance helps reduce friction in new partnerships and supports investment decisions.
Competitiveness and trust. Canada has pursued privacy reform for several years. While reforms remain unfinished, guidance modernization is one of the main tools available to increase clarity and reduce uncertainty. Clear rules improve investor confidence and support firms that want to expand or build new financial services.
This guidance modernization consultation gives fintechs and financial firms an opportunity to help improve how privacy guidance develops in Canada. The OPC wants a process that delivers timely updates, clearer expectations and stronger transparency.
By submitting practical examples and highlighting where current guidance creates uncertainty, fintech firms can support a framework that strengthens trust and reduces friction across the market. Clearer guidance also supports growth, investment and innovation at a time when Canada needs stronger competitiveness in financial services and technology.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Innovation | Nov 26, 2025
Image: Freepik/DC Studio
On November 24 2025, the United States introduced the Genesis Mission by presidential executive order to create a national plan to use AI to accelerate scientific discovery by turning federal scientific data and national lab supercomputers into one research engine. The Mission instructs the Department of Energy to bring together national lab compute systems, decades of federal datasets, and advanced AI tools into a unified discovery platform.
The United States invests about $940B each year in total R&D across business, academic, and government sectors. Federal agencies perform roughly $74B of that work according to National Science Board data showing total U.S. R&D and federal R&D performance. The Genesis Mission uses this large research base to speed up discovery and strengthen national competitiveness.
Federal leaders say scientific progress has slowed. Research in biotechnology, materials science, clean energy, and other fields takes too much time and requires significant resources. The Genesis Mission will use artificial intelligence to help researchers simulate experiments, test ideas, and find scientific patterns faster.
Federal scientific datasets include information from the Department of Energy open data portal, National Institutes of Health scientific data resources, NASA Earth science and satellite data, NOAA climate and environmental datasets, Environmental Protection Agency public data, and the United States Geological Survey geological data platform. These datasets include physics records, biological data, climate observations, satellite readings, environmental measurements, and outputs from high performance computing systems.
Artificial intelligence can examine large datasets, run simulations, detect scientific relationships, and support experiment design. The White House states that the Mission will “harness Federal scientific datasets, the worlds largest collection of such datasets, developed over decades of Federal investments” to accelerate discovery through new scientific models.
The Mission targets strategic fields such as semiconductors, quantum science, fusion energy, biotechnology, advanced manufacturing, and critical materials. Federal leaders link this work directly to national security and economic strength.
Federal documents describe the Genesis Mission as a national platform that brings government, industry, and academic researchers into one discovery system. The Department of Energy states that the Mission “will mobilize the Department of Energy’s 17 National Laboratories, industry, and academia” to build an AI enabled discovery platform that uses national lab supercomputers and curated federal datasets as described in the Department of Energy announcement of the Genesis Mission.
The executive order also defines the American Science and Security Platform as infrastructure that includes high performance computing, advanced AI models, secure access to federal and synthetic datasets, and tools for AI assisted experimentation. These documents show that the United States intends to create structured pathways for companies and researchers who need access to national compute systems and curated scientific data.
The United States holds a large base of scientific data created through national laboratory work and federal research. These datasets often sit in separate systems. The Genesis Mission brings this information together and connects it to artificial intelligence tools. This gives the United States a clear advantage in fields that rely on data and high performance computing.
Artificial intelligence can help researchers test ideas faster, explore scientific patterns, and move from manual processes to rapid model driven cycles. If the United States reduces discovery times across key scientific fields it can improve innovation strength and create more commercial opportunities.
Canada invests far less in R&D than the United States. The comparison below uses verified public data from the National Science Board, Statistics Canada, the OECD, and Canadian research analysis.
| Measure | United States | Canada | Sources |
| Total R&D spending | $940B in U.S. R&D spending | $55B in Canadian R&D spending 2024 | NSB, Statistics Canada |
| Federal R&D spending | $74B in U.S. federal R&D performance | smaller share inside the total figure | NSB, Statistics Canada |
| R&D intensity | above 3% in many measures | among lowest in G7 according to Canadian reporting on weak R&D intensity | University Affairs, OECD |
| Business R&D | strong private sector | weak according to research on structural gaps in Canadian business R&D | Checkpoint Research |
| Labour productivity | higher output per hour | persistent gap according to OECD reporting on Canada’s productivity | OECD |
This comparison shows the structural difference between the two countries. The United States enters the Genesis Mission with a large research base that artificial intelligence can accelerate. Canada enters with weaker investment and slower productivity growth.
Canada invests less in R&D than the United States and shows lower business led research compared with peer countries. A recent Canadian assessment ranks Canada near the bottom of advanced economies in business enterprise R&D intensity according to research that highlights Canada’s weak private sector R&D investment. Canada also has world class AI research centers such as Vector, Mila, and Amii, and they contribute strong scientific output. However they don't operate a national system that brings together federal datasets, high performance computing, and artificial intelligence for coordinated discovery.
These gaps limit Canada’s ability to compete against countries that build stronger national research infrastructure. If the United States speeds up discovery through a national artificial intelligence platform Canada may rely more on foreign systems and lose ground in advanced materials, biotech, quantum research, and energy.
The Genesis Mission gives the United States a new way to use scientific data, computation, and artificial intelligence to speed up discovery. It supports national security, innovation, and economic strength. For Canada it raises a serious challenge. Canada invests far less in R&D and lacks a unified artificial intelligence research platform. As the United States accelerates discovery Canada must decide how to strengthen the outcomes of its research base and protect its competitiveness in a world where artificial intelligence supports scientific progress.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016