




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Crypto | Nov 7, 2025
Image courtesy of AI
On November 5 2025, Ripple announced a $500 million strategic raise led by Fortress and Citadel Securities at a $40 billion valuation. The company positioned the funding round as confirmation of its recent trajectory and a way to deepen ties with financial partners after its strongest year on record.
Brad Garlinghouse, CEO Ripple:
“This investment reflects both Ripple’s incredible momentum, and further validation of the market opportunity we’re aggressively pursuing by some of the most trusted financial institutions in the world. We started in 2012 with one use case payments and have expanded that success into custody, stablecoins, prime brokerage and corporate treasury, leveraging digital assets like XRP. Today, Ripple stands as the partner for institutions looking to access crypto and blockchain.”
Ripple points to six acquisitions completed in just over two years that expand Ripple's ecosystem from a payments specialist to a broader institutional platform spanning custody, prime brokerage and corporate treasury.
On May 17, 2023 Ripple acquired Metaco for approx $250 million, adding an institutional custody stack and tokenization tooling that supports enterprise use cases.
On June 11, 2024 Ripple officially acquired Standard Custody and Trust Company (M&A price undisclosed), following regulatory approvals, expanding Ripple’s portfolio of licences and custody capabilities.
On April 8, 2025 Ripple acquired Hidden Road for $1.25 billion (now operating as Ripple Prime). The deal gives Ripple a global multi asset prime broker serving hundreds of institutional clients and positions RLUSD for collateral and cross margin uses.
Then on August 7, 2025 Ripple acquired Rail for $200 million, a Toronto based stablecoin payments platform, strengthening Ripple Payments with virtual accounts, cross border flows and back office automation.
On October 16, 2025 Ripple acquired GTreasury for $1 billion, opening up the corporate treasury market to Ripple’s infrastructure and customers that want to use stablecoins and tokenized deposits at scale.
And on November 3, 2025 Ripple acquired Palisade for an undisclosed amount, adding wallet and custody technology designed for real time institutional payments and treasury use cases.
The Rail acquisition anchors part of Ripple’s stablecoin payments build in Toronto, tipping the hat that Canada can be a node for institutional stablecoin flows. For Canadian banks, credit unions and large corporates, the combination of Rail for payments, GTreasury for treasury systems and Ripple Prime for brokerage creates an end to end platform that could change how liquidity, collateral and settlements move across borders and time zones.
For regulators, Ripple’s accumulation of more than seventy licences via Standard Custody's acquisition suggest a regulatory path where custody, treasury and brokerage converge. This raises familiar questions about prudential oversight and new ones about stablecoin collateral, cross margining and non bank market infrastructure that interfaces with core payment systems.
Ripple continues to prioritize licensing and compliance as part of its core strategy. When announcing the Standard Custody deal in February 2024, CEO Brad Garlinghouse said the acquisition “underscores Ripple’s ongoing commitment to working closely with regulators and maintaining the highest standards of compliance.” That focus on regulatory engagement gives institutions and policymakers a clearer sense of how Ripple plans to connect custody, brokerage, and treasury activities within today’s legal frameworks.
Ripple’s institutional expansion now focuses on integrating custody, payments, and treasury capabilities gained through its recent acquisitions. The company said these additions strengthen its position as a full-service provider for financial institutions, combining secure custody infrastructure, stablecoin payment tools, and prime brokerage access within one platform.
Brad Garlinghouse, CEO Ripple when announcin the GTreasury deal:
“For too long, money has been stuck in slow, outdated payments systems and infrastructure, causing unnecessary delays, high costs, and roadblocks to entering new markets problems that blockchain technologies are ideally suited to solve,”
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Nov 6, 2025

Image: Freepik
Reviews on the internet can be the difference between success and failure for an organization. They have become a crucial part of how consumers evaluate and decide on brands. Each company should pay careful attention to online reviews.
The modern day consumer trusts online reviews just as much as personal suggestions. Positive feedback increases trust and attracts potential buyers. If you do not take care, negative reviews could damage your brand's reputation. Understanding how to handle reviews is essential to ensure online success.
Manually managing the reviews isn't easy and can become overwhelming. Nowadays, businesses use software for online review management. The tools collect reviews across multiple sites into one dashboard. They assist you in monitoring responses, analyzing, and responding to reviews efficiently.
A good software for online review management provides automation as well as real-time alerts. The software allows quick resolution of negative reviews and thank happy customers. The quick response will help ensure your reputation on the internet. All reviews being all in one location helps save time and energy which makes it simpler to identify trends and problems.
Advanced platforms can also provide analytics. They can show which topics pop on the top of their list, analyze customer sentiment, and highlight areas. Certain tools allow you to solicit new reviews from happy clients. The result is that your profile stays current and positive.
The reviews on websites are open and are permanent. Prospective customers frequently read reviews before making a decision. One bad review could turn away buyers, but the majority of positive reviews will boost sales. The company must concentrate on review management to safeguard their reputation.
Reviews provide feedback directly about the products as well as services. Companies can gain insight into what is working and improve upon. By responding to customer reviews, you show the value of customer reviews. This builds trust and increases trust and loyalty. The proper review management turns feedback into business growth.
Yotpo is the best alternative for managing reviews on the web. It comes with extensive features to allow review management simple and effective. Yotpo collects reviews from a variety of sources and puts them on one dashboard. Companies can effortlessly monitor the feedback, reply to it, and analyse all reviews.
Yotpo stands out due to its automation tools. It automatically requests reviews immediately after purchase, providing an ongoing flow of feedback. Yotpo lets you show reviews on your site which increases trust as well as increasing conversion rates. Yotpo's analytics tools allow you to keep track of customer sentiment and spot trends to help you make better business choices.
Integration integration with eCommerce platforms is easy. Yotpo connects to major shopping carts, which makes setting up simple. Yotpo's moderation functions help in removing fake as well as fake reviews.
There are many tools that offer Digital Reputation Management, but not all of them are created equal. Some tools focus on gathering feedback while others offer more comprehensive analytics. Yotpo offers both and provides complete tools to manage and review reviews.
Some tools might not have automation as well as real-time alerts. The result is slower responses to feedback that is negative. Yotpo's software for online review management has stood out due to its innovative features. Its integration and customization options makes it a good fit to fit any size business.
Yotpo is also an extensive moderation as well as reporting tools. This ensures that only genuine reviews are published and allow brands to assess the effects of review reviews on sales. Regarding online review management, Yotpo's comprehensive approach makes it the perfect choice for those seeking to increase and secure their reputation.
The Yotpo makes it easier to collect, organize and publish online reviews. It makes requests easier and accumulates reviews in one location. Brands are able to monitor reviews across platforms, respond rapidly, and then analyze patterns.
Yotpo's analytics aid in digital reputation management by tracking customer sentiment. The company's integration to eCommerce platforms as well as sophisticated moderation makes it different. Most businesses will find that Yotpo is the top choice of software for online review management.
The Trustpilot provides a reliable platform for collecting testimonials from actual customers. The dashboard is simple to use, and it provides the most basic analytics. Brands are able to reply to reviews directly, inciting greater engagement.
Trustpilot's platform for public use helps increase the transparency of digital reputation management. Customers can read real reviews and improve brand credibility.
The Birdeye collects reviews from more than 150 websites into one dashboard. The platform provides tools to monitor responses, soliciting review updates. Automated features allow brands to reduce time.
Birdeye's analytics and reports help with digital reputation management by identifying the trends that are most prevalent and those areas where there is room to improve. The user-friendly interface works for businesses of any size.
The Podium concentrates on helping businesses gather reviews through texts. This improves the rate of response and guarantees constant feedback. It also allows two-way communication for direct contact with the customer.
The Podium software for online review management offers sentiment analysis and reporting. These tools can help brands safeguard and boost their reputation online.
The ReviewTrackers consolidates reviews from different review sites. It provides instant notifications as well as an integrated dashboard which makes managing more productive. Brands can make use of analytics to identify problems and potential opportunities.
ReviewTrackers aids in digital reputation management by allowing prompt response to customer feedback. The features for tracking are beneficial in improving service reputation.
The Reputation.com offers enterprise-level software for online review management. It streamlines review requests and gathers feedback from different sources. Brands can make use of dashboards for monitoring sentiment and performance.
Their digital reputation management tools include analytics reports, analytics, as well as competitive benchmarking. Brands with large footprints as well as franchises reap in the most significant way from these functions.
The Sprout Social combines review management along with other social media tools. It organizes mentions, reviews as well as messages into one mailbox. Brands are able to interact with their users across multiple social media platforms.
The Sprout Social analytics aid in tracking online sentiment and also overall brand reputation. This is ideal for companies needing review or social management of media.
Google My Business lets brands control reviews appearing in the search results as well as maps. Businesses are able to reply to reviews and update their details effortlessly. It's completely free and widely utilized.
Even though it is basic, Google My Business remains essential to digital reputation management. Local companies especially profit from its reach as well as its simplicity.
The Grade.us can customize review campaigns for acquisition. Companies can manage requests via text messages and email. Its platform collects reviews from a variety of sites to allow an easy and efficient following.
Grade.us assists with digital reputation management by encouraging positive feedback and addressing negative reviews in the early stages. The company's reporting tools help brands measure the impact.
The Capterra is a specialist in reviews of software in helping B2B businesses build their credibility. Capterra is a safe place where customers can leave comprehensive reviews.
Capterra's software for online review management is easy to use but highly effective for both tech as well as SaaS companies. With its focus on transparency, it boosts digital reputation management in the software sector.
Yotpo is a leader in software for online review management using its integrated platform. Automated features collect reviews easily and ensure a constant supply of feedback. The integrated dashboard allows you to monitor and respond to reviews. Yotpo's analytics and moderation tools go beyond the basics of management and provide deep insight.
Yotpo's integration with the most popular eCommerce platforms gives it more versatility and scope. Companies can show trusted reviews in the areas where customers shop while also assisting with digital reputation management. The system's moderation makes sure that only real reviews are displayed, safeguarding your company from being sucked into spam or fake reviews.
Different platforms could offer comparable features, but Yotpo's blend with automation, analytics, and user-friendliness sets the platform distinct. If you're serious about expanding your business and securing their online presence, Yotpo is the clear top choice in software for online review management.
The management of online reviews is crucial for the business's success. It is essential to choose the right software for online review management for example, such as Yotpo helps streamline feedback and assists with digital reputation management. Through automation and analytics companies can increase trust as well as improve service and ensure a robust online reputation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Digital Banking | Nov 5, 2025
Image: Freepik/vectorpocket
On November 4, 2025, Tangerine Bank announced a 10-year partnership with UK Fintech, Engine by Starling to deliver a next generation digital banking platform for more than two million Canadians. The agreement marks Engine’s first North American deployment, and for Tangerine, a commitment towards faster, cloud-based innovation.
For Canada and the buy Canadian movement, it's a reminder of the importance of building homegrown fintech infrastructure that can compete globally.
Tangerine chose Engine by Starling (part of the UK’s Starling Group) to provide a cloud-based, API-powered banking platform that includes digital onboarding, chequing and savings accounts, payments, and spending insights. The company already supports banks in Europe and Australia. By adopting Engine's platform solution, Tangerine is upgrading its technology foundation to deliver quicker feature rollouts, smoother operations, and better digital experiences for clients.
Engine’s expansion into North America has been steady. The company took part in the Grow London Global Fintech Trade Mission to North America 2025, which visited Toronto and New York in mid-October. The mission brought together sixteen UK fintechs to meet with banks, investors, and ecosystem partners, helping build connections that may have opened doors for the Tangerine partnership announced just weeks later.
Canada has a strong and growing community of fintech infrastructure firms such as VoPay, Fintel Connect, and Zevoy Canada that are developing payments, data, and Banking-as-a-Service platforms. What remains a challenge is scale. Few Canadian providers have reached the same visibility or size as the international players that dominate large transformation projects. More partnerships and work has to be done for domestic financial tech firms to capture these opportunities.
The Tangerine–Engine deal proves that if Canadian fintechs have the right mix of support, capital, and partnerships, they can compete similarly in global markets. It’s a chance for Canada’s policymakers, investors, and banks to create more conditions that help local technology providers grow into global suppliers of digital infrastructure.
While it's great for millions of Canadians that Tangerine's upgrade will provide a faster and more modern digital banking experience, it highlights gaps and opportunities for growth in Canada's fintech ecosystem.
Innovation is a global game for many fintechs and strengthening Canada’s fintech infrastructure will help ensure that the next digital banking platform upgrade has 'built in Canada' digitally printed on it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Stablecoins | Nov 4, 2025
On October 28, 2025, Visa CEO Ryan McInerney told investors in a Visa Q4 earnings call (22 page PDF) that the company is adding support for four stablecoins operating on four distinct blockchains across two currencies, with conversion to more than 25 fiat currencies. He said Visa’s stablecoin-linked card spend has quadrupled over the past year, with monthly settlement volumes reaching an annualized $2.5 billion. So now we can all expect to have access to embedded digital currency settlement directly into its global treasury and FX systems.
Visa’s public Onchain Analytics Dashboard reports more than US $9.6 trillion in adjusted transaction volume, over 10 billion transactions, and an average stablecoin supply above US $221 billion across Ethereum, Solana, Polygon, and Avalanche. The numbers confirm that fiat-backed stablecoins are already a growing part of daily global payments.
Based on Visa’s earlier pilot programs using USDC on Ethereum and Solana, it is reasonable to expect these networks to be among the four blockchains involved, though earnings call transcript doesn't name specific stablecoins or chains.
Visa’s expansion is a transition from testing digital currency settlement to making it part of its core infrastructure. The company is linking stablecoins to its global treasury and FX networks, allowing conversion between digital assets and traditional currencies without adding new intermediaries. So stablecoins will become programmable tools for cross-border settlement and liquidity management.
Ryan McInerney, Visa CEO:
“We are adding support for four stablecoins, running on four unique blockchains, representing two currencies, that we can accept and convert to over 25 traditional fiat currencies. Our digital currency work builds on our core competencies — connecting buyers and sellers, securing payments, and enabling interoperability across currencies and networks.”
Fintechs and financial institutions should take notice because Visa is not just planning to accept stablecoins as a form of payment, it's building a bridge between regulated banking infrastructure and onchain finance. Visa’s integration also provides a compliance template that shows how large-scale financial networks can handle digital assets safely within existing frameworks.
Visa’s financial results strengthen the case why stablecoin settlement is strategically important. According to Visa’s investor materials, cross-border payment volume grew 10% year over year in Q4 2025, driven by travel and international eCommerce. Total revenue reached US $9.2 billion, up 9%, with payment volume increasing 8% on a constant-dollar basis.
Stablecoins fit naturally into this picture. They can move value instantly across borders, reducing settlement friction and costs for businesses that operate in multiple currencies. For enterprises, corporates, and fintechs, Visa’s model offers a regulated approach to use stablecoins for treasury, payroll, and remittances at scale.
Visa’s partnerships with digital wallets, neobanks, and blockchain platforms extend its reach into Web3 commerce while maintaining the dispute resolution and identity safeguards that make card networks trusted globally.
McInerney emphasized continued collaboration with policymakers and central banks to ensure that new payment models meet regulatory expectations while delivering tangible economic benefits.
For Canada, Visa's approach of blending real world payments with programmable finance is a framework offering lessons on how to connect open banking, digital money regulation, and cross-border innovation at scale and under clear governance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Banking Regulation | Nov 4, 2025
On November 3, 2025, Questrade officially entered the banking sector. The company received federal approval from the Office of the Superintendent of Financial Institutions to open Questbank, one of the few new Schedule I banks authorized in Canada in the past two decades. The approval was confirmed through the Canada Gazette publication of Questbank incorporation.
This is significant as Questrade evolves from an investment brokerage into a full service digital bank. It adds a new competitor to a market long dominated by Canada’s largest institutions and will hopefully advance innovation, inclusion, and national competitiveness in the country.
After six years of preparation, OSFI approved Questrade’s bank license on November 3 2025, granting an Order of Commencement and Carrying on of Business under the Bank Act. The approval allows Questbank to accept deposits and issue loans under federal oversight.
The decision aligns with priorities set out in the OSFI Strategic Plan 2024–2027, which focuses on stability and responsible modernization. Licensing a fintech type of institution signals that regulators are confident digital firms can meet Canada’s prudential standards while helping to diversify and strengthen the banking system.
A Bank of Canada study on market concentration shows that Canada’s Big Six control over 93% of total banking assets, one of the highest levels in the G7. This concentration limits competition and slows innovation. The entry of Questbank introduces a new competitor focused on digital experience, transparency, and affordability.
Current market data indicate that Questrade manages more than $85 billion in client assets, giving Questbank the scale to compete with mid-tier lenders from day one. Its digital first model could reduce overhead and improve pricing for both savers and borrowers. In a country where banking profits exceed $60 billion annually, new entrants are needed to expand access and encourage modernization.
For Canadians, the launch of Questbank could make it easier to manage money in one place. People who already invest through Questrade will be able to bank, borrow, and save using a single digital platform. This integration may lower fees and increase transparency.
For policymakers, the development shows both progress and remaining friction. Only a handful of Schedule I banks have launched since 2000, and the approval process remains lengthy (see Santander Bank 5 years to get license). A more flexible licensing approach could allow other qualified fintechs to join the system while maintaining strong oversight. Countries including the United Kingdom and Singapore have implemented phased authorization programs for digital banks, allowing limited early operations before full licensing. A similar framework in Canada could help attract investment and skilled talent while supporting responsible innovation.
Questrade’s success also underlines the importance of governance. The company’s record of compliance and consumer protection likely strengthened its application and sets a precedent for fintechs seeking federal status.
Questrade plans to roll out Questbank publicly in 2026, combining savings, lending, and investment services under one regulated brand. The achievement shows that innovation and oversight can advance together to build a more inclusive and efficient financial system.
It confirms that fintechs investing in trust, governance, and compliance can now better compete directly with established banks. Questrade’s path from brokerage to federally regulated institution offers a roadmap for how collaboration with regulators can fuel growth and improve Canada’s competitiveness in global finance.
Q: What exactly did OSFI approve on November 3 2025?
A: On that date, OSFI issued an Order of Commencement and Carrying on of Business, authorising Questbank to begin operations as a Schedule I bank under Canada’s Bank Act. Verified by Reuters reporting on November 3 2025.
Q: When was Questbank officially incorporated?
A: The federal government issued letters patent on March 29 2025, as published in the Canada Gazette.
Q: How large is Questrade’s current business?
A: The company manages more than CAD 85 billion in client assets, based on publicly reported data.
Q: Why is this move important for Canadian fintech?
A: Because Canada’s Big Six banks still control roughly 93% of banking assets, Questbank’s approval brings fresh competition and shows fintech innovation can thrive under federal regulation.
Image generated by AI
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Tokenization | Nov 3, 2025
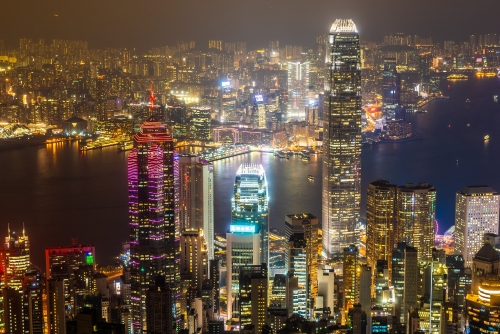
Image: Freepik/lifeforstock
On November 3, 2025, speaking at Hong Kong FinTech Week 2025 (Nov 3-7), Standard Chartered Group CEO Bill Winters told attendees that the bank is working with regulators and infrastructure providers across Asia to make tokenized settlements operational.
“Our belief, which I think is shared by the leadership of Hong Kong, is that pretty much all transactions will settle on blockchains eventually, and that all money will be digital,” adding that institutional adoption is now driving the market.
Digital currency momentum is building across Asia. According to Quartr, during Standard Chartered’s Q3 2025 earnings call, he emphasized that blockchain and tokenized asset infrastructure are “a core part of our payments and securities business strategy.” The bank’s venture arm SC Ventures has invested in settlement platforms and digital asset custody providers in Hong Kong, Singapore, and the UAE to prepare for institutional scale.
Hong Kong’s digital finance policy is moving from experimentation to scale. The Securities and Futures Commission (SFC) circular on expanding virtual asset trading platform services removes earlier barriers for banks and licensed exchanges to issue and custody tokenized securities under supervision. It also aligns with Hong Kong’s new stablecoin licensing regime, which took effect on August 1 2025, creating a pathway for licensed entities to offer regulated stablecoins towards broader public access.
Hong Kong Monetary Authority chief executive Eddie Yue unveiled the city’s Fintech 2030 strategy built on four pillars. Data, AI, Resilience, and Tokenization (DART) and announced the next phase of the Project Ensemble pilot (read his full speech here).
The pilot now extends beyond proof-of-concept to real transactions in tokenized deposits and money-market funds between major banks and corporates. Yue said tokenization will make bond settlement and trade finance “faster, cheaper, and safer” while preparing the city for cross-border interoperability.
Hong Kong’s strategic approach shows how regulatory clarity and infrastructure readiness can draw investment and accelerate industry innovation. The model offers a blueprint for Canada to move beyond regulatory sandboxes and innovation hubs toward supervised tokenized settlement and digital-asset custody frameworks built into the financial system.
For Canadian fintechs and banks, staying competitive will depend on how quickly policymakers complete payment modernization, establish clear rules for stablecoins and tokenized assets, and open Payments Canada’s systems to more participants through the Real-Time Rail.
Remember, Standard Chartered is already building tokenized-finance capabilities across Asia. Institutions will need to update their core systems to benefit from faster cross-border and digital settlement and to connect with the growing global networks for tokenized finance.
The SFC and HKMA frameworks create one of the world’s most coordinated environments for institutional blockchain adoption and banks like Standard Chartered are positioning themselves to capitalize on that alignment.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Licensing | Nov 3, 2025
Image: Freepik/rawpixel.com
On October 31 2025, Getty Images and Perplexity announced a global multi-year agreement that gives Perplexity permission to display Getty’s creative and editorial photos within its AI search tools. The partnership uses Getty’s API to bring licensed images directly into Perplexity’s results with clear credits and links to the original source.
It’s one of the first major deals between an AI company and a content rights holder, an example of how licensing can help AI platforms respect creators while improving the quality of what users see.
Jessica Chan, Head of Content and Publisher Partnerships at Perplexity:
“Getty Images shares our belief that the future of AI‑powered discovery requires respecting the creators behind the content. Attribution and accuracy are fundamental to how people should understand the world in an age of AI"
Perplexity has faced several plagiarism and scraping allegations during the past year, including incidents involving Getty photos that appeared without license. The new agreement resolves those issues by providing legitimate access under clear terms.
Nick Unsworth, Vice President Strategic Development at Getty Images:
"This agreement paves the way for a productive and collaborative partnership between our companies, where we will work together to improve attribution of our contributors' work and Getty Images’ high‑quality creative and editorial content will enhance Perplexity’s platform.”
Attribution does not grant any rights, and any reuse or commercial application still requires a separate license from Getty Images. There is no indication of sublicensing or user-level permissions in any official material.
The Perplexity–Getty deal is a win-win where a structured licensing partnership can strengthen trust and reduce copyright exposure while improving the user experience. For Getty, the deal adds a new business stream in AI search.
For Perplexity, it helps rebuild credibility after a year of public criticism while following through on stronger commitment to transparency and proper credit for creators. This partnership also builds on the company’s earlier initiative to share value with content creators through its 80/20 revenue-sharing program for publishers.
Being transparent about where information comes from builds confidence with users and regulators. As Canada develops its own rules for AI and copyright, partnerships like this one show how respecting creators can go hand in hand with innovation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016