




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 19, 2026 | NCFA Insight | Capital Markets And Funding, Crowdfunding, Regulation And Policy
On May 16, 2026, U.S. Regulation Crowdfunding (Reg CF) marked 10 years since eligible companies could start raising capital under the SEC’s final crowdfunding rules. Our colleagues at Crowdfund Insider posted New 10 year Reg CF data from Crowdfund Capital Advisors (CCA) providing the market with a full decade of evidence, certainly something rare in early stage finance.
For NCFA and its community, this milestone deserves attention, since the association has supported investment crowdfunding through advocacy, education, market intelligence, and ecosystem building for well over a decade. In 2022, Fintech Fridays hosted a special episode on 10 Years of Investment Crowdfunding, focused on the JOBS Act. This 2026 anniversary is different because it's been 10 years since Reg CF actually went live.
The data suggests that a meaningful portion of companies using Reg CF were not just raising money once and disappearing. CCA reviewed 10,771 offerings by 8,955 issuers, and 6,063 issuers completed 7,459 offerings. Those numbers show a market with repeat activity, not just one off campaigns.
The revenue data sends a stronger business signal. Among issuers with three or more revenue data points, CCA reports 27% median annualized revenue growth, with 70% growing revenue and a 1.81x median revenue multiple. This means many companies with enough reporting history showed measurable operating growth after raising capital through crowdfunding. That supports the case that Reg CF financed real businesses, not only speculative startups.
Among issuers that raised multiple rounds, CCA reports a 24% median valuation CAGR, a 1.54x median valuation step up, and valuation increases for 79% of multi round issuers. That suggests many repeat issuers returned to the market with stronger investor validation and higher implied company value.
The repeat raise numbers are important too. More than 7,400 successful offerings from about 6,000 issuers suggests a meaningful number of companies returned to the market more than once. That points to crowdfunding evolving beyond one time community fundraising into an ongoing capital formation channel for some businesses.
Sherwood Neiss, Principal, Crowdfund Capital Advisors:
“A decade of actual market data tells a completely different story.”
That sentence captures why this milestone matters. Reg CF didn't replace venture capital like many suggested. It didn't solve every funding gap, but it democratized and proved that regulated online capital formation can support real issuers, real investor participation, and measurable growth over time.
The strongest data point is not only the growth metrics. It's now also about discipline. CCA separates issuers that keep reporting and return to the market from those that disappear from the data. It's important because transparency creates trust. A crowdfunding market cannot mature if investors, platforms, regulators, and researchers cannot track performance after the raise.
CCA reports that there's a large compliance gap in reporting. Among 5,077 Reg CF issuers with active annual reporting obligations, only 301, or 5.9%, are fully current. Another 32.4% are partially current, while 61.7% are not current. It's a gap that needs to be fixed. It is a reason to modernize reporting, reduce unnecessary friction, and build better data infrastructure.
Canada should use the Reg CF 10 year milestone to modernize investment crowdfunding. The current $1.5 million 12 month issuer cap under National Instrument 45-110 now acts as a real constraint for stronger companies, especially when campaigns can approach the limit before meeting full market demand. NCFA has long argued that Canada risks falling behind international peers that raised their crowdfunding limits years ago, including the U.S., which increased the Reg CF cap to USD $5 million in 2021.
Canada should raise the issuer cap, index it to inflation, and create a higher fundraising tier for issuers that meet stronger disclosure, financial reporting, and portal due diligence standards. NCFA has also previously advocated for right sized disclosure rules, including director and officer certified financial statements for smaller raises, reviewed financial statements for mid sized raises, and audited financials only for larger raises where the added cost is proportionate.
Investor participation rules also need modernization. Canada should review the current retail investment limits, allow greater participation from experienced and repeat crowdfunding investors, and explore a knowledge based or self certified investor category with appropriate safeguards. A modern private capital market should not assume that all retail investors have the same risk profile, sophistication, or investing experience.
Structural incentives would help strengthen the market further. Canada should explore clearer pathways for TFSA and RRSP eligibility where appropriate, support secondary market liquidity after holding periods, and encourage co investment structures that allow funds, angels, and retail investors to participate together in compliant online financings.
Canada needs standardized campaign data, stronger post raise reporting, issuer education, and technology enabled compliance for KYC, background checks, risk warnings, issuer updates, and ongoing disclosure. NCFA previously covered why Reg CF data quality matters. If regulators and policymakers rely on incomplete reporting data, they risk misunderstanding how capital actually forms, performs, and scales through online private markets.
A stronger crowdfunding market doesn't require weaker oversight. It requires smarter rules, better data, and a funding framework that reflects how modern private capital forms online.
The 10 year Reg CF story is evidence that digital investment markets can widen participation, support early stage companies, and create a more transparent private capital market. The next phase should focus on quality, not just volume. Better issuer readiness, clearer post raise reporting, credible data, secondary liquidity experiments, and stronger investor education can help crowdfunding move from alternative finance into core capital formation infrastructure.
For NCFA, this is also a moment to recognize the builders, platforms, lawyers, advocates, educators, investors, and founders who kept pushing when the market was dismissed as too small or too risky. Reg CF at 10 shows that the model works when policy, platforms, and market discipline move together. Canada should not watch from the sidelines at a time when more capital needs to flow.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 18, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Digital Assets Blockchain And Tokenization
On May 18, 2026, Paytrie enabled CADC stablecoin powered remittances from Canada to international markets, beginning with Mexico and Nigeria. A Canadian sender starts in Canadian dollars. Paytrie uses CADC as the Canadian dollar stablecoin bridge, converts into USDC through liquidity providers, and then uses Circle Payments Network for local currency payout.
CADC is being used inside a live cross border remittance corridor, with a Canadian dollar starting point and global stablecoin infrastructure behind the payout.
Recent Canadian stablecoin activity includes Loon’s CADC acquisition, QCAD adoption work, and policy debate around a domestic stablecoin framework. This launch is different because it connects CADC to an outbound remittance flow.
Jason Tong, CEO, Paytrie:
“For the first time, a Canadian dollar stablecoin is being used to help power fast and affordable remittances from Canada. CADC gives Canadians a familiar Canadian dollar starting point, while USDC and global stablecoin infrastructure help move value across borders more efficiently.”
Most stablecoin payment activity is still tied to U.S. dollar tokens due to liquidity, distribution, and network support. Canada has a different need given that Canadian users and businesses earn, bank, invoice, and plan in Canadian dollars. A CAD stablecoin can reduce friction at the first mile before funds enter a global corridor.
CADC acts as the Canadian dollar bridge. USDC carries the payment through Circle Payments Network before payout in the recipient’s local currency. That keeps CADC close to the Canadian user and uses USDC where global liquidity is needed most.
CAD pegged stablecoins don't have to compete with USD stablecoins everywhere. They can support Canadian dollar funding, treasury, settlement, and corridor access at the point where Canadian payment flows begin.
Families need funds to arrive quickly, safely, and at a fair cost. Senders need clear pricing. Recipients need local currency in a bank account without having to handle crypto directly.
For PSPs and MSBs, the corridor still needs the hard parts of payments. Onboarding. Sanctions screening. Fraud controls. Refund handling. Customer support. Local payout partners. Stablecoins can reduce settlement friction, but they don't remove the need to operate the full payment workflow.
Circle Payments Network positions stablecoins as institutional payment infrastructure, not a retail crypto app. Circle says the network supports 24/7 near instant settlement and uses a compliance first architecture where partners are vetted for licensing, regulatory compliance, operational risk, and security.
That's a strong signal for Canadian payment providers. Stablecoin remittances are starting to look like a settlement option for regulated firms. If the model works, banks and PSPs will need to decide whether to build, partner, or risk losing international payment flows to faster specialist rails.
The treasury angle is just as important. Stablecoin corridors can reduce the need for some prefunded local accounts. That can improve working capital and speed up payouts. It also adds new questions around liquidity, FX spreads, counterparty exposure, and more.
For Canadian fintechs, banks, and PSPs, the read is direct. CAD stablecoins may not win by competing head on with USD stablecoins everywhere. They may win by making Canadian dollar entry, treasury, and settlement flows easier to connect to global stablecoin networks.
If CAD stablecoins become the Canadian dollar entry point into global payment networks, which firms will control the customer relationship, FX economics, compliance layer, and payout corridor?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Capital Markets And Funding
On May 12, 2026, Ottawa announced $66 million for 44 Canadian AI projects through the AI Compute Access Fund, part of Canada’s $300 million Sovereign AI Compute Strategy. Evan Solomon, Minister of Artificial Intelligence and Digital Innovation, announced the funding at Web Summit Vancouver.
Compute has become a hard cost of AI growth. If an AI company wants growth, even if they have strong talent, a useful model, and early customers, without affordable processing power, it still can’t train, test, or serve the product at scale. So in a sense, compute access (or lack of) is now part of Canada’s productivity and capital formation problem.
The announcement says the funded projects cover health care, energy, manufacturing, agriculture, finance, natural resources, and transportation. Use cases are across a range of sectors, such as wildfire detection, public transit, drug discovery, agriculture, financial services, and business tools.
Evan Solomon, Minister of Artificial Intelligence and Digital Innovation and Minister responsible for the Federal Economic Development Agency for Southern Ontario
“AI is not just a technology of the future. It is already helping Canadian companies solve real problems, improve services, create products and compete globally. But to build with AI, companies need access to compute power. Through the AI Compute Access Fund, we are helping Canadian businesses get the processing power they need to scale, create jobs, transform industries and keep more of the value they create here in Canada.”
The AI Compute Access Fund program guide says eligible project costs must range from $100,000 to $5 million. Projects can run for up to three years and must end no later than March 31, 2028. Important to note that this amount of funding can help companies overcome smaller experiments, but it doesn't solve the full scale problem.
The Bank of Canada’s recent AI productivity speech shows the size of the race. Top U.S. technology firms spent roughly US$200 billion on AI related investment in 2024. That doubled to about US$400 billion in 2025. Canada cannot match that dollar for dollar. So it's moved quickly to fund firms that can turn compute into commercial products, owned IP, and exportable capability.
For fintechs and financial institutions, compute connects directly to governed AI workflows in finance. The value is output that teams can review, explain, and control.
Canada also needs more domestic capacity. Clean power, secure data centres, competitive cloud options, and private capital must all converge to support AI growth. Compute support shouldn't only be given to the best funded firms. It should also reach applied AI builders, regional companies, regulated sector use cases, and firms solving productivity problems that don't always attract venture capital.
Can Canada turn compute funding into scaled AI companies, or will the largest gains still flow to firms that control the platforms, data centres, and capital behind the AI economy?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, SME Finance And Business Banking, Capital Markets And Funding
On May 14, 2026, Synthetic raised USD $10 million in seed funding led by Khosla Ventures to build autonomous AI bookkeeping for software startups. Basis Set Ventures also participated. Operator investors include Shopify CEO Tobi Lütke, Opendoor CEO Kaz Nejatian, Bridge co founder Zach Abrams, Accrual CEO Cosmin Nicolaescu, and Figure CEO Michael Tannenbaum.
Synthetic is aiming to deliver accrual basis books without human bookkeepers or accountants. The system connects to a customer’s banks, payroll, billing systems, and inboxes, then asks clarifying questions when it needs more information. The output promised is a clean set of books that a tax preparer can use.
Synthetic says pricing will start at USD $49 per month, about a quarter of the cost of a human staffed service. The company is starting with software, SaaS, and AI businesses because their accounting workflows are narrower and easier to model than the full small business market. Autonomous bookkeeping will only work if the system understands the business and sector well enough to avoid a range of potential errors, both simple and complex.
Ian Crosby, Founder and CEO, Synthetic:
“I'm not sure if it's yet technologically possible to make this work,”
That quote is perhaps one of the most interesting parts of the announcement. Crosby isn't selling certainty, but he's calling out and going after a hard problem. AI is still unreliable, and no founder wants books that look clean but are wrong. In accounting, a small error can affect taxes, financing, board reporting, future planning, and investor trust.
Synthetic is trying to solve that by narrowing the customer type and building around quality control. The company says the team is iterating on a prototype with early design customers. The firm hasn't disclosed revenue, customers, launch timing, error rates, or benchmark results as of yet.
Bookkeeping touches sensitive financial data such as banking, billing, and payroll. If AI can handle that work with enough accuracy, it could cut cost for early startups and reduce one of the most common back office bottlenecks for founders.
Jon Chu, Khosla Ventures:
“This one’s quite simple. You have a large, valuable problem that will inevitably be solved by AI. A founder who’s spent multiple decades working on the problem with near perfect founder market fit. And resilience and grit that’s been forged through multiple founding experiences and scale ups at companies like Shopify and Mercury,”
While Synthetic is headquartered in San Francisco, the Canadian angle is three time founder (ie. Bench and Teal) Ian Crosby. Bench was a Vancouver built bookkeeping company that became one of North America’s best known small business accounting platforms before it later shutdown and was acquired.
So why not base the company in Canada? It's a competitiveness question for Canada. Canadian founders keep showing up in high value AI and fintech infrastructure deals, but company formation, lead capital, senior hiring, and headquarters often land in the United States. If Canada wants the next generation of AI finance companies to scale here, it needs more than talent. It needs lead capital, customers, technical density, and a culture that lets ambitious teams move fast.
This also connects to Canada’s productivity and competitiveness challenge. AI can reduce manual work, but the economic value goes to the companies that own the IP, workflow, data, customer relationship, and product layer.
Synthetic has to show that AI can handle edge cases, ask the right questions, document decisions, and produce books that accountants, tax preparers, investors, regulators, and founders can trust.
The company’s longer vision is even bigger. Synthetic says it wants founders to press a button and watch a company assemble around an idea, including the website, incorporation, bank accounts, payments, accounting, and other operating pieces. Accounting is the starting point with the bigger ambition being the required operating infrastructure.
Can autonomous AI earn enough trust to run startup bookkeeping, or will reliability, tax risk, and financial controls keep humans in the loop longer than investors expect?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 13, 2026 | NCFA Resource | Risk Compliance And Regtech, Digital Identity Privacy KYC AML ATF
On April 8, 2026, the UK FCA published customer due diligence (CDD) findings from a multi firm review. The review covers practical weaknesses that matter to fintech teams, including thin policies, unclear review cycles, weak evidence records, poor senior approval steps, and audit gaps.
This is a UK resource, but the operating lessons travel well. Canadian fintechs still need local legal and compliance advice, including FINTRAC obligations where applicable. The FCA shows where customer checks break down when firms grow, add automation, rely on vendors, or treat onboarding as a sales funnel instead of a risk control.
The FCA review gives compliance and product teams a useful checklist for testing how customer due diligence works inside the business. It doesn't just ask whether a policy exists. It looks at whether staff know what to collect, when to escalate, how to record decisions, and how often files need review.
Stronger firms clearly separate standard CDD from enhanced due diligence (EDD) for higher risk customers. They define when senior approval is needed. They document EDD steps, keep review cycles clear, and test whether onboarding files support the risk decision made at the time.
The weaker examples are just as useful. The FCA points to firms that could not show what extra checks were completed for high risk customers, did not record key information about the purpose of a business relationship, lacked clear review schedules, or used the same people to onboard customers and review their own work.
For fintechs, fast onboarding can become a liability when the business cannot prove why a customer passed, why a file received extra review, or who approved a higher risk relationship. Policies are no longer enough, as teams need evidence.
This resource is useful for fintech founders, compliance leads, money laundering reporting officers (MLROs), onboarding teams, product managers, payments companies, lending platforms, crypto firms, crowdfunding portals, regtech providers, and financial institutions reviewing digital account opening.
It is especially relevant for firms that use automated onboarding, AI assisted reviews, third party identity vendors, risk scoring tools, or outsourced compliance support. Those tools can improve speed, but companies still needs clear accountability, review rules, exception handling, and audit trails.
The strength of this resource is its practical format. It shows good and poor practice side by side. That makes it easier for a fintech team to compare the report against its own onboarding journey, file review process, vendor controls, and board reporting.
The review also makes a simple point that many growing firms miss. Regulators want to see how decisions happen in real life. A clean policy document doesn't help much if customer files are thin, staff guidance is vague, or senior approval only exists in theory.
The limit is geography. The FCA findings reflect UK regulation and UK supervisory expectations. Canadian firms shouldn't treat this as Canadian legal guidance. They should use it as a practical benchmark, then test their own controls against Canadian requirements, sector rules, and legal advice.
FCA Customer Due Diligence Findings (primary FCA resource with good and poor practice examples)
FCA Risk Assessment Controls Findings (companion FCA review on customer and business risk assessments)
FCA 2025 To 2030 Strategy (broader strategy context for financial crime supervision)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 13, 2026 | NCFA Insight | Artificial Intelligence And Data, Capital Markets And Funding, Risk Compliance And Regtech
On May 13, 2026, Bank of Canada External Deputy Governor Michelle Alexopoulos delivered a speech on AI and productivity at the Ottawa Economics Association and Canadian Association for Business Economics Spring Policy Conference. Her message was direct. AI can help Canada grow faster, but only if firms turn adoption into workflow gains, owned IP, stronger investment, and real operating results.
Michelle Alexopoulos, External Deputy Governor, Bank of Canada:
“To put it simply, the Bank of Canada cares about AI because of its potential to significantly affect productivity, economic growth, employment and inflation.”
Adoption numbers show progress, but also a gap:
Statistics Canada gives the upside a useful range. AI could raise Canada’s annual labour productivity growth by 0.4 to 1.1 percentage points over the next decade. Its April 2026 analysis also found that Canadian firms that adopted AI were 16.8% more productive than firms that did not. Those numbers are encouraging but they aren't automatic.
The first wave of AI in many companies has been useful but shallow. Staff use tools to draft, summarize, search, analyze, and code faster. That saves some time but it doesn't always change the business or lead to large productivity increases. The harder work (and benefits) starts when AI enters high value workflows such as onboarding, fraud review, lending files, advisor support, treasury, payments, and compliance testing.
That's where fintechs and financial institutions should focus.
Better AI execution should show up in operating numbers. Faster approvals. Lower error rates. Stronger fraud detection. Lower cost per file. Cleaner compliance evidence. If a firm cannot measure the workflow gain, it has not found the productivity gain.
The Bank is also using AI in its own work. AI helps forecast inflation and economic activity, track sentiment, analyze household and business data, review earnings call transcripts, and monitor financial stability. AI is already entering regulated analysis, but the Bank is clear that AI doesn't make monetary policy decisions. It use AI to sharpen judgment, not replace accountability.
That same control point now runs through governed AI workflows in finance. The value isn't just a quicker answer, but a workflow that leaves evidence, keeps humans responsible, and gives risk teams something they can inspect.
The compute point is hard to ignore. Top U.S. technology firms like Alphabet, Microsoft, Meta, Amazon and Oracle spent roughly US$200 billion on AI investment in 2024. That figure doubled to about US$400 billion in 2025. The Bank also noted that AI data centres are expanding so quickly that power generation is struggling to keep up. Compute is no longer a back office technology cost. It's now industrial, economic and national security infrastructure.
Canada has started to respond. The federal AI Compute Access Fund helps Canadian SMEs access compute for AI projects, with project compute costs ranging from $100,000 to $5 million. That funding helps some companies get beyond small pilots, but it doesn't solve the whole problem. If Canadian companies cannot sustainably access enough affordable compute, the country risks training talent here while building value somewhere else.
For fintech operators, compute affects competitiveness. AI in fraud, risk, underwriting, compliance, markets, and customer support needs secure data pipelines, model testing, and monitoring. Firms that cannot fund compute and controls will stay stuck in trials. While companies that can fund and execute both have a better chance of turning AI into operating advantage.
The Bank’s labour message is more balanced than the public debate. There is no evidence yet that AI is replacing workers on a large scale. About 90% of Canadian businesses that adopted AI reported no staffing effect. Roughly 4% reported job creation, while about 6% reported employment decreases linked to AI use.
The reality is reported job data can lag, and i t doesn't mean the AI labour risk narrative fake. The Bank noted weak hiring in AI exposed roles such as entry level coding and customer service. It also flagged younger workers as a group to watch. This connects directly to recent evidence on AI spending and workforce redesign and AI’s hidden workforce costs. The question is how companies are redesigning workflows in the age of AI. Will they break training channels, judgment, supervision, and customer trust?
The time savings are real. The Bank cited Indeed research showing that 57% of Canadians who use AI at work save one to two hours a day, while 22% save three to five hours. The value depends on what happens next.
If workers use the time for better service, stronger analysis, and tighter controls, then productivity can improve. If companies only cut junior roles, then they might lose the next generation of trained operators.
Execution takes money. AI firms and AI adopting fintechs need a lot of investment to compete and the middle stage is expensive. Canada has strong research and strong founders, but too many companies hit a capital wall before they become global platforms.
Budget 2025 recognized part of the gap. It proposed $750 million to support Canadian firms facing early growth stage funding gaps, with details expected in 2026. It also proposed $1 billion for BDC to launch the Venture and Growth Capital Catalyst Initiative. This is good but allocation matters. Capital needs to reach firms when compute, enterprise sales, compliance, and global distribution become expensive.
Beyond just announcements, Canada needs a fuller capital stack with more domestic lead investors, growth equity, private credit, venture debt, angel capital, compliant investment crowdfunding, strategic corporate capital, and better public market routes for quality scaleups. Capital should help productivity companies scale from Canada, not push them to sell early or move the value elsewhere. CVCA reported $56.5B in Canadian private equity investment across 483 transactions in the first nine months of 2025, the strongest nine month period on record. More of that capital needs to back productivity firms that can scale from Canada and keep IP, customers, and senior talent here.
Fintech investment is concentrating into fewer larger deals, which makes scale-up capital more important. Otherwise, Canadian companies may build and test the prototype in Canada but scale the value somewhere else. That’s the leakage problem. That is where fintech’s role in Canada’s productivity revival becomes practical. Better access to capital, faster technology adoption, and stronger business investment need to show up in firm level execution.
The OECD’s 2025 Canada survey lays out the structural problem clearly. Canada’s productivity performance has lagged peers, and limited investment in intellectual property and digital technologies has held back growth. That is the bridge between AI use and AI value.
In a recent Financial Post op ed on Canada’s IP gap, Louis Carbonneau argues that Canadian founders often build strong technology but lack the literacy, capital discipline, and enforcement capacity needed to own and extract value from it. He points to weak IP diligence in venture funding, limited IP education, thin enforcement culture, and policy support that often helps companies file a first patent without helping them turn it into a defensible business asset.
If Canadian companies use imported AI tools but don't own proprietary workflows, data layers, patents, models, or distribution channels, the productivity gap can widen and value continue to leak away. IP strategy shouldn't be a legal afterthought. It needs to be part of the productivity and growth plan.
Budget 2025 proposed new IP support, including $84.4 million over four years to extend Elevate IP, $22.5 million over three years to renew support for the Innovation Asset Collective’s Patent Collective, and $75 million over three years to extend the National Research Council’s IP Assist Program. That support can help, but only if it's tied to business strategy, and follow through after the first filing.
The IP Canada Report 2025 shows an eye popping statistic. In 2024, nearly 86,500 patents, trademarks, and industrial designs were filed in Canada by non residents. In 2023, Canadian residents filed about 44,500 IP rights abroad. Although Canada participates in global IP markets, participation is not the same as owning the most valuable parts of AI enabled productivity.
Canada needs to treat AI execution like an economic buildout and not another software trend. Adoption is still early. Compute is expensive. Jobs are changing. Capital is thin at the scale up stage. IP decides who keeps the value.
That's how AI adoption improves becomes Canadian productivity and competitiveness. Not through more pilots. Not through more research reports. Through financed, governed, IP protected companies, skilled workers, and community capacity that can turn AI into practical gains.
Can Canada turn AI adoption into owned productivity gains, or will the biggest value flow to foreign platforms that provide the tools, compute, capital, and distribution?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 13, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech
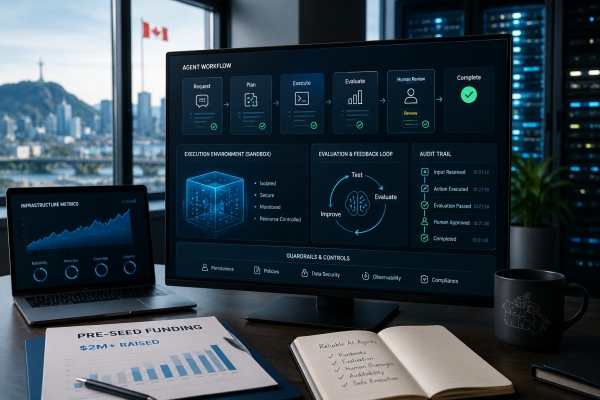
On May 6, 2026, Montreal based Jetty raised over $2 million in pre seed funding to build infrastructure for reliable agentic AI applications. AQC Capital and Hidden Layers Capital led the round. Mila Ventures, Akinox, and strategic angel investors with AI systems experience at Google and Meta AI also joined. While the round is early, the production problem is already very real.
Jetty is targeting the gap between AI agents that work in demos and agents that can handle enterprise workflows. Jetty's platform gives agents structured runbooks, isolated execution environments and evaluation loops. The agent gets a defined job, runs in a controlled space, checks the result, and improves with human oversight. It's operating infrastructure for AI work that has to be repeatable, observable, and safe enough to review.
Jonathan Lebensold, Founder and CEO, Jetty
“Most AI systems today are still fragile - they work in isolation but break under real-world complexity,”
Gartner predicts that over 40% of agentic AI projects will be cancelled by the end of 2027 because of rising costs, unclear business value, or weak risk controls. McKinsey’s 2025 global AI survey found that 23% of respondents are scaling agentic AI in at least one business function. Another 39% are experimenting.
These numbers explain Jetty's opening. Enterprises want to implement agentic AI, but they need proof before they let agents touch real workflows. Buyers need agents they can test, limit, monitor, correct, and review. This type of rigorous testing isn't optional in finance, insurance, health, and public services to name a few.
Doina Precup, Professor at McGill University and CIFAR AI Chair:
“As AI systems become more autonomous, ensuring they behave reliably in complex environments becomes a central challenge.”
Financial institutions will only use and trust AI agents when the workflow transparently shows what happened, who approved it, and how mistakes get corrected.
Controls matter in onboarding, fraud review, compliance checks, and underwriting. They also matter in customer support, reporting, and internal operations. If an agent makes a mistake, teams need to see the inputs, how the tool used the inputs, the outputs, approvals, and any corrective actions.
The near term opportunity isn't just replacing staff with free running agents. It's reducing manual drag in workflows where humans still own the decision. That lines up with governed AI workflows in finance, where the value comes from evidence, reviewability, and accountability.
Canada has deep AI research talent, but productivity gains depend on companies that turn research into owned enterprise infrastructure. Reliable agent systems could become part of that. If Canadian firms build tools for evaluation, audit trails, controlled execution, and human review, they can own more of the AI workflow stack instead of only using tools built elsewhere.
This is still an early stage round, but the production problem is real. Jetty hasn't disclosed revenue, customer metrics, deployment volume, or reliability benchmarks. The company says it will use the funding to accelerate product development, expand engineering, and support enterprise customer deployments. That is the right use of proceeds, but the market will need proof that Jetty can make agents reliable in regulated workflows, not just promising in pilots.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016