




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


AI | July 25, 2025

Image courtesy of Mantle Starter website
On July 24, 2025, Toronto-based fintech Mantle announced the launch of a new free AI cap table management platform called 'Mantle Starter' for founders to track ownership and raise their first round of capital. The service gives startups a way to automate equity records without paying for expensive software in the earliest stages of growth.
Mantle Starter allows unlimited users, such as founders, employees, investors and advisors, access to use an AI featured called Extract to read documents such as SAFEs, option grants and share certificates to build a structured cap table automatically. This automation eliminates the need to manually enter each transaction, which is both time consuming and often prone to mistakes.
The platform also supports one click export of data in the Open Cap Table Format (OCX), which is a standard that law firms and investors are adopting for easier sharing of ownership data. Mantle says that the free Starter plan will cover the needs of most early stage companies and that more complex features such as 409A valuations, preferred share classes and Nasdaq Private Market integrations will remain part of its paid tiers.
Until Mantle's free offering, many small teams have to choose between manual spreadsheets or paid cap table software, but Mantle Starter removes this barrier. There are some alternatives in market but mostly with caps or less functionality such as Carta Launch, Pulley Pricing, and Gust Equity Management.
Early users have responded positively on Product Hunt and other review platforms like G2, highlighting simplicity and customer support, though some reviewers on G2 have pointed out that advanced reporting and additional workflows remain on the roadmap.
“Unlimited stakeholders for free? That’s wild, tbh. Setting up cap tables always felt like a pain—love how you’re making it actually founder-friendly. Big win fr!”
— Joey Zhu“As a founder who’s battled cap table chaos myself, your AI‑driven approach to unlimited stakeholders + flat‑fee pricing feels like a breath of fresh air.”
— Comment on launch page discussion
For the NCFA community, Mantle Starter is significant because it lowers the cost and effort of creating clean equity records, which directly supports capital formation, investor readiness and founder education. By using AI to remove tedious setup and by adopting an open data standard, Mantle is making ownership tracking easier at a time when startups need every advantage to attract funding and talent. It's a good way to get early control of your funding outreach plan, and establish a clean cap table from day 1.
Can't get more affordable than free, so there's no excuses to figure out your approach to early stage equity management. As more Canadian founders take advantage of these tools, it will help improve record keeping quality, improve transaction friction with investors and broaden access to capital markets. Those interested can explore Mantle Starter at withmantle.com/free.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Web3 Jobs | July 23, 2025

The digital workforce is evolving fast. Remote work is no longer a trend - it’s the norm. But there’s a deeper shift happening that’s reshaping how we define work, identity, and opportunity: Web3. And at the frontlines of this revolution? Women. From developers to strategists, artists to marketers, women are carving out space - and power - in the decentralized world of Web3 jobs.
A Web3 nomad is a professional leveraging decentralized technologies, crypto networks, and blockchain protocols to work anywhere, anytime - without being tied to traditional employers or physical offices. These aren’t your typical remote workers on Slack and Zoom. They’re part of DAOs (Decentralized Autonomous Organizations), using crypto wallets as logins, earning in tokens, and managing their careers through reputation scores instead of résumés.
This shift isn’t just about new tools. It’s a complete restructuring of how people earn, collaborate, and build wealth online. And it’s drawing in more women than ever before, especially those who’ve been underserved or overlooked in traditional tech sectors.
Women are embracing Web3 jobs not because the system is perfect, but because it offers something rare: possibility without permission. Unlike legacy tech industries dominated by gatekeepers, Web3 is still fluid. It rewards output, creativity, and initiative over credentials.
Here’s why Web3 is fertile ground for female talent:
Despite the jargon, Web3 jobs aren’t all about coding. In fact, some of the highest-demand roles don’t require deep tech skills. The space is still young, and it needs a wide range of talent to grow, organize, and communicate.
Every one of these roles exists outside of traditional job boards. Most are project-based or governed by contributor reputation within DAOs. Salaries vary, but in many cases, Web3 pays better than Web2 - especially in token-based systems with upside potential.
You don’t need to “wait until you’re ready” to enter the Web3 world. Learning in public, contributing to projects, and showing up consistently gets you further than just taking courses or collecting certifications.
To navigate Web3 jobs, you need to be fluent with the platforms and tools where work happens. Here's a quick breakdown of where things go down:
Let’s not pretend this space is perfect - Web3 is still volatile, chaotic, and full of hype. But that’s also what makes it open to disruption and new voices. The reward systems, autonomy, and flexibility are lightyears ahead of anything in corporate tech.
Key advantages of Web3 work:
For women who’ve been underpaid, under-mentored, or underestimated in traditional tech, these dynamics are a game-changer.
Web3 isn’t just changing how we work. It’s changing who gets to lead. And women are already rewriting the script - not as tokens for diversity panels, but as architects of the next digital economy.
From Bali to Berlin, Lagos to Lisbon, a new class of Web3 nomads is rising - self-directed, skilled, and unstoppable. They're building portfolios, collecting tokens, and gaining influence - not just jobs.
If you’re looking for more than a paycheck - if you want autonomy, community, and upside - then Web3 might just be your next move. The ecosystem is wide open. And Web3 jobs are waiting.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Research | July 22, 2025
Image: Freepik AI
According to a recent WORKBank audit, a major new study from Stanford's SALT Lab, 41% of Y Combinator-backed AI agent companies are
to tasks that workers have no desire for automation. These 'no go zones' represent tasks that are technically automatable but socially or emotionally rejected by workers. It's a growing disconnect that highlights a fundamental challenge for the future of work.
Should AI companies and investors automate tasks that people do not want or lead to no progress, no matter how advanced these systems are?
The WORKBank database is based on a comprehensive survey of data collected between January and May 2025 from 1,500 U.S. workers across 104 occupations and 844 occupational tasks. Each task is drawn from the U.S. Department of Labor’s O*NET database and evaluated by worker preferences and AI expert assessments. Responses were collected using an audio interface to reflect practical real world task experience.
This structured format asked workers whether they would want a task fully automated by an AI agent, and how much human collaboration they believe is needed to maintain task quality.
To assess the balance between automation and augmentation, the research team created the Human Agency Scale, a 5 level scale from H1 (no human involvement) to H5 (essential human involvement).
The most preferred response across the workforce was H3, an equal partnership between humans and AI agents. This level was dominant in 47 out of 104 occupations, however for 47.5% of tasks, workers wanted more human involvement than experts believed was technically necessary. It's a gap that could evolve into resistance points in high efficiency AI rollouts.
Despite concerns, 46.1% of tasks received a positive rating for automation. Workers were most supportive of AI when it freed up time for more important work (69.4%), reduced repetitive or tedious tasks (46.6%), or improved quality (46.6%).
On the other hand, resistance appeared from fear of losing trust, jobs, or creativity. Among those expressing concerns, 45% cited lack of trust, 23% named job loss, and 16.3% described the loss of a human touch. Arts, Design, and Media was the sector with the lowest interest in automation where only 17.1% of tasks received a positive score.
Researchers compared the WORKBank tasks with descriptions of companies backed by Y Combinator’s public portfolio. The results show a concentration of capital in areas workers are skeptical about.
41% of companies were mapped to tasks in the Low Priority Zone or Automation Red Light Zone, where worker demand is weak or negative, while many tasks in the Automation Green Light Zone and R&D Opportunity Zone where workers want automation remains underfunded (Read: ripe for AI task automation).
The research also looked at how AI is impacting the demand for certain job skills. Tasks that require higher levels of human agency usually involve interpersonal and decision making abilities rather than data analysis or technical information processing.
Comparing skill rankings based on wage data from the U.S. Bureau of Labor Statistics with human agency requirements revealed a trend away from solo technical execution toward organizational coordination, collaboration, and judgment. This suggests a shift in the kinds of competencies that AI will complement rather than replace.
Canada is investing heavily in AI innovation, fintech development, and reskilling strategies for the future economy. The WORKBank research shows that AI innovation must be aligned with worker needs and social context. If Canadian fintechs and investors focus only on technical feasibility without considering how workers feel about automation, they risk building tools that sit unused, untrusted, or even opposed. AI companies and investors must engage the people whose work is being transformed.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 21, 2025

Image: Freepik/DC Studio
Canada’s home-care system is approaching a pivotal moment. According to federal projections, the country will need 39,000 additional personal support workers (PSWs) by 2043 to keep up with demand. As the population ages and more Canadians express a preference to age in place, this gap will only grow especially in rural and remote areas, where the care shortage is most severe.Provincial PSW Shortage Heat‑Map: Scheduling Tech for Rural & Remote Gaps
In Budget 2024, the federal government acknowledged this growing concern, flagging urgent incentives for rural recruitment, training, and deployment. But without better workforce management, even new funding can fall short. To bridge this divide, agencies must turn to smart scheduling and care management tools that optimize existing staff, reduce missed visits, and improve continuity of care no matter how remote the setting.
While urban centres like Toronto and Vancouver face their own home-care challenges, rural communities across provinces are confronting a different kind of crisis: chronic staffing shortages, long travel distances, and high burnout rates among the few remaining PSWs.
Provincial heat-maps reveal some of the hardest-hit areas:
| Province | High-Demand Regions | Rural Challenges |
| Ontario | Thunder Bay, Timmins, Kenora | Vast geography, staff shortages, long travel |
| Nova Scotia | Cape Breton, rural South Shore | Aging population, low PSW retention |
| Alberta | Northern Alberta, Peace River | Harsh weather, sparse housing, recruitment |
| Manitoba | Interlake and Northern regions | Limited access to training, high turnover |
| Newfoundland | Labrador and outport towns | Transport access, isolation, overwork |
In these zones, agencies often can't fill shifts, and residents go without consistent care, leading to emergency visits or premature long-term care admissions.
The federal Budget 2024 introduced welcome support: incentives to recruit PSWs to under-served regions, expand training pipelines, and bolster home-care programs. However, infrastructure without intelligent deployment tools risks underperformance.
Many providers still rely on manual spreadsheets or outdated systems that:
This results in wasted time, unbalanced workloads, and frustrated care teams—especially in areas where every PSW hour counts.
ShiftCare Canada offers a dedicated care management and scheduling platform that helps Canadian agencies meet growing demand—without overextending limited staff.
With ShiftCare, providers can:
By making it easier to assign the right carer to the right client at the right time, ShiftCare helps agencies maximize their existing workforce while reducing burnout and missed visits.
Whether you're operating in rural Nova Scotia or northern Alberta, smart scheduling is no longer optional—it’s mission-critical.
Here’s how modern care management software stacks up against traditional systems in rural care environments:
| Feature | Manual/Legacy Systems | ShiftCare Canada |
| Geographic Scheduling | ❌ Not supported | ✅ Optimized for travel time |
| PSW Availability Tracking | ❌ Often outdated | ✅ Real-time mobile updates |
| Multi-Region Scheduling | ❌ Cumbersome | ✅ Streamlined with filters and templates |
| Alerting for Cancellations | ❌ Manual follow-up | ✅ Instant push notifications |
| Compliance & Documentation Logs | ❌ Risk of error | ✅ Built-in audit trails and reports |
By using purpose-built care management scheduling tools like ShiftCare, providers can stretch their workforce further, without stretching them too thin.
The PSW shortage isn’t going away. But how we respond to it—through policy, planning, and technology adoption—will define the future of community-based care in Canada.
With platforms like ShiftCare Canada, home-care agencies can better navigate the challenges of rural service delivery, empower their staff, and ensure that no matter where a client lives, care shows up on time.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 21, 2025

Image: Freepik/rawpixel.com
Creating a proper website for a portfolio is a big deal for anyone who works online. While a polished portfolio might raise your credibility and help you gain recognition in professional circles, a sloppy one can cost you an offer.
A rich portfolio can be used interchangeably with a CV and a business card. It is a showcase of you as a professional.
It can be a collection of your past works, for example, illustrations, a Linktree to sites you built, a story about events you organized. The format of a portfolio is mostly determined by its substance.
If you are a programmer, a designer, a copywriter, an event manager, or an SMM specialist, you need a neatly made portfolio page to present to your potential employers.
There’s a reason why even successful creative producers have their own websites. Having a webpage dedicated to you makes it easier to find you online. By publishing your portfolio, you basically invest in your future employment.
You should choose a reliable platform that won’t suddenly go on maintenance when you need to share it.
Pro-tip: always save the backups. It might also be a good idea to have your portfolio saved on your local device.
Google Docs
It may seem funny, but actually Google Docs is a good starting point. It’s better to have a portfolio in some shape or form than nothing at all. With creativity, you can make even a simple Google Doc shine.
Unfortunately, this option has obvious limitations and won’t work long-term when you have more projects, more pictures, and more info to share.
Pros
Cons
A Portfolio Platform
There are specialized platforms to publish your portfolio and look for a job at the same time. Examples include Behance and ArtStation. They already have a much more compelling design than Google Docs, but their page structure is always the same and doesn’t have much room for personalization. Besides, ArtStation is made specifically for artists and graphic designers, and Behance is mostly used for job hunting. Professionals often have links to their actual portfolios on their Behance page.
Pros
Cons
A PDF File
If you don’t want to think about hosting a website, you can just make your portfolio into a pretty single document and upload it to a cloud of your choice. Or you can share it directly through a USB flash drive. It’s a bold choice. A viable one, although not the most convenient.
Pros
Cons
CMS
You can make your own website from scratch with Content Management Systems like WordPress or Joomla. It’s certainly one of the better options, but a tricky one. To use CMS to its fullest, you need to have at least basic coding skills. Not to mention that they may be hard to navigate for a beginner.
Pros
Cons
Website Builders
A website builder presents the best of both worlds. It offers a lot of room for customization with templates and ready-to-use blocks while being easy to use and intuitive. There are both free and paid plan options.
Pros
Cons
There are, however, options that are both easy to use and affordable. Site.pro is a website builder with 200 templates, lots of plugins, and an AI website generator function. Its minimal plan starts at only $1.3 a year.
With Site.pro you can build a website in less than 10 minutes with no prior knowledge.
Follow these steps:
Your website is ready to go!
Structure is always the key. Nothing sells a portfolio like compelling storytelling. Split your website into sections.
You can use this plan as an example.
Main Page
Here should be all the navigation to other sections. At a single glance at your homepage, a user should get a general idea of who you are, what you do, and what you can offer. That’s also why naming is so important. Both your domain and the text on your main page should include your name.
About Me
It’s a place to introduce yourself. Your portfolio has to complement your CV and give the most positive first impression. There shouldn’t be too much text, just enough to get to know you in a nutshell. Your actual work will speak for you.
My Projects
There’s a simple rule: if you’re only starting out, you should include every project you worked on. But if you have more than a couple of projects under your belt, you should only choose the ones that showcase your abilities best. Keep in mind, no one is going to browse through your entire working history.
Place your works chronologically and give them a little context: what you did, when, what the results were.
If you use someone else’s material, remember to give proper credit.
Contact Me
Leave links where people can find and contact you: your email address, your social media. Make sure that your email address is active and all the links are properly named and actually lead where they say they do.
The draft of your portfolio is ready. What now? You should make it both good-looking and convenient.
Here are 4 tips for that:
Don’t hesitate to put the link to your portfolio on your professional and personal social media, share it when applying to a new job, and be proud of your work at all times.
And be sure to ask for feedback from people you trust. It can be other professionals, your colleagues, or friends.
Your portfolio has to keep up with your professional journey. Remember to update it with new projects and change links in case you lose access to your email address or social media accounts.
Making a portfolio is not an easy task, but with the right tools, references, and attitude, everything is possible. Everyone can build a website and make their portfolio truly shine. Prove it, try it yourself!
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Funding | July 16, 2025
Image courtesy of Quandri
Vancouver and Boston-based insurtech Quandri has raised US$12 million to accelerate the rollout of its AI-powered Renewal Intelligence Platform across the Canadian and U.S. insurance markets. The round was led by Framework Venture Partners, with follow-on investments from FUSE and Defined Capital, and strategic backing from Intact Ventures. To date Quandri has raised over US$20 million since founding in 2021.
The new capital will fuel a hiring push, deepen AI engineering capacity, and support the opening of a new U.S. office in Boston alongside the expansion of its Vancouver headquarters.
"We’ve had strong conviction in our vision from day one, but having new investors like Framework and Intact supporting our journey adds real momentum," said Jackson Fregeau, co-founder and CEO. "Their support affirms the value we’re delivering to brokerages and agencies, and gives us the insight and fuel we need to keep pushing the industry forward."
In a recent interview with the National Crowdfunding and Fintech Association (NCFA), Quandri co-founder and CEO Jackson Fregeau shared additional insights on the company’s platform, market traction, and future plans.
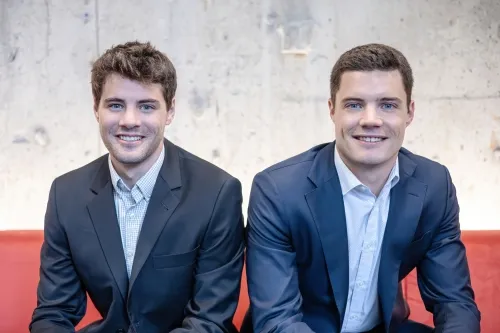
Image: Quandri Co-founders, Jackson Fregeau (CEO) and Jamieson Fregeau (President)
Quandri’s Renewal Intelligence Platform is designed specifically to automate renewal servicing workflows for insurance brokerages and agencies. It stands out in a crowded insurtech space due to its deep contextual understanding of insurance data, its focused product design, and its high degree of configurability.
Jackson Fregeau, co-founder and CEO:
"What differentiates us as a business is threefold.
First, deep intelligence. We ingest millions of insurance policies every month, and our AI has a deep understanding of underwriting guidelines across all regulatory environments in North America. This means we have a deep insurance context and can apply this to the automation of a process — taking it all the way to communication with a client, thanks to the trust our customers have in us.
Second, focus. We chose a clear focus area and spent our time driving as much value as possible. With renewals as an example, we aren’t just automating the process — we’re driving additional revenue through cross-selling and upselling, while also increasing retention rates.
Third, a high degree of configurability. Our AI can analyze hundreds of variables on a single renewal to surface insights and deliver action. Our customers can configure all of this if they want, to build a highly personalized and relevant experience for their clients."
Brokerages using Quandri have reported major productivity and revenue improvements.
"We’ve seen customers save over 6,000 hours a year by automating their renewal review process — work that previously required full teams to manually review documents," said Fregeau. "For example, one of our customers repurposed over 5% of their workforce — 10 of 200 employees — shifting experienced team members into higher-impact roles that support growth and improve the client experience.
"In another case, one brokerage reported a 350% return on investment in just a few months — proof that this isn’t just about saving time. It’s about unlocking a more resilient, scalable way to run a brokerage. And the benefits go beyond operational efficiency; one brokerage reported a 2% increase in client retention, driven by the ability to proactively reach out to customers with consistent, value-based renewal conversations."
Quandri has been operating in the U.S. for the past two years, but has seen significant acceleration over the last 12 months.
"The biggest learning has been about market dynamics. It’s 50 different markets, with a high degree of fragmentation and regionalism," said Fregeau. "Understanding how this all worked, and ensuring our platform could support this complexity was very important.
"What we did find consistent across the board is that brokers and agents are facing the same core challenges: shrinking margins, excessive manual work, and insufficient time for clients. If anything, the urgency for AI-powered solutions feels even greater in the U.S., where scale and complexity make these pain points harder to ignore."
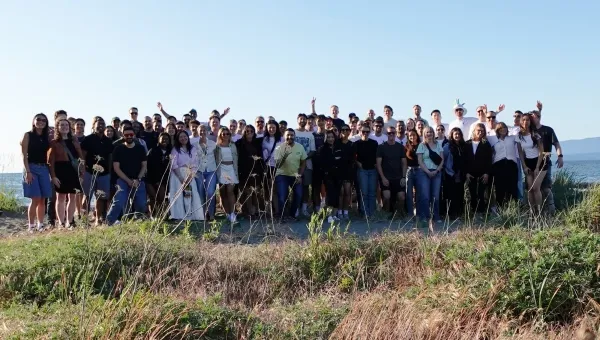
Quandri team June 2025
The company plans to hire more than 40 people before the end of 2025 and has opened a new 15,000-square-foot office in Vancouver to support its growth.
"Our priorities are expanding our integrations so we can serve more customers across the U.S. who want to use our platform," said Fregeau. "We’re also hyper-focused on growing our engineering team to drive deeper AI capabilities and scale our impact across the broker and agent servicing stack."
Fregeau also offered reflections on scaling a fintech business into the U.S., especially for Canadian startups.
"While there is work when it comes to data localization, regulatory alignment, and compliance, those aren’t significant hurdles to overcome. The larger barriers are related to your product-market fit (PMF). Don’t assume PMF in one market will translate to the other — even though they may look similar, they are different.
"Do your due diligence, interview prospects, understand the real pains in the market and what’s different from your home market. It will take time to learn this, and that's okay, because it's worth it. However, we initially underestimated the differences and could have made better decisions had we been more open-minded in the beginning."
Fregeau added:
"There’s massive opportunity, so go for it. Getting to 70% operational isn’t that hard — the hard part is taking something that works in 70% of cases, and making it work in the enterprise 95% of the time, predictably and consistently. Otherwise, you won’t get adoption, renewals or expansions. Listen to your customers, but also know when you need to give them something that they aren’t asking for that will solve the root of their problem. There is no secret formula besides hard work and doing the gritty things right, day in and day out, over a long period of time."
Quandri's recent financing round highlights the demand for specialized, AI powered tools built for legacy industries. By focusing on renewals and customer engagement in a data-drien environment, Quandri is helping clients boost operational gains and capture longer term strategic value. Expanding product suite and footprint across North America, Quandri's stack could become foundational infrastructure for insurance broker operations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Trade and Tariffs| July 10, 2025
Image: Freepik/rawpixel.com
As of July 8, 2025, Reuters reports that the U.S. has collected about $100 billion in tariff revenues in 2025, and according to U.S. Treasury Secretary Scott Bessent, tariff revenue projections could reach $300 billion by the end of this year.
Customs duties in May alone reached $22.8 billion or almost 4x the amount one year prior. While the White House views this revenue as a fiscal benefit, economists caution that tariffs create economic distortions, raise costs for importers, and increase prices for consumers.
FactCheck.org analyzed Treasury data and found that U.S. customs and tariffs generated $37.8 billion in April and May combined, with $22.2 billion in May alone, which is well below the $88 billion those months were referenced to yield, let alone the larger $122 billion claimed later. It highlights how public statements about tariff income often exceed actual collections.
The Business Council of Canada reports that Canadian exports to the U.S. dropped 26.5% year-over-year, with Canada's share of exports to the U.S. falling from 78% to 68%.
Export volumes fell 10.8% in April before seeing a small 1.1% rebound in May but remain historically low. The Business Council of Canada warned that this declines is another “wake-up call” with advocates pushing to diversify trade into Southeast Asia, and move ahead with the One Canadian Economy Act .
Canada’s proposed 3% digital services tax was supposed to raise C$7.2 billion over five years but was dropped by PM Carney late June after it triggered the suspension of trade talks .
According to The Guardian, Nobel laureate economist Joseph Stiglitz warned that Canada's repeal represents “a troubling precedent for economic sovereignty,” describing it as a resignation to U.S. economic coercion instead of a strategic trade policy.
On July 7, Trump issued letters announcing tariffs between 25–40% to start August 1 on imports from 14 countries, including South Korea and Japan. Canada wasn't included on this list but is still subject to existing 25% tariffs on steel, aluminum, and autos, along with 10% U.S. duties on energy and potash not covered by CUSMA. Copper tariffs are also in Trump's sights which is another concern. The S&P 500 fell nearly 1%, it's largest global drop in weeks following the tariff letter announcement.
Tariff uncertainty is directly affecting Canadian fintechs. Cross-border payment providers are facing higher Foreign Exchange (FX) costs and more regulatory complexity.
Trade finance platforms have warned that rising tariff uncertainty is leading to higher invoice default rates among SME exporters and creating pressure on fintech services who need predictable trade flows.
According to PYMTS, many fintechs are accelerating adoption of tokenized receivables and embedded credit insurance tools to help manage risk, speed up funding, and reduce exposure to trade disruption.
“Tokenization… offers the potential to streamline the inefficient $9.7 trillion trade finance market.”
Canada and the U.S. are negotiating a new security and economic partnership with a July 21 target date but without consequences for missing the deadline, extended talks will cause further economic harm. And if there is no deal, Canada could move forward with retaliatory tariffs while providing targeted relief, which could include SME and export-orientated fintechs.
Looking to diversify and reduce reliance on U.S. markets, Canada is moving quickly to finalize a free trade agreement with Southeast Asian nations. Foreign Minister Anita Anand confirmed that “work is being done with alacrity to finalise the text of the free trade agreement” with ASEAN, adding that economic cooperation will also include energy, food security, digital economy, and artificial intelligence.
The July 21 deadline will impact Canada’s exports and redefine trade, innovation, and the financial ecosystem, as it impacts geopolitical volatility, SME access to financing, and investor perceptions. This is a decisive moment for Canada’s economic resilience and fintech innovation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016