




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Nov 9, 2026
Work can be stressful, especially in our busy world. Many people feel pressured to meet deadlines and juggle multiple tasks, which can leave them feeling overwhelmed. Work stress and fatigue can hurt both your job performance and your personal life. Recognize these feelings and look for ways to reduce them for better overall well-being.
Many believe that working long hours is unavoidable. However, you can find simple ways to manage stress and boost your energy for a more balanced and satisfying work life. Here are some strategies to help you reduce work stress and fatigue.
Setting boundaries is the first step in managing stress. In a world that expects you to always be available, define your work hours. Let your colleagues know when you are available, and stick to that schedule. When you decide when to stop working, make sure you follow through. This may mean turning off notifications or avoiding emails after work hours.
Taking breaks throughout the day is also crucial. Short breaks can increase your productivity and clear your mind. Use these moments to move away from your desk, go for a walk, or take deep breaths. These small pauses can refresh your energy and help you focus better.
Physiotherapy North York can help reduce work-related stress and fatigue. It improves movement and function, which can help you feel more comfortable. Stress often shows up as physical tension, especially in the neck, back, and shoulders. Physiotherapists can identify and treat these tensions to reduce discomfort.
Physiotherapy also teaches you how to use your body correctly. Learning to sit, stand, and lift properly can help prevent strain and injuries over time. Many physiotherapists provide personalized exercises that meet your needs, helping you keep a healthier posture and movement. The benefits of physiotherapy go beyond relaxation; they help you manage your body better and improve your overall health.
Your physical health greatly affects how you manage stress. Regular exercise is an excellent way to reduce stress and fatigue. Whether you prefer walking, yoga, or the gym, choose an activity you enjoy. Exercising releases endorphins, which help lift your mood and boost your energy.
Good nutrition is also vital. Eating a balanced diet filled with whole foods, fruits, vegetables, and lean proteins provides the energy you need for the workday. Staying hydrated is important too, as it helps your body perform at its best.
Chiropractors offer another way to reduce stress and fatigue by focusing on spine health. Proper spine alignment can improve how your body functions. Misalignments can cause discomfort and tension, which may increase stress. Regular chiropractic adjustments can help bring balance back and relieve these issues.
A chiropractor often combines adjustments with guidance on posture, ergonomics, and lifestyle changes. This complete approach treats not just the symptoms but also the underlying causes of your stress and fatigue. Many clients feel more relaxed and energized after chiropractic sessions, showing how spinal health affects well-being.
Adding relaxation techniques to your daily routine can help you manage stress. Simple practices like deep breathing, meditation, or mindful walking can calm you and reduce anxiety. Taking a few minutes each day to focus on your breath or appreciate your surroundings can greatly shift your mental state.
Mindfulness helps you stay in the present moment, allowing you to step back from overwhelming thoughts. It can also improve your focus, making it easier to complete tasks clearly. As you practice mindfulness, you may feel calmer and more resilient when facing workplace challenges.
No one should handle stress alone. Building a strong support system at work can make a big difference. Sharing experiences with trusted colleagues can provide emotional relief and build friendship. Team-building activities or group discussions can create a supportive atmosphere, making it easier to tackle challenges together.
If stress feels too heavy, consider talking to a counsellor or therapist. Sometimes, an objective view can help you find specific strategies for your situation. This resource can help you manage stress better and improve your mental health.
In the end, reducing work-related stress and fatigue needs a well-rounded approach that includes physical health, emotional well-being, and supportive relationships. By being proactive about your needs, you can create a more balanced and fulfilling work experience. Small changes can lead to big improvements in your quality of life.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
October 20, 2026 | NCFA Story Intelligence | Capital Markets And Funding, Leadership And Governance, Artificial Intelligence And Data
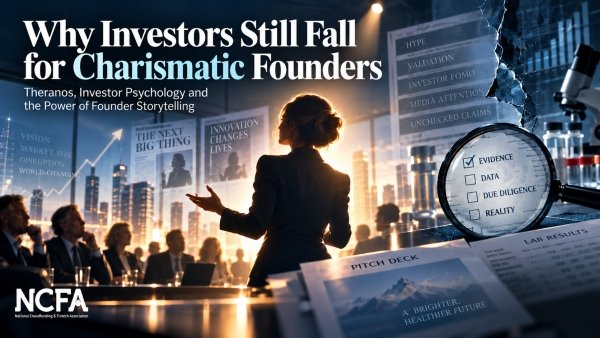
On October 16, 2026, You Can See Everything opened in Canadian theatres. Four days later, the documentary about Elizabeth Holmes is still one of the biggest stories at the North American box office. It opened with about US$15 million from only 855 screens. That's an extraordinary result for a documentary about a founder whose company collapsed years ago and is now serving a federal prison sentence.1
Holmes didn't raise money because investors wanted to lose it. She sold a future that sounded possible, surrounded herself with people whose reputations made belief easier, and built a company whose story moved faster than outsiders could verify the technology. By the time the evidence caught up, investors had committed hundreds of millions of dollars.
What follows is a story of how founder trust becomes part of an investment case and how evidence can lose ground to momentum. The same human problem returns whenever investors finance an uncertain future.
The idea is bigger than the product. Theranos tells investors that its technology can run a broad range of tests from tiny amounts of blood. The company is private, the technology is closely guarded and outsiders have limited access to what happens inside the machines. That secrecy can sound like competitive protection when the founder is believed.
Conviction becomes part of the product. Holmes presents Theranos as a mission driven company that can transform healthcare. Investors hear a founder who appears certain about the future and willing to devote herself to it. That confidence is valuable in a startup because the product, market and operating model are all unfinished. It also makes the founder unusually important to the investment case.
The board looks formidable. Fortune described Theranos in 2014 as having one of the most illustrious boards in American business. George Shultz, Henry Kissinger, William Perry, Sam Nunn, James Mattis and other prominent figures gave Holmes access to experience, networks and public credibility that most young founders could never assemble.4
The board can't substitute for technical oversight. A famous director can open doors and challenge strategy. That doesn't automatically give a board the scientific depth to test a diagnostic platform. Prestige can make a young company look safer while leaving the hardest operating question untouched.
The numbers make the story feel real. A multibillion dollar valuation, hundreds of millions raised and national retail partnerships give investors familiar business signals. Those signals usually matter. They become dangerous when investors start treating them as evidence about the one thing the company still has to prove.
The media helps close the loop. Holmes becomes a symbol of Silicon Valley ambition. WIRED has now revisited its own 2014 coverage and acknowledged how media enthusiasm helped amplify the founder story before the science received enough scrutiny.7 The founder earns attention because investors believe. Investors see attention and find another reason to believe.
Good diligence can still ask the wrong question. Investors may spend weeks testing market size, legal structure, partnerships and founder references while the core product remains difficult to inspect. A deal room can contain thousands of pages and still miss the fact that matters most.
The founder can become the gateway to the evidence. That creates a dangerous loop. Investors trust the founder enough to accept the materials, then use those materials to decide whether they should trust the founder. Independent verification has to break that loop.
The criminal case narrows the facts. In January 2022, a federal jury convicts Holmes of conspiracy to defraud investors and three counts of wire fraud tied to transfers totalling more than US$140 million. The jury acquits her on patient related conspiracy and several patient fraud counts, while other investor counts end without a unanimous verdict.10
The sentence makes the cost tangible. In November 2022, Holmes receives 135 months in federal prison. She begins serving the sentence in 2023. The SEC had put the investor principle plainly years earlier when it said investors are entitled to “complete truth and candor” from companies and executives.11
The audience knows how the story ends. That makes the continuing fascination more revealing. People aren't buying tickets because the verdict is unknown. They are watching because confidence, ambition, deception and failure are still compelling human material.
Persuasion still moves money. Canadian investors see the same mechanism in a different setting. How AI Is Changing Canadian Investors’ Decisions found that 84% of surveyed self directed investors used AI, financial creators or both. Technology changes the channel. It doesn't remove the human desire to find someone or something that makes uncertainty feel easier.
Founder conviction still has value. Early stage investors are paid to finance businesses before every answer exists. A founder who can't make others believe in an uncertain future may never recruit the team, customers or capital needed to build it.
Conviction needs independent evidence beside it. Customer calls, production data, technical review, board oversight and financial reconciliation give investors something that doesn't depend on the founder's version of events. The earlier the company, the more important it becomes to know which assumptions are still beliefs.
Holmes is in prison, Theranos is gone and investors now know how the story ended. That makes the mistakes look obvious in hindsight. They were much harder to see when the company was raising money, signing national partners, attracting famous directors and appearing on magazine covers.
The next founder who lets belief outrun the evidence will probably look nothing like Holmes. The company may be building AI, financial infrastructure, robotics, biotech or something investors have not learned how to value yet. The founder may have respected backers, impressive customers and a demonstration that makes the future feel close enough to touch.
Early founders often have to sell conviction before the product, revenue or market fully exists. That's part of building a venture, not evidence of deception. Investors are financing a future that has not happened yet, so imagination belongs in the deal.
The line gets crossed when aspiration is presented as fact, a controlled demonstration is presented as independent proof, or hoped for traction is sold as something already verified. A founder can sell why the future might happen. The investor still has to know what is already true.
STORY INTELLIGENCE
How OpenAI And Anthropic Reached Public Markets
OpenAI and Anthropic show what happens when founder vision, strategic backers, governance choices and enormous private capital converge before public market scrutiny arrives.
FOUNDER BUILD
Inside a Licensed Profession: What Ownright’s Build Teaches Fintech Founders
Ownright offers a current founder case where credibility comes from operating evidence, regulatory fit, customer execution and a system that has processed more than $2 billion of transactions.
MARKET ACTIVITY
FNZ Turnaround Tests La Caisse and Canadian Pension Capital
Repeated capital raises and management changes at FNZ show what investor conviction looks like after the cheque is written, when ownership starts turning into active governance.
NCFA INSIGHT
Canada’s Early Stage Startup Funding Funnel Narrows
A tighter Canadian funding market raises the stakes for founders trying to earn attention and for investors deciding which stories deserve scarce early stage capital.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 21, 2026
Employee benefits have undergone a quiet technological transformation. Not long ago, managing a health benefits plan meant paper forms, printed receipts, mailed claims, and significant administrative work for employers and employees. Over time, insurance providers digitized much of the process. Employees could submit claims online, access their coverage through a website, and eventually manage their benefits from a mobile device.
Today, another shift is taking place. The rise of digital financial infrastructure is making it possible for businesses to rethink not only how benefits are administered, but also what type of benefit they provide in the first place. Instead of purchasing a traditional insurance plan and paying recurring premiums to an insurance provider, some businesses are choosing a Health Spending Account, where the employer establishes a healthcare spending budget and employees are reimbursed for eligible expenses. This development is closely connected to the broader evolution of fintech.
Traditional employee benefits were built around an insurance model. An employer purchased coverage from an insurer, employees received a defined set of benefits, and claims were processed through the insurance provider. For decades, much of the administration surrounding that process was paper-based. Employees might fill out claim forms, collect receipts, submit documentation, and wait for reimbursement.
The internet gradually changed that process. Insurance providers began offering online portals where employees could submit claims electronically, view coverage details, and track reimbursements. Electronic payments replaced cheques, while digital records replaced much of the paperwork that had previously been required to administer a benefits plan.
The underlying insurance product remained largely the same, but the infrastructure surrounding it became digital. This was an important first step in the digitization of employee benefits, but it also raised a bigger question: if technology can digitize the administration of benefits, can it also change the underlying model?
Fintech has repeatedly demonstrated that digitizing an existing process is only the beginning. Payments are a good example. Businesses moved from cash and cheques to credit cards, online banking, electronic funds transfers, and automated payments. Accounting moved from desktop software and paper records to cloud-based platforms, while lending increasingly moved online, with applications, underwriting, and funding taking place digitally.
These developments created something more important than convenience: new financial infrastructure. Once the infrastructure exists, businesses can build entirely new products and services on top of it.
See:
The same thing is happening with employee benefits. Modern benefits platforms can connect employers, employees, financial institutions, and payment systems through software. Claims can be submitted digitally, reviewed electronically, and reimbursed through electronic funds transfer. Once these pieces of infrastructure exist, businesses have more options than simply purchasing a traditional insurance product.
This is where Health Spending Accounts become particularly interesting from a fintech perspective. A traditional health insurance plan transfers a defined set of healthcare risks to an insurance provider. The employer pays premiums in exchange for coverage according to the terms of the insurance policy.
An HSA takes a different approach. The employer establishes a defined healthcare spending allocation for employees, and employees submit eligible expenses for reimbursement, subject to the rules of the plan. Rather than purchasing an insurance product that provides a predetermined package of coverage, technology can provide the infrastructure needed to administer a defined healthcare budget.
This distinction opens up an entirely different model for employee benefits. The business can establish the amount it wants to make available, while employees have greater flexibility in how they use that benefit within the eligible expense rules.
The concept of giving employees a healthcare spending allowance is not new. What has changed is the infrastructure required to administer it efficiently.
Imagine an employer with 20 employees trying to manage an HSA using paper forms and cheques. Every claim would require documentation. Someone would need to review the expense, calculate the reimbursement, record the transaction, update the employee's available balance, and issue payment. The administrative burden could quickly outweigh the benefit of the flexibility.
Digital infrastructure changes that equation. An employee can submit a claim online, upload supporting documentation, and have the claim reviewed through a centralized platform. The employee's available balance can be updated electronically, while approved reimbursements can be sent directly to their bank account. What once required multiple manual steps can now be handled through a single digital workflow.
The evolution of electronic payments has been particularly important in making this model practical. Electronic funds transfer (EFT), pre-authorized debits (PADs), and other digital payment infrastructure allow money to move between businesses and individuals without paper cheques or manual bank transfers.
For an HSA platform, this infrastructure can operate on both sides of the transaction. When an employee submits an eligible claim, reimbursement can be sent electronically to their bank account. On the employer side, funds can be automatically withdrawn when claims are approved, allowing the business to fund reimbursements without manually paying an invoice for every transaction.
The result is a much more automated financial workflow: an employee submits a claim, the claim is reviewed, reimbursement is approved, funds are transferred electronically, and the employer's account is automatically debited. The development of these payment rails is an important part of what makes a digital, claims-based benefits model feasible at scale.
Digital HSA platforms also introduce a different way for businesses to think about benefit costs. With a traditional insurance plan, employers generally pay recurring premiums for coverage, regardless of how much employees ultimately use the plan. An HSA can instead operate on a claims-based model, where the employer establishes a budget but funds are used as eligible claims are submitted.
This can provide small businesses with greater visibility and control over healthcare spending. Rather than paying a fixed premium for a predefined package of coverage, a business can establish how much it is prepared to allocate toward employee healthcare and allow employees to use that allocation for eligible expenses.
This reflects a broader fintech trend toward usage-based financial products. Businesses increasingly expect technology to provide more transparency into where money is going and to reduce the friction involved in moving and managing funds.
The digital transformation of benefits is also changing the employee experience. Traditional insurance plans are designed around predefined coverage. An employee may have coverage for certain services but little or no use for others.
An HSA can approach the problem differently. Instead of deciding exactly which healthcare services employees should use, the employer establishes a budget and employees decide how to use that budget among eligible expenses. One employee might use their allocation primarily for dental expenses, while another might have significant vision, physiotherapy, or prescription medication expenses.
This creates a more personalized benefit without requiring the employer to manually manage every reimbursement. The software handles the administrative infrastructure while the employee has greater choice over how to use the benefit.
This shift reflects a broader pattern across financial technology. Fintech does not always eliminate traditional financial institutions, but it can change where value is created and which parts of a financial transaction require an intermediary.
Digital payment platforms have reduced the need for businesses to rely on traditional payment processes. Online lending platforms have created alternatives to traditional lending channels. Digital investment platforms have reduced some of the friction involved in accessing financial markets.
Similarly, digital benefits infrastructure gives businesses an alternative to relying exclusively on traditional insurance-based employee benefits. The opportunity is not simply to make insurance administration faster. It is to allow businesses to choose a fundamentally different way of delivering healthcare benefits.
This is an important distinction. The innovation is not necessarily that an insurance product has become easier to use online. It is that the availability of digital claims administration and payment infrastructure makes it possible for a business to consider a different financial model altogether.
This evolution is particularly relevant to small businesses. Large companies have traditionally had access to dedicated benefits teams, negotiated insurance plans, and significant administrative resources. A five-person business typically does not have those resources.
Digital platforms can make sophisticated financial and benefits infrastructure accessible to businesses that previously would not have had the resources or administrative capacity to manage it themselves. A small business can establish a defined benefit budget, provide employees with access to a digital claims platform, and use electronic payments without building the infrastructure internally.
That can change the competitive landscape. A small business may not be able to compete with a large corporation on salary alone, but it can potentially offer a flexible digital health benefit that employees can use according to their individual needs. Technology effectively lowers the administrative barrier to offering that benefit.
The evolution of employee benefits follows a familiar fintech pattern. First, the paper process was digitized. Then the user experience moved online. Now the underlying financial model itself is being reconsidered.
Health Spending Accounts are one example of what becomes possible when digital claims administration, cloud software, automated payments, and electronic banking infrastructure come together. For businesses considering this approach, understanding how Health Spending Accounts work is an important step in evaluating whether a digital, claims-based benefit model makes sense for their workforce.
The important development is not simply that employees can submit a claim from their phone instead of filling out a form. It is that technology has made it possible to rethink the relationship between employers, employees, insurers, and healthcare spending altogether.
As fintech continues to develop, more financial products may follow the same path: from paper, to digital, to fundamentally different. Employee benefits may be one of the clearest examples of that transition already underway.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 21, 2025

Image: Freepik/DC Studio
Canada’s home-care system is approaching a pivotal moment. According to federal projections, the country will need 39,000 additional personal support workers (PSWs) by 2043 to keep up with demand. As the population ages and more Canadians express a preference to age in place, this gap will only grow especially in rural and remote areas, where the care shortage is most severe.Provincial PSW Shortage Heat‑Map: Scheduling Tech for Rural & Remote Gaps
In Budget 2024, the federal government acknowledged this growing concern, flagging urgent incentives for rural recruitment, training, and deployment. But without better workforce management, even new funding can fall short. To bridge this divide, agencies must turn to smart scheduling and care management tools that optimize existing staff, reduce missed visits, and improve continuity of care no matter how remote the setting.
While urban centres like Toronto and Vancouver face their own home-care challenges, rural communities across provinces are confronting a different kind of crisis: chronic staffing shortages, long travel distances, and high burnout rates among the few remaining PSWs.
Provincial heat-maps reveal some of the hardest-hit areas:
| Province | High-Demand Regions | Rural Challenges |
| Ontario | Thunder Bay, Timmins, Kenora | Vast geography, staff shortages, long travel |
| Nova Scotia | Cape Breton, rural South Shore | Aging population, low PSW retention |
| Alberta | Northern Alberta, Peace River | Harsh weather, sparse housing, recruitment |
| Manitoba | Interlake and Northern regions | Limited access to training, high turnover |
| Newfoundland | Labrador and outport towns | Transport access, isolation, overwork |
In these zones, agencies often can't fill shifts, and residents go without consistent care, leading to emergency visits or premature long-term care admissions.
The federal Budget 2024 introduced welcome support: incentives to recruit PSWs to under-served regions, expand training pipelines, and bolster home-care programs. However, infrastructure without intelligent deployment tools risks underperformance.
Many providers still rely on manual spreadsheets or outdated systems that:
This results in wasted time, unbalanced workloads, and frustrated care teams—especially in areas where every PSW hour counts.
ShiftCare Canada offers a dedicated care management and scheduling platform that helps Canadian agencies meet growing demand—without overextending limited staff.
With ShiftCare, providers can:
By making it easier to assign the right carer to the right client at the right time, ShiftCare helps agencies maximize their existing workforce while reducing burnout and missed visits.
Whether you're operating in rural Nova Scotia or northern Alberta, smart scheduling is no longer optional—it’s mission-critical.
Here’s how modern care management software stacks up against traditional systems in rural care environments:
| Feature | Manual/Legacy Systems | ShiftCare Canada |
| Geographic Scheduling | ❌ Not supported | ✅ Optimized for travel time |
| PSW Availability Tracking | ❌ Often outdated | ✅ Real-time mobile updates |
| Multi-Region Scheduling | ❌ Cumbersome | ✅ Streamlined with filters and templates |
| Alerting for Cancellations | ❌ Manual follow-up | ✅ Instant push notifications |
| Compliance & Documentation Logs | ❌ Risk of error | ✅ Built-in audit trails and reports |
By using purpose-built care management scheduling tools like ShiftCare, providers can stretch their workforce further, without stretching them too thin.
The PSW shortage isn’t going away. But how we respond to it—through policy, planning, and technology adoption—will define the future of community-based care in Canada.
With platforms like ShiftCare Canada, home-care agencies can better navigate the challenges of rural service delivery, empower their staff, and ensure that no matter where a client lives, care shows up on time.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 22, 2025
Image: Freepik/rawpixel.com
In recent years, the demand for quality in-home health care has surged across Canada. As more families choose to support aging loved ones or individuals with chronic conditions at home, care providers are turning to home care software to manage services more efficiently, ensure compliance, and enhance client outcomes.
In this article, we’ll explore how technology, especially caregiver-focused platforms is transforming the delivery of home-based healthcare across the country.
Canada’s aging population, combined with the shift toward patient-centered care, is fueling a major transformation in the healthcare landscape. In-home care services are not only more cost-effective than institutional care, but they also promote comfort, independence, and better health outcomes.
To meet growing demand while maintaining high standards of care, home care agencies are adopting digital tools that streamline workflows, simplify compliance, and improve caregiver communication.
Home care software is a digital solution designed to support the administrative and clinical needs of in-home health providers. These platforms allow providers to:
Platforms like Shiftcare Home Care Software are built specifically for Canadian providers, with localized features and compliance support.
At the heart of every successful home care service is a reliable workforce. But managing schedules, shift changes, and availability manually can be chaotic.
Caregiver scheduling software, a core feature of advanced home care platforms solves this challenge by:
This not only improves staff satisfaction and reduces burnout but also ensures continuity of care for clients.
ShiftCare’s Home Care Software is tailored for Canadian in-home care providers, offering:
ShiftCare supports agencies of all sizes whether you're a solo practitioner or managing a large team of carers.
The future of in-home health services in Canada is digital and home care software is at the heart of this transformation. From automating caregiver schedules to improving transparency and compliance, these tools are empowering providers to deliver higher-quality, more efficient care.
If your organisation is ready to streamline operations and focus more on what matters most, delivering compassionate care, then it's time to explore how ShiftCare can help.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Financing | April 18, 2025

Image: Freepik
On April 16, 2025, Toronto-based digital insurance provider PolicyMe confirmed that they raised $30 million CAD through a mix of equity and debt financing between 2023 and 2025, bringing a total of $51 million CAD funding to date. The new funding round was led by Blue Cross Life Insurance Company of Canada and Securian Canada, and included support from existing investors RGAX, HCS Capital, Westdale Properties, and others.
Andrew Ostro, CEO & Co-Founder of PolicyMe:
“We’ve seen tremendous success over the past three years. At PolicyMe, we’re not just growing—we’re revolutionizing the insurance journey and setting a new standard for a customer-centric experience. By balancing digital speed with human support, we give customers the choice between a fully online process or advisor guidance, making coverage truly seamless.”
In just the past few years since closing an $18 million Series A round in 2022, PolicyMe has sold more than $10 billion in life insurance coverage, has grown its annual premium sales by more than 5.5x, and team to 100 employees.
The insurtech provides a end-to-end digital platform for policy quoting, underwriting, and issuance all in one place, enabling partners to launch insurance products in as little as 3 to 6 months with a B2B2C distribution model.
The funding will help PolicyMe to expand its product suite and technology, as they grow beyond term life insurance to add new digital health and dental insurance products, especially for self-employed and gig economy workers (more than 7.3 million Canadians, many without access to health or protection plans). PolicyMe aims to close this gap with affordable and accessible insurance, and also plans to invest in artificial intelligence to improve the efficiency and personalization of its platform.
Tim Mawhinney, President & CEO of Blue Cross Life:
“At Blue Cross Life, our purpose is to improve the well-being and financial security of Canadians through innovative insurance solutions. By leveraging PolicyMe’s end-to-end digital platform, we’ve simplified what can be a complex process into something Canadians can complete in just minutes.”
Insurtech's are finally winning over traditional insurance companies who are often said to be the most conservative sector in financial services. With $30M in new funding, AI-driven tools, and broader distribution, Canadians can finally look forward, flexible, affordable and inclusive financial protection standards and digital insurance products that work for all sectors in real life.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto | Release | Dec 4, 2024

Image: Bitcoin for Corporations (website)
LQwD Technologies Corp., a leader in Bitcoin infrastructure and payments, has joined Bitcoins for Corporations (view press release) spearheaded by MicroStrategy in partnership with Bitcoin Magazine with the aim of accelerating corporate adoption of bitcoin. It's a hub for learning, collaboration and leadership and now Canadian fintech, LQwD, is at the forefront of the movement.
As an Executive Member, LQwD gains access to exclusive resources, networking opportunities, and the collective knowledge of other innovative businesses. LQwD is no stranger to driving Bitcoin adoption. The company announced just last week that they have facilitated over 1 million transactions across its Lightning Network channels (transferring approximately 857 Bitcoin) with over half of these transactions occurring between Jan 1 to Oct 31, 2024, showcasing LQwD's rapid growth.
For companies looking to stay ahead in the evolving and fast paced world of finance, this initiative is chance to connect and learn from top crypto experts.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016