




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Crypto | Aug 28, 2025
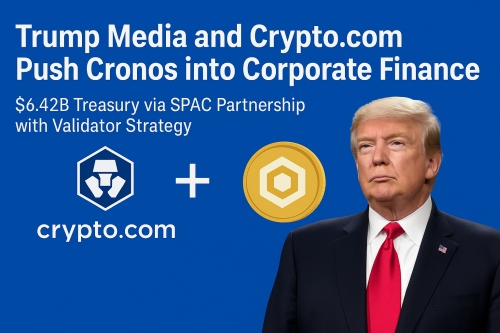
On Aug 26, 2025, the Trump Media & Technology Group, Crypto.com and Yorkville Acquisition Corp (SPAC). announced the launch of Trump Media Group CRO Strategy Inc., a new treasury firm designed to acquire, hold and actively manage large reserves of the Cronos token (CRO).
Devin Nunes, CEO of Trump Media, said:
“We continue to be bullish on cryptocurrency, and we are excited to be partnering with a leading global cryptocurrency platform and namesake of its industry in Crypto.com and one of the most sophisticated investor groups in Yorkville for this strategic initiative.”
The company will go public on Nasdaq under the ticker MCGA. The venture combines 6.3 billion CRO tokens valued at $1 billion (approx 19% of supply)+ $200 million in cash + $220 million in warrants + $5 billion equity line of credit from a Yorkville affiliate YA II PN. In total,$6.42 billion in committed resources.
Trump Media will also buy $105 million worth of cronos for its balance sheet, and Crypto.com has agreed to invest $50 million into Trump Media stock.
All told, the deal will be the first and largest publicly traded CRO treasury company and what is being described as the largest deal ever when compared to the total size of the token’s market. The business combination is being reinforced by a mandatory 1 year lock-up and 3 year release schedule on founding shares. See Form 8-K filing.
Kris Marszalek, CEO of Crypto.com, said:
“The sheer size and structure of this project will encompass more than the entire current market capitalization of CRO … this, combined with share lock-ups by each party and the treasury’s validator strategy, make it a unique and compelling offering compared to all other digital asset treasuries.”
Markets reacted immediately. Cronos spiked nearly 30% in the hours after the news (currently trading at $0.3205 on CoinGecko), while Trump Media’s stock rose 5% to $18.11. Yorkville shares fell 2.4% on the day of the announcement. This is another massive deal for crypto and boost for corporate crypto treasury strategies.
One of the most distinctive aspects of the venture is its validator strategy. Trump Media Group CRO Strategy will establish and operate a validator node on the Cronos network, delegating CRO under management to that node. This allows the company to directly participate in the security and governance of the blockchain while generating native staking rewards that will be reinvested to grow CRO holdings and offset operational expenses.
AP reported that “the Trump family is expanding its crypto empire,” adding to a series of projects that include a proposed bitcoin ETF and a $2 billion bitcoin reserve. With the White House progressing friendly crypto policies, this venture shows how closely aligned political influence and corporate strategy can be, which raises conflict of interest and transparency questions, as Trump’s family business benefits directly from a favourable regulatory climate.
The United States is moving fast with token-backed treasury vehicles and SPAC-financed listings, while Canada’s regulatory approach has been slower and more cautious. In Canada, a deal structured as a SPAC merger with a crypto corporate treasury at its core would likely not pass regulatory muster today.
That's a competitive gap. If American firms can put tokens on their balance sheets, raise capital through SPAC mergers, and connect those tokens to consumer platforms, they can innovate at a scale in a way that Canadian firms cannot match.
The question for Canada is whether to stay on the sidelines or to create the right framework for safe experimentation. That could mean regulatory sandboxes for token-based treasuries, pilot programs to test new structures, or clearer rules that give firms confidence to innovate. Without these kinds of steps, Canada risks falling further behind (skilled jobs, innovation and global capital flows) as U.S. firms set the pace in crypto finance.
The Trump Media and Crypto.com deal is an experiment to see if a token like cronos can play the same role in corporate reserves that bitcoin has for MicroStrategy. Investors jumped in quickly, but the approach still comes with the risks of big price swings and political baggage.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Digital Assets | Aug 27, 2025

Image: Freepik
Digital lives now include high value property and high emotion content. Crypto's digital assets and tokens sit next to family photos in the cloud and personal emails, but the rules for accessing them after someone's death (or incapacity) vary widely between platforms and jurisdictions.
In Canada, Bitcoin ownership was about 10% in 2023 per the Bank of Canada’s Canadian Bitcoin ownership in 2023, while the CSA 2024 Investor Index shows that 33% of investors under 35 years old hold crypto assets. Growing exposure combined with the Canada Revenue Agency’s disposition at death requirement, makes digital estate planning a growing mainstream need instead of a niche topic that could get buried (no pun intended).
Four provinces and territories in Canada have passed laws that give executors and trustees specific rights to access digital assets.
KPMG notes that these four are the only Canadian jurisdictions with dedicated statutes so far with Alberta adding digital accounts to executor duties through other legislation. Their overview of Canadian gaps notes that most provinces still lack clear rules, a challenge also underlined in the ALRI’s analysis of digital estate law.
The Canada Revenue Agency states that, “a person who died is considered to have disposed of all the property they own right before death.” That disposition also applies to crypto which is considered a capital property, with gains included on the final return. Executors and advisors need procedures that capture wallet inventories, cost base evidence, and transaction records. See CRA’s guidance on capital gains at death and its crypto asset tax page.
Big platforms provide inheritance tools that users must enable to access them. Apple’s Legacy Contact and Digital Legacy let a named person request access using an access key plus a death certificate, while Google’s Inactive Account Manager lets users direct data sharing or deletion after a chosen period of inactivity. For custody and to exchange accounts, some platforms offer support such as Coinbase deceased account handling and Binance inheritance appeal show families how to proceed.
Practical client checklist: Confirm a complete inventory of digital property and accounts, enable Apple Legacy Contact or Google Inactive Account Manager where applicable, include digital assets and directions in the will or memorandum, and securely record wallet locations and recovery material.
Fintechs and advisors should help clients list all their digital accounts, turn on inheritance tools offered by platforms, and record their wishes in estate documents. Advisors can use checklists that follow provincial laws and make sure keys and login details are stored securely. Putting these steps in place builds trust with clients and prevents problems when someone dies or becomes unable to manage their accounts.
Globally, the tax treatment of digital assets after death remains inconsistent. The UK, US, and Canada all vary in their approach, which can complicate planning for cross-border families. An in-depth analysis of inheritance tax for digital assets across jurisdictions highlights these differences.
For estates with US connections as of 2021, a total of 47 states have enacted laws based on the Uniform Law Commission model, see Revised Uniform Fiduciary Access to Digital Assets Act (RUFADAA). If users don't enable official legacy features or provide clear authority, custodians could refuse access based on terms of service, forcing families to obtain court orders from foreign jurisdictions.
Digital estate planning has moved from fringe cases to everyday expectations. The legal tools exist, platform features are available, and client demand is growing. NCFA members should operationalize digital inheritance today to create and protect real value for families while improving compliance and client experience.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Aug 27, 2025
Image: Freepik AI
For generations, investors have imagined a system that could analyze company filings, market news, and stock prices without bias, synthesize all the information, and generate transparent recommendations. Until now, this dream has remained out of reach. New research by BlackRock, the world's largest asset manager, finds that multi agent artificial intelligence may finally bring this vision closer to reality.
A collection of specialized large language model agents called AlphaAgents who collaborate and debate with each other have proven to outperform benchmarks in certain back tested cases and to provide explainable decision making trails that mirror investment committee discussions.
The system uses three unique agents with focused expertise to deliver a type of collective intelligence into portfolio construction.
Instead of outputting isolated judgments, the agents debate until they reach consensus which produces a stronger investment view aligned with specific risk profiles.
The BlackRock team tested AlphaAgents on 15 technology stocks between February and May 2024. In practical terms, the back test showed that multi agent reasoning can deliver superior returns in balanced mandates and greater stability in conservative ones.
Four portfolios were created. One for each single agent, plus a multi agent consensus portfolio. These were compared against an equally weighted benchmark with the results showing measurable gains and improvements.
With a neutral risk setting, the multi agent portfolio outperformed single agent portfolios and the benchmark on cumulative returns and rolling Sharpe ratios. A case example showed one stock gaining 13.56% in January 2024, far ahead of the 3.85% increase in the S&P 500.
Interestingly, using the risk averse setting, all agent portfolios underperformed the benchmark during a technology rally, but the multi agent portfolio still produced lower volatility and smaller drawdowns, demonstrating its value for downside protection.
The difference between a 13.56% stock return and a 3.85% market return in the same month illustrates why investors have long dreamed of such systems. AlphaAgents not only captured the upside but also flagged risks such as insider selling and negative operating margins.
For managers and advisors, this means decision support that is both measurable and transparent.
AlphaAgent debate logs are like committee notes, creating an audit trail that supports compliance and strengthens client conversations.
For regulators, the full record of data inputs and reasoning provides an unprecedented level of model oversight.
While there are back testing limitations of evaluating a mere four month window across 15 tech stocks, there's real evidence now that multi agent AI systems can produce superior ROI and risk management in risk neutral strategies. If integrated into live portfolios, these systems could in fact significantly alter equity investing.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 27, 2025
Image: Unsplash/PiggyBank
Putting a child through higher education is an expensive affair. The average annual tuition fee is over $7,000, with some fields like dentistry exceeding $24,000 per year. That’s not including books and living expenses like transportation, accommodation, food, and healthcare, so saving money early is key.
A registered education savings plan (RESP) gives you two powerful benefits. Firstly, you can access government grants. Secondly, you can take advantage of tax-sheltered growth. Here are practical strategies to help you use your RESP wisely and get the most out of every dollar you put in.
Through the Canada Education Savings Grant (CESG), the government can match your contributions by up to 20%. As an example, let’s say you put $2,500 into your RESP one year. The government will add $500. That’s the maximum amount per year per child. If you contribute less, your deposit can still be matched up to 20%. For example, if you contributed $1,000 in a given year, the government could add $200.
The earlier you start saving, the more earning potential your money has, thanks to compound interest. Even small monthly contributions can add up over time. For instance, if you can afford just $50 a month starting when your child is born, you’ll contribute $10,800 by their 18th birthday. With grants and investment growth, the RESP could reach over $20,000 by that time, based on a 2.4% annual compound return.
RESPs have lifetime limits on how much you can contribute ($50,000 per child). Go over that, and the extra amount is taxed at 1%. There’s also a cap on how much grant money you can receive: $500 per year and $7,200 total per child.
Let’s say you contribute a lump sum of $50,000; you’d only receive a CESG contribution of $500 for the first year, but the money would have the maximum time to grow. On the other hand, if you spread out the same contribution over 15 years, you could collect the full $7,200 per child.
Which approach works better depends on your investment returns. With higher growth rates, the lump sum is often more beneficial. With lower returns, the grant can be more valuable.
If you missed contributions in the past, you can collect two years’ worth of CESG in a single year by contributing $5,000. However, you can only catch up one year at a time. If you missed five years, it will take another five years of doubling contributions to collect all the grant money.
The good news is the CESG isn’t the only support available. Depending on your income or where you live, you may qualify for the Additional Canada Education Savings Grant (ACESG), Canada Learning Bond (CLB), or provincial programs. The CLB is designed for lower-income families. You don’t even need to contribute; in the first year, the government adds $500 to the RESP automatically. For the subsequent years that the child is eligible, it adds $100, up to a total of $2,000. In British Columbia and Quebec, programs include the B.C. Training and Education Savings Grant and Québec Education Savings Incentive.
Life is busy, especially with kids. It’s easy to forget about RESP contribution deadlines. The CESG calculations are based on a calendar year, so if you forget to deposit before December 31, you’ll miss that year’s grant. The easiest solution is to set up automatic contributions. Most RESP providers let you set up pre-authorized payments from your bank account.
An RESP is one of the smartest ways you can save for your child’s education, but like any tool, it works best when you use it right. Contribute enough to get the full CESG, start early, watch your limits, catch up if you fall behind, claim all the grants you’re eligible for, and automate where possible.
Applying these strategies will help you get the best value for your money and give your child the strongest start when the time comes for college or university.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 27, 2025
Image: Freepik AI
Canada is preparing for the launch of “Consumer-Driven Banking” in early 2026. This promises to be a system that will give people more control over how their financial data is shared. The main goal is to replace current risky practices, including screen scraping, with safe, consent-based data exchange. The government has made it its aim to focus on trust, clearer guidelines and regulations, to provide a system where security comes first, while still encouraging innovative services.
For more than 30 years, Interac has been the foundation of Canada’s payment system. The payment gateway is well-known for debit payments, ABMs, and the popular e-Transfer service. In 2024, Canadians sent more than one billion e-Transfers, transferring more than $132 billion.
The reach of Interac extends further than banks and credit unions. Its services are also used in online services. For instance, with online casino platforms, players rely on the same fast and trusted payments they use with their bank. The payment option allows players to access the same bonuses, gaming library, and promotions whether they use an e-wallet, cryptocurrencies, or traditional banking methods. With Interac e-transfer casinos, players can expect a fast, convenient, and highly secure way to fund their accounts with strong protections against fraud and theft.
Additionally, Interac is widely accepted for online purchases in Canada because it supports secure direct payments through Interac Online or Interac e-Transfer, which many online merchants and platforms integrate. This widespread trust and familiarity with Interac in everyday payments reflects the confidence Canadians place in its security and convenience. This acceptance and reputation for safe transactions make Interac an ideal foundation for supporting the secure, consent-based data sharing envisioned by Canada’s open banking framework
Interac already connects banks, credit unions, payment processors, and more than 1.4 million point-of-sale terminals across the country. It also has significant experience with APIs, tokenization, and authentication, which are exactly the kinds of tools that open banking requires.
Equally important is Interac’s reputation for security. With three decades of experience, Interac has well-established governance frameworks, security protocols, and operational standards. These can easily be adapted and extended to open banking APIs to accelerate compliance and risk management processes.
Standardized APIs are central to consumer-driven banking. Interac has already been running pilot projects with dozens of third-party providers that want to connect directly to financial data. The network includes shared services that are vital for open banking, such as identity verification, consent management, and secure data transfer.
It makes sense to use infrastructure that already exists. This could speed things up considerably. Instead of starting from scratch, Canada can build on a network that already processes millions of transactions every day. Interac’s reliability, low downtime, and widespread acceptance mean both banks and fintechs are more likely to support a model that is proven and trusted.
Interac’s experience helps reduce the time needed for open banking to become a reality. With ready-made standards and existing relationships across the financial sector, deployment can move faster than in countries that had to build new systems entirely. This is significant, given that the federal government has set early 2026 as the target date.
Interac also works closely with regulators. It advises on governance, security, and consumer protection, and it has teamed up with fintech incubators to test new applications in controlled environments. The focus has been on creating clear, transparent consent processes for consumers, ensuring people understand and control how their data is used.
In 2025, important steps were taken to prepare for rollout. Despite mixed reactions and backlash, Parliament passed legislation requiring accredited entities to use secure APIs, annual consent renewal for data sharing, and oversight by the Financial Consumer Agency of Canada. Major banks, including RBC and TD, continued expanding their API systems and entered new partnerships with fintechs to test services ahead of the launch.
Interac, for its part, strengthened its focus on fraud prevention. The appointment of David Bruyea as Group Head of Financial Crimes signalled an investment in protecting the system at a time when trust will be vital. With consumers still learning what consumer-driven banking means for them, Interac is positioning itself as the trusted partner that can balance innovation with security. Its long-standing role in Canadian finance, paired with ongoing developments in 2025, places it at the centre of the country’s move toward open banking in 2026.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI | Aug 26, 2025
Image: Freepik
On Aug 25 2025, Perplexity announced the launch of Comet Plus, a $5 per month subscription service that commits to paying 80% of revenue to publishers while Perplexity retains 20% for compute and platform costs. The company has allocated a $42.5 million pool to start the program.
Aravind Srinivas, Perplexity CEO hits the nail on the head:
“AI is helping to create a better internet, but publishers still need to get paid.”
The launch comes as Perplexity faces mounting legal and reputational pressure. Media companies including News Corp, Forbes, and Condé Nast have accused Perplexity of unauthorized use of their journalism. By offering direct revenue, the company is positioning itself as a collaborator rather than an adversary.
The launch also represents an evolution from Perplexity’s earlier Publisher Program announced in 2024. That program partnered with outlets like Time, Der Spiegel, and Fortune, sharing ad revenue and offering free developer tools, however payout percentages were lower and less transparent. Comet Plus is aiming to scale with openness.
Perplexity defines three categories of traffic that qualify for payouts:
1. Human traffic means direct visits to publisher program content.
2. Indexed traffic means AI citations or synthesized use of publisher content in answers.
3. Agent traffic means tasks completed by the Comet Assistant using publisher material.
Comet Plus subscriptions cost $5 per month, with Pro and Max tiers including access automatically. In September 2024 Perplexity processed 350 million user queries, showing the scale of demand.
For publishers, the model offers a new and potentially recurring revenue stream tied to the actual use of their work (different than relying on traffic referral triggers). For fintech innovators, Comet Plus demonstrates how programmable revenue sharing tied to verifiable usage can enable micropayments and real-time attribution systems. For policymakers, Comet Plus is a test case for AI compensation models that could reduce litigation and support fairer AI-publisher frameworks.
There are questions about scalability though. The $42.5 million pool is significant but could quickly be depleted as content consumption is growing quickly. Subscription adoption will need to keep pace for the model to deliver meaningful returns.
Another issue is equity. Larger media brands might capture the majority of rewards, while smaller publishers see little benefit unless Perplexity ensures diverse citation and equitable weighting. Transparency in reporting will be key to monitoring the balance and maintain trust with stakeholders.
Perplexity frames the program as part of building a better internet and ensuring creators are compensated in the AI age. If successful, it could set a precedent for AI companies globally.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 26, 2025

Image: Unsplash/PiggyBank
Two of Canada’s largest banks, RBC and BMO, are currently exploring the possibility of selling their joint payments processing venture, Moneris. If the deal follows through, it could potentially be valued at around $2 billion, which would be a record-breaking transaction in Canadian history.
At the moment, no final decision has been made yet because it’s still early days and discussions are still being held. However, the potential sale has already sparked considerable interest within the industry, given the size and importance of Moneris in Canada. The banks are said to be working with top financial advisors, including PJT Partners, RBC Capital Markets, and BMO Capital Markets, to evaluate their options.
Moneris currently generates about $700 million in annual revenue and serves about 325,000 merchant locations across the country. This basically means the company processes roughly one out of every three business transactions in Canada, which is proof of just how central it is to everyday commerce. If sold, Moneris would present a rare opportunity for investors to acquire a pretty decent share of Canada’s payments market.
Retail isn’t the only sector that relies on efficient payment systems, because industries like online gaming have also highlighted the demand for fast, reliable processing. According to gambling expert Matt Bastock, part of the reason fast cashout sites have become so popular among players is the growing demand for better payment systems and instant payouts. Like online casinos and many other sectors of the economy, more and more businesses are starting to rely on fast, reliable transactions to meet customer expectations and stay competitive.
Moneris was established in 2000 as a 50/50 joint venture between the Royal Bank of Canada (RBC) and the Bank of Montreal (BMO), at a time when card payments were the go-to for merchants. In the last two decades, the company has grown into one of Canada’s largest payment processors and a trusted name for businesses of all sizes.
With a commanding market share of about 33%, Moneris is more than just a routine asset; it’s also the backbone of payments processed in and around the whole country. Today, Moneris’ offerings cover mobile payments, e-commerce platforms, and integrated point-of-sale systems, making it a one-stop shop for most businesses.
The company has also been strategic in expanding its services through partnerships and acquisitions. In 2021, Moneris acquired Quebec-based UEAT, which is a platform that provides online ordering solutions for restaurants, as a way to cement its presence in the hospitality sector. More recently, in 2025, the company went into a partnership with Cardstream to strengthen its capabilities in e-commerce.
Should RBC and BMO move forward with the sale, it would mark a turning point in Canadian fintech history. The immediate impact on businesses and consumers might not be as harsh as most people expect it to be, as payment processing services will likely continue uninterrupted. However, under new ownership, Moneris could pursue more aggressive strategies, introduce new technologies, or even go beyond Canadian borders in the hopes of finding better opportunities.
This potential sale reflects the ongoing transformation of Canada’s financial services industry, where traditional banks are adapting to an era that is defined by fintech solutions. In fact, the Canadian fintech sector is growing three times faster than traditional finance. For stakeholders across the board (consumers, investors, and competitors), the coming months will be worth watching closely. The outcome will provide valuable insights into how things are going to change and how institutions like RBC and BMO intend to position themselves in the future.
Although payment processing operations are profitable and generate reliable cash flow, they also require ongoing investment in technology, which tends to be costly. For RBC and BMO, exiting their joint venture may allow them to refocus on their core banking operations, while leaving the demands of payment technology to specialized industry players.
On the other side of the equation, potential buyers (private equity investors or established payment companies) may find new ways to scale the business even further. Comparable moves have already been seen in and outside of Canada. For instance, TD Bank recently partnered with U.S.-based Fiserv for its merchant payments operations, opting to work with a dedicated payments provider instead of maintaining the business internally. Cases like these are good examples of how banks are rethinking their role in the ecosystem, often favouring partnerships or outright sales.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016