




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 18, 2026 | NCFA Fintech Market Activity | Payments And Market Infrastructure, SME Finance And Business Banking
On June 16, 2026, London based fintech SumUp launched in Canada, expanding into its 38th market and bringing another global merchant platform into a competitive Canadian small business payments sector.
Founded in 2012, SumUp says it serves more than 4 million businesses globally. What began as a mobile card acceptance provider has expanded into a broader merchant platform that includes payments, invoicing, point of sale software, online selling tools, business accounts, loyalty capabilities, and other services designed to help small businesses manage day to day operations.
Canada represents a significant SME opportunity. According to Innovation, Science and Economic Development Canada, the country had approximately 1.10 million employer businesses as of December 2024, including roughly 1.08 million small businesses. SumUp's launch targets that market with SumUp Go for in person card acceptance and Payment Links for remote payment collection.
Merchant payments have become one of the most valuable distribution channels in financial services.
Every transaction generates information about sales activity, customer demand, cash flow, seasonality, business growth, and operating performance. Companies that are closest to payment activity gain visibility into how a business actually operates. That information can support additional products and services ranging from invoicing and software to banking, lending, cash flow management, loyalty programs, and embedded finance.
As a result, competition is no longer limited to transaction processing fees. The larger opportunity is the business relationship itself.
Canada has already seen evidence of this shift. TD's merchant infrastructure partnership with Fiserv highlighted how financial institutions are rethinking merchant services strategies. Rather than treating payment acceptance as a standalone product, providers increasingly view merchant relationships as an entry point into broader financial and operational services.
SumUp enters Canada with meaningful scale. The company reported processing more than 1 billion transactions annually and previously raised €590 million at an €8 billion valuation. The company has also expanded by aquisitions including Goodtill, Tiller, and Fivestars as it broadened its merchant software and commerce capabilities.
In Canada, SumUp's initial offer includes transaction based pricing without monthly subscription fees. That positions the company against a market that includes banks, merchant acquirers, point of sale providers, and fintech competitors serving Canadian SMEs.
The competitive question is becoming increasingly clear. Businesses need payment acceptance. They also need software, reporting, reconciliation, invoicing, customer engagement, and access to capital. Providers that can combine those capabilities into a simple operating experience may be better positioned to deepen merchant relationships over time.
As payment providers expand into software, banking, lending, and business operations, will merchant payments become the primary gateway to the SME financial relationship?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Event contracts are evolving from niche prediction markets into a regulated market category. The strongest openings may not be operating the markets themselves, but building the integrity, settlement, intelligence, distribution and risk management systems required for the category to scale.
Prediction market and event contract estimates vary because some sources measure revenue, others measure trading volume, decentralized markets, regulated event contracts or broader forecasting activity. The range is wide, but the category appears large enough to support venture scale investigation.
Recent evidence points to a larger infrastructure thesis. Event contracts need systems for market integrity, settlement, probability intelligence, distribution access and enterprise risk use cases. The strongest opportunity may be the trusted operating layer that helps many venues, brokers and data users participate without each rebuilding the same controls.
CFTC event contract decisions, broker access, Canadian distribution, stablecoin settlement activity, sportsbook challenges, enterprise pilots and evidence that buyers will pay for specialized infrastructure.
Evidence now supports five venture paths. These are product directions inside the parent opportunity, not automatic child Opportunity Briefs.
Surveillance, disclosure and outcome disputes
Event contracts are beginning to face the same trust problems that traditional exchanges faced as participation increased. Disclosure concerns, promotion practices, insider information risks, sensitive event pricing and outcome disputes are appearing before common standards have formed.
The opportunity is to help operators manage trust. Potential buyers include exchanges, brokers, operators and compliance teams. The strongest products may focus on surveillance, audit trails, disclosure monitoring, conflict detection and dispute management.
Large exchange surveillance providers extend existing products into event contracts before specialist vendors establish a foothold.
Is the first buyer the operator, broker or compliance function? Is the pain severe enough to create budget now?
Funding, payout and stablecoin workflows
Settlement is becoming a core operating requirement. Stablecoin activity, payout workflows and always available market participation increase the need for reliable funding, custody, reconciliation and settlement rails.
This path may support transaction based revenue if event market activity grows. The challenge is competition from payment providers, stablecoin issuers, custodians and existing financial infrastructure firms.
Existing payment providers absorb most of the value before specialized event market tools gain adoption.
Can the product reduce settlement cost, risk or complexity enough to win budget from operators or brokers?
Forecast signals for investors and operators
Prediction markets can produce forward looking probability signals that traditional datasets often miss. Private market valuation odds, policy forecasts, economic expectations and event risk pricing are early examples.
This path is broader than a data feed. The opportunity is to package probabilities into intelligence products that help investors, enterprises, researchers and operators make decisions. Customers still need proof that the signals improve decisions enough to justify recurring spend.
Forecast signals fail to outperform existing indicators or cannot be packaged into trusted workflows.
Who pays for the signal, and can accuracy, timeliness or decision value be demonstrated over time?
Brokerage, wealth and retail access
Canadian retail distribution, wallet integrations, sports partnerships and operator relaunch activity show that event contracts are moving through channels that already have users, compliance obligations and product discovery workflows.
The opportunity is the access layer around event contracts: brokerage integrations, suitability controls, education, product limits, risk warnings, onboarding, reporting and venue connectivity.
Distribution remains locked inside a small number of large brokers, exchanges or wallet platforms that build the access layer themselves.
Can brokers or wealth platforms justify a specialized event contract access layer rather than relying on venue supplied tools?
Promotion, campaign and business exposure
Event contracts are beginning to appear in practical business settings, including promotion risk management and event exposure. This suggests a possible enterprise use case beyond retail speculation and market forecasting.
The opportunity is infrastructure that helps brands, agencies and enterprises model, cap, transfer or monitor event driven exposure. This remains earlier than the other paths, but it could become a repeatable category if more non financial buyers adopt event contracts for operational risk.
Enterprise use remains a novelty or occasional hedge rather than a repeatable workflow with budget.
Which repeatable enterprise event risks are measurable, hedgeable and large enough to support a dedicated product?
Filter by signal type to review source records, early market signals and thought leadership supporting this opportunity. Evidence is sorted newest to oldest.
Share your perspective, research, case study or video response. You can also express interest in future discussions, collaboration opportunities and innovation activities related to this topic.
Learn how NCFA identifies, validates and tracks innovation opportunities →NCFA Opportunity Intelligence tracks emerging venture opportunities using evidence, market developments and validation signals. Opportunity briefs are updated as new information, evidence and stakeholder perspectives become available. This content is provided for information purposes only and does not constitute legal, investment, financial, tax or professional advice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 17, 2026

Online casino gaming has become one of the most popular forms of entertainment in Canada. Canadian players have access to thousands of casino games, ranging from classic slot machines and blackjack tables to live dealer experiences that closely replicate the atmosphere of a land-based casino. With so many options available, choosing the best online casino games in Canada can be challenging.
This guide explains everything Canadian players need to know about online casino games, including the most popular game categories, payout percentages, house edges, winning potential, gameplay mechanics, and tips for selecting the right games.
The best online casino games in Canada combine strong payout potential, entertaining gameplay, fair odds, and accessibility across desktop and mobile devices. Canadian players consistently favour the following game categories:
Among all casino games available online, blackjack generally offers the lowest house edge when played with optimal strategy, while slots remain the most popular choice because of their simplicity and massive jackpot opportunities.
Online casino games allow Canadian players to enjoy casino entertainment from virtually anywhere. Modern casino platforms offer thousands of games, fast-loading mobile applications, secure payment methods, and live dealer technology.
Several factors contribute to their popularity:
The growth of regulated online gambling markets, particularly in Ontario, has further increased player confidence in online casino gaming.
Online slots remain the most-played casino games in Canada. Industry sources estimate that slots account for the majority of wagers placed on Canadian online casinos due to their simplicity, variety, and jackpot potential.
Online slots require no prior experience or strategy. Players simply select a bet amount and spin the reels.
Benefits include:
Canadian players frequently enjoy games such as:
Many of these titles offer RTP percentages between 94% and 97%, while some exceed 98%.
Return to Player (RTP) represents the theoretical percentage of wagers returned to players over the long term.
For example:
Higher RTP percentages generally indicate better long-term value.
Blackjack is widely considered the best online casino game in Canada for players seeking favourable odds.
Unlike slots, blackjack involves strategic decision-making that can significantly reduce the house edge.
Blackjack provides:
Experienced players who use basic blackjack strategy can achieve some of the best odds available in any online casino game.
Canadian online casinos commonly offer:
Blackjack strategy focuses on making mathematically optimal decisions based on the dealer's visible card.
Key principles include:
Players who learn these fundamentals can significantly improve their long-term results.
Roulette remains one of the most recognizable casino games in Canada.
The game revolves around predicting where a ball will land on a spinning wheel.
Canadian casinos typically offer:
French Roulette generally provides the best odds because of special rules that reduce the house edge.
Typical house edges include:
For players focused on maximizing value, French Roulette is often the preferred option.
Players can wager on:
This flexibility appeals to both beginners and experienced players.
Baccarat is one of the simplest casino games available online.
The objective is to predict which hand will win:
Baccarat attracts players because:
The Banker bet typically carries a house edge around 1.06%, making it one of the most favourable wagers in online casinos.
The Banker bet consistently offers the strongest mathematical advantage.
Most experts recommend avoiding the Tie bet because of its significantly higher house edge.
Live dealer casino games have experienced significant growth among Canadian players.
These games use real dealers who operate tables through live video streams.
Live dealer games offer:
Popular live games include:
Providers such as Evolution Gaming have become especially popular among Canadian players.
Modern live casinos also offer entertainment-focused game shows such as:
These games combine casino mechanics with television-style presentations.
Video poker combines slot machine mechanics with poker strategy.
Players receive cards and choose which cards to hold before drawing replacements.
Video poker offers:
Some versions of Jacks or Better can achieve RTP figures above 99% when played optimally.
Canadian casinos commonly feature:
Specialty games have become increasingly popular at online casinos.
These games often provide unique gameplay compared to traditional casino titles.
Examples include:
Many younger players enjoy these games because of their fast-paced action and straightforward mechanics.
Players looking for the highest potential returns should focus on games with strong RTP percentages.
| Game | Approximate RTP |
| Video Poker | Up to 99.9% |
| Blackjack | Up to 99.5% |
| Baccarat (Banker Bet) | 98.9% |
| French Roulette | 98.65% |
| High-RTP Slots | 96%–98% |
Higher RTP does not guarantee profits, but it generally improves long-term value.
The best game depends on personal preferences and goals.
Recommended games:
These games require minimal learning.
Recommended games:
These games reward skill and decision-making.
Recommended games:
These titles offer the largest potential payouts.
Recommended games:
Live dealer tables provide the closest experience to a physical casino.
Responsible gambling should always be a priority.
Best practices include:
Canadian players should only play on reputable, licensed casino platforms that provide responsible gambling tools and support resources.
Blackjack is often considered the best online casino game in Canada because it offers one of the lowest house edges when played with proper strategy.
Video poker and blackjack generally provide the highest RTP percentages available at online casinos.
Online slots are the most popular online casino games in Canada because they offer simple gameplay, large jackpots, and thousands of themes.
Baccarat and blackjack are often considered among the safest options because they feature relatively low house edges.
Live dealer games are worth playing for players who enjoy real-time interaction and a more authentic casino experience.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 16, 2026 | NCFA Story Intelligence | Fraud, Cybersecurity And Trust
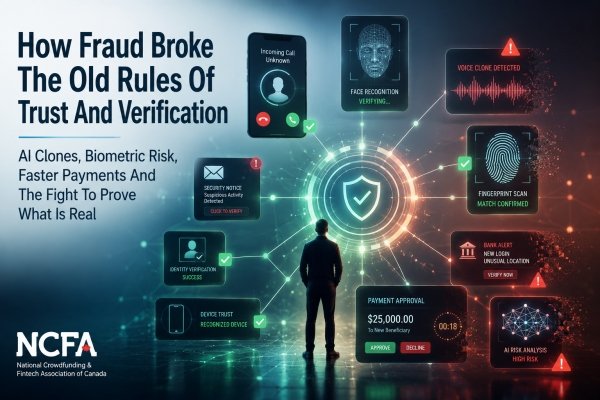
The phone rings. Many people no longer answer.
Not because they’re too busy. Because they’re not sure who is calling, what’s real, or whether the message is safe to trust. That small behaviour change tells a bigger story about finance, fraud, identity, and technology.
For years, financial trust relied on familiar signals: a voice, a face, a password, a bank name, a phone number, a regulator, a delay before money moved. AI clones, biometric breaches, deepfakes, cyberattacks, weak AML controls, and faster payments are now breaking those signals at the same time.
Financial trust used to have more time. Branch visits, paper signatures, settlement delays, call centre checks, account holds, and human review gave institutions more room to spot problems before money moved too far. The system was slower, but that slowness created time to verify.
Consumers learned to trust familiar signals. A bank logo felt official. A caller who knew account details sounded credible. A voice sounded personal. A password felt private. Those signals were never perfect, but they worked well enough when fraud was slower, less automated, and easier to recognize.
Online finance moved trust away from the branch. Banking, investing, lending, crypto, payments, and onboarding shifted into screens and apps. That created better access and faster service, but it also made customers depend on passwords, text codes, device checks, email links, and remote identity tools.
Fraudsters followed the customer online. Phishing, fake websites, account takeover, crypto wallet scams, approval phishing, QR abuse, and spoofed support channels made digital convenience feel less certain. Operation Avalanche showed how coordinated fraud response is becoming part of the market.
Voice used to feel personal. Then AI cloning made it copyable. Cloned voices bypassed Voice ID tests at Santander and Halifax, exposing weakness in systems that treated a voice as a reliable authentication signal.1
The scam no longer has to sound like a scam. A cloned voice can sound calm, familiar, urgent, or official. That changes the risk for banks, call centres, families, executives, seniors, and anyone asked to approve a transfer or share information after hearing a voice they think they know.
Biometrics raise the stakes because they cannot be replaced easily. A major India breach exposed fingerprints, facial scans, and sensitive records tied to police officers and applicants.2 A password can be reset. A fingerprint can’t.
Fintech products increasingly depend on biometric convenience. Face ID, Touch ID, palm payment, device based onboarding, and selfie checks reduce friction. They can also concentrate risk if biometric templates, face scans, or identity documents are stored poorly or exposed through vendors.
Deepfakes make fraud feel human. Deepfake scams have used AI generated voices, fake identities, digital banks, and crypto rails to trick victims and move funds quickly.3
AI makes deception cheaper to personalize. Fraudsters can imitate an executive, a family member, a bank employee, a support agent, or an investment promoter. The scam can be written better, timed better, targeted better, and delivered through channels that look more legitimate than old phishing emails.
Faster money gives fraud less time to fail. Real Time Rail, instant payments, request to pay, and faster settlement can improve cash flow and customer experience. They also shrink the window for fraud teams to stop a bad payment before it settles.
Fraud controls become part of the payment product. Real Time Rail analysis connects instant payments with centralized fraud capability, payment finality, and trust.4 Faster money only works if participants believe the system can manage faster mistakes.
Institutions are not only defenders. They are targets. CIRO confirmed approximately 750,000 Canadian investors were affected by a cybersecurity incident after a 9,000 hour forensic review.5 When regulated bodies are breached, trust damage extends beyond one account.
Third party systems can carry hidden risk. SaaS vendors can create concentration risk across fintech and financial services. A startup may inherit risk through a vendor, API, data processor, onboarding tool, cloud provider, or fraud vendor it does not fully control.
AML failure shows how controls can become business risk. TD’s more than $3 billion US AML penalty and leadership fallout showed how weak controls can limit strategy, growth, reputation, and trust.6
Canada is trying to organize the response. Canada’s first National Anti Fraud Strategy and Financial Crimes Agency push point toward more public and private collaboration on cyber risk, data sharing, and proceeds of crime recovery.7
Fraud didn’t break trust all at once. It weakened the signals people and institutions used to verify reality. The phone call. The voice. The face. The fingerprint. The login. The bank name. The official looking message. The settlement delay. The regulated institution. Each one still matters, but none can carry trust on its own anymore.
That’s the hard part for financial innovation. Canada is moving toward faster payments, consumer driven banking, digital identity discussions, AI adoption, crypto market controls, and more automated financial services. None of those systems succeed simply because they’re fast or digital. They succeed because people trust what they’re seeing, hearing, approving, and authorizing.
What trust signal do you question now that you wouldn’t have questioned five years ago?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 16, 2025 | NCFA Resource | Risk Compliance And Regtech, Artificial Intelligence And Data, Regulation And Policy
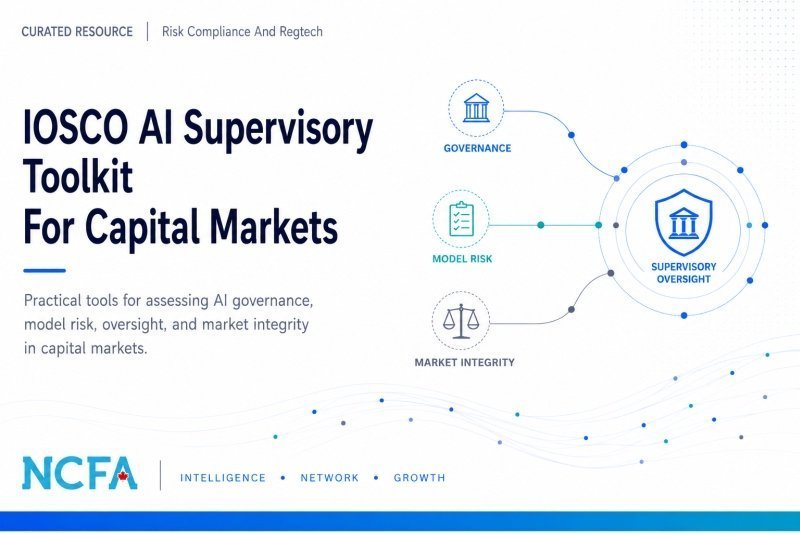
On May 25, 2026, the International Organization of Securities Commissions (IOSCO) published its Supervisory Toolkit for Artificial Intelligence Use in Capital Markets. The report provides practical tools for regulators supervising AI systems used by market participants, exchanges, investment firms, and capital market infrastructure providers.
The toolkit arrives as AI goes beyond experimentation and into production environments across trading, surveillance, compliance, onboarding, fraud detection, customer service, research, risk management, and operational workflows. IOSCO focuses on the supervisory questions regulators need to ask rather than promoting a specific technology approach.
Stakeholder Input Opportunity: IOSCO is also seeking feedback related to the toolkit and AI supervision in capital markets. Interested regulators, market participants, technology providers, academics, and industry stakeholders can review the report and submit responses to IOSCO by this short survey by June 26, 2026.
The report organizes supervision around seven areas. These include governance and accountability, model development and testing, data quality and management, monitoring and controls, outsourcing and third party providers, market conduct risks, and operational resilience.
Rather than prescribing rules, IOSCO provides supervisory questions, review approaches, and practical considerations that regulators can use when assessing AI systems operating in capital markets. The toolkit is designed to support risk based supervision while remaining flexible as technologies evolve.
The report also recognizes that AI risks often emerge from combinations of factors rather than a single model failure. Poor quality data, weak governance, limited oversight, inadequate testing, vendor dependencies, and insufficient monitoring can interact in ways that create market, operational, or investor protection concerns.
Many financial institutions are already deploying AI in regulated environments. The challenge is no longer whether AI will be used. The challenge is whether firms can demonstrate appropriate governance, explainability, oversight, and accountability once those systems affect clients, markets, or investment decisions.
For fintech operators, the toolkit offers a useful preview of the questions regulators may increasingly ask during examinations, supervisory reviews, audits, and risk assessments. Firms that build governance and controls into deployment processes early may face fewer compliance and operational challenges as expectations mature.
This resource is useful for securities regulators, exchanges, investment dealers, fintech founders, regtech providers, compliance teams, AI governance specialists, risk managers, and market infrastructure operators.
It is especially relevant for organizations using AI in trading, surveillance, onboarding, fraud detection, compliance monitoring, client communications, investment research, portfolio management, or operational decision making.
The strength of the toolkit is its practical orientation. It extends beyond high level AI principles and focuses on supervision, controls, accountability, and operational implementation. The framework can be applied across a wide range of AI use cases and organizational structures.
It also provides a common language that regulators and industry participants can use when discussing AI oversight. That consistency becomes increasingly important as firms operate across multiple jurisdictions with different regulatory approaches.
The toolkit does not create binding rules or regulatory obligations. IOSCO's role is to provide guidance and supervisory tools that member jurisdictions can adapt to their own legal and regulatory frameworks.
IOSCO Supervisory Toolkit For AI Use In Capital Markets (primary resource)
IOSCO Media Release (official announcement)
AI Agents Enter Governed Financial Workflows (AI governance and oversight)
Customer Due Diligence Controls For Fintechs (controls, monitoring, and accountability)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 16, 2026 | NCFA Insight | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization
On June 14, 2026, the Financial Times reported that China is preparing mBridge for commercial rollout (subscription needed), with central banks from mainland China, Hong Kong, Thailand, the United Arab Emirates and Saudi Arabia involved.
The participating central banks haven't yet published a matching launch announcement. The Bank for International Settlements said mBridge reached minimum viable product stage in 2024 and that more central banks and commercial banks could join the legal framework and perform real transactions on the platform.
mBridge is important to watch because it tests a different model for cross border settlement. Instead of routing payments through long correspondent banking chains, participating central banks and commercial banks use a shared multi CBDC platform for payment and foreign exchange settlement. That makes the project a practical test of whether wholesale CBDC rails can reduce cost, settlement delay and liquidity friction in trade corridors where participating jurisdictions already have strong commercial ties.
mBridge began in 2021 with the BIS Innovation Hub, the Hong Kong Monetary Authority, the Bank of Thailand, the Central Bank of the UAE and the Digital Currency Institute of the People’s Bank of China. Saudi Arabia joined as a full participant in 2024. BIS also identified more than 26 observing members, including the European Central Bank, IMF, World Bank, Reserve Bank of India, Bank of Korea, Bank of France and the Federal Reserve Bank of New York’s New York Innovation Center.
The project has already gone beyond lab testing. The HKMA said the 2022 pilot involved 20 banks across four jurisdictions and completed more than 160 payment and foreign exchange transactions totaling over HK$171 million. It was among the first multi CBDC projects to settle real value cross border transactions on behalf of corporates.
BIS later said the MVP platform allowed participating jurisdictions to undertake real value transactions, subject to their own readiness. The project also created a governance and legal framework, including a rulebook, to match its decentralized operating model. That's why the current story isn't whether CBDCs can be piloted. It's whether participating jurisdictions can turn mBridge into operating payment infrastructure?
mBridge should be read alongside Project Agorá tests real money bank settlement rails. Agorá is testing tokenized commercial bank deposits and wholesale central bank money with major Western central banks and more than 40 commercial banks. mBridge is testing a direct multi CBDC settlement network among participating jurisdictions.
The difference is important for Canadian banks, exporters, fintechs and policymakers. Agorá is closer to upgrading existing correspondent banking through tokenized deposits and shared workflows. mBridge is closer to building a parallel wholesale settlement arrangement for selected currency corridors. Both are trying to reduce payment friction, but they reflect different governance choices, legal assumptions and geopolitical incentives.
The commercial test is liquidity, compliance and repeat usage. If real trade flows begin routing through mBridge, banks and payment firms will have to assess whether lower cost and faster settlement justify the legal, operational and supervisory work needed to connect to a new network.
The sensitive issue is whether a new wholesale settlement network can preserve anti money laundering controls, sanctions compliance, legal certainty and supervisory visibility across jurisdictions with different policy goals. Debate around mBridge's geopolitical implications has followed the project for years. See: mBridge could affect sanctions enforcement and payment routing.
In 2024, BIS General Manager Agustín Carstens said the BIS handoff of mBridge to participating central banks was not politically driven and was not a sign of project failure. He also said mBridge was not mature enough to operate commercially at that time and rejected the claim that it was designed as a BRICS sanctions workaround.
That tension remains central. If mBridge enters commercial use, participating institutions will need to prove that faster settlement isn't at the expense of enforceable controls, transaction monitoring, governance accountability or cross border legal clarity.
If wholesale CBDC networks start carrying real trade flows, how should Canada position payment modernization so Canadian banks, exporters and fintechs can participate in the infrastructure race instead of only reacting to it?
CBDCTracker, these Central Banks have Launched a CBDC or Pilot Initiative
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 15, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Payments And Market Infrastructure, SME Finance And Business Banking
On June 15, 2026, Montreal based Nuvei announced a definitive agreement to acquire Payoneer for approximately $2.75 billion ($7.40 per Payoneer share in cash). The companies expect the transaction to close in mid 2027, after Payoneer shareholder approval, regulatory approvals, and other closing conditions.
If completed, the combined company expects about $3 billion in annual revenue. It also expects to process more than $500 billion in annual payment volume and serve over 2.4 million customers across more than 190 countries and territories.
While the price tag will certainly get some attention. The stronger story is what Nuvei is buying. Payoneer brings cross border payouts, multi currency accounts, marketplace reach, banking connectivity, regulatory approvals, and access to businesses that operate globally every day.
Payment processing is only one part of global commerce. Businesses also need to collect funds, hold balances, convert currencies, pay suppliers, settle marketplace earnings, and manage funds across borders.
Payoneer has spent two decades building that infrastructure. Its customers operate across Amazon, Walmart, Airbnb, Fiverr, Etsy, Upwork, Shopify, WooCommerce, eBay, ByteDance, and other global platforms. These businesses don't just need checkout tools. They need financial rails that help them operate in multiple currencies and jurisdictions.
Payoneer also brings regulated market access. The announcement highlights online payment licensing in mainland China and authorization in principle as a cross border payment aggregator in India under the Reserve Bank of India framework. That kind of access is tough to replicate. It takes capital, local knowledge, compliance depth, and time.
Nuvei connects businesses to local acquiring, alternative payment methods, risk tools, fraud management, and merchant services. Payoneer is closer to the operating side of international commerce. It helps businesses receive earnings, manage currencies, send payouts, and use global banking networks.
Together, the companies can cover more of the financial workflow. A merchant may start with payment acceptance. Then it may need supplier payments, foreign exchange, treasury tools, card issuance, marketplace settlements, or embedded financial services.
A provider that manages more of the money flow earns a stronger role in daily operations, otherwise a payment processor alone may just lose a merchant at renewal.
The expected combined scale gives Nuvei a larger role in global commerce infrastructure. It also puts the company in a different competitive conversation.
Nuvei is no longer competing only as a payments processor. It's trying to become a broader platform for acceptance, payouts, settlement, treasury, FX, and embedded finance. Merchants and platforms increasingly want fewer providers handling more of their financial operations. They want simpler workflows, cleaner reconciliation, faster settlement, and stronger compliance across markets.
That matters because every additional financial provider adds complexity. Merchants must reconcile transactions across multiple systems, manage separate compliance requirements, monitor third party risk, and track funds moving through different settlement networks. As Canadian payment rules place more weight on payment service provider operational risk and incident response rules, businesses have greater incentive to reduce handoffs and work with providers that can handle more of the process inside one platform.
For Canada's fintech ecosystem, the deal shows where value often forms behind the scenes. Some of the most important fintech companies are not consumer brands. They are infrastructure firms embedded behind marketplaces, exporters, software platforms, and global merchants. The acquisition also fits the larger opportunity in NCFA's Financial Innovation Map, where payments, data, digital assets, capital markets, and financial infrastructure are becoming more connected.
As payments, payouts, treasury services, FX, and embedded finance come together, will businesses keep using separate financial providers or choose platforms that manage the full flow of money across borders?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016