




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Apr 28, 2026 | NCFA Fintech Insight | Capital Markets And Funding
Image: Freepik/DC Studio
On April 27, 2026, Prime Minister Mark Carney launched the Canada Strong Fund, calling it Canada’s first national sovereign wealth fund. Ottawa will seed the fund with $25B over three years and invest alongside private capital in Canadian projects tied to energy, critical minerals, infrastructure, advanced manufacturing, transport, data, telecommunications, and other national priorities.
The Canada Strong Fund is an attempt to change how Canada builds. The constraint isn't only capital. It's the shortage of investable assets that meet institutional standards on returns, timing, governance, approvals, and scale. Canada has capital but it has fewer projects that investors can underwrite with confidence compared to global peers.
The Rt. Hon. Mark Carney, Prime Minister of Canada:
"Through the Canada Strong Fund, all Canadians will have the opportunity to share directly in these benefits.”
Canada’s capital problem shows up as fewer productive assets and weaker productivity. Workers operate with fewer productive assets than peers in the United States and across the OECD. C.D. Howe Institute research shows that investment capital per worker is falling. In 2025, investment per worker in Canada is expected to be about 70% of the OECD average and about 55% of US levels.
The gap is larger in the areas that matter most for productivity. In 2024, Canada invested only about 41% as much as the US in machinery and equipment per worker, and about 32% as much as the US in intellectual property. Software investment per worker is about half US levels, while US research and development spending is roughly four times higher.
The gap is real and shows up in the economy. Canadian companies operate with fewer machines on the floor, less software across teams, and fewer systems they can scale. The Canada Strong Fund aims to close that gap by turning national priorities into projects investors can back with real capital.
The Canada Strong Fund will be seeded by the government with $25B over three years, but the outcome still depends on discipline.
Who's going to invest? Pension funds, infrastructure funds, banks, insurers, private credit, sovereign funds, and strategic corporates all have the capacity to deploy capital. Finance Canada says Canadian pension funds hold over $3T in assets.
Projects need to make money, get approved without long delays, and run with clear rules that keep politics out of investment decisions. Finance Canada says the fund will target market rate returns, operate at arm’s length through a Crown corporation, and focus mainly on equity investments. That helps align the fund with private investors. If execution slips, that alignment can break down quickly.
Alberta offers a provincial reference point launching the Heritage Savings Trust Fund in 1976, which grew from $1.5B to $31.9B by Dec 31, 2025. Over time, it also contributed more than $45.8B to public spending. That supported public priorities, but it limited compounding. A sovereign wealth fund cannot build long term national wealth if returns are regularly redirected to annual budgets.
Ottawa has also signalled a potential retail investment product that would allow Canadians to participate directly. Retail access requires clear disclosure, defined liquidity, strong suitability controls, and consistent reporting. Public participation raises the standard for execution.
On Apr 28, the federal government released the 2026 Spring Economic Update putting the Canada Strong Fund inside a broader build agenda. Capital is only one constraint. Canada also needs workers, approvals, governance, reporting, and project discipline.
Finance Canada says Team Canada Strong aims to recruit, train, and hire 80,000 to 100,000 skilled trade workers by 2030 to 2031. That matters because housing, infrastructure, energy, and major projects need enough skilled workers to turn capital into real assets.
For fintech and alternative finance, the practical role is retail access. If Canadians can invest in national projects, the experience needs to be simple, trusted, and clear. People need to know what they are buying, how risk is explained, how many flows in and out, and what kind of reporting they can expect after they invest.
Can Ottawa help build more productive assets while maintaining commercial discipline and public trust? If it can, the fund can help close Canada’s capital formation gap and give Canadians a direct stake in national wealth creation. If it cannot, Canada risks creating another financing structure that absorbs capital without improving how the country builds.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Apr 28, 2026 | NCFA Insight | AI, Fintech And Productivity

AI Image: Jobs vs Compute
AI layoffs are becoming a capital allocation story. In April 2026, large firms across technology, retail, media, and financial services kept cutting roles while at the same time spending more on AI, automation, cloud infrastructure, and operating efficiency.
That doesn’t mean all layoffs are as a result of AI, but boards are asking a harder question now as they divert capital from labour to compute: where does the next dollar produce more output, people, platforms, or compute?
The numbers are getting harder to ignore. Big Tech AI spending could reach about $600 billion in 2026. Meta plans to cut about 10% of its workforce while guiding to $115 billion to $135 billion in capital spending driven largely by AI infrastructure. Microsoft is offering a voluntary employee buyout as it manages rising AI and cloud costs. Snap is cutting about 16% of full time staff. Nike is cutting about 1,400 jobs, with technology roles taking most of the impact.
The decision has been made in the boardroom. AI investment is competing with payroll, product teams, operations, and layers of management. Every job and role now has to show where it adds judgment, customer trust, regulatory knowledge, risk control, or revenue that automation can’t easily replace.
A fintech that can process more volume and scale without adding the same number of people has a better margin story. A fintech cost structure that needs a new team every time revenue grows will be under pressure fast.
AI usage and early labour strain is already appearing before every company announces formal cuts. Entry level roles in AI exposed fields are tightening first. That’s where the next generation of operators and compliance talent usually starts.
A recent Armstrong Economics commentary on AI costs raises a useful counterpoint: AI can reduce headcount pressure, but it doesn't remove cost. For example, the cost of compute, vendor fees, data cleanup, cybersecurity, audit trails, , human review and workflow redesign are all part of real ROI calculations. For fintechs and financial institutions, the acid test is whether the full process costs less, runs faster, and keeps risk under control.
That makes unit economics more important than AI headlines. If those metrics improve, AI is creating operating leverage. If they don't, the company may end up moving cost from payroll to infrastructure in the end.
Nike may be a clearer signal for Canada than Meta. Canada has fewer Meta sized AI infrastructure bets, but it has many established firms that added apps, data projects, digital teams, and customer platforms during the low rate years. Some of that work created real value. Some became expensive to maintain, hard to scale, or too slow to justify.
As a result, many companies are replacing older internal builds with leaner AI enabled stacks, vendor platforms, and automation tools that reduce operating cost. That’s the opening for fintech infrastructure. Companies still need modern payments, identity, credit, fraud controls, compliance tools, treasury, and customer finance.
They just don't want every capability built and staffed internally. Easier said than done but the option is goals and motivations are to buy proven tools, connect them faster, and reduce cost without adding another large costly operating layer. It’s removing friction from financial workflows. Faster onboarding. Cleaner risk checks. Less manual reconciliation. Better fraud detection. More useful cash flow data. Compliance that costs less to run.
The economics are are already visible. AI agents and return on intelligence in finance shows that 77% of financial institutions report positive ROI from AI, while nearly half plan to allocate more than half of their AI budgets to agent driven systems.
Productivity gains are now the baseline expectation, not the upside case. That changes how financial services teams are built and what gets funded.
There are limits, though. If companies eliminate too many junior roles, they risk weakening the talent pipeline. Financial services can’t automate accountability (can they?). Someone still needs to understand the customer, the regulation, and the risk.
Founders and investors should monitor operating metrics to understand where leverage is. Revenue per employee. Gross margin. Onboarding cost. Support cost. Compliance cost per customer. Fraud loss rates. A fintech that grows without adding headcount at the same pace stands out. One that talks about AI without showing better unit economics doesn’t.
Canada is earlier in this cycle, but the friction is starting to show. Statistics Canada reports that about 6% of AI adopting businesses say they've reduced employment due to AI, which suggests the adjustment is underway but not yet widespread. Firms are not always announcing large AI driven layoffs (publicly), but they are slowing hiring, tightening teams, and pushing more output through automation.
That pressure is also showing up in large Canadian incumbents, even when AI isn't named as the cause. Rogers is offering voluntary departure packages to about half of its workforce as it looks to reduce costs.
Canada also won’t follow the US pattern exactly. The country has fewer hyper-scaleup companies and less direct exposure to massive domestic AI infrastructure spending. Canadian companies are more likely to buy AI capability through partners than build it internally. That creates a different risk. The US may adjust faster. Canada may carry this margin and efficiency friction longer.
It's important because productivity remains a concern. Statistics Canada reports that business labour productivity declined in late 2025.
The labour story is not about pure job cuts but whose rebuilding their operating model and productivity structure. If large US firms trade headcount for compute, Canadian firms need to trade manual work and fragmented systems for better infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 28, 2026
Clean water is one of those things people assume is handled in the background – until the tap starts smelling like a pool, the kettle fills with scale, or a boil-water advisory hits the news. That’s usually when the search for a reliable water treatment company begins, and it becomes obvious fast that not every outfit in this space deserves access to your main supply line.
The right water treatment company is not just a vendor. It becomes part of the building’s infrastructure, shaping what everyone drinks, cooks with, showers in, and feeds to equipment worth thousands. Choosing on price alone, or after one flashy demo at the kitchen table, is how homeowners and businesses end up with oversized systems, locked-in contracts, and almost no real improvement in water quality.
Here’s how to narrow the field without needing to become a chemist.
Any serious conversation about treatment should begin with: what’s actually in the water?
Before talking gear, look for a company that:
They should be able to show hardness, iron, manganese, pH, TDS, maybe specific metals or nitrates depending on the region. Then they should calmly explain what’s aesthetic (taste, staining, soap scum) and what’s a potential health concern.
If someone walks in and pushes the same big package they sold to “everyone in the area” without even asking for a sample, that’s not expertise. That’s inventory they’re trying to move.
A water system is plumbing and, often, electrical work tied directly into your main supply. This is not side-hustle territory.
A credible company will have:
Ask directly. Legitimate firms are used to those questions and have no problem answering them. Evasive answers here are a reason to stop the conversation.
Brand names and shiny housings don’t mean much if the guts haven’t been independently tested.
Questions worth asking:
A solid company answers simply and specifically. “This whole-house filter is certified to reduce chlorine and sediment to X level. For lead, you’d need this additional stage at the kitchen tap.” That kind of clarity shows they understand both the limits and strengths of their gear.
When explanations drift into “energizing” water, altering “structure” without data, or miracle magnets, it’s time to be skeptical.
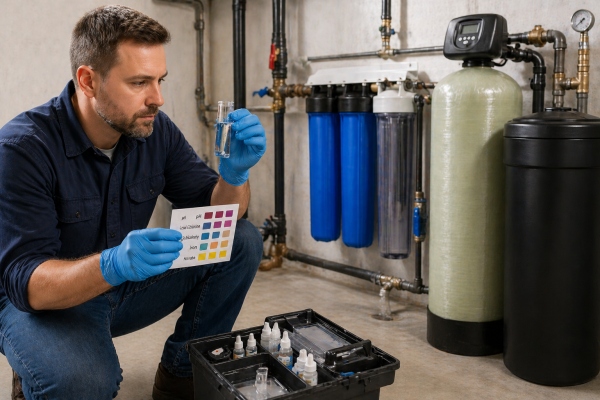
Water testing can be a tool or a weapon. The difference is tone.
Reliable providers:
Watch out for:
If the entire conversation is built on panic and urgency, it’s probably not being driven by your best interests.
A water system has two price tags: the installation, and the long-term cost of keeping it running.
A good quote will:
Ask what a typical year of ownership looks like. How many cartridges? How often does media need to be changed or tanks serviced? Can simple filters be swapped by staff, or does everything require a technician?
High-pressure “today only” discounts, financing pushed harder than the technical discussion, or vague answers about future costs are all signs to slow down.
Performance depends as much on installation as on brand. The most advanced system will underperform if someone rushes it in a corner and leaves.
A reliable company will:
On support, ask:
If everything is smooth until the contract is signed and vague after that, expect trouble later.
Online reviews can be noisy, but patterns are useful.
Look for:
Then ask for a couple of references, ideally with similar water (city vs well) and similar building type (home, restaurant, plant). A quick call to a past customer asking, “Would you hire them again?” is more valuable than any brochure.
Commercial sites have more at stake: compliance, process reliability, and brand reputation.
For a business, a water treatment provider should also:
Here, the right partner behaves almost like a utility consultant, not just an equipment installer.
A few behaviours consistently predict regret later:
When something feels off in the first meeting, it usually doesn’t improve after money changes hands.
Choosing a water treatment company is less about filters and tanks and more about trust, clarity, and long-term thinking. Get those right, and water goes back to being what it should be in a home or business: reliable, unremarkable, and safe enough that nobody has to think twice before taking a sip.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 27, 2026 | NCFA Fintech Insight | Cybersecurity And AI Risk
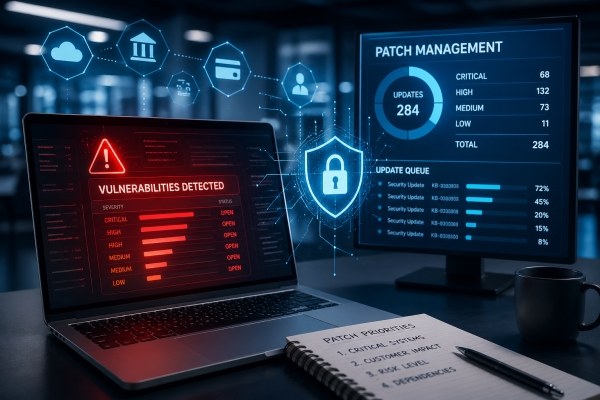
On April 21, 2026, Mozilla's Firefox team said early access to Anthropic’s Claude Mythos Preview helped identify 271 vulnerabilities in Firefox 150, after an earlier Anthropic collaboration with Opus 4.6 helped fix 22 security sensitive bugs in Firefox 148. It's a real world test Warning that AI has started to compress months of expert vulnerability research into a much shorter discovery cycle.
The deeper issue for financial services isn’t whether AI can find bugs. Mozilla’s post makes that answer fairly clear. The harder question is whether banks, fintechs, payment providers, cloud vendors, and critical infrastructure operators can test, rank, schedule, and deploy fixes fast enough once the bug volume rises?
Security teams have always fought an unfair game. That is attackers only need one weakness while defenders have to protect the full surface. Mozilla’s Bobby Holley wrote that elite security researchers find bugs that fuzzers miss by reasoning through source code, and that computers “were completely incapable of doing this a few months ago, and now they excel at it.” He also wrote that Mythos Preview was “every bit as capable” as the best security researchers Mozilla has studied.
Limited human cyber security expertise no longer limits discovery in the same way. Once AI can reason through large codebases, the volume of known vulnerabilities rises quickly. Mozilla for example jumped from 22 bugs in Firefox 148 to 271 vulnerabilities in Firefox 150. Detection capacity jumps faster than operational capacity.
For fintechs, that means security teams may see more vendor alerts, more emergency updates, more dependency risk, and more pressure to patch without breaking customer facing systems. More discovery helps defenders, but only when organizations can practically execute on the risk.
The Financial Times reported that companies with Mythos access want stronger joint defense across government and business, especially for hospitals, banks, utilities, and other critical infrastructure. It also reported that Microsoft, Fifth Third’s technology provider, has rolled out almost 150 software updates since Mythos’s release. Patching can affect numerous areas, such as customer access, payments, fraud controls, and vendor dependencies.
Financial infrastructure like core banking systems, payment gateways, and fraud engines operate on tight turnaround schedules and a bad patch or gap can interrupt service, leaving a known weakness open. And the tradeoff becomes harder when AI expands the queue of fixes beyond human capacity.
A 2026 analysis summarized on the Harvard Law School Forum on Corporate Governance found that Russell 3000 companies hit by significant cyber incidents underperformed the broader market by about 5% on average over three years. The study reviewed 176 unique cyber events from 2022 through 2024, and found that finance, banking, and health care accounted for more than half of reported incidents. That means board failures, patch delays, poor vendor oversight can damage shareholder value for years.
The old comfort of quarterly patch cycles won’t hold up well in a world where AI can surface hundreds of issues at once.
Reuters reported on April 21 that unauthorized users accessed Mythos through what Anthropic described as a third party vendor environment. Anthropic said it was investigating the report and had no evidence that the access affected Anthropic systems.
If a tool can find bugs as well as top security experts, then that tool becomes a prime target. Anyone who gets access to it could shortcut months of work and go straight to weak points. That means security is no longer just about protecting your systems. It also includes controlling who can use these AI security tools, how they’re accessed, and what they can see across your vendors and environments.
Warnings from Palo Alto Networks point to where this could go. These tools may allow attackers to link multiple weaknesses together and automate attacks. That’s why the unauthorized access issue matters even without confirmed misuse. The real risk is that the capability itself could leak.
Canadian fintechs don’t run everything themselves. They depend on cloud providers, banks, payment networks, identity services, and other vendors. That means they don’t control when fixes happen, but they still carry the risk if something goes wrong.
That puts pressure on knowing how vendors handle security. Fintech teams need to understand how quickly partners fix serious issues, how they report problems, and whether important updates get priority. Even smaller firms can push for clearer answers before relying on a vendor for critical services.
Regulators should pay attention too. AI can help find problems faster, but only if companies can act on that information in a coordinated way. If not, bigger firms with early access move ahead, while smaller ones fall behind. In Canada, where many fintechs depend on a few key providers, that gap could widen quickly.
Mozilla believes there’s a limit to how many bugs exist, and that defenders may finally be able to find them all. That could happen over time. Right now, though, things will feel messy. More bugs will show up. Fix lists will get longer. Vendors will have to decide what to fix first. Leaders will have to choose between keeping systems running and fixing issues right away. For banks and fintechs, the edge will go to those who can move faster, work closely with partners, and handle frequent updates without disrupting customers, payments, or data.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 27, 2026
The growing anticipation surrounding SpaceX reflects a broader shift in how investors evaluate high-impact private companies approaching potential public listings. Unlike traditional IPO candidates, SpaceX operates at the intersection of advanced aerospace engineering, satellite communications, and long-term space infrastructure development. This evolving landscape has significantly increased interest in SpaceX stock, positioning it as a focal point for forward-looking investment discussions. This positions it uniquely within capital markets, where valuation is not solely driven by current financial disclosures but by projected industry dominance and technological scalability. As discussions around a possible IPO intensify, investors are increasingly focused on measurable indicators that signal readiness for public market entry.
This blog explores the key signals that investors analyze when assessing IPO preparedness, offering a structured and professional perspective tailored to informed financial evaluation.
One of the most critical indicators investors monitor is the evolution of financial transparency within the organization. For a company transitioning toward public markets, the shift from selective disclosure to structured, standardized reporting is essential. In the context of SpaceX stock, this involves the gradual alignment of financial practices with public market expectations, including detailed revenue segmentation, cost structures, and forward-looking guidance. Investors closely observe whether the company begins adopting reporting frameworks similar to publicly traded peers, even before an official filing. This includes clarity on recurring revenue streams such as satellite services, as well as capital expenditure patterns linked to launch infrastructure and research initiatives. Transparency not only builds investor confidence but also reduces perceived risk associated with limited visibility.
A company demonstrating consistent, disciplined financial communication signals readiness for broader market participation, as it reflects internal maturity and preparedness for regulatory scrutiny. This transformation is often incremental, yet highly indicative of IPO intent.
Operational scalability plays a decisive role in determining whether a company can sustain the demands of public market expectations. Investors evaluating SpaceX stock focus on how effectively the company expands its core operations while maintaining efficiency and reliability. This includes launch frequency, mission success rates, and the ability to scale satellite deployment without compromising quality or timelines. Equally important is revenue diversification. A company heavily reliant on a single income stream may face valuation volatility, whereas diversified revenue sources provide stability and resilience. In SpaceX’s case, the integration of satellite internet services alongside launch operations represents a strategic effort to broaden its financial base.
Investors analyze how these segments contribute to overall revenue and whether they demonstrate sustainable growth trajectories. Scalability combined with diversification indicates that the company is not only growing but doing so in a structured and balanced manner. This reinforces confidence in its ability to perform consistently under the scrutiny of public investors.
A transition toward an IPO requires a robust governance framework that aligns with regulatory standards and investor expectations. Investors closely examine the composition of leadership teams, board independence, and decision-making transparency when assessing IPO readiness. For a company like SpaceX, strengthening governance structures signals a shift from founder-driven agility to institutional accountability. This does not diminish innovation but ensures that strategic decisions are supported by oversight mechanisms suitable for public markets. Key indicators include the appointment of independent directors, the establishment of audit and compliance committees, and the implementation of clear reporting hierarchies. These elements demonstrate that the company is preparing to operate within a regulated environment where accountability is paramount.
Strong governance reassures investors that risks are managed systematically and that leadership decisions are aligned with long-term shareholder value. This structural evolution is often subtle but serves as a powerful signal of readiness for broader market participation.
Capital efficiency is another defining factor in evaluating IPO readiness. Investors assess how effectively a company utilizes its funding to generate sustainable growth. In the case of SpaceX, this involves analyzing how capital raised through private funding rounds is deployed across research, infrastructure, and operational expansion. Efficient capital allocation indicates disciplined management and reduces concerns about excessive cash burn. Additionally, investors monitor the company’s funding strategy, particularly whether it begins transitioning from reliance on private capital to preparing for public fundraising mechanisms. This includes optimizing cost structures, improving margins, and demonstrating a clear pathway to profitability.
A company that balances innovation with financial discipline is more likely to attract long-term investors in public markets. Capital efficiency also reflects the organization’s ability to scale without compromising financial stability, a critical requirement for sustaining investor confidence post-listing. These indicators collectively shape perceptions of financial readiness and strategic alignment.
Regulatory preparedness is a fundamental requirement for any company considering a public listing. Investors analyze how well the organization aligns with compliance standards, disclosure requirements, and legal frameworks governing public markets. This includes readiness for filing documentation, adherence to international operational regulations, and the ability to manage cross-border business complexities. For SpaceX, operating across multiple jurisdictions adds an additional layer of scrutiny. Investors also evaluate how the company positions itself within the competitive landscape, particularly in terms of market dominance and strategic partnerships. A strong market position enhances IPO appeal, as it signals long-term growth potential and industry leadership.
Regulatory alignment combined with strategic positioning ensures that the company is not only compliant but also competitive in a global context. These factors collectively influence how investors perceive the timing and viability of a potential public offering, making them essential components of IPO readiness analysis.
Assessing IPO readiness requires a multidimensional approach that extends beyond surface-level financial metrics. The case of SpaceX stock illustrates how investors evaluate a combination of transparency, operational strength, governance maturity, capital discipline, and regulatory alignment before forming expectations about a potential listing.
Each of these indicators provides insight into how well the company can transition into a publicly traded environment while maintaining its growth trajectory. As interest continues to build, informed analysis becomes essential for separating speculation from measurable progress.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 27, 2026
Image: Unsplash/Sortter
Interest rates can cause drastic changes in the real estate markets, as seen in 2025. Among this market, the luxury market in the US with its waterfront mansions, and a strong neighbourhood is affected the most. Buyers are making ultra-sensitive decisions more than ever. However, it is also noted that in 2026, the luxury industry has both potential and hardships.
Luxurious homes are usually financed through big loans, construction loans, or bridge financing systems. Broader rates are a problem here. But buyers are still strict about looking for high-quality homes for privacy, amenities, and locations, and for an overall premium product that delivers higher profit. Uprising rates can change the market environment, but also create opportunities driven by higher demand.
Rates are not swinging wildly anymore. 2026 has stable, measured interest rates compared to the previous change in the rate environment. Buyers are still very conscious about budgets and purchase decisions, trying to gain a competitive advantage in the market. When they invest huge time and effort, being careful is expected.
For developers, the case is even harder because they tend to borrow at every level of the project. It affects land acquisition, permissions, material acquisition, labour cost, and design. In the matter of buyers, mortgage terms are affected by the monthly carrying costs.
Luxury constructions, which depend on loans and bridge financing, are impacted by increasing margins and rising borrowing costs. In fewer instances, buyers compromise on the back square footage, finish of the housing, or delay in groundbreaking the property. According to Lake Geneva Area Realty, Americans are leaning towards renting single-family houses instead of directly buying them to gain long-term benefits. This strategy helps them avoid the property tax, maintenance costs, and repairs.
The higher rates are a warning to owners of luxury construction who have not been owning newer properties that have delayed resale capacity. The bottom line is that when the market has a higher rate, the financial case for luxury households becomes straightforward.
Rising rates affect not only properties but also construction costs. Financing is exclusive and developers have a lag period of time to figure out labour and materials. But the financial realities have to be matched to the practical situation, however strong the design concept.
Luxury buyers have become more selective in this age, instead of rushing to make a purchase decision. Previously, properties were counted as trophies. Now, features like price, long-term benefits, and amenities have become a point of question. Second-home buyers are another layer of selective investors who want nothing but properties with financial benefits despite elevated rates.
A portion of buyers are waiting desperately for rates to fall. They are delaying commitment to big renovation projects or custom builds. Many are drawn towards homes that are already built, so they can avoid the longer duration and financial complexities. The market is currently dominated by ready-to-move-in luxury homes.
Luxury has a value now that is more precious than before: flexibility, easy ownership, and lower friction. Buyers want to get rid of the burden of repairs and maintenance and stay well-adjusted with the changing rates. Luxury is active but remains more value-conscious with time.
Developers are structuring their projects more strategically than ever. Given the current rate situation, they are opting for predictable demands and smaller, targeted developments. They are catering to a specific profile of buyers, for instance, affluent downsizers, second-home buyers, and moving professionals.
Some builders are strategizing differently. They are digging deep into phased construction, more deposit requirements, and pre-sales, so that they can mitigate their risks in bigger projects. They are strict with the timelines and monitor their calendar now and then, since extra months mean more financial pressure. Putting themselves into a renter’s shoes, buyers are looking into homes with lower maintenance and projects with energy-efficient systems.
Image: Unsplash/paws_and_prints
There are regional variations in coping with the rising interest rates as well. Some regions have strong local wealth and limited land supply, while others rely on second-home buyers. In the Midwest of the US, luxury markets are still thriving because buyers are into long-term value. In Lake Geneva, domestic demand, beautiful surroundings, and a stable reputation have kept the market steady.
On the contrary, coastal side resorts are facing shifts in demand since there are plenty of options. In these regions, a modest change in rates can change the overall environment overnight. The outcome is more imbalanced when in a luxury construction landscape. Here, markets stay resilient while others become more cautious.
Developers and buyers who keep track of the interest rates and their changing environment, and who can predict the pattern, win. Amid hardships, they manage to find homes that are not defined by their size, but its quality and location. They further invest in homes that are easy to own with a lesser burden of maintenance and taxes. Luxury is shifting its formats in this economy. Short-term trends are long gone. Buyers want beauty with convenience that stays well-preserved for ages.
The luxury market witnesses a shortage in labour, supply chains, and regulations as interest rates rise exponentially. Skilled trades are in demand to remain under budget, while supply chain shifts material pricing and delivery routines. Regulations become stricter with permissions and rigidity in review. In this case, homes with all the approval papers remain in high demand.
The change in interest rate has driven a change in the operation of the luxury construction sector. Buyers are cautious, developers are selective, and markets are more resilient. The luxury sector now values long-term appeal. Buyers and builders can only adapt to the changing environment. In 2026, winners are those who look for homes that are easy to acquire, own, and justify. Stability meets a strong lifestyle, and that is smart in a constantly changing market.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 27, 2026
What makes Image to Video AI interesting is not just that it can animate a still image. Plenty of platforms now try to do that. What makes it worth discussing is that it addresses a very human desire: we often want our images to carry more life than a single frozen moment can hold. A portrait wants a little breath. A product image wants a little movement. A memory wants a little atmosphere. The tool becomes useful when it helps that transition happen without turning the process into technical homework.
That emotional side of the workflow matters more than people admit. Most users do not come to image-to-video tools because they want to study software. They come because a static picture feels almost complete but not fully expressive. They want to add just enough motion to make the visual communicate more clearly. In that context, a platform that feels approachable becomes more valuable than one that merely sounds advanced.
This is why I rank Image2Video first among six image-to-video platforms. In my experience, the public product logic reflects a real understanding of user intent. It is built around a sequence people can immediately grasp. Begin with the image. Describe what should happen. Generate the motion. Export the result. That clarity makes the platform easier to trust.
There is a difference between having an image and having a piece of content. An image can be beautiful, but it may not always hold attention in the same way a moving visual can. The rise of image-to-video tools comes from this gap.
People sometimes talk about motion as if it exists only to create excitement. I think that view is too narrow. Motion can guide attention, emphasize mood, shape pacing, or suggest narrative. A slight camera move can make a product look more dimensional. A subtle animation can make a portrait feel more intimate. Even a simple movement can transform the emotional interpretation of a scene.
That is where platforms like Image2Video become useful. They do not just decorate a still image. At their best, they help the image say more.
One misconception about AI generation is that more dramatic output is always better. In practice, I often find the opposite. The most effective result is frequently the one that respects the original image and adds motion with restraint. That is why prompt-driven systems can be powerful. They let the user communicate a direction instead of simply accepting a random effect.
A product earns trust when its process can be described clearly. Image2Video performs well here because the public workflow is straightforward and concrete.
Based on the official public pages, the process looks like this:
| Step | User Action | Creative Purpose |
| 1 | Upload a still image | Establish the visual starting point |
| 2 | Enter instructions or a motion prompt | Define how the image should move or feel |
| 3 | Generate the video | Let the system transform the static visual into motion |
| 4 | Export the completed output | Save the result for sharing or further use |
This matters because the workflow matches the way people think. They do not think in software architecture. They think in intentions. I have an image. I want it to move like this. I want a usable result.
The fact that the product publicly supports common image types like JPG, JPEG, PNG, and WebP is more meaningful than it may appear. Small points of convenience shape whether a tool becomes part of everyday use. When a platform reduces technical interruptions, it preserves creative energy.
That is one reason Image2Video feels easier to recommend to a wide range of users, not just specialists.
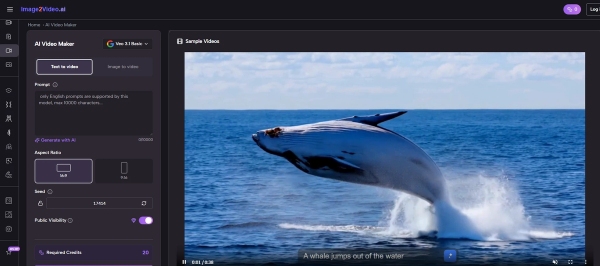
Many rankings of AI video platforms focus on power, novelty, or dramatic output. I prefer a more grounded lens: which platform best supports the moment when a user wants to give an image more life?
| Rank | Platform | Why It Matters | Where Caution Helps |
| 1 | Image2Video | Clear image-first workflow and approachable generation process | Output quality can vary with prompt clarity |
| 2 | Runway | Broad toolset and wider creative environment | More expansive than some users need |
| 3 | Kling | Frequently associated with strong motion appeal | May feel less direct for beginners |
| 4 | Pika | Fast and socially oriented visual creation | Better for speed than deep predictability in some cases |
| 5 | PixVerse | Strong energy for short-form visual content | Can feel more effect-driven than purpose-driven |
| 6 | Hailuo | Interesting option within the AI video space | Not always the most immediately readable experience |
Image2Video takes the top spot because its strength is not only generation. It is comprehension. The platform communicates its role clearly.
This first-place ranking is not a claim that Image2Video will outperform every alternative in every situation. Runway may suit users who want a larger toolkit. Kling may appeal to users chasing particular motion qualities. Pika and PixVerse may be excellent for rapid visual experimentation. Hailuo may develop into a stronger choice over time. Still, for the common task of turning one image into one moving result with minimal confusion, Image2Video currently feels the most balanced.
A review becomes more useful when it connects features to actual use cases. Image2Video makes the most sense when viewed through practical scenarios rather than abstract marketing language.
Here are some situations where the platform feels especially relevant:
These use cases share something important. They do not require a full cinematic production system. They require a workable bridge from stillness to motion.
That is why the product’s structure matters so much. If the user needs quick experimentation, a direct Photo to Video workflow is more valuable than a platform that offers endless possibilities but slows down action. In many real projects, finishing a good result matters more than imagining a perfect one.
It is easy to overpraise AI tools. That usually makes a review less useful, not more. The limitations of Image2Video deserve clear mention.
In my testing mindset, the platform works best when the user brings a reasonably clear idea. If the motion instruction is too vague, the result may feel generic. If the source image is weak, the animation may have less impact. If the creative goal is highly specific, it may take multiple attempts to get close to the intended feeling.
This is not a special failure of Image2Video. It is part of the wider nature of generative systems. But it matters to say so openly.
A user may need to test different phrasings, compare several outputs, and decide which version feels strongest. That is normal. In fact, one of the advantages of a simple platform is that iteration becomes emotionally cheaper. You are more willing to try again when the process does not feel burdensome.
The rise of image-to-video tools reflects a broader shift in digital communication. People increasingly expect visuals to do more. A still image is no longer always enough.
Audiences respond to movement, mood, and rhythm. Brands want richer presentation. Creators want more expressive assets. Ordinary users want memories that feel more vivid.
As this category grows, the platforms that matter most may be the ones that lower the barrier to creative motion. They do not have to be the loudest. They have to be understandable. They have to make experimentation feel natural rather than intimidating.
That is where I think Image2Video stands out today. It reduces the emotional resistance that often surrounds new creative tools. It tells users what to do, gives them a manageable path, and helps them move from a static image to a living visual idea. In a category full of excitement, that kind of clarity is not boring. It is valuable.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016