




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 4, 2026 | NCFA Fintech Market Activity | Regtech And Financial Crime Compliance
AI image robot analyzing financial data in office
On March 4 2026, UK based Vivox AI raised £1.3 million to scale AI agents built for AML, KYB, and KYC workflows inside regulated financial institutions.
Vivox AI ties the raise to current deployment claims across enterprise customers operating in more than 100 countries, including the UK, Europe, the United States, and Singapore. The release says complex compliance case processing time falls from about six hours to about 30 minutes, false positive screening alerts fall by up to 86%, and straight through processing reaches up to 50% for selected onboarding and due diligence workflows.
AML, KYC, and KYB work is repetitive, document heavy, and costly. Time per case, alert volume, and exception handling drive staffing levels and backlog risk. The goal is to target those exact cost drivers. Less time per case reduces analyst hours. Lower false positive rates reduce review load. Higher clean through processing reduces manual touch rates.
The product is described as separate task agents rather than one general AI layer. That design fits regulated workflows more closely because onboarding, due diligence, screening, and case handling can be controlled, tested, monitored, and audited as separate processes. In practice, compliance teams need faster file handling, cleaner audit trails, and fewer manual reviews that do not add risk insight.
Canada recently updated its Canada anti fraud policy and continues to raise expectations on prevention, detection, and reporting. That pushes more pressure through AML, KYC, and KYB operations while boosting financial crime compliance innovation.
Vivox AI is entering a category where established Canadian and Canada connected firms already cover adjacent parts of the stack. Trulioo identity verification supports global KYC and KYB onboarding. iComply compliance automation covers modular AML, KYC, KYB, and KYT workflows. Nasdaq Verafin financial crime controls serves financial institutions with AML, fraud, and investigation tools. Vivox AI’s stated position is narrower and more execution focused: task specific agents inside case work, screening, and due diligence workflows.
For operators key metrics such as time saved per case, false positive rates, exception rates, audit evidence quality, and post approval error rates will determine whether automation lowers cost or adds a second layer of review.
If compliance automation cuts a six hour case to 30 minutes and reduces false positives by up to 86%, does workflow design replace compliance team size as the main scaling lever?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 3, 2026 | NCFA Fintech Market Activity | Wealthtech And AI Operations

On March 3 2026, Canadian wealthtech based in Calgary OneVest launched its Agentic Wealth Operating System, a new platform built to automate core wealth management workflows across onboarding, account opening, fund movements, fee billing, document handling, and multi step operational tasks.
The launch is a product and workflow infrastructure improvement. OneVest’s own platform pages already position the company around advisor experience, client experience, home office tools, compliance, and workflow automation. The new operating system pushes that model further into direct task execution across the middle and back office. OneVest describes it as 'a unified intelligence layer that proactively connects advisors, operations teams, and clients'. OneVest recently closed $20M Series B to Lead Wealthtech.
OneVest is aiming at the operational layer of wealth management. Wealth firms still lose time and margin in areas such as onboarding, account setup, approvals, data re entry, billing, and document processing. These are repeatable workflows where automation can cut labour time, reduce handoff friction, and improve operating consistency.
The new launch adds an AI native execution layer on their stack which is designed to streamline execution and reduce manual steps, duplicate tasks and improve faster completion of advisor and operations work. If firms can automate account opening, fund movement workflows, billing processes, and document extraction inside the operating system, then labour cost, processing time, and error rates all become addressable.
For operators, the key test is measurable workflow impact. How much onboarding time will be saved, manual touches removed, billing accuracy, exception rates, and the number of workflows that move from staff handled to system executed.
Firms that control workflow execution inside wealth infrastructure can become harder to replace than firms that only improve the interface. If OneVest can move from software layer to operating layer, the product value and switching costs both get stronger.
As wealthtech moves from dashboards to workflow execution, does the next valuation premium go to firms that automate operations instead of firms that only modernize the front end?
Wealthtech is evolving from digital interfaces to operational automation. Client portals and advisor dashboards improved the front end. The next competition layer sits behind the screen in workflow engines, approvals, data flow, and execution control. That is where firms either scale cleanly or absorb more overhead as assets and client counts rise.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 3, 2026 | NCFA Fintech Market Activity | Payments And Market Infrastructure

On March 3 2026, Hanna Zaidi, VP Payments Strategy and COO of Wealthsimple announced on LinkedIn that Wealthsimple just became the first Canadian fintech to earn direct access to Swift, and the second non-bank fintech globally to gain direct access. The Globe and Mail reported that Wealthsimple will be offering cheaper international money transfers than larger Canadian competitors and a spring launch for the new service.
From reviewing WS's website, Wealthsimple wire fees lists CA$15 for outgoing CAD wires (US$15 for outgoing USD wires), while inbound wires will have no fee on Wealthsimple’s side. There's also a per transfer limit of up to CA$1,500,000 or US$1,500,000.
Swift membership rules explain why direct access is hard to secure. Applicants must qualify under Swift’s user categories and Swift's onboarding requires mandatory security controls and a security attestation before a new member can go live. Meaning WS earned a direct network membership milestone, not a reseller arrangement.
Swift's network scale connects 11,500+ institutions across 220+ countries and territories, handles 53 million+ FIN messages each day on average, and routes 75% of payments to destination banks within 10 minutes.
The table below highlights the price gap Wealthsimple is attacking, compared with TD fees and RBC fees for incoming/outgoing wire transfers which are more expensive. Wealthsimple enters the wire market below the published outgoing wire fees at both banks and below the published incoming wire fees in both schedules.
| Comparison | Wealthsimple | TD | RBC |
|---|---|---|---|
| Outgoing international wire | CA$15 CAD wire / US$15 USD wire | $50 | Starting at $45 |
| Incoming wire | $0 (WS's side) | $15 | Starting at $17 over $50 |
| Published transfer limit | Up to CA$1.5M / US$1.5M | Not stated in cited fee schedule | Not stated in cited fee page |
| SWIFT Access | Direct member access as a fintech | Direct bank member access | Direct bank member access |
The strategic value goes beyond a wire product though. In addition to direct Swift access, Wealthsimple has also earned direct participation in Payments Canada, Interac, and the Bank of Canada’s coming real time rail. That gives one non-bank platform direct reach across more of the domestic and global payment stack that sets pricing, speed, and settlement.
For Canada, from a competitive perspective, when a fintech now has direct entry into the same global messaging network used for bank wires and is attaching a lower listed fee to that access, consumers benefit. That puts direct pressure on wire pricing and strengthens Wealthsimple’s position in cross-border money movement services.
When a non-bank fintech gets direct Swift access and lists lower wire fees than major banks, does the competitive edge move to firms that control the rail instead of firms that only package the service?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 2, 2026 | NCFA Fintech Market Activity | Funding Access And Market Structure
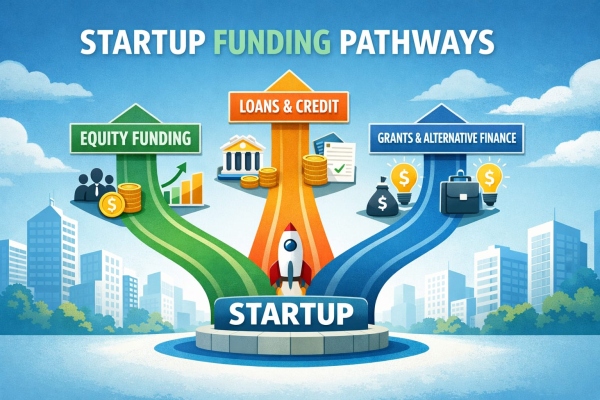
On March 2 2026, FrontFundr and Swoop launched a funding partnership that brings equity, debt, and specialized financing into one coordinated path for Canadian startups.
FrontFundr enters the partnership with more than 69,000 investors, more than $336 million in processed investments, more than 35,000 transactions, and more than 285 successful raises.
Peter-Paul Van Hoeken, Founder & CEO of FrontFundr:
“Raising capital is rarely straightforward, and founders shouldn’t have to navigate fragmented options alone. By partnering with Swoop, we’re giving startups a single, coordinated path to financing, so they can focus on building their business instead of managing complexity.”
Swoop Finance, launched in the UK in 2018, adds a broader financing reach with more than $2.5 billion in completed funding for more than 282,000 global customers. Together, that combines community based equity access with a wider range of debt and structured funding options.
Daire Burke, Head of Swoop North America
“Canadian startups need access to both capital and guidance to grow efficiently. Working together with FrontFundr allows us to combine our expertise in loans, grants, and financing solutions with FrontFundr’s equity crowdfunding platform, creating a seamless funding experience for founders.”
Founders rarely use one funding tool from start to scale. Equity can fund product development and early traction. Loans, lines of credit, grants, asset-backed financing, acquisition finance, and other structured products can support working capital, expansion, and specific transactions. A combined and simplified path can reduce friction at a time when founders still lose time moving between separate funding providers.
For Canada, this points to a more connected funding stack at a time when Canadian venture funding pressure continues to make capital access one of the hardest constraints on startup growth. The stronger platforms offer more than one product, and help founders match the right capital to the right stage with less delay and less administrative drag.
For founders and investors, access to capital is becoming a workflow issue as much as a supply issue. Platforms that combine investor reach, financing options, and execution support can become more valuable than standalone marketplaces.
As startup funding gets harder to piece together, does long term value move to platforms that control more of the capital journey, not just one part of it?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 2, 2026
Image: Unsplash/CardMapr.nl
Ontario’s regulated online gambling market is now measured in tens of billions of dollars. That scale has caught the attention of financial literacy advocates who see wagering not as entertainment alone, but as a financial behaviour. The question is simple: are the safeguards keeping pace with participation?
Online gambling in Canada is no longer a fringe activity. It sits inside the broader digital finance system you work in every day. Card networks process the payments and fintech firms build the rails while regulators try to get ahead of the game. Ontario offers the clearest picture: the province launched its regulated iGaming market in April 2022. Two years later, the numbers show just how quickly participation has grown.
In its 2023–2024 fiscal year, Ontario’s regulated online gambling market recorded $63 billion in total wagers and $2,4 billion in gaming revenue.
The first year of regulation, from April 2022 to March 2023, saw $35,5 billion in wagers. The jump from $35.5 billion to $63 billion in one year represents millions of card transactions moving through Canada’s payment infrastructure.
When activity reaches that scale, it becomes part of the larger financial system conversation. Consumer advocates are no longer talking only about odds and advertising. They are asking whether financial guardrails are designed for a market processing tens of billions in digital transactions.
The payments side of this discussion rarely makes headlines, but it is central. Visa and other networks sit behind a large share of online gambling deposits. Operating within global compliance frameworks, they classify transactions and manage settlements.
Visa’s recent expansion of stablecoin settlement across Central and Eastern Europe, the Middle East and Africa shows how fast payment rails are modernising. The initiative allows settlement in USDC and operates outside traditional banking hours. That is infrastructure innovation at scale, and a good argument can be made that this is the future of money, the future of finance. Regardless of ones feelings about crypto, one cannot ignore the fact that it is now something people are starting to use in every day transactions, and not just on-chain speculation.
This signals something as simple as it is interesting: the rails are getting faster and settlement options are widening. When payment systems modernise at that pace, consumer safeguards cannot rely on static policy language written for a different era of finance. Policy needs to catch up, and fast. Policy hardly ever moves at the pace of innovation, and maybe its time that changes.
Canada’s National Financial Literacy Strategy 2021–2026 focuses on building financial resilience and improving how people navigate digital financial services. The strategy calls for clearer information, stronger consumer protection and behavioural design that supports better decisions.
Online gambling now sits inside that digital ecosystem. It involves credit products, payment authorisations and real-time account transfers. When $63 billion in wagers flow through regulated platforms in a single province, it becomes part of everyday financial behaviour.
Advocates argue that safeguards should mirror the scale of activity. Deposit limits, clearer transaction labelling and easier access to account history are not abstract features. They are tools that support informed use of financial products.
Most Canadian players fund accounts with familiar tools. Visa remains one of the most recognised options. Behind the scenes, gambling transactions are commonly coded under Merchant Category Code 7995. Some issuers apply additional scrutiny or decline those payments based on internal risk rules.
That friction pushes players to look for clarity. Many compare online casinos that accept Visa in Canada to understand where card deposits are supported and under what conditions. The comparison is less about brand loyalty and more about payment certainty.
From a financial literacy perspective, this is where awareness becomes practical. A cardholder may not know how transaction coding affects approval rates and they may not understand how chargebacks are treated in gambling contexts. As wagering volumes rise into the tens of billions, even small gaps in understanding can scale quickly.
Canada’s open banking infrastructure continues to advance even before final policy implementation. The push is toward greater data portability and clearer consumer visibility over transactions.
Greater transparency has direct relevance here. When consumers can see where funds move and how categories are assigned, financial decision-making improves. In a market measured in billions of dollars, visibility is not cosmetic. It supports accountability across payment networks and platforms alike.
Ontario’s $63 billion wagering figure is not a social commentary. It is a financial data point. That scale places online gambling squarely inside Canada’s digital finance system.
The takeaway here is straightforward. Growth in participation requires growth in clarity. Safeguards need to be built into the rails, not layered on after problems appear. The Fintech world is technology driven, and competition in the field sets the pace. Can regulation keep up?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 2, 2026 | NCFA Fintech Market Insight | AI And Market Structure
On February 21 2026, India’s AI declaration (from it's AI Impact Summit 2026 held in New Delhi from Feb 18-19, 2026) got 91 countries and international organizations behind a voluntary and non-binding framework on AI access, trusted systems, workforce development, scientific use, energy efficiency, and economic growth. Canada is on the list. So are the United States, the United Kingdom, the European Union, China, Russia, Japan, and India.
That kind of participation is a strong policy marker that still makes it relevant for fintech because the document goes straight at the building blocks that determine who can deploy AI at scale and who gets left behind. Affordable compute, trusted tools, resilient infrastructure, workforce skills, and broader access to AI resources all sit closer to the practical operating requirements for financial institutions and fintechs than generic summit language usually does.
One of the interesting facts about the declarative coalition itself is ten of the 11 BRICS members also appear on the declaration list. That means roughly 90.9% of the Brics bloc also signed onto the same AI framework. On a second axis, six of the 10 named Board of Peace funding contributors also appear on the declaration list. That overlap does not make the declaration binding, but it does show India assembled broader support than a narrow Western technology coalition.
AI infrastructure is becoming a competitive input, not just a policy topic. The countries that line up early around access, trusted systems, and workforce capacity can make it easier for domestic firms to adopt AI tools across lending, compliance, onboarding, fraud controls, customer support, and internal operations. The countries that lag on compute access, skills, or deployment frameworks risk a wider productivity gap.
Canada signed onto a wide multilateral AI framework that includes both major Western economies and most of BRICS. That doesn't create immediate legal obligations. It does, however, strengthen the case for domestic follow through on AI infrastructure, talent, and trusted deployment if Canada wants its fintech and financial services firms to stay competitive as AI moves deeper into core operations.
If nearly the full BRICS bloc and much of the Western alliance can align on a voluntary AI framework, does the next real competitive divide come down to execution rather than diplomacy?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 2, 2026 | NCFA Fintech Market Activity | Digital Assets And Market Structure

On February 28 2026, Coincheck completed its 3iQ acquisition, taking about 99.8% beneficial ownership of the Ontario based digital asset manager and turning an announced January 3iQ agreement into a finished cross-border ownership change with direct Canadian relevance.
Coincheck Group is the holding company of Coincheck, one of Japan’s largest crypto asset exchanges. Monex Group remains the controlling shareholder of Coincheck Group and was also the seller in the 3iQ transaction. That fact makes this deal more than just a portfolio add, and moves a Canadian digital asset manager into a larger international platform that already spans exchange access, brokerage, staking, and institutional client distribution.
3iQ brings a regulated product track record that already has market credibility in Canada. 3iQ product history includes becoming Canada’s first regulated digital asset investment fund manager in 2017, launching one of the first diversified crypto funds in 2018, and bringing major exchange listed Bitcoin and Ether funds to the Toronto Stock Exchange in 2020. More recent expansion added managed accounts, Ethereum staking products, a Solana staking ETF, and a spot based XRP ETF. That mix gives Coincheck immediate reach into regulated investment wrappers that already matter to institutional allocators.
Coincheck’s institutional buildout now includes 3iQ in Canada, Aplo in France (Oct 2025), and Next Finance in staking infrastructure (Apr 2025). Digital asset firms are consolidating beyond single product competition and toward control of a wider institutional stack. Distribution, regulated wrappers, staking capability, and client relationships carry more strategic value when the market shifts from retail access to institutional scale.
For Canada, this is a reminder that proven digital asset platforms continue to attract global buyers. Leading digital assets companies may be the groups that control more of the full client path, from exchange access and staking to regulated investment products and institutional distribution.
As crypto firms consolidate across exchanges, staking, brokerage, and regulated funds, does long term value move to the groups that control more of the institutional stack?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016