




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Feb 9, 2026 | NCFA Fintech Market Activity | Platform Monetization and AI Infrastructure

On February 9 2026, OpenAI began testing ads in ChatGPT in the United States for logged in adult users on the Free and Go subscription tiers.
OpenAI says Plus, Pro, Business, Enterprise, and Education tiers will not include ads. The company also says ads don't influence ChatGPT answers and it keeps conversations private from advertisers. Advertisers only receive aggregated performance data such as views and clicks.
OpenAI says ads will appear as clearly labelled sponsored listings that are visually separated from the organic answer. It also says users can dismiss ads, share feedback, manage ad personalization, and delete ad data. If a user prefers not to see ads, OpenAI says they can upgrade to Plus or Pro plans, or opt out of ads in the Free tier in exchange for fewer daily free messages.
This test follows earlier commercial integrations connecting AI platforms with financial infrastructure. In 2025, OpenAI partnered with PayPal on ChatGPT Instant Checkout functionality, demonstrating how conversational AI and fintech rails are already intersecting in commerce contexts.
ChatGPT isn't just a place where people consult. It's a place where people compare options as they are already close to a decision. That's important because ads placed inside a timely decision moment can convert demand faster than ads placed in a scrolling feed.
For fintechs, this adds a new acquisition layer that sits upstream of search and downstream of intent. Founders who rely on organic discovery or comparison traffic should assume this channel will become part of the distribution stack if OpenAI expands beyond a limited test.
OpenAI says it selects ads by matching advertiser submissions to the topic of the conversation, past chats, and past ad interactions. That selection method will shape what winning looks like (similar to the power of Google search, and we know how that's turning out). If relevance depends on conversation context, product positioning and category language, it may matter as much as a strong bid strategy.
There is also a compliance edge that finance teams should watch. Sponsored placements inside a conversational interface can blur user expectations, even with clear labelling. OpenAI says it will not show ads near sensitive or regulated topics such as health, mental health, or politics, and it says it will avoid showing ads to users it predicts are under 18. If OpenAI later expands categories or geographies, regulators may examine how financial promotions work in a chat interface, how disclosures show up, and how users interpret sponsored content when they are asking for guidance.
The competitive response will follow quickly if engagement holds; think Google, Microsoft, Amazon, Stripe, Shopify, Fintech ad networks and more. If conversational ads convert, other AI platforms will test their own models. If users push back, competitors may try to win trust by staying ad free. Either outcome changes the market. It changes how products compete for attention and how platforms price access to users.
If people begin comparing financial products inside AI conversations instead of search, what becomes the sustainable competitive advantage, brand trust, distribution partnerships, or the ability to convert inside the chat itself?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
February 9, 2026 | NCFA Fintech Insight | Strategic Finance and Infrastructure
Image: Freepik/upklyak
On February 3 2026, Montreal International promoted the Defence Security and Resilience Bank initiative as part of its effort to position Montreal as a potential hub for a global defence finance platform focused on strategic resilience and security capital formation. Montreal International is a publicly funded economic development organization supported by federal, provincial, municipal, and private sector partners. On December 17, 2025, Toronto already pitched its bid to make Toronto the home of DSR Bank. So has Ottawa, Vancouver, and Halifax.
The DSR Bank initiative was launched under the leadership of Rob Murray, former NATO Head of Innovation, who now serves as Chief Executive Officer of the DSR Bank Development Group. He has been central to developing the bank’s concept, governance framework, and early design strategy. It's structured as a multilateral capital formation platform to mobilize institutional capital for defence, dual use tech, and resilience infrastructure aimed at governments, sovereign funds, development institutions, and private investors.
The model resembles a structured institutional capital pool rather than a commercial bank. It would channel long term investment into defence supply chains, industrial capacity, and strategic infrastructure.
Canada has historically approached strategic finance through fragmented federal programs, export financing vehicles, and institutional lending channels. A coordinated capital platform of this scale would represent a structural evolution in how defence finance is organized.
Large scale capital vehicles now rely on digital infrastructure to function efficiently. Institutional platforms require:
• Cross border settlement rails
• Structured credit distribution tools
• Automated compliance reporting
• Digital identity verification
• Treasury management systems
• Secure asset tracking and reconciliation frameworks
Canada doesn't currently lead peer markets in payments modernization or open banking implementation but it's making headway. The Retail Payment Activities Act introduced a safeguarding and operational risk baseline, with registration opening in November 2024. Broader financial infrastructure modernization remains uneven compared to Europe and parts of Asia.
If the DSR Bank advances, the architecture beneath the capital will matter as much as the capital itself.
Canada's own experience shows that large financial frameworks become harder to modernize once core governance and operational structures are set. Early design decisions determine speed, transparency, and long term adaptability.
The DSR Bank is presently framed around banks, governments, and institutional investors. That foundation is essential. But modern capital platforms increasingly depend on digital infrastructure providers that support reporting, settlement, and liquidity management.
If Canada intends to position any of its great provinces or territories as a global defence finance hub, embedding capital infrastructure financial technology expertise at the design stage could strengthen execution credibility and investor confidence.
Canada has recent examples that show how large initiatives become harder to modernize once core structures are set.
Open Banking Implementation Delay
Canada began formal work on consumer driven banking in 2018, yet operational rollout has trailed peer markets. Early design focused on policy structure and liability allocation, while technical and ecosystem readiness moved more slowly. See the final open banking advisory committee report.
Real Time Payments Modernization
Payments Canada’s real time rail has experienced timeline revisions as governance, risk frameworks, and integration complexity became clearer during development. Coordinating multiple institutions and technology providers has required program level adjustments. See the real time rail payment system overview.
Phoenix Payroll System
The federal Phoenix payroll transformation remains one of Canada’s clearest infrastructure cautionary cases. The Auditor General found that system readiness and implementation decisions led to widespread pay errors and long running remediation. See the Auditor General Phoenix report landing page and the Phoenix audit report (44 page PDF).
Canada Infrastructure Bank Deployment Pace
The Parliamentary Budget Officer has tracked a persistent gap between the Canada Infrastructure Bank’s disbursement pace and its stated targets, highlighting execution and delivery constraints that can emerge once governance and operating models are set. See the PBO update on Canada Infrastructure Bank spending outlook.
These cases are not failures of ambition. They illustrate a recurring pattern. When operational builders and infrastructure participants are engaged after structural decisions are locked in, modernization becomes more expensive and slower to execute.
The DSR Bank initiative is being advanced with participation from large commercial banks. That is expected. Banks bring capital, balance sheet depth, regulatory experience, and global distribution. Scotia Bank and CIBC announced support, and so has TD bank, RBC bank, and international major banks such as JP Morgan and Deutsche Bank.
However, infrastructure design isn't only about capital. It is also about execution architecture, digital onboarding, identity verification, cross-border payment integration, compliance automation, and secure API connectivity. These are areas where fintech firms often build faster and operate closer to modern digital workflows.
If fintechs are engaged only after structural governance and system architecture decisions are finalized, the result can be slower integration, higher compliance retrofitting costs, and reduced competitive diversity.
Early participation allows design decisions to account for digital identity systems, embedded finance models, cross border transaction tooling, and programmable settlement layers that defence and resilience financing may increasingly require.
Montreal International’s pitch positions the city as a strategic hub for financial innovation and international collaboration. If that positioning includes fintech operators alongside global banks at the planning stage, it could strengthen the technical credibility of the initiative in addition to its capital backing.
The question is not whether fintech replaces banks. The question is whether ecosystem architecture benefits from involving builders who design digital infrastructure daily, before governance structures become fixed.
If Canada hosts a global defence capital platform, should digital capital infrastructure be embedded from day one?
The DSR Bank proposal reflects provincial ambition (not federal coordination, nor execution). Whether it becomes a durable strategic finance platform will depend not only on institutional capital, but on how effectively its underlying infrastructure is built.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech Super Bowl | February 9, 2026
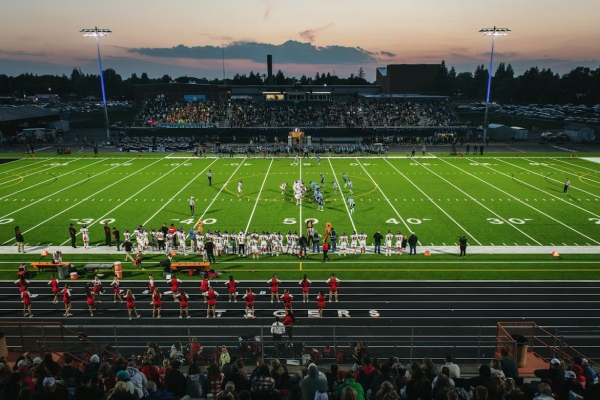
Image: Unsplash/Tim Mossholder
On February 8, 2026, Super Bowl LX took place at Levi’s Stadium in Santa Clara. The night also pulled in a wider culture audience with Bad Bunny headlining the Apple Music Super Bowl LX Halftime Show.
In crypto, the footprint looked far smaller than previous years with Yahoo Sports reporting that a 30 sec Super Bowl commercial costs about $8 million.
SportsPro reported that NBCUniversal sold 30 sec Super Bowl slots for more than $10 million.
That level of spend pushed fintech brands towards commercials that didn't only sell features. The ads needed to build confidence fast, because the cost demanded durable recall, not a momentary laugh.
In parallel, the night exposed operational risk when campaigns sent millions of people clicking call to actions at the same time. Business Insider reported multiple brands hit traffic driven glitches tied to Super Bowl campaigns, which showed that mass awareness could turn into public friction if the landing experience buckled.
Coinbase ran a karaoke style commercial built around Backstreet Boys lyrics and a delayed brand reveal. There was no voice overs or narration at all, and the spot was published as Everybody Coinbase.
Coinbase used a shared living room ritual to lower resistance and widen familiarity, then relied on the brand name at the end to do the work. That tactic could have widened reach, but it also created a predictable weakness. People who didn't already know Coinbase could have left without a clear sense of what the product did. Adweek argued the spot delivered weak product clarity, which matters when the goal depends on trust from first time viewers.
Ramp ran a Big Game spot that turned finance operations into the story and used Brian Baumgartner as the hook. Ramp published the commercial as Multiply What’s Possible. Ramp grouped some extra creative in its Ramp at Super Bowl 2026 playlist.
Ramp’s creative did something many B2B ads avoided. It treated spend control and finance workflows as a mainstream category that deserved brand memory, not just a rational comparison chart. That approach aimed to shorten the gap between hearing the name and feeling safe enough to bring it into a buying conversation. It also helped Ramp anchor a simple mental model for non-finance viewers. Finance work holds the business together, and Ramp sits close to the centre of it.
Rippling debuted a Super Bowl commercial featuring Tim Robinson while depicting workplace software friction as the villain. Rippling published the commercial as The Mastermind featuring Tim Robinson.
Rippling picked a different trust route than Ramp. Ramp leaned into competence and control. Rippling leaned into recognition. The ad reminded buyers how bad tools created chaos across payroll, HR, access, and compliance tasks. It then positioned Rippling as the way out. That message landed even for viewers who never bought workforce software, because most people had lived the pain of broken workplace systems.
This years Super Bowl showed a smaller crypto footprint and a stronger tilt toward enterprise fintech and business software. Coinbase was the only crypto advertiser, while Ramp and Rippling used the same stage to make finance operations and workforce operations feel like mainstream categories.
The ads also showed three different trust strategies. Coinbase used culture and participation to widen familiarity. Ramp used credibility and control to feel safe for finance teams. Rippling used humour to make operational pain feel universal, then offered relief as the brand promise.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 9, 2026 | NCFA Fintech Market Activity | Ecosystem and Capital
Image: Freepik
On January 26 2026, Y Combinator removed Canada from its standard deal terms, limiting eligibility for startups incorporated domestically. Within days, it reinstated Canada after founder backlash, restoring access under its typical investment framework, which details how incorporation jurisdiction directly affects capital access, governance structure, and long term scaling strategy for Canadian founders.
The initial decision did not involve a specific fintech company or funding round. It was structural. Y Combinator’s standard deal applies to startups incorporated in approved jurisdictions. Removing Canada effectively meant founders would need to incorporate elsewhere, typically in the United States, to participate under YC’s typical structure.
YC is one of the most influential accelerators in the world. Its standard deal, global demo day visibility, and alumni network continue to shape where and how startups incorporate. When a jurisdiction falls off that list, it forces founders to revisit fundamental questions about domicile, governance, and long term capital access.
Canada has long faced tension between building domestic champions and watching startups reincorporate in the U.S. to access deeper venture pools. The temporary exclusion exposed that pressure in real time. Founders openly questioned whether remaining Canadian limited their path to global capital. Investors pushed back on the optics and the implications for ecosystem competitiveness.
The reversal confirms something important. Founder voice still carries weight. When structural barriers appear, the community responds quickly.
This episode also lands in a broader moment of scrutiny around capital flows and jurisdictional friction. As previously covered by NCFA in prediction markets pricing geopolitical risk, capital increasingly reacts to policy shifts, regulatory posture, and national positioning. Incorporation strategy is no longer a back office decision. It sits at the center of competitive positioning, a topic that many legal advisors regularly bring up with their client firms for years, often to the detriment of Canada's startup ecosystem.
YC did not publicly frame the move as a statement about Canadian founders. The accelerator has previously highlighted data showing many international startups choose U.S. incorporation for fundraising efficiency. But the optics of removing an entire G7 country triggered a deeper conversation about structural competitiveness and capital alignment.
For fintech specifically, where your company is registered and domiciled affects licensing pathways, regulatory relationships, and banking partnerships. A Canadian incorporated fintech navigating CIRO, CSA, or RPAA requirements faces a different operating map than one structured under Delaware law. Founders weigh tax efficiency, governance flexibility, investor familiarity, and exit pathways.
Before choosing incorporation jurisdiction, founders should be clear on a few points:
These questions affect investor comfort, term sheet dynamics, and how quickly you can close capital when markets tighten.
The episode also puts a spotlight on Canada’s policy environment. If global accelerators and venture firms default to U.S. incorporation for efficiency, policymakers should ask why. Founders make structural decisions based on predictability, tax treatment, regulatory clarity, and access to institutional capital. If Canada wants more high growth companies to incorporate and remain here, it must reduce friction in securities regulation, modernize capital formation rules, and deepen domestic late stage capital pools. Incorporation decisions follow incentives. Capital flows toward simplicity and scale.
Capital markets still reward certain structures and jurisdictions more predictably than others. That doesn't mean Canadian incorporation is a disadvantage. It does mean founders must approach the decision deliberately, not emotionally.
The larger takeaway is not about one accelerator. It is about ecosystem resilience. When capital gatekeepers adjust terms, even briefly, founders notice. Policymakers should notice too.
If incorporation jurisdiction influences access to global capital networks, how can Canada strengthen incentives so founders choose to build and scale at home without sacrificing investor reach?
This episode resolved quickly. The underlying tension did not.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026).
The hard part isn't moving money, it's proving every step. Teams that package premium flows with clean records and clear controls can earn carrier trust faster and grow without drowning in back office work.
This rule draws a hard line around who owns the onshore asset, who carries the filing burden, and what gets blocked before a token ever reaches the market. For founders building real world asset tokenization rails, this pushes compliance into the product spec, not the legal appendix. For investors and institutions, it also hints at where future supply can actually clear, which issuers can survive the documentation load, and which token structures will get rejected early.
This deal pushes tokenized gold closer to mainstream rails. Wallets and platforms now face tougher buyer questions on custody, redemption, and who controls the customer relationship at conversion.
Platforms that want to scale under Canadian dealer oversight now need custody choices, contracts, and segregation controls that hold up under faster and more explicit supervision.
Stablecoin rewards now sit on the critical path for US rules. Fintech teams that sell payments, custody, compliance, or market infrastructure into US regulated buyers should expect procurement questions to lock onto rewards design, reserve treatment, and where yield can legally sit in the stack.
A limited first cohort can steer who wins distribution and which stablecoin infrastructure stacks become the default for partners and platforms.
UK buyers will treat payments as national infrastructure, not a feature set. Fintechs that win distribution will show they can plug into policy goals on resilience, competition, and security while still shipping product fast.
This changes the bar for anyone selling account to account payments, open banking rails, fraud controls, or programmable payments. Founders should align roadmaps to the coming scheme design work and the Spring consultations the Bank flags, because UK infrastructure choices will shape product requirements for years.
This matters for any stablecoin issuer and infrastructure provider that wants institutional distribution. When regulators expand who can issue an eligible payment stablecoin for margin collateral use, counterparties get a clearer path to treat certain stablecoins as real plumbing inside regulated derivatives workflows. Fintechs that sell custody, collateral management, settlement, and stablecoin compliance can use this to anchor partner conversations around issuer structure, segregation controls, and how tokenized collateral actually clears inside regulated accounts.
This deadline forces teams that rely on Switzerland for issuance or operations to lock in licensing and controls early. Partners will push for clear governance, clean reserve treatment, and cross border compliance that holds up under scrutiny.
Fintech teams feel this through tighter budgets, higher buyer scrutiny, and more demand for products that raise productivity inside core financial workflows, especially in trade, credit, risk, and compliance.
Stress scenarios push banks to revisit credit appetite, model controls, and operational risk tolerance.
This deadline matters to fintechs that serve high net worth users, wealth platforms, brokers, and crypto firms that want UK market access. Teams that treat categorisation and conflicts as product logic, not legal text, will cut future remediation cost and speed up institutional partnerships.
OSFI sets an execution timetable that forces bank and fintech partners to treat prudential policy as a product requirement. Teams that sell underwriting, credit risk, treasury, or compliance tooling into federally regulated institutions will face tighter questions on governance ownership, model controls, and liquidity evidence.
This creates a real bottleneck for financings and time sensitive filings. Operators win time when they build buffer into launch plans, keep disclosure ready ahead of pricing, and avoid dependencies on last minute staff action.
Stablecoin rewards now sit in the middle of a real fight between banks and crypto firms, and that fight can decide how fast regulated buyers adopt stablecoin rails. In Canada, CIRO puts sharper expectations on digital asset custody, which raises the bar on contracts, segregation, and proof of control for any platform that wants to scale. In the UK, the payments roadmap starts to look like a build plan, not a wish list, and conduct rules keep moving into onboarding logic and product decisions. This week rewards teams that treat controls and governance as part of the product, because that is what buyers need before they expand distribution, and tokenized assets like tokenized gold now face the same test, prove custody, prove redemption, and prove who carries responsibility when real value moves across platforms.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Economy | February 6, 2026
On February 5, 2026, Bank of Canada Governor Tiff Macklem delivered a speech at the Empire Club of Canada called 'Structural Change - Canada at Crossroads' warning that Canada has reached a productivity crossroads, where long standing structural limits now cap growth, wages, and competitiveness. Inflation no longer defines the constraint. Productivity does. For founders, investors, and policymakers, the question is no longer whether innovation exists in Canada, but whether the economic system allows it to scale. Of course, many stakeholders have been eluding to this data-driven fact for a decade, including NCFA.
“Canada’s productivity performance has been weak for a long time, and that limits how fast our economy can grow.”
Macklem identifies productivity as the binding constraint on Canada’s economic outlook. The data is clear. According to OECD GDP per hour worked data, Canada’s labour productivity remains well below the United States and has fallen further behind over the past decade. In 2023, Canada produced roughly 72% of US output per hour worked, a gap that continues to widen.
The Bank of Canada links this shortfall to weak business investment, slow technology adoption, and limited competitive pressure. These factors suppress output growth even as employment rises. As a result, wage growth, firm profitability, and national competitiveness all face structural limits.
NCFA analysis shows that productivity challenges increasingly reflect underinvestment in digital infrastructure, automation, and scalable financial systems rather than a shortage of talent or ideas. For example, see: Breaking Canada’s Productivity Trap For Stronger Growth or Fintech’s Role In Canada’s Productivity Revival or Canada's Productivity Depends on Intangible Tech Adoption, which detail how capital misallocation and limited competition slow modernization across sectors.
For fintech founders, productivity gaps point to unmet demand for tools that reduce friction in payments, lending, compliance, and data driven decision making. Where legacy systems persist, productivity losses accumulate across the economy.
“More competition pushes firms to innovate, invest, and become more productive.”
Macklem ties productivity directly to competitive intensity. Where markets concentrate, firms face less pressure to adopt new technology or improve efficiency. Canada’s financial services sector illustrates this clearly. In fact, the Bank of Canada's Senior Deputy Governor, Carolyn Rogers, called Canada's banking system an Oligopoly. Concentration in lending, payments, and capital markets slows adoption of new models that could lower costs for businesses.
NCFA tracks this dynamic, here are just a couple of examples: How Competition Powers Canada’s Economic Growth and Why SME Loan Competition In Canada Is Under Review.
Small and medium sized businesses feel the impact most. Limited lender choice raises borrowing costs and lengthens approval timelines. For fintech lenders and embedded finance platforms, this reinforces demand for modern credit models that expand access while maintaining risk discipline.
“Investment needs to flow to the firms that can grow and raise productivity.”
Canada’s venture capital structure continues to constrain scale. According to RBCx data, Canadian VC Fundraising Contracts And Concentrates, raising just over $2 billion in 2025. Capital concentrates heavily. The top five funds account for roughly 83% of total capital raised, while emerging managers raise approximately $249 million.
At the same time, total venture investment reached about $4.9 billion across 386 deals through the first nine months of 2025, compared with roughly $8.6 billion across all of 2024. These figures describe two forces in the same system. Fundraising concentrates while deployment becomes more selective.
For founders, capital access becomes a strategic constraint rather than a timing issue. For investors, it narrows the pool of companies able to scale inside Canada.
“Good policy supports competition, investment, and long term growth.”
Macklem acknowledges that productivity doesn't improve in a vacuum. Firms respond to the regulatory environment they operate in. When compliance costs rise faster than firms' capacity, or when rules favour incumbents over new entrants, productivity suffers.
NCFA has consistently shown that regulatory design plays a decisive role in whether innovation scales. When rules increase cost or delay without improving outcomes, firms delay investment and avoid experimentation. Productivity improves when regulation supports entry, proportional compliance, and faster market testing, as outlined in Innovative Approaches to Smarter Regulation and Overcoming Barriers to Growth in Financial Regulation.
Smarter regulation does not weaken safeguards. It reduces duplication, improves clarity, and aligns oversight with actual risk. Jurisdictions that achieve this balance create space for competition and faster technology adoption, lessons explored in Lessons for Canada from Global Leaders in Regulation.
“Efficient financial systems help capital move to its most productive uses.”
Macklem’s remarks extend naturally to payments infrastructure. Canada payments system processes enormous transaction volumes, reaching $12.2 trillion in 2024, yet modernization remains uneven.
Slow settlement and high transaction costs lengthen working capital cycles and increase operational risk, especially for SMEs. The productivity impact of faster payments and modern rails can't be understated as many countries rush to modernize their payment ecosystem and functionality, including Canada who has been working to update it's payment system for years and only now making progress being under the gun.
For fintech builders, payments remain one of the most direct ways to improve productivity across the economy.
“Productivity growth depends on the environment firms operate in.”
Macklem’s framing helps explain why successful Canadian built companies increasingly scale elsewhere. Why A $35M Built In Canada Startup Still Moved To The US, shows how growth stage constraints shape founder decisions even after proving traction at home. When capital pools, market size, and regulatory pathways align more clearly abroad, relocation of entrepreneurs and venture brain drain mirrors operating decisions, not national sentiment.
This trend reinforces the need to address productivity, competition, capital access, and regulation together rather than treating talent retention as a standalone issue. Founders are now at crossroads, and trying to make it work within system constraints.
When capital, regulation, and market access align, firms stay. When they do not, firms move.
Macklem’s speech aligns closely with the productivity, competition, and innovation themes NCFA has tracked and raised for years. Productivity improves when competition deepens, capital flows efficiently, regulation supports entry, and technology adoption accelerates. Fintech sits at the intersection of all four.
Policy tools that support SME expansion, such as export financing and market access programs, can reinforce financial innovation when aligned properly. Programs like CanExport SMEs show how capital support and operational scale can work together rather than in isolation. The challenge now is execution. Productivity gains come from systems that allow new firms to compete, scale, and deploy technology without unnecessary friction.
You may like these additional reads:
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 6, 2026 | NCFA Fintech Market Activity | Digital Banking and Regulation
Image: Freepik/lifeforstock
On January 29 2026, Nu received US bank approval to establish a US national bank under the Office of the Comptroller of the Currency (OCC).
The company said the approval supports its plan to build a federally chartered bank in the United States, subject to conditions and further steps before the bank can begin operating. A national bank structure sits at the core of how US banking works, including capital rules, governance expectations, and ongoing supervision.
Nu operates a large digital banking platform across Latin America. A US charter path places the firm inside a regime built for deposit taking institutions, not for sponsor bank partnerships or program structures. That changes what the company must build behind the scenes, including compliance controls, audit readiness, and risk management that can stand up to sustained regulatory oversight.
For founders and investors, this is a clean reminder about where scale often ends up. A fintech can grow quickly with product and distribution. A fintech can protect that growth only when it builds the governance and control stack that regulators and counterparties demand at national scale and volume.
A US national bank charter also sets a different operating ceiling. It can support a broader product set, a more direct funding base, and national reach under a single federal framework, but it comes with tighter obligations and less room for improvisation.
When a fintech steps into full bank regulation, which capability becomes the real constraint, distribution, underwriting, or the control stack that keeps regulators and partners confident?
Nu now faces an execution test that rewards operational strength, not marketing. Teams that incorporate governance as a product feature can sometimes scale faster because large buyers and regulators stop asking the same questions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016