




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


January 27, 2026 | NCFA Resource | Open Banking And Consumer Driven Finance, Risk Compliance And Regtech, Artificial Intelligence And Data
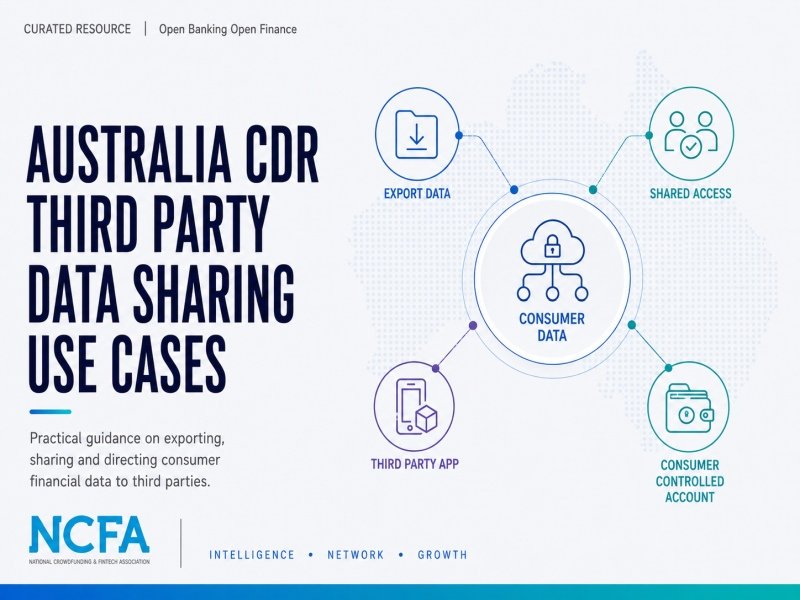
On January 27, 2026, Australia’s Consumer Data Right updated its Third Party Data Sharing Use Cases with practical examples showing how consumers can export financial data, give another person access, send data to another application or direct it into an account they control.
The Australian Competition and Consumer Commission developed the guidance with input from Treasury. It tackles a straightforward product question. After an accredited provider receives a consumer’s financial data, what can the consumer do with it next?
The answer depends on who initiates the sharing, where the information goes and who controls the destination. Those details affect consent, privacy and the provider’s responsibilities.
The guidance organizes third party sharing into four situations:
Who initiates the sharing is the key distinction. The ACCC says these consumer directed scenarios are unlikely to raise compliance concerns when the consumer makes a clear and informed choice. Downloading data, configuring access or instructing the provider to send information helps establish that the consumer chose the disclosure.
If the provider is making the disclosure itself, the permitted use and disclosure rules apply. The provider needs the authority and consent required under Australia’s Consumer Data Right rules.
That difference becomes concrete in product design. Letting someone download transaction history for personal analysis carries different responsibilities from automatically sending customer information to another company. Giving an accountant controlled access inside an SME finance platform is also different from transmitting the data outside that service.
Where the financial data remains inside the accredited provider’s service, the provider continues to carry the relevant Consumer Data Right obligations. These include privacy safeguards covering data security and the destruction or de-identification of information that is no longer required.
When consumers send their data outside that environment, they need to know how the recipient will handle it. The ACCC says providers should explain that other privacy laws may apply and encourage consumers to review the recipient’s data handling policies.
The same framework can support a single disclosure or recurring sharing for a defined period. The provider must hold the collection and use consents required for the service. Consumer Data Right consent generally lasts for up to 12 months, while some business consumer consents can extend for up to seven years.
Fintech product teams can use these examples when building financial data portability into real services. A personal finance app could let customers export transaction data for their own analysis. An SME platform could give an accountant controlled access to business records. A lending or cash flow application could let customers send selected information into another service they already use.
Compliance and legal teams can review the same features by asking a few direct questions. Who initiated the disclosure? Who controls the destination? Does the information stay inside the accredited service? What consent supports the sharing? Which obligations continue once the data leaves?
Banks and other financial institutions can use the examples to anticipate how customers may expect data portability to work. Consumers are unlikely to organize their behaviour around regulatory terminology. They will want financial information to work with budgeting software, accounting systems, lending applications, analytics tools and other services they choose.
Canada will face similar product questions as Consumer Driven Banking reaches implementation. Canada Open Banking And Consumer Driven Banking Rules tracks accreditation, authentication, consent, data sharing, security and liability requirements. Australia’s examples show what product teams have to consider after the first regulated transfer, when a customer wants to reuse the information somewhere else.
Standardized financial data can support credit assessment, fraud detection, cash flow analysis and financial guidance as well. NCFA’s Open Banking Decision Intelligence looks at how firms can turn permissioned financial data into better decisions. Third party sharing gives consumers and businesses more control over which tools can participate in those workflows.
The four examples are specific enough to use in product and compliance discussions. Teams can look at an export button, an accountant access feature, an application-to-application transfer or recurring sharing arrangement and ask exactly who controls the data at each point.
The guidance also shows why interface design and compliance cannot be separated. A button that lets the consumer choose where information goes can create a different regulatory position from a service that sends the same information on its own. Consent, control of the destination and whether the provider continues to hold the data all affect the answer.
That's useful context for Canadian teams working through consent and downstream data use. Canada can define who participates in regulated sharing and how financial institutions transfer data to accredited recipients. Customers will still want to download that information, share it with professionals, use it in another application or authorize access over time.
Australia’s rules do not determine what Canadian firms can do. The two countries have different legislation, privacy requirements, accreditation models and regulatory terminology. The Australian examples are useful because they expose practical questions Canadian product, compliance and policy teams will also have to answer.
The ACCC also makes clear that the article is general guidance. Whether a particular implementation complies with Australia’s Consumer Data Right depends on the circumstances, and providers remain responsible for assessing their legal obligations.
Consumer Data Right (Australian framework, participants and consumer information)
Legal Obligations For Data Recipients (collection, consent, use and disclosure requirements)
CDR Privacy Safeguard Guidelines (privacy requirements for handling consumer financial data)
Canada’s Open Banking Strategy Starts With Trust (consent, fraud, liability and consumer protection in Canada)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 1, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, SME Finance And Business Banking, Digital Banking And BaaS
On September 1, 2026, London, Ontario based VersaBank announced the first U.S. Real-Time SRP implementation with ECN Capital. The system can fund eligible point of sale loans within hours. VersaBank says conventional funding can leave lenders waiting five to 30 days or longer while enough receivables accumulate.
ECN isn't a new customer. It implemented VersaBank's original U.S. Structured Receivable Program in 2025, and another ECN subsidiary joined the program in July with at least US$300 million in expected annual fundings. ECN Capital's Chris Johnson said the original SRP helped the company “grow our business faster” while improving profitability. The September implementation adds the newer real time capability, although VersaBank hasn't disclosed how much volume is flowing through it yet.
The scale is already substantial. VersaBank's total Structured Receivable Program portfolio exceeded C$4.4 billion as of January 31, 2026 after growing at a 33% compound annual rate over five years. U.S. SRP credit assets reached US$604.9 million by the end of the bank's second fiscal quarter of 2026, and VersaBank was targeting at least US$1 billion in additional U.S. SRP fundings during fiscal 2026.
What changes with ECN is speed. A funding model VersaBank has used in Canada for more than 15 years, and recently accelerated with Financeit, is now running in the U.S. with an established finance company.
Point of sale lenders need capital to keep making loans. A lender financing home renovations, HVAC systems, equipment or other large purchases may hold new receivables on its own balance sheet or borrow against them through a warehouse facility until the loans can be sold, refinanced or packaged into a securitization. That interval ties up capital and carries a financing cost.
VersaBank's Structured Receivable Program purchases qualifying receivables from finance companies. Real-Time SRP brings that funding closer to the original loan by evaluating and financing eligible individual receivables within hours rather than waiting for a larger pool to accumulate.
The model was first tested through an April Financeit pilot. The pilot finished ahead of schedule, and Financeit became the first partner to use Real-Time SRP at large scale when VersaBank formally launched the program in June. Financeit was approaching C$2 billion in annual loan originations, giving VersaBank a sizeable Canadian lending operation on which to prove the process before taking it into the U.S.
VersaBank describes the system as AI enabled, but its public disclosure supports a more targeted description. The bank says its internal AI technology helps evaluate individual loans underlying SRP receivables. It has not disclosed enough detail to determine exactly how eligibility, credit scoring, fraud checks or other decisions are divided between automation and human oversight.
Financeit completed a C$201 million ABS in June while also using VersaBank's real time funding. Those sources of capital can serve different stages of the same lending business. VersaBank can provide funding closer to origination, while securitization can provide longer term institutional capital after loans have accumulated into a larger pool.
Forward flow provides another option. Propel Holdings secured a US$60 million forward flow from Mesirow managed funds for Freshline loans, allowing institutional capital to purchase eligible production as it is originated. Warehouse lenders, forward flow investors, banks, private credit funds and ABS buyers are all competing to fund the period between a lender making a loan and receiving longer term capital.
VersaBank is trying to compress that period. The economic benefit depends on whether the cost of its funding, integration requirements and credit rules are attractive enough to save lenders money or free enough capital to justify adding another funding relationship.
VersaBank has operated versions of its Structured Receivable Program in Canada for more than 15 years. It entered the U.S. point of sale finance market after acquiring a U.S. bank in 2024, giving VersaBank an OCC chartered national banking platform in Minnesota.
VersaBank is doing more than licensing software to ECN. It's using deposits and its own balance sheet to buy qualifying U.S. receivables through a funding model developed in Canada. That lets the bank grow through lending partners without having to build a large consumer lending operation itself.
ECN is now using the faster version in the U.S. VersaBank already had hundreds of millions of dollars in U.S. SRP assets, and the wider ECN relationship includes at least US$300 million in expected annual fundings. The real time version gets eligible receivables onto VersaBank's balance sheet sooner.
Faster funding can help lenders keep more cash available for new loans, but only if VersaBank's price and credit rules beat the alternatives. Lenders already have warehouse lines, forward flow buyers, banks and securitization markets competing for their business, so speed alone won't win the account.
For VersaBank, more U.S. receivables mean more loans and leases earning interest on the bank's balance sheet without VersaBank having to find the borrowers itself. The economics work only if what the bank earns on those assets stays comfortably above its funding costs and credit losses.
Growth can also concentrate risk. A few large partners, weaker loan quality or rising deposit costs could turn faster asset growth into lower returns. ECN is the first U.S. user of the real time version, so the more telling evidence will be whether other lenders adopt it and whether those portfolios perform well as volumes rise.
Private credit adds another source of competition for finance companies seeking capital. Canadian institutions already have roughly C$500 billion of private credit exposure, much of it outside Canada, while U.S. private credit funds have become major lenders to businesses and specialty finance companies. VersaBank is entering that competition with a regulated bank balance sheet, a deposit base and a funding system designed to work much closer to loan origination.
Can VersaBank turn a Canadian funding model into a scalable U.S. lending business?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 2, 2026
India is increasingly relevant to fintech companies for more than market access. It is also a significant source of technology, product, finance, risk, data, and operational talent that global scaleups can integrate into international teams.
India's wider startup ecosystem had more than 2.23 lakh government-recognised startups by March 31, 2026, while the country's digital financial infrastructure continues to expand rapidly. UPI alone processed more than 24,000 crore transactions during FY26, illustrating the scale at which digital financial services now operate in the country.
For a Canadian or international fintech, however, deciding to recruit in India creates a strategic question:
Should the company establish an Indian entity before building a team, or can it begin hiring first and make the larger corporate investment later?
For many scaleups, these decisions do not need to happen simultaneously.
A phased talent strategy can allow a fintech to test access to Indian talent, build an initial team, understand operating costs, and validate its long-term requirements before committing to a full local entity.
India combines a large technology workforce with an established ecosystem across financial services, digital payments, software development, data, and startup innovation.
This creates hiring opportunities across functions that fintech companies frequently need as they scale, including:
India's digital payments ecosystem also gives fintech professionals exposure to financial products operating at substantial scale. UPI accounted for 85.5% of India's digital payment transaction volume in the second half of 2025, according to RBI data reported by IBEF.
But the business case for building a team should not begin with the question, "How many people can we hire?"
It should begin with:
Which capabilities should the company own internally, and which of those capabilities can be built effectively in India?
That changes hiring from a cost exercise into a talent strategy.
A fintech talent strategy defines which capabilities a company needs, where those capabilities should be located, and how employees will be hired, managed, and integrated into the organisation.
For an India expansion, a useful talent strategy should address five areas:
This is particularly important for fintech companies because many roles interact with sensitive financial data, regulated products, security systems, or customer operations.
Hiring should therefore be considered together with data access, information security, governance, internal controls, and business continuity.
The first India hires should solve clearly defined business problems rather than simply expand headcount.
A practical approach is to prioritise functions where the company already understands the workflows and can manage outcomes remotely.
| Function | Why a Fintech May Build It in India |
| Engineering | Product development, integrations, platform infrastructure |
| Data | Analytics, reporting, data engineering and modelling |
| QA | Product testing, automation and release support |
| Cybersecurity | Security operations and technical monitoring |
| Finance operations | Reporting, reconciliation and operational support |
| Customer operations | User support and service delivery |
| Risk operations | Process-driven risk and verification support |
| Product operations | Coordination between technology, product and commercial teams |
Leadership should also identify whether the function is supporting the global business or conducting activity directly in the Indian market.
That distinction can affect entity, regulatory, tax, and Permanent Establishment considerations later.
Yes, depending on the type of relationship and business activity.
A foreign fintech typically has several potential models available.
Contractors may be appropriate for genuinely independent, project-based work.
For example, a fintech might engage a specialist for:
Contractors should not simply be used as substitutes for employees where the actual working arrangement functions like regular employment.
A fintech can outsource a complete function or defined process to another company.
In this model, the external provider typically manages its own employees and delivers an agreed service or outcome.
That is different from building a dedicated internal team.
Where a fintech wants dedicated employees in India but does not yet have a local employing entity, an Employer of Record India model can provide another option.
The EOR becomes the legal employer in India, while the fintech continues to manage employees' daily responsibilities, goals, projects, and performance.
A fintech can establish its own Indian company and employ staff directly.
This generally provides greater long-term control but also introduces ongoing corporate, accounting, payroll, HR, tax, and administrative responsibilities.
The best structure depends on the company's stage and objectives.
| Factor | Contractor | Outsourcing | EOR | Own Entity |
| Dedicated employee relationship | No | Usually no | Yes | Yes |
| Local entity required | No | No | No for EOR employment | Yes |
| Client controls daily work | Limited by independent relationship | Usually outcome-focused | Yes | Yes |
| Local payroll | Not employee payroll | Provider handles employees | EOR handles | Company handles |
| Initial setup burden | Low | Low | Lower than entity | Highest |
| Suitable for testing India | Yes, for genuine projects | Yes | Yes | Possible but larger commitment |
| Long-term large workforce | Limited | Depends on model | Depends on scale | Strongest fit |
For a fintech building an internal product or operations team, the main comparison is often between EOR employment now and direct employment through an entity later.
Entity establishment is a strategic corporate decision.
Hiring can be an operational decision.
Those decisions may move at different speeds.
Suppose a Canadian fintech has funding to build a six-person engineering and data team in India. It already knows the roles it needs, but management is not yet certain whether India will eventually support 10 employees, 50 employees, or a much larger operation.
Immediately building a company around an uncertain headcount assumption can create unnecessary fixed infrastructure.
A staged approach allows the fintech to answer questions such as:
The business can then make its entity decision using operating evidence rather than projections alone.
Salary is only one component of India workforce costs.
Finance teams should compare the total cost of different structures.
Relevant categories can include:
An EOR may involve a per-employee service fee, while an owned entity introduces more fixed organisational costs.
The economics can therefore change as the team becomes larger.
Companies comparing these structures can also review State of India EOR 2026 when assessing employment costs, entity considerations, compliance responsibilities, and potential tax exposure.
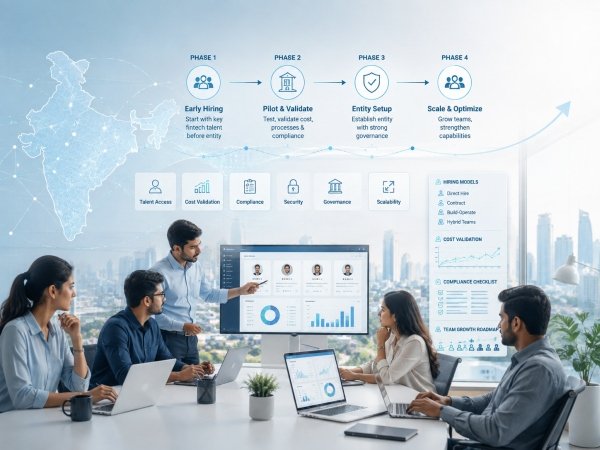
Fintech teams often work within more sensitive operating environments than ordinary remote teams.
The question is not simply whether a developer or analyst can work remotely.
Companies may also need controls around:
Employees may interact with customer data, financial information, transaction records, or internal risk systems.
Access should be based on role requirements.
Devices, authentication, credentials, source code, and internal platforms require appropriate security controls regardless of where employees are located.
Certain finance or payment workflows may require multiple layers of approval rather than giving one employee end-to-end control.
Teams should understand who owns decisions, where approvals are recorded, and how processes are audited.
Hiring someone in India does not itself determine whether the fintech is permitted to offer regulated financial services in India.
Employment structure and financial-services licensing are separate questions.
A company building an India team to support overseas operations should therefore distinguish workforce expansion from market entry.
India's four consolidated Labour Codes came into effect on November 21, 2025, covering wages, industrial relations, social security, and occupational safety and working conditions.
Companies employing workers directly need processes covering relevant employment requirements, including areas such as:
Under an EOR structure, many agreed employer-side administrative responsibilities are handled by the EOR.
However, using an EOR does not remove the fintech's responsibility for how employees access systems, handle information, perform regulated activities, or represent the business.
Potentially, depending on what the employees do.
An EOR or contractor arrangement does not automatically eliminate Permanent Establishment or wider business-connection considerations.
India's Income Tax Department states that business income of a non-resident can be taxable in India where the enterprise has a Permanent Establishment or business connection, subject to applicable tax treaties.
Indian tax rules also identify activities such as habitually concluding contracts or playing a principal role leading to the conclusion of contracts as potentially relevant to business-connection analysis.
A fintech should therefore obtain appropriate tax advice where India-based personnel:
A developer supporting a global product and a senior commercial executive entering contracts on behalf of the foreign company may present very different risk profiles.
An entity can become increasingly attractive as India moves from an experimental talent location to a strategic operating hub.
Common indicators include:
There is no universal employee number at which every fintech should incorporate.
The decision should consider scale, cost, tax, regulation, employment requirements, business activity, and long-term strategy together.
A practical expansion sequence can look like this:
Identify the roles that India can support and the business problem each role solves.
Recruit a small number of clearly defined roles using an appropriate employment structure.
Implement security, communication, management, documentation, payroll, and performance systems.
Compare productivity and total employment costs against the original business case.
Estimate whether the India operation is likely to remain a small global team or grow into a major operating centre.
Once the scale and commercial requirements are clearer, evaluate establishing a local entity.
This approach allows a fintech to treat entity setup as a consequence of proven scale rather than a prerequisite for exploring Indian talent.
For fintech companies that want employees in India before establishing their own entity, Asanify provides an India-focused Employer of Record model.
Asanify operates through its own Indian entity and can act as the legal employer while the client fintech retains control over employees' daily work, responsibilities, and performance.
Its EOR support can include:
This structure can be useful for scaleups testing the Indian talent market or building an initial team while their long-term entity strategy remains under evaluation.
Tax, regulatory, financial-services licensing, PE, data, and other business-specific risks should still be assessed separately.
For fintech scaleups, India expansion should start with the capabilities the business needs, not with entity setup.
Companies can first define the right roles, choose a suitable employment model, and validate costs, compliance, and team performance. This gives leadership a clearer view of how India fits into the wider operating strategy.
As the team grows, the business can then decide whether a larger local infrastructure or entity is justified. A phased approach helps keep early expansion flexible while supporting more informed long-term decisions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 2, 2026
Image: Pexels
Ontario has turned a small product detail into a serious design question. A deposit limit once looked like a setting near the edge of an account page. In 2026, the Ontario Lottery and Gaming Corporation moved it closer to the centre of the experience when it introduced a measure requiring some online players under 25 to set deposit limits as engagement rises through its safer gambling approach. That decision gives fintech designers a live case study in timing and restraint.
The point reaches beyond gaming. Banking apps, trading platforms and payment products all ask people to make money decisions on small screens. Speed helps when someone pays a bill and it can harm judgment when a screen nudges faster spending. Ontario’s model shows how a digital product can add friction at the right place without turning every action into a lecture.
OLG’s under-25 measure focuses on a group that research often links with higher gambling harm. The rule does not ban play. It asks certain users to set a cap as their activity grows. A cap can be daily or longer term. In financial design, the same idea can apply to stock trading deposits or crypto purchases. Earlier boundaries can reduce decisions made under pressure.
Ontario also gives designers a mature market to study. iGaming Ontario says its regulated market produced $82.7 billion in wagers during 2024 to 2025, with $2.9 billion in gaming revenue across more than 2.6 million active accounts in its annual report. A market of that size creates real design evidence. The best lessons come from how controls appear during ordinary use.
Spending controls work best before stress arrives. A daily limit has more force when someone sets it during account setup. A reminder has more value when it appears before a pattern becomes hard to interrupt. Product teams often want the shortest route to a completed transaction. Ontario’s approach suggests a better question for finance apps: at which point does speed stop helping the customer?
Investing apps already face a version of this test. A user may understand a company but misunderstand leverage. Another may know the price of a fund but overlook currency exposure. A good interface does not need to scold either person. It should show the cost, the limit and the consequence before confirmation. Ontario’s spending controls offer a model for that kind of intervention.
Casino comparison sites entered this landscape because choice became too large for casual browsing. Readers now compare payment methods, transaction times and withdrawal rules before opening an account. They also check licences, customer support and responsible-gambling tools before making a first deposit, a research habit that increasingly resembles fintech comparison. Someone choosing a trading app, for example, wants fees and account conditions visible before funding begins.
A regional review page can serve the same purpose by showing how product design differs across approved platforms. Someone looking at options selected by Casino.ca in Ontario can compare licensed casinos across practical criteria such as payment methods, withdrawal speeds, games and overall experience. The review format becomes more useful when it goes beyond a simple ranking and helps readers understand why platforms differ, including differences in security, banking options and customer support.
That structure also shows fintech teams how third-party guides can add value by making fees, risks, account controls and other important product information easy to inspect and compare. In both casino and fintech contexts, the strongest comparison experience helps users evaluate the product before they commit funds, rather than leaving important conditions until after registration.
Behaviour signals can help a product notice risk before a user asks for help. A sudden limit increase has meaning in one context and less in another. Several deposits in a short period can show excitement, confusion or distress. The product cannot read motive. It can slow the next step and offer support without pretending to know the full story.
The Alcohol and Gaming Commission of Ontario tells operators to use automated and manual monitoring so they can identify signs of harm and respond at a pace that matches changing behaviour in its operator guidance. Automated checks can catch patterns at volume. Staff review can add judgment where a rule may overreach. Fintech products need that same balance when they flag risky payments or rapid trading.
Crypto products face a harder version because transfers move fast and reversal options can be limited. A wallet app can show network fees and destination checks before a transfer leaves. A trading product can display volatility ranges before a purchase. Those steps protect choice by adding context. They work best when the words sound like service language rather than legal fog.
A control that users cannot find has little practical value. iGaming Ontario reported player awareness of responsible gambling tools at 71.5% in 2024 to 2025 through its 2026 to 2029 business plan. That figure gives product teams a hard target to think about. Of course, awareness doesn't arrive by placing a link in a footer. The interface has to bring the tool into normal view.
Fintech apps often place limits in account settings. Many users visit that area only when something breaks. Better design brings controls into the flow. A deposit screen can show the current cap. A payment app can show a monthly spending marker. A trading platform can let customers set cooling-off periods before volatile orders. The user still decides, but the decision gains context.
Language decides whether people use the feature. “Set a deposit limit” works better than “configure responsible-use parameters.” “Take a break” works better than a policy label. The same rule applies in banking. “Pause card spending” tells the user what will happen. “Manage transaction governance” sends them elsewhere. Good fintech design respects attention.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 1, 2026 | NCFA Market Activity + Insight | Insurance And Insurtech, Embedded Finance, Competition And Market Structure
On September 1, 2026, Foxquilt launched E&O insurance in the United States, giving the Toronto founded insurtech its second admitted U.S. product. The initial rollout covers Alabama, Arizona, Georgia, Michigan, New Jersey, Ohio, Pennsylvania, South Carolina, Texas and Wisconsin, with nationwide availability targeted by the end of 2026.
Errors & Omissions (also called Professional Liability) covers financial losses caused by mistakes or failures in professional services. Foxquilt is targeting consultants, technology firms, beauty and health professionals and other service businesses, adding a different type of risk to the Commercial General Liability coverage already available through its U.S. platform.
Customers, agents and brokers can quote and bind both products through Foxden, Foxquilt's insurance platform. Embedded partners can also place E&O inside marketplaces, networks and other services used by independent professionals. Foxquilt describes the launch as part of its development from a single product U.S. MGA into a multi product commercial insurance business.
Foxquilt was founded in Toronto in 2016 and started testing U.S. expansion years before this launch. It raised C$8 million in Series A funding in 2021 to support hiring, product development and expansion across the U.S. and Canada, followed by a C$12 million Series B aimed at North American expansion, technology infrastructure and a wider product offering.
Its U.S. footprint has since become much more substantial. Foxquilt expanded its small business insurance products into New York as it built agent, wholesale and enterprise distribution. The company now lists offices in Toronto and Charlotte, overall distribution across 50 U.S. states and eight Canadian provinces, and more than 50 distribution partners. Foxden supports direct retail, embedded partnerships, wholesale distribution and MGA syndicates.
E&O adds more value to those relationships because a broker or partner can now place more commercial coverage through the same system. A consultant or software company may need General Liability for property damage or injury claims and Professional Liability for financial losses tied to its work. Foxquilt can serve more of that account without asking the distributor to switch platforms.
The company is also building on its U.S. capacity relationship with Markel. CEO Karim Jamal says “E&O is the first of several strategic additions to our platform”, making today's launch part of a larger product plan rather than a one off filing.
Canadian insurtech funding remains selective. KPMG counted only two Canadian InsurTech deals in H1 2026, compared with 19 AI and machine learning fintech deals. More activity is happening inside underwriting, automation and distribution, where insurers are spending to reduce manual work and get products to customers faster.
NCFA's 2023 Canadian insurtech overview highlighted multi channel distribution, insurer partnerships and automation as important industry trends. Foxquilt is now commercializing several of those ideas through digital underwriting, broker distribution and embedded insurance in the U.S.
KPMG reports that 73% of insurance CEOs see AI as a top investment priority, while 67% expect returns within one to three years and plan to allocate 10% to 20% of technology budgets to AI. Canadian insurers are already applying those investments to underwriting, claims, distribution and customer service.
Canadian companies are selling into that demand in different ways. Quandri raised C$12 million to expand insurance automation across Canada and the U.S., while Manulife has cut eligible life insurance approvals to as little as two minutes using automated underwriting. Foxquilt is working on another part of the market by combining underwriting software, digital distribution and insurance products for small businesses.
The U.S. gives Foxquilt far more room to grow, but execution gets harder. Insurance approvals vary by state, underwriting still has to produce acceptable losses as volume rises, and agents or embedded partners can control much of the customer relationship. Adding products only helps if distributors use them and the business remains profitable.
Can Foxquilt turn one successful U.S. product into a durable multi product insurance business?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 1, 2026 | NCFA Market Activity + Insight | Lending Consumer Credit And BNPL, Digital Banking And BaaS, Competition And Market Structure
On September 1, 2026, Solifi acquired Inovatec Systems, a Vancouver company whose cloud software handles digital applications, loan origination and servicing for banks, credit unions, captive finance companies and specialty lenders across North America. Financial terms weren't disclosed. Inovatec brings more than 160 employees and 20 years of lending technology development into a much larger secured finance business.
For Inovatec, the sale provides the scale its founders say customers are demanding. For Solifi, it adds retail automotive, powersports and specialty lending capabilities to a platform already strong in equipment, wholesale, working capital and automotive finance. Canada gets another successful fintech commercialization event, while ownership and future capital decisions now sit with a global company under foreign private equity control.
The transaction arrives in a Canadian market where those outcomes are common. KPMG estimates that nearly half of Canadian acquisition targets across industries are bought by international firms. Canadian companies are active buyers abroad too, completing more than two thirds of their own transactions outside Canada. The question is whether Canada is producing enough companies that can keep scaling into global buyers themselves?
Vladimir and Danijela Kovacevic founded Inovatec in 2006 with two people. The platform now spans its Propel digital application portal, loan origination software and loan and lease servicing. It supports automotive, powersports, equipment and other consumer and commercial lending, with more than 70 third party integrations across its products.
The software reaches several workflows where lenders spend time and money. Applications can flow from consumers or dealers into credit decisioning and funding, while the servicing system handles payments, collections, customer service and asset recovery. Inovatec says lenders using its AI based funding automation have cut time spent manually reviewing documents by as much as 80%. That's a company reported customer result rather than an industry benchmark, but it shows the type of operating efficiency Solifi is buying.
Inovatec has also kept adding capabilities while expanding in the United States. In August, less than a month before the acquisition, it integrated Fortiro technology to detect altered and AI generated lending documents during origination. The company reports annual SOC 1, SOC 2 and SOC 3 audits along with ISO 27001 and ISO 27018 certifications, requirements that help lending software get through the security reviews of banks and other regulated customers.
The founders described the reason for selling in unusually direct terms. Customers want more products, channels and automation, and “meeting those needs requires scale.” Solifi gives Inovatec access to a much larger product portfolio, implementation organization and international customer base.
Solifi has dual headquarters in Minneapolis, United States, and Milton Keynes, United Kingdom, and sells software to banks, captive finance companies and independent lenders around the world. When TA Associates became its majority investor in October 2024, Solifi had more than 650 employees globally. Thoma Bravo, which had backed the company since 2019, kept a meaningful investment.
The ownership change came with an explicit acquisition plan. TA and Solifi said they intended to expand into adjacent finance markets and new countries through strategic acquisitions as well as internal growth.
That plan started producing deals. In September 2025, Solifi acquired DataScan, an Atlanta area company whose wholesale finance and inventory risk software serves more than 45 major banks and captive lenders. DataScan added floorplan lending, digital inventory audits and field inspection capabilities.
While DataScan strengthened the wholesale side of automotive finance. Inovatec adds the consumer application, credit, funding and servicing work that happens on the retail side. Solifi can now sell across more of the financing relationship instead of relying on separate products for each part.
That makes the Vancouver acquisition easier to understand. Solifi isn't simply adding another software company. Its private equity owners are funding a deliberate expansion across secured lending, and Inovatec brings technology and customer relationships that would take years to reproduce organically.
The timing fits Canada's current fintech market. KPMG counted US$996.7 million invested across 47 Canadian fintech deals in the first half of 2026. That was down more than 40% from US$1.7 billion across 82 deals a year earlier, while capital concentrated in companies with established scale, specialized technology and clearer economics.
KPMG partner Dubie Cunningham summarized what is attracting capital as “technology, customers, licences or regulated platforms that can accelerate expansion.” Inovatec fits that description closely. Solifi is buying working lending software, a North American customer base, integrations, regulated industry experience and a team that has spent two decades inside automotive and specialty finance.
Recent Canadian sales highlight various versions of the same commercial pattern. Fiserv bought Toronto based Payfare for C$4 per share, with the final acquisition covering roughly C$193.1 million of outstanding shares. Fiserv wanted Payfare's card program management, white label app and embedded finance capabilities. Payfare's situation included customer concentration and financial pressure before the sale, so it isn't a direct parallel to Inovatec.
Robinhood acquired WonderFi for about C$250 million for a different reason. WonderFi's Bitbuy and Coinsquare platforms brought roughly 300,000 funded customers at closing and regulated Canadian crypto access. Robinhood used the acquisition to enter Canada rather than spending years building that position itself.
European payments company Paynt used its 2025 acquisition of Vancouver based E-xact Transactions to expand in North America. E-xact was processing more than C$3.5 billion annually across 50 million transactions, and Paynt made Vancouver a new operational hub. The transactions differ, but the assets being purchased are software, customers, transaction volume, licences, regulatory experience and local distribution.
Canada isn't simply selling companies while everyone else buys. KPMG's wider M&A data show Canadian firms conduct more than two thirds of their transactions outside the country. The domestic fintech market is also still financing independent growth. Nesto raised C$302 million in its 2026 Series E at a C$1.47 billion valuation, the largest Canadian fintech financing in KPMG's H1 data.
Selling to a larger company can be a good outcome. Founders and investors get paid, employees may get more resources, and Canadian technology can reach customers that would have been costly to win alone. The bigger concern is when Canada keeps building valuable fintechs but too few grow large enough to become global buyers themselves.
Solifi says customers will keep their existing products and support, and that it will continue investing in Inovatec's products. The founders also say clients will keep working with the same team. What Solifi hasn't said is whether Vancouver headcount will grow, where future product decisions will be made, or where new intellectual property will be developed. There is no evidence today of layoffs, office cuts or development work leaving Canada.
Canada's economic return will depend on more than where the shareholder register ends up. Inovatec found the scale it wanted by joining Solifi. Canada's fintech market becomes stronger when more companies can eventually provide that scale themselves.
How many Canadian fintechs can grow from attractive acquisition targets into global acquirers?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 1, 2026
Betting has been one of our favourite activities for centuries, with people eager to wager on what they predict will happen when dice are thrown, wheels are spun, and so on. For most of human history, it was an extremely low-tech activity that relied on everyone being in the same room. While those games still exist in much the same form, it’s become far easier to engage with them, thanks to the following key innovations.
A vastly wider range of games represents the biggest change in casinos since they went online. While casinos were always limited due to their physical space in the past, the switch to online sites allowed operators to greatly increase their collection of games. This began with the introduction of more classic games, such as roulette and blackjack, which were usually very similar to the traditional versions.
However, leading game developers have taken our favourites in new directions since then. The Sportaza online casino contains a huge variety of slots, such as Royal Coins by ELA Games, Chicken Road 2.0 by InOut, and 3 Million BC by Betsoft. These games take the tried and trusted slots mechanism from the past and add new themes. Features such as jackpots and bonus rounds have been added to create more varied gameplay too.
In terms of table games, the biggest change has been implemented through livestreaming technology, which allows casinos to host online games with live presentation. A group of 4K cameras is typically used to provide different camera angles that the player can choose from, giving a smooth, uninterrupted view of the action at all times. In some cases, augmented reality is added, meaning that the cards and chips on the screen move between digital and real life. The Google AR & VR page explains how these technologies fit together.
This has led to classic table games being reimagined with new features, such as multipliers and side bets. It’s also given us game shows including Candy Wheel, Football Thrill, and Robin the Fair. These games introduce giant wheels, slots rounds, and other types of props to let players place varied wagers in a live setting.
The integration of different types of betting on the same site has been another huge change in the way we gamble. Sports betting has always been about wagers placed before the action begins, which are then settled once the final result is known. When online sports betting began, it followed this same process. However, the work carried out to integrate live scores and updates onto the same sites as casinos has allowed sportsbooks to now provide live betting.
This means that fans can bet on games and events as they take place, predicting what happens next based on what they see happening at the time. This has fundamentally changed the way we place sports wagers.
It works through advanced APIs that integrate live event data. Automated risk engines look at the data and adjust the odds instantly to take into account the flow of the action. The other major change has come with the way that users can choose whether to cash out early. This can be done in those cases where a cashout price is shown during the game, so that users can decide whether it makes sense to accept that price or wait for the event to end.
Modern players don’t want to wait days or weeks for transfers to go through, which was one of the issues that held back the early online betting industry. Therefore, casinos now put their cashier experience as one of the most important parts of the overall site performance. This can be done thanks to the fact that several fintech innovations have helped make it a lot easier to move funds back and forth.
Digital wallets were among the earliest of the changes that were introduced to this sector, with the likes of Skrill and Neteller proving popular in North America. Canadians have also benefited from the introduction of Interac, which allows almost instant transfers to and from bank accounts. Interac is a decentralized interbank clearing network. In other countries, open banking allows users to easily move funds when they want to gamble.
The different types of innovation that have led to these changes have made it far easier for people to enjoy online gambling. As the industry carries on growing, we can expect to see more new technology and ideas being used. If you just want to spin some slots or put some chips on the blackjack table, the good news is that innovations in fintech and beyond make this super easy to do from your own home.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016