




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 18, 2026 | NCFA Fintech Market Activity | Payments And Market Infrastructure, SME Finance And Business Banking
On June 16, 2026, London based fintech SumUp launched in Canada, expanding into its 38th market and bringing another global merchant platform into a competitive Canadian small business payments sector.
Founded in 2012, SumUp says it serves more than 4 million businesses globally. What began as a mobile card acceptance provider has expanded into a broader merchant platform that includes payments, invoicing, point of sale software, online selling tools, business accounts, loyalty capabilities, and other services designed to help small businesses manage day to day operations.
Canada represents a significant SME opportunity. According to Innovation, Science and Economic Development Canada, the country had approximately 1.10 million employer businesses as of December 2024, including roughly 1.08 million small businesses. SumUp's launch targets that market with SumUp Go for in person card acceptance and Payment Links for remote payment collection.
Merchant payments have become one of the most valuable distribution channels in financial services.
Every transaction generates information about sales activity, customer demand, cash flow, seasonality, business growth, and operating performance. Companies that are closest to payment activity gain visibility into how a business actually operates. That information can support additional products and services ranging from invoicing and software to banking, lending, cash flow management, loyalty programs, and embedded finance.
As a result, competition is no longer limited to transaction processing fees. The larger opportunity is the business relationship itself.
Canada has already seen evidence of this shift. TD's merchant infrastructure partnership with Fiserv highlighted how financial institutions are rethinking merchant services strategies. Rather than treating payment acceptance as a standalone product, providers increasingly view merchant relationships as an entry point into broader financial and operational services.
SumUp enters Canada with meaningful scale. The company reported processing more than 1 billion transactions annually and previously raised €590 million at an €8 billion valuation. The company has also expanded by aquisitions including Goodtill, Tiller, and Fivestars as it broadened its merchant software and commerce capabilities.
In Canada, SumUp's initial offer includes transaction based pricing without monthly subscription fees. That positions the company against a market that includes banks, merchant acquirers, point of sale providers, and fintech competitors serving Canadian SMEs.
The competitive question is becoming increasingly clear. Businesses need payment acceptance. They also need software, reporting, reconciliation, invoicing, customer engagement, and access to capital. Providers that can combine those capabilities into a simple operating experience may be better positioned to deepen merchant relationships over time.
As payment providers expand into software, banking, lending, and business operations, will merchant payments become the primary gateway to the SME financial relationship?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Event contracts are evolving from niche prediction markets into a regulated market category. The strongest openings may not be operating the markets themselves, but building the integrity, settlement, intelligence, distribution and risk management systems required for the category to scale.
Prediction market and event contract estimates vary because some sources measure revenue, others measure trading volume, decentralized markets, regulated event contracts or broader forecasting activity. The range is wide, but the category appears large enough to support venture scale investigation.
Recent evidence points to a larger infrastructure thesis. Event contracts need systems for market integrity, settlement, probability intelligence, distribution access and enterprise risk use cases. The strongest opportunity may be the trusted operating layer that helps many venues, brokers and data users participate without each rebuilding the same controls.
CFTC event contract decisions, broker access, Canadian distribution, stablecoin settlement activity, sportsbook challenges, enterprise pilots and evidence that buyers will pay for specialized infrastructure.
Evidence now supports five venture paths. These are product directions inside the parent opportunity, not automatic child Opportunity Briefs.
Surveillance, disclosure and outcome disputes
Event contracts are beginning to face the same trust problems that traditional exchanges faced as participation increased. Disclosure concerns, promotion practices, insider information risks, sensitive event pricing and outcome disputes are appearing before common standards have formed.
The opportunity is to help operators manage trust. Potential buyers include exchanges, brokers, operators and compliance teams. The strongest products may focus on surveillance, audit trails, disclosure monitoring, conflict detection and dispute management.
Large exchange surveillance providers extend existing products into event contracts before specialist vendors establish a foothold.
Is the first buyer the operator, broker or compliance function? Is the pain severe enough to create budget now?
Funding, payout and stablecoin workflows
Settlement is becoming a core operating requirement. Stablecoin activity, payout workflows and always available market participation increase the need for reliable funding, custody, reconciliation and settlement rails.
This path may support transaction based revenue if event market activity grows. The challenge is competition from payment providers, stablecoin issuers, custodians and existing financial infrastructure firms.
Existing payment providers absorb most of the value before specialized event market tools gain adoption.
Can the product reduce settlement cost, risk or complexity enough to win budget from operators or brokers?
Forecast signals for investors and operators
Prediction markets can produce forward looking probability signals that traditional datasets often miss. Private market valuation odds, policy forecasts, economic expectations and event risk pricing are early examples.
This path is broader than a data feed. The opportunity is to package probabilities into intelligence products that help investors, enterprises, researchers and operators make decisions. Customers still need proof that the signals improve decisions enough to justify recurring spend.
Forecast signals fail to outperform existing indicators or cannot be packaged into trusted workflows.
Who pays for the signal, and can accuracy, timeliness or decision value be demonstrated over time?
Brokerage, wealth and retail access
Canadian retail distribution, wallet integrations, sports partnerships and operator relaunch activity show that event contracts are moving through channels that already have users, compliance obligations and product discovery workflows.
The opportunity is the access layer around event contracts: brokerage integrations, suitability controls, education, product limits, risk warnings, onboarding, reporting and venue connectivity.
Distribution remains locked inside a small number of large brokers, exchanges or wallet platforms that build the access layer themselves.
Can brokers or wealth platforms justify a specialized event contract access layer rather than relying on venue supplied tools?
Promotion, campaign and business exposure
Event contracts are beginning to appear in practical business settings, including promotion risk management and event exposure. This suggests a possible enterprise use case beyond retail speculation and market forecasting.
The opportunity is infrastructure that helps brands, agencies and enterprises model, cap, transfer or monitor event driven exposure. This remains earlier than the other paths, but it could become a repeatable category if more non financial buyers adopt event contracts for operational risk.
Enterprise use remains a novelty or occasional hedge rather than a repeatable workflow with budget.
Which repeatable enterprise event risks are measurable, hedgeable and large enough to support a dedicated product?
Filter by signal type to review source records, early market signals and thought leadership supporting this opportunity. Evidence is sorted newest to oldest.
Share your perspective, research, case study or video response. You can also express interest in future discussions, collaboration opportunities and innovation activities related to this topic.
Learn how NCFA identifies, validates and tracks innovation opportunities →NCFA Opportunity Intelligence tracks emerging venture opportunities using evidence, market developments and validation signals. Opportunity briefs are updated as new information, evidence and stakeholder perspectives become available. This content is provided for information purposes only and does not constitute legal, investment, financial, tax or professional advice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 15, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Payments And Market Infrastructure, SME Finance And Business Banking
On June 15, 2026, Montreal based Nuvei announced a definitive agreement to acquire Payoneer for approximately $2.75 billion ($7.40 per Payoneer share in cash). The companies expect the transaction to close in mid 2027, after Payoneer shareholder approval, regulatory approvals, and other closing conditions.
If completed, the combined company expects about $3 billion in annual revenue. It also expects to process more than $500 billion in annual payment volume and serve over 2.4 million customers across more than 190 countries and territories.
While the price tag will certainly get some attention. The stronger story is what Nuvei is buying. Payoneer brings cross border payouts, multi currency accounts, marketplace reach, banking connectivity, regulatory approvals, and access to businesses that operate globally every day.
Payment processing is only one part of global commerce. Businesses also need to collect funds, hold balances, convert currencies, pay suppliers, settle marketplace earnings, and manage funds across borders.
Payoneer has spent two decades building that infrastructure. Its customers operate across Amazon, Walmart, Airbnb, Fiverr, Etsy, Upwork, Shopify, WooCommerce, eBay, ByteDance, and other global platforms. These businesses don't just need checkout tools. They need financial rails that help them operate in multiple currencies and jurisdictions.
Payoneer also brings regulated market access. The announcement highlights online payment licensing in mainland China and authorization in principle as a cross border payment aggregator in India under the Reserve Bank of India framework. That kind of access is tough to replicate. It takes capital, local knowledge, compliance depth, and time.
Nuvei connects businesses to local acquiring, alternative payment methods, risk tools, fraud management, and merchant services. Payoneer is closer to the operating side of international commerce. It helps businesses receive earnings, manage currencies, send payouts, and use global banking networks.
Together, the companies can cover more of the financial workflow. A merchant may start with payment acceptance. Then it may need supplier payments, foreign exchange, treasury tools, card issuance, marketplace settlements, or embedded financial services.
A provider that manages more of the money flow earns a stronger role in daily operations, otherwise a payment processor alone may just lose a merchant at renewal.
The expected combined scale gives Nuvei a larger role in global commerce infrastructure. It also puts the company in a different competitive conversation.
Nuvei is no longer competing only as a payments processor. It's trying to become a broader platform for acceptance, payouts, settlement, treasury, FX, and embedded finance. Merchants and platforms increasingly want fewer providers handling more of their financial operations. They want simpler workflows, cleaner reconciliation, faster settlement, and stronger compliance across markets.
That matters because every additional financial provider adds complexity. Merchants must reconcile transactions across multiple systems, manage separate compliance requirements, monitor third party risk, and track funds moving through different settlement networks. As Canadian payment rules place more weight on payment service provider operational risk and incident response rules, businesses have greater incentive to reduce handoffs and work with providers that can handle more of the process inside one platform.
For Canada's fintech ecosystem, the deal shows where value often forms behind the scenes. Some of the most important fintech companies are not consumer brands. They are infrastructure firms embedded behind marketplaces, exporters, software platforms, and global merchants. The acquisition also fits the larger opportunity in NCFA's Financial Innovation Map, where payments, data, digital assets, capital markets, and financial infrastructure are becoming more connected.
As payments, payouts, treasury services, FX, and embedded finance come together, will businesses keep using separate financial providers or choose platforms that manage the full flow of money across borders?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 15, 2026
Image: Unsplash/Sasun Bughdaryan
More and more Canadians are no longer leaving the business of cross-border acquisitions to institutional investors, and they are increasingly relying on technology to simplify international purchases. Whether accessing real estate market data and analyses or taking a virtual walk through properties, the evolution of PropTech has significantly altered how investors can scout, assess, and acquire assets abroad.
The appeal is evident: Investors can browse neighborhoods, compare yields, and contact service providers from their own homes, without needing to travel. Technology has helped overcome many of the conventional barriers of purchasing overseas real estate.
However, technology is only one component of the equation, and the key to making the right decision still lies with a deeper understanding of the market and local expertise.
There are a number of things that make America attractive. Firstly is scale: you have thousands of cities, many with their own driving forces, their own pricing structure, and rental possibilities. Secondly, many areas in the US have an entry price point that is lower than in the large Canadian metro cities; diversified investors can find regions that offer higher cash flow potential and a wider array of inventory to choose from.
Thirdly is the diversity of the economies, so in one city there could be employment growth from the medical field, another from technology, and another from tourism: these provide diversification across sectors, reducing concentration of risk.
Fourth is movement of currency; at various times favorable exchange rates can make buying opportunistic in US real estate and encourage purchasing. Fifth and perhaps most importantly, many investors recognize US property for long-term wealth accumulation as well as supplementing their existing real estate holdings in Canada.
PropTech has dramatically changed the way that investing is performed. Researching a foreign market used to involve many trips and scarce data points.
Digital platforms now allow immediate viewing of market statistics, population reports, rental data, and transaction records. This allows investors to view options from home and pre-qualify their search before proceeding. AI allows investors to take advantage of predictors that indicate growing jobs, rental rates, and infrastructure developments. Electronic document systems further streamline transaction processes by allowing contracts, disclosures, and loan documents to be viewed and electronically signed.
Virtual property tours enhance accessibility and allow buyers to view a property and area without actually going there. PropTech has given Canadians an experience with investing in American property that can now be performed more quickly and knowledgeably than ever before.
Image: Unsplash/Jakub Żerdzicki
Property intelligence – Data is quickly becoming one of real estate’s most prized assets. Canadian buyers are reviewing population migration trends, job numbers, school scores, and investment in infrastructure before choosing where to buy. There are fewer assumptions and more calculations involved. Rental performance indicators offer data to gauge anticipated occupancies, average rents, and overall income for a property.
Many also follow the number of building permits issued as a predictor of market confidence or for the impact that a build may have on supply. Statistics surrounding migration give further data points for regions experiencing an influx from those new to the workforce or in retirement.
News about business expansion, road improvements, or the number of crimes are all part of the picture. This approach eliminates the assumptions—there's a data-driven reason to consider some markets over others before other investors catch on.
We have a powerful arsenal of technology. Technology alone will not replace ground-level knowledge, though. As Jeff Tricoli, the prominent Southeast Florida real estate broker, puts it:
"I believe real estate is built on clarity, trust, and education. We guide clients with market insight. So every decision is informed and not speculative in manner."
However, technology cannot solve all issues. Cross-border taxation, for instance, is still a thorny subject. Investors need to be able to familiarize themselves with disclosure rules, ownership, and potential liability in two different countries.
Financing can also be tricky. Banks lend at different rates and have different criteria, and one might not be able to get good terms without more extensive paperwork. The law varies by state. Each has its own set of laws regarding what a landlord may and may not do, how to evict, and what must be disclosed to the tenant. Another problem has to do with interpreting data. The internet can flood you with information, but if you don’t interpret it correctly, you may end up making a mistake.
The market is another quick-changing variable. One that appears robust today might not be tomorrow if some new economic trend or government action destabilizes it. Ultimately, human acumen is still important. Networks of local experts—lawyers, accountants, brokers, and the like—still matter for a successful deal. Technology, in the absence of it, is certainly not a replacement for diligent investigation.
It is also reasonable to assume that PropTech will continue to evolve and exert influence. The predictive capabilities of artificial intelligence could be enhanced in such a way that investors know which neighborhoods will perform best. They will also happen to be the neighborhoods that will be in most demand in the future.
The use of blockchain will undoubtedly streamline transactions, as well as increase security with records. It is likely that data will also be more thoroughly integrated. Investors could be provided with a suite of not only market analysis tools but also financing, legal advice, and property management information.
Interest from Canadians remains strong because the United States offers size, variety, and scope for portfolio growth.
Proptech has changed the way investors look at cross-border transactions. Data analytics, virtual tours, prediction technology, and online platforms allow for easy research and access to investments.
However, tech is not a total substitute for local experience and knowledge. Legal, tax, financing, and neighborhood issues require local input. Hope this read helped you and best of luck on your journey in this way.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 14, 2026
Family-owned businesses across Canada offer a strong opportunity for entrepreneurs because many are already profitable, trusted locally, and ready for ownership transition. Instead of starting from zero, buyers can acquire an established business with customers, staff, systems, and reputation already in place, especially as more owners consider retirement or succession.
Family-owned businesses play an important role in Canada’s economy. They often operate in local communities for years or even decades, serving loyal customers and building strong reputations through consistent service and personal relationships. Many are owner-operated businesses where trust, reliability, and long-term commitment matter just as much as the products or services they provide.
For buyers, this creates a significant advantage. A family-owned company in Canada may already have an established customer base, experienced employees, dependable supplier relationships, equipment, and stable revenue. It may also benefit from a recognizable local brand and years of goodwill within the community. These are valuable assets that usually take considerable time and investment to develop from scratch.
For entrepreneurs researching acquisition opportunities, Canadian business for sale on Yescapo can be a useful starting point for finding established companies with existing operations, customer relationships, and market history. Instead of buying only physical assets, buyers gain access to business knowledge, working systems, and relationships that have often been built over generations.
This is particularly important in industries where reputation drives success. Local retailers, construction companies, restaurants, service providers, and manufacturing businesses often rely on repeat customers and word-of-mouth referrals. A well-established family business may therefore offer a competitive position that would be difficult and expensive for a new startup to achieve.
One of the biggest opportunities in Canadian family businesses comes from succession. Thousands of owners are approaching retirement after spending decades building successful companies, yet many do not have family members interested in continuing the business. Children may choose different careers, relocate, or simply prefer not to take on the responsibilities of ownership.
As a result, many profitable businesses enter the market despite having healthy financial performance and loyal customers. They are being sold not because they are struggling, but because the owner wants to retire, reduce day-to-day responsibilities, or ensure the company continues under new leadership.
For entrepreneurs, this creates a unique entry point into business ownership in Canada. Buying a family-owned business with established operations can provide immediate access to customers, revenue, trained staff, and existing systems while avoiding many of the challenges involved in launching a company from zero.
Understanding the seller’s motivation is an important part of the process. In succession transactions, owners often care deeply about preserving the company’s reputation, protecting employees, and maintaining relationships with long-standing customers and suppliers. Buyers who respect that legacy and present a clear plan for the future may find it easier to negotiate a successful acquisition and ensure a smoother transition after the sale.
Starting a new company usually means building everything from the ground up. The founder must test demand, find customers, create systems, hire staff, develop supplier relationships, and survive the early stage when cash flow is uncertain.
Buying a family business in Canada offers a different path. The buyer can study real financial records, customer history, contracts, equipment, employee structure, and market position before making a decision. This makes the process more practical and less based on assumptions.
A startup may offer full creative freedom, but it also carries higher uncertainty. A family business may come with older systems or traditional ways of working, but it also provides an existing customer base and proven business model.
For many buyers, the question is simple: why build market trust from zero when an established business for sale in Canada may already have it?
Family businesses are often attractive because they are built around long-term relationships. Many have repeat customers, local recognition, supplier trust, and employees who understand the business well. This can make the transition easier for a new owner.
Another advantage is stability. Many Canadian family businesses operate in practical sectors such as trades, retail, food, manufacturing, distribution, professional services, hospitality, and local services. These businesses often solve everyday needs rather than depend on trends.
A buyer may also find hidden growth potential. Some family businesses are profitable but underdeveloped digitally. They may have weak websites, limited social media, no online booking, outdated branding, or little paid advertising. A new owner can modernize the business without changing its core.
This is why many investors search for profitable businesses for sale Canada listings. They want companies that already work, but still have room to grow.
Family-owned businesses can be found across many industries and provinces. Some operate in large cities such as Toronto, Vancouver, Calgary, Montreal, and Ottawa. Others are based in smaller communities where local trust is especially important.
Common examples include restaurants, cafés, bakeries, convenience stores for sale, construction companies, repair shops, cleaning businesses, accounting firms, dental or wellness clinics, manufacturing companies, logistics businesses, landscaping companies, and specialty retail stores.
Buyers often look for businesses that are simple to understand and have steady demand. A local business for sale Canada opportunity may be attractive if it has repeat customers, reliable employees, clean financial records, and clear room for improvement.
Businesses with recurring revenue can be especially valuable. Examples include maintenance companies, B2B services, subscription-based services, commercial cleaning, bookkeeping, and companies with long-term contracts.
Retiring business owners are one of the main reasons family business transition is becoming important in Canada. Many owners have strong companies but no clear successor. They may be ready to step back, but they do not want the business to disappear.
This can create a more flexible acquisition process. Some sellers may agree to stay involved during a transition period, introduce the buyer to customers and suppliers, and train the new owner. This helps protect business continuity.
For buyers, this is valuable because the seller’s knowledge is often one of the most important assets in a family business. Understanding customer relationships, staff dynamics, supplier terms, and daily operations can reduce risk after the sale.
A good transition plan can make the difference between a smooth acquisition and a difficult one. The best deals usually include clear handover support, communication with employees, and a plan for preserving customer trust.
Before buying a family-owned business, due diligence is essential. The buyer should review financial statements, tax records, revenue trends, profit margins, debts, leases, supplier agreements, employee contracts, equipment, inventory, licences, customer concentration, and legal issues.
It is also important to understand how dependent the business is on the current owner. Some family businesses rely heavily on the founder’s personal relationships. If customers only trust the owner, revenue may fall after the sale unless the transition is handled carefully.
A buyer should also check whether family members work in the business and what will happen after the acquisition. Staff roles, responsibilities, salaries, and expectations should be clear before the deal is completed.
Buying an established business in Canada can be a strong opportunity, but only if the buyer understands the real numbers, the risks, and the operational structure.
Many family businesses have strong foundations but outdated systems. A new owner can often grow the company by improving marketing, technology, pricing, customer service, and operations.
For example, a local service company may have loyal customers but no strong online presence. A buyer could improve the website, SEO, Google Business Profile, paid ads, online reviews, and booking systems. These changes can increase leads without changing the core service.
A retail business might benefit from e-commerce, better inventory management, updated branding, or stronger social media. A B2B company could grow by improving sales processes, customer follow-up, and recurring contracts.
The opportunity is not always about changing the business completely. Often, it is about keeping what works and modernizing what holds the company back.
Many buyers assume they need the full purchase price in cash, but business acquisition Canada deals can be structured in several ways. Buyers may use personal savings, bank financing, investor capital, seller financing, or a combination of these.
Seller financing can be especially relevant in family business succession. This means the seller allows the buyer to pay part of the price over time. It may help the buyer complete the deal and give the seller confidence that the new owner is committed to the business.
Some deals also include an earn-out, where part of the final payment depends on future performance. This can be useful when the seller and buyer need to bridge a valuation gap.
Clean financial records make financing easier. A profitable small business Canada opportunity with strong documentation is usually more attractive to lenders and investors than a business with unclear accounts.
Family businesses can be excellent acquisitions, but they are not risk-free. Some may have outdated systems, informal agreements, weak financial reporting, or operations that depend too much on the founder.
There may also be emotional complexity. A family business is often personal to the seller. Decisions about employees, branding, customers, and legacy may matter deeply. Buyers need to handle the process with respect and clarity.
Another risk is hidden underinvestment. Some owners delay upgrades before selling. Equipment, premises, technology, or staffing may need improvement after acquisition. Buyers should factor these costs into the purchase price.
The best approach is practical: verify the numbers, understand the people, check the contracts, and plan the transition carefully.
Buying a family-owned business in Canada can be a strong strategy for entrepreneurs who want an established company rather than a startup. It offers access to customers, revenue, staff, systems, and local reputation from the beginning.
This strategy is especially attractive for buyers who are good at operations, marketing, modernization, and relationship management. They can take a business that already works and make it stronger.
However, it is not the right path for everyone. Buyers need patience, due diligence, capital, and the ability to manage people and change. A family business may be established, but it still needs leadership.
For the right buyer, Canadian family businesses can offer one of the most practical routes into entrepreneurship through acquisition.
The hidden opportunity in family-owned businesses across Canada lies in the gap between retiring owners and entrepreneurs looking for established companies. Many of these businesses have customers, revenue, employees, reputation, and operational history already in place.
Instead of starting from zero, buyers can acquire a profitable local company and improve it through better marketing, stronger systems, digital tools, and modern management. The opportunity is not only to buy a business, but to continue its legacy and unlock its next stage of growth.
For entrepreneurs searching for Canadian business opportunities, family-owned businesses may be one of the most overlooked paths to ownership.
They often have loyal customers, local reputation, proven operations, trained employees, and steady revenue. This gives buyers a stronger starting point than launching a new company.
Business succession is the process of transferring ownership from the current owner to a new owner. In family businesses, this often happens when the founder retires or no family member wants to take over.
Buying can be better if the buyer wants existing customers, cash flow, and a proven business model. Starting may be better for someone with a unique idea or limited acquisition capital.
You should check financial records, tax documents, debts, leases, supplier agreements, employee contracts, customer concentration, licences, equipment, and how dependent the business is on the current owner.
Yes. Buyers may use personal funds, bank loans, investor capital, seller financing, or earn-out structures. Clean financial records usually make financing easier.
Common examples include restaurants, cafés, retail stores, construction companies, cleaning businesses, clinics, manufacturing companies, repair shops, logistics businesses, and local service companies.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 12, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, Lending Consumer Credit And BNPL
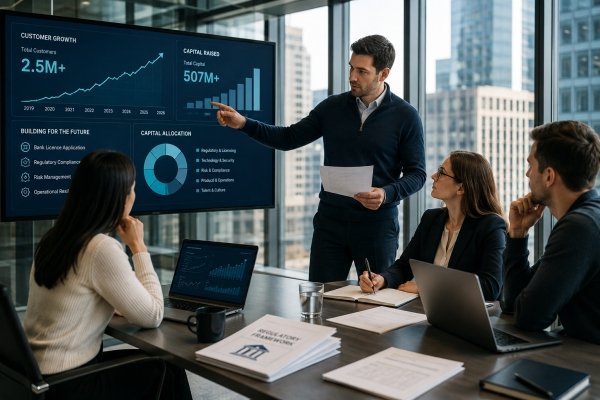
On June 11, 2026, KOHO announced a $130 million CAD financing at a $1.33 billion CAD valuation. KOHO says the capital will support growth and provide the initial capital base for a federally regulated bank, subject to ministerial approval. The round includes new investors Mubadala, Savano Capital, Shopify founder Tobi Lütke, and Affirm COO Michael Linford, with participation from Portage Ventures, Drive Capital, BDC Capital, HOOPP, and Eldridge. KOHO says it has raised $507 million CAD since launch and lists more than 2.5 million customers.
KOHO previously said it entered the second phase of acquiring a Canadian banking licence in January 2024, after raising an $86 million extension at an $800 million valuation and surpassing 1 million users.
The numbers have changed since that earlier milestone, but approval remains a federal decision. KOHO has added customer reach, capital base, and product depth behind its application. A bank licence requires proof of customer demand, not just capital strength, governance, risk controls, compliance systems, consumer protection, and trust. KOHO is trying to cross that line while still competing as a consumer fintech.
KOHO's round lands as OSFI prepares to launch a more defined path for targeted new entrants in June 2026. OSFI fast track approval framework analysis explains why the change is important for fintechs, challenger banks, and other firms with innovative banking models.
While the framework doesn't make approval easy, it offers eligible applicants a clearer route through the federal process while preserving prudential oversight. For fintechs, that is useful because demand for a product is not enough. A bank licence requires capital, governance, risk controls, compliance systems, consumer protection, and trust.
Questbank gives the KOHO story a recent Canadian benchmark. In November 2025, Questbank received approval to operate as a Schedule I bank after a six year approval process. KOHO is pursuing a different strategy, but the approval highlights that new federally regulated banking entrants can still emerge in Canada. That goes for international banking groups too like Santander who was approved by OSFI for a Canadian Banking License in 2025, after waiting for 6 years.
KOHO's financing follows two other large Canadian fintech disclosures. Wealthsimple raised C$750 million at a C$10 billion valuation in October 2025. nesto announced a C$302 million Series E at a C$1.47 billion valuation on June 10, 2026. KOHO followed one day later with a C$1.33 billion valuation.
Wealthsimple is pushing further into personal finance and banking style products. nesto is scaling mortgage and lending infrastructure. KOHO is putting new capital behind a federal bank licence effort. The same funding cycle is reaching different parts of financial services.
Customer growth and venture funding helped create Canada's latest generation of fintech firms. The next evolutionary question is whether firms that already have users and capital can obtain the regulatory permissions needed to participate more directly in deposits, lending, payments, and other core financial services.
KOHO has more than 2.5 million customers, a $1.33 billion valuation, and fresh capital earmarked for its bank licence effort. If customer scale and funding are no longer the hardest milestones, is regulated banking capacity now the real test for Canadian fintech competition?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 11, 2026 | NCFA Story Intelligence | Payments And Market Infrastructure
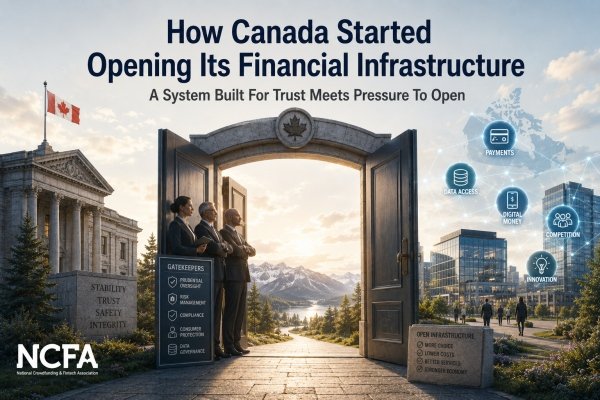
On June 3, 2026, Payments Canada announced that 15 organizations had joined its membership in 2026 following expanded eligibility rules. The latest intake included Beem Credit Union, Ebury Partners Canada, Shaype, Libro Credit Union, and Newton. Earlier additions included Wise Payments Canada, Float, KOHO, Neo Financial, Paramount Commerce, Brim, Meridian Credit Union, Tru Cooperative Bank, DoBusiness.com, and other newly eligible participants.
The membership announcement is the latest chapter, not the whole story. The story is how Canada moves from a tightly controlled payments model toward wider participation in the infrastructure that moves money, shapes competition, influences product design, and affects the choices available to consumers and businesses.
Canada builds its payments foundation around safety and trust.1 The Canadian Payments Association is created in 1980 under what is now the Canadian Payments Act. Payments Canada now owns and operates national payment systems including Lynx and the Automated Clearing Settlement System. The design reflects a clear priority: money movement is critical infrastructure, and critical infrastructure has to be reliable.
For a long time, that model works well enough for most people. Consumers trust their banks. Businesses use established payment tools. Settlement happens in the background. Most Canadians never need to think about who has direct access to the rails because the system mostly shows up as cards, transfers, bill payments, payroll, and cheques.
The market changes faster than the rails. Digital commerce grows. Mobile payments spread. Online transfers become a daily habit. Payments Canada’s 2025 trends report says Canada processed 22.5 billion retail payment transactions worth $12.2 trillion in 2024, with digital payments representing 86% of transaction volume.2
Fintechs start building around systems they can’t fully access. KOHO, Neo Financial, Float, Wise Payments Canada, Paramount Commerce, Brim, and Newton grow because customers want simpler financial products. The problem isn’t demand. The problem is that many new firms still depend on infrastructure controlled by others.
Competition becomes the pressure point. Critics of Canada’s payments model argue that control by a small number of large institutions has contributed to high fees, delay, and limited competition. Reuters reported this criticism when the Bank of Canada began payment service provider registration under the Retail Payment Activities Act.3
The fintech argument becomes practical. If firms outside the largest banks can’t connect on fair terms, they often need intermediaries, workarounds, sponsorship relationships, or slower product paths. That affects costs, margins, speed to market, and the ability to challenge incumbents with better consumer and business experiences.
Ottawa starts changing the legal frame. Finance Canada says amendments to the Canadian Payments Act made on June 20, 2024 expand Payments Canada membership eligibility to Bank of Canada supervised payment service providers, credit union locals that are part of a credit union central, and designated clearing and settlement system operators.4
The Bank of Canada brings PSPs into supervision. Under the Retail Payment Activities Act, the Bank registers and supervises payment service providers and focuses on operational risk, incident response, safeguarding end user funds, and reporting. As of September 8, 2025, PSPs must have risk management and funds safeguarding frameworks in place.5
Real Time Rail becomes the execution test. Payments Canada says the Real Time Rail is planned for launch in Q4 2026 and will support instant, data rich payments through a new exchange, clearing, and settlement system.6 The promise is simple: money should move faster, carry better data, and support new products.
The delays create frustration because the opportunity is real. Payments Canada selected Interac as the exchange solution provider in 2021, when the system was expected to launch in 2022.7 NCFA has tracked the execution question through RTR delay coverage and RTR productivity analysis.
The first wave of PSP members makes the policy visible. Payments Canada welcomes Wise Payments Canada, Float, KOHO, Paramount Commerce, and Brim as new payment service provider members in January 2026.8 NCFA tracks that moment when Payments Canada admits five new PSPs.
Membership is not only about access to rails. Payments Canada’s by law changes update membership requirements and support new eligible members as Canadian Payments Act amendments come into force.11 Membership gives new firms a closer role in the rules, standards, and modernization discussions that shape the system.
That changes the politics of infrastructure. A fintech that has to build around the system is one kind of participant. A fintech that can join, comply, learn the rules, and contribute to modernization discussions is another. The same applies to credit unions, FX firms, and other payment providers that want a role in Canada’s next financial infrastructure chapter.
Consumer driven banking brings the same access debate to financial data. Finance Canada says the framework is meant to let Canadians securely access and share financial data with financial service providers, without fees for accessing and sharing that data, while reducing reliance on risky practices such as screen scraping.12 The Bank of Canada says it will administer the framework so Canadians and businesses can securely share financial data with approved providers of their choice.13
But the friction does not disappear just because the law changes. Tier one banks, fintechs, data aggregators, and policymakers still have to work through scope, liability, accreditation, implementation timelines, commercial terms, and API performance. NCFA’s open banking commercialization roadmap frames the next phase as real API usage, accreditation, liability, and business model design, not just a policy announcement.
Stablecoins pull the payments debate into digital money. Bill C 15 gives Canada a legal framework for stablecoins and consumer driven banking, moving both into the financial policy stack. NCFA framed that moment in Bill C 15 gives Canada a digital finance framework.
The payment infrastructure question is no longer only about bank rails. Stablecoins, payment service providers, RTR, consumer driven banking, and Bank of Canada oversight are starting to occupy the same policy conversation. NCFA’s question post on stablecoins as payment infrastructure shows why digital money now belongs in the same access debate.
Canada’s payments story now connects directly to productivity. The Bank of Canada has warned that weak productivity threatens living standards, and NCFA has linked payments modernization to execution, competitiveness, and growth. Faster settlement, better data, lower friction, and more competition are not abstract infrastructure benefits. They affect how firms operate every day.
Cross border capability becomes part of the same test. Canada’s payment system cannot only work well at home. Canadian businesses, newcomers, exporters, marketplaces, and financial platforms also need better global money movement. That is why NCFA’s cross border payments analysis belongs beside RTR, open banking, and stablecoins.
Canada’s payments infrastructure didn’t turn a corner overnight. The change reflects years of modernization work, policy debate, fintech pressure, consumer demand, and the practical reality that a digital economy needs payment systems that are safe, fast, open enough to compete, and trusted enough to scale. The result is a more diverse payments membership base than Canada had a decade ago, with fintechs, PSPs, credit unions, FX firms, and digital finance companies gaining a larger role in the systems that move money.
Opening access isn’t the finish line. It’s the starting point. Canadian fintechs, banks, credit unions, payment providers, regulators, and infrastructure operators now have to prove broader participation can become better financial services. Now is the time to get to work. Launch Real Time Rail, make consumer driven banking usable, widen the tent responsibly, improve domestic and cross border capability, lower friction for merchants and consumers, and connect these reforms to the Canadian Financial Innovation Map and pipeline Canada needs to compete.
Canada's infrastructure modernization is creating new commercial opportunities in Consumer Driven Banking. See NCFA's Open Banking in Canada Opportunity Brief for the evidence trail, product pathways, competitive benchmark and commercialization outlook.
Which part of Canada’s payments story stood out most to you?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016