




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Jun 9, 2026 | NCFA Resource | Capital Formation And Crowdfunding
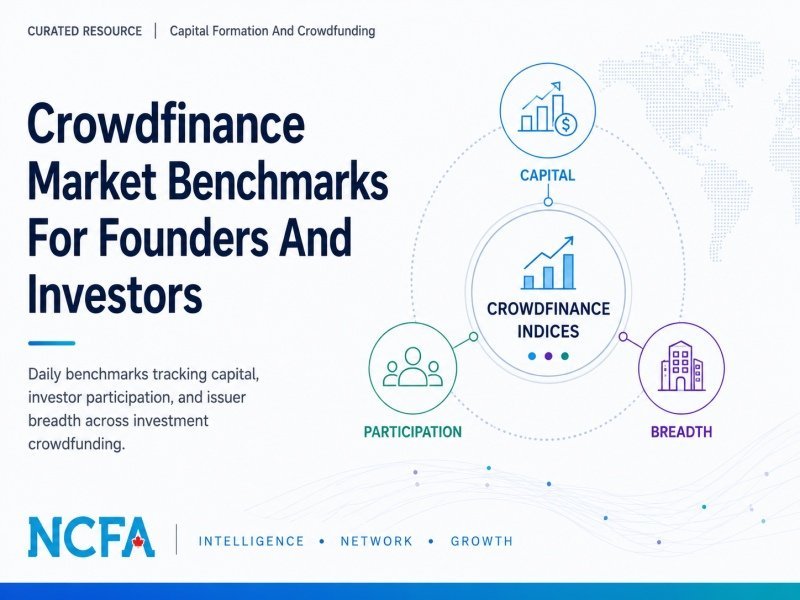
Crowdfund Capital Advisors launched the CCA Crowdfinance Indices, a family of daily benchmarks for the U.S. Regulation Crowdfunding market. The resource tracks more than dollars raised. It measures capital, investor participation, and issuer breadth so founders, investors, platforms, and policymakers can see whether market activity is broadening, concentrating, or cooling.
The data is U.S. specific, but the measurement framework travels. Canada and other jurisdictions can use the same lens to think more clearly about crowdfunding market health, capital access, investor activity, and whether opportunity reaches a wider base of companies.
The indices separate investment crowdfunding activity into three useful indicators.
That breakdown matters because capital raised alone can hide what is really happening. A market can show higher capital while fewer companies receive funding. It can also show more investor activity while average checks get smaller. CCA’s framework helps users see the drivers behind the headline number.
CCA says the indices draw from its CCLEAR data platform and cover activity across leading U.S. intermediaries. The dashboard also includes sector views across technology, healthcare and life sciences, food and beverage, consumer and retail, fintech and financial, energy and cleantech, and real estate and construction.
CCA reports that issuers tracked by the Composite have raised nearly $3.1B across more than 9,000 companies. That makes the index family useful as a market reference, not just a launch announcement.
This resource is useful for crowdfunding platforms, founders, angel investors, policy teams, researchers, ecosystem builders, securities regulators, funding portals, and capital formation advocates.
It is especially useful for anyone trying to understand whether investment crowdfunding is becoming a deeper market, a more concentrated market, or a broader channel for startup and small business finance.
The strength of this resource is its market structure lens. It turns crowdfunding activity into a more useful set of indicators. Capital shows money flow. Participation shows investor engagement. Breadth shows issuer access.
The limit is geography. The indices measure U.S. Reg CF activity. They don't measure Canadian crowdfunding activity or global crowdfunding flows. Canadian readers should use the resource as a benchmark for comparison and market design, not as a proxy for Canada.
That distinction makes the resource more valuable, not less. It shows what better market intelligence could look like in other jurisdictions where crowdfunding data remains fragmented, delayed, or hard to compare.
CCA Crowdfinance Indices Dashboard (primary dashboard)
Reg CF At 10 Shows Equity Crowdfunding Works (cap modernization context)
Fintech Fridays EP57: Equity Crowdfunding 10 Years After Jobs Act (investment crowdfunding history)
UK Crowdfunding Caps Lift As EU Pushes €12M (global cap comparison)
National Instrument 45-110 (Canadian startup crowdfunding rules)
SEC Regulation Crowdfunding (U.S. Reg CF overview)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 8, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization
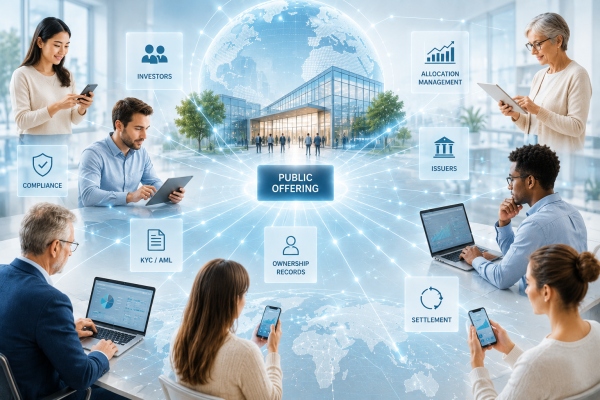
On June 7, 2026, Bybit launched IPO Express, a platform that gives eligible users access to tokenized IPO allocations starting with SpaceX. The launch arrives as SpaceX prepares for a public offering expected to value the company at approximately $1.75 trillion, making it potentially one of the largest IPOs ever. While the SpaceX name grabs attention, the bigger story is what this says about investor access, capital formation, and the growing role of digital infrastructure in public markets.
While the SpaceX name grabs attention, the bigger story is how firms are competing to expand investor access and improve IPO distribution.
Traditional IPO allocations typically flow through investment banks, brokerage firms, institutional investors, and private banking networks. Retail investors often participate only after public trading begins.
Bybit's model broadens access by allowing eligible users to subscribe through exchange infrastructure before trading starts. Investors can receive allocations and subsequently trade tokenized exposure through the platform.
The model combines several functions that have historically operated through separate systems, including investor onboarding, allocation management, compliance, custody, ownership records, and trading. Companies are now competing to modernize how investors access public offerings.
Much of the discussion around how tokenization is changing markets has focused on stocks, bonds, funds, real estate, and other assets after issuance. IPO Express focuses on an earlier stage of the investment lifecycle.
For decades, financial innovation concentrated around trading efficiency, lower transaction costs, and faster settlement. Tokenized IPO access targets a different challenge related to who gets access to investment opportunities in the first place.
Investor verification and eligibility checks now matter as much as trading access. So do allocation rules, ownership records, compliance controls, and settlement. Platforms that combine these functions in one clean workflow may earn an advantage as capital markets become more digital.
Canada has already seen similar efforts to expand investor participation through equity crowdfunding, online exempt market platforms, private market technology, and digital investment platforms.
Canada already has a live comparison point. Wealthsimple’s IPO Access for Canadian retail investors broadens access through a brokerage account, while Bybit’s IPO Express adds a tokenized layer around allocation and trading. Both are aiming to solve the same pressure in capital markets: retail investors want earlier access, cleaner digital onboarding, and a fairer shot at high demand offerings.
NCFA’s Who Gets Capital As Funding Channels Multiply? asks the same core question for Canadian markets. More channels don't automatically create better access for every founder or investor.
Tokenized IPO access brings the same access and onboarding pressure to public exchange listings. For Canada, the practical question is whether regulated platforms can use digital infrastructure to make capital raising easier without weakening disclosure, custody, suitability, or investor protection. That question fits NCFA’s financial innovation market infrastructure research, where access to capital, tokenization, compliance, and investor trust now overlap.
If retail investors can access high demand offerings through faster digital channels elsewhere, how long can domestic platforms rely on slower, relationship driven distribution models?
The competitive advantage may no longer come from who controls the allocation. It may come from who makes access easiest while still meeting regulatory requirements.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 8, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization
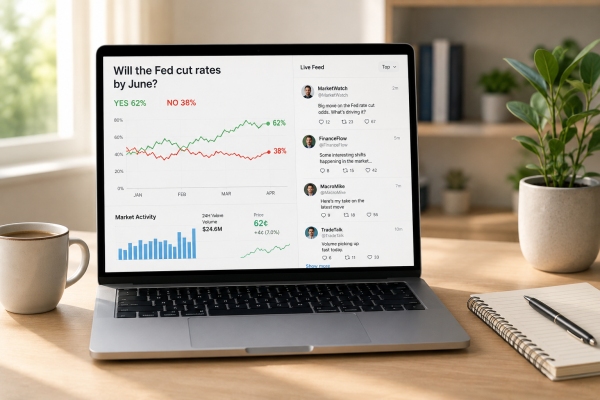
On June 5, 2026, Politico published an investigation into Polymarket's influencer marketing program. The report found that Polymarket chief marketing officer Matthew Modabber allegedly used a personal PayPal account to send at least $350,000 to content creators between January 2025 and February 2026. Politico's review identified over 490 social media posts promoting Polymarket that allegedly didn't clearly disclose paid relationships.
The investigation paints a picture far larger than a disclosure dispute. It's a rare look into how prediction markets are building distribution, visibility, and cultural relevance while simultaneously becoming one of the most discussed forecasting platforms in politics, sports, current events, and financial markets.
At least 20 creators identified by Politico promoted Polymarket after receiving payments. The report also found more than $2.5 million in transfers from the account to over 800 recipients during the period reviewed. Several influencers allegedly framed Polymarket odds as breaking news or authoritative indicators of future events. One creator told Politico that the company provided suggested post copy and encouraged promotion of specific markets.
The story reveals something many people inside fintech have quietly observed for years. Prediction markets are no longer simply markets. They are becoming media businesses.
Traditional exchanges compete for liquidity. Prediction markets increasingly compete for attention.
Polymarket's growth coincided with the 2024 U.S. election cycle, where billions of dollars flowed through election related contracts. Politico's reporting shows that influencer distribution became part of that growth strategy. The objective was not only attracting traders. It was turning Polymarket into a source people referenced when discussing politics, government decisions, sports outcomes, and breaking events.
The strategy appears to have worked. Today, prediction market odds regularly appear in mainstream media coverage. News organizations cite them. Social media users share screenshots of them. Investors discuss them. Politicians reference them. The market itself increasingly becomes part of the story.
It's a new category that's somewhere between financial infrastructure, media distribution, forecasting, and social networks.
The obvious asset is trading volume. The less obvious asset is trust. Many of the influencers highlighted in Politico's investigation promoted Polymarket as exceptionally accurate. Some described the platform as a superior forecasting mechanism compared to polling. Others highlighted successful market predictions as evidence of credibility.
This creates an unusual challenge. Prediction markets derive value from the perception that they aggregate independent information better than traditional alternatives. If users begin questioning how information reaches the market, who amplifies market narratives, or whether promotion and prediction are becoming intertwined, trust becomes harder to maintain.
The issue isn't whether influencer marketing is permitted. Many fintech companies use creators, affiliates, newsletters, podcasts, and social media personalities. The issue is whether users can clearly distinguish between market intelligence and paid amplification.
The most important opportunity may not be another prediction market. It's infrastructure that helps users understand how market information forms, spreads, and gains credibility.
As prediction markets, AI systems, social media platforms, and financial products become more connected, users need better ways to answer practical questions.
The next generation of prediction market innovation opportunities may come from building verification, disclosure, provenance, surveillance, and transparency tools around these markets.
These capabilities are still early. As prediction markets expand into politics, sports, finance, and public policy, demand for trust infrastructure should grow with them.
The Politico investigation focuses on influencer payments, disclosure practices, and marketing tactics, but the larger takeaway is that prediction markets are evolving beyond trading venues. They're becoming information platforms. That evolution creates opportunity, but it also creates responsibility. Today, Reuters posted about predication markets facing rising scrutiny over insider trading controls, reinforcing that these markets need trust infrastructure around promotion, surveillance, suspicious trading, and market transparency.
Markets that increasingly influence public understanding of events will face greater scrutiny over how information enters the system, how narratives spread, and how trust is earned. The next competitive opportunity may be proving that market intelligence can be trusted.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 8, 2026
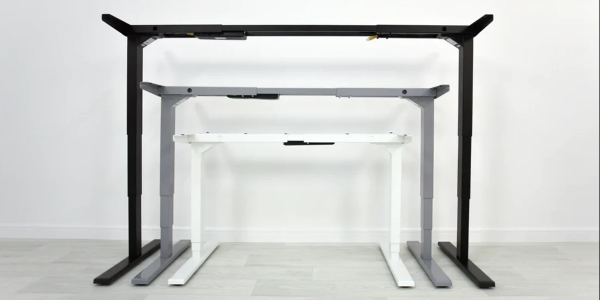
Building your own standing desk is one of those projects that seems more complicated than it is. The frame does the mechanical work. The desktop is just a surface. Put the right two together and you end up with a custom sit-stand desk that fits your exact dimensions, matches your workspace aesthetic, and costs less than most comparable products bought as a complete unit.
The frame decision is where most of the thinking needs to happen. Get that right and the rest of the project is straightforward.
Commercial standing desks come in a limited range of widths, depths, and surface materials. If your space is non-standard, if you want a specific wood species, a particular thickness, a reclaimed material, or dimensions that don't match what's on the market, building your own is the practical route.
The cost argument is also real. A quality motorised frame without a top is considerably less expensive than the same frame sold as a complete desk with a manufacturer's surface. If you already have a desktop you want to keep, or you're sourcing a slab of solid wood, the frame-only route saves money while improving the result.
Control over the finished product is the third reason. You know what you're getting: a specific frame with specific specifications, paired with a surface you chose rather than what was available in the product line.
Single-leg frames are compact and suited to smaller desktop sizes, typically up to around 120cm wide. The single column limits the maximum stable width but keeps the footprint minimal. For a compact home office setup or a secondary workstation, this configuration works well and costs less than a full two-leg frame.
Two-leg frames are the standard for most desktop sizes. Two columns, one at each end of the desk, provide stability across a wider span. Most two-leg frames accommodate desktops roughly between 100cm and 180cm wide, though the exact range varies by manufacturer. For a main workstation with multiple monitors and full equipment, this is typically the right starting point.
Three-leg and corner configurations support L-shaped or very large surfaces. These are more complex mechanically and more expensive, but they solve the stability problem that arises when a single straight frame is asked to support an unusually wide or non-rectangular top.
Motor configuration is the starting point. A single motor driving both columns through a crossbar is the entry-level approach. It works but introduces some flex between the columns during adjustment on wider desktops. Dual motors, one in each column, driven synchronously by the controller, produce more stability and more even lifting force distribution. For a desktop wider than about 140cm, or for anyone who wants the desk to feel genuinely solid at standing height, dual motors are worth the additional cost.
Height range needs to accommodate both the seated and standing positions of the person using it. The seated position is more constrained by the chair height and the working ergonomics. The standing position needs to allow the keyboard to sit at a height where elbows are roughly at 90 degrees while standing. Most people need a standing height somewhere between 100cm and 120cm. Check the frame's maximum extension against this requirement, and check the minimum against your preferred seated height, before buying.
Weight capacity for the standing desk frame needs to account for the combined weight of the desktop surface and everything on it. A solid wood slab can be heavy. Two monitors, a laptop dock, and accessories add up. Frames rated comfortably above the actual loaded weight will be more stable and last longer than those running near their limit.
Stroke speed affects the experience of using the desk in practice. A frame that adjusts at a reasonable pace, roughly 25 to 40mm per second, feels purposeful without being abrupt. Very slow frames make adjustment feel effortful. Very fast frames can feel slightly aggressive. Most quality frames in the mid-market land in a speed range that works well for daily use.
Controller quality is consistently the underspecified element. A controller with memory presets, the ability to save specific sitting and standing heights and return to them with a single button press, changes whether the desk gets adjusted regularly or sits at one height indefinitely. Manual height finding every time introduces just enough friction that most people stop bothering. Presets remove that friction entirely. This is worth specifying rather than accepting whatever comes with the cheapest frame option.
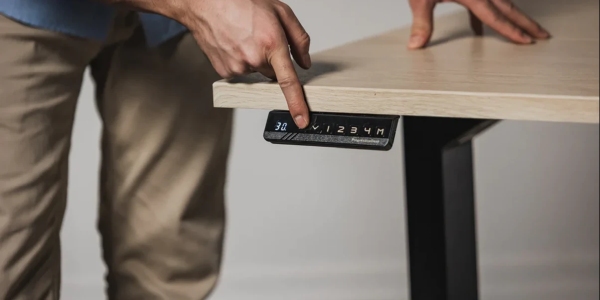
The frame's desktop compatibility specification typically gives a minimum and maximum width and depth range. The desktop needs to fit within this range for the frame to support it correctly.
Thickness matters for the mounting hardware. Most frame cross-beams use bolts that pass up through the frame into the desktop from below. A desktop that's too thin won't provide enough material for the bolts to grip. A desktop that's too thick may not work with the standard bolt lengths. Around 18 to 25mm is the typical practical range. A solid wood slab can be considerably thicker, which may require longer fasteners.
The stand up desk frame mounting pattern determines how the columns attach to the desktop. Most frames use a crossbar arrangement that spans between the two columns and attaches to the underside of the desktop at multiple points. The crossbar width is adjustable within a range, which is what allows the frame to accommodate different desktop widths.
For solid wood desktops, leave time for the wood to acclimatise to the room's humidity before mounting the frame. Wood moves with seasonal humidity changes, and a slab mounted while it's at one moisture content may develop tension or movement as conditions change.
Most two-leg motorised frames assemble in under an hour with basic tools. The columns attach to the crossbar or base beam, the controller and motor wiring connects through the columns, and the crossbar attaches to the desktop from below.
Cable management is worth planning before assembly rather than after. The desktop will have monitor cables, power, USB, and other runs that need to go somewhere. A cable tray mounted to the underside of the desktop along the back edge, and a cable spine or guide that allows wires to move with the desk during height adjustment without straining, keeps the setup clean and prevents cable damage over time.
Levelling the frame on the floor is the detail that gets skipped and then causes problems. A frame that isn't sitting level will put slightly unequal stress on the columns during adjustment. On hard flooring this is usually managed with the adjustable floor glides that most frames include. On carpet, the glides may need to be extended to compensate for compression. Spend two minutes checking this before loading up the desktop.
Running the anti-collision calibration, where the controller tests the range of travel and sets its limit positions, is a required step on most motorised frames and sometimes gets skipped by people who just want to use the desk. Do it. The calibration is what prevents the motor from running past its travel limits, which over time damages the drive components.
The result of getting all of this right is a desk that fits exactly where it needs to fit, carries the surface you actually wanted, and performs consistently for years. That combination is harder to get from a product catalogue than most people expect, which is what makes the frame-plus-custom-top route worth considering for anyone setting up a serious long-term workspace.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 5, 2026 | NCFA Resource | Financial Innovation
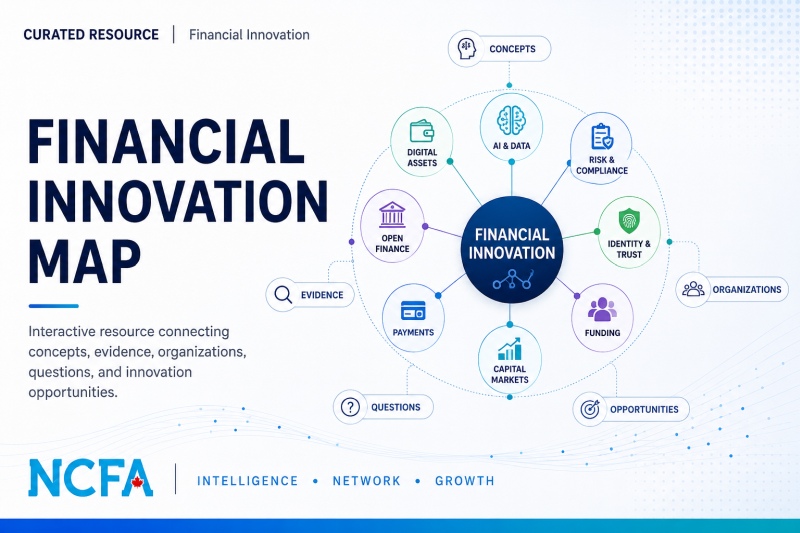
NCFA launched a Financial Innovation Map on June 5, 2026, as a practical resource for founders, investors, financial institutions, policymakers, researchers, and ecosystem builders. The map connects financial innovation concepts, use cases, featured organizations, evidence, questions, and innovation opportunities across fintech, funding, AI, digital assets, open finance, payments, capital markets, compliance, cybersecurity, and trust.
The Financial Innovation Map helps users move from concept awareness to opportunity discovery. Users can select a category, choose a concept, review sample use cases, scan featured organizations, explore innovation questions, and review resources tied to practical financial innovation activity.
The opportunity cards are practical and will continue to evolve. They show where adjacent concepts could combine into practical opportunities, supported by early, growing, or strong evidence. This helps users think beyond definitions and ask where an idea may create real value.
The need for better financial innovation intelligence is global. The BIS Innovation Hub works with central banks on technology trends that affect the global financial system, including digital finance, payments, market infrastructure, regtech, suptech, and financial stability. NCFA’s map gives Canada’s innovation ecosystem a practical way to explore many of the same themes from a founder, investor, policy, and market building lens.
Founders can use the map to test ideas, find adjacent concepts, and sharpen market theses. Investors can scan emerging areas before they become obvious sectors. Financial institutions can explore where new technology may reduce friction, improve workflows, or open new product opportunities.
Regulators, policymakers, researchers, and ecosystem builders can use the map to understand how technologies, rules, organizations, and unanswered questions connect across Canada and global financial innovation markets.
The strength of the Financial Innovation Map is structure. It brings concepts, organizations, resources, questions, and opportunity cards into one place so users can explore financial innovation with more context and less noise.
The first release is intentionally focused. Some concepts have more evidence and opportunity cards than others. That's by design. Opportunities are not added to meet a fixed count. They are added when there is enough evidence, friction, thesis strength, funding interest, or market activity to support inclusion.
The map isn't investment advice, legal advice, or a forecast. It's a curated intelligence resource that will improve as new evidence, resources, organizations, and opportunities are added. Stay tuned for future iterations.
Start with the Financial Innovation Map and explore the categories most relevant to your work.
For related NCFA coverage, see how AI agents, wallets, and financial identity are starting to connect, how agentic AI in banking is moving into practical workflows, and how tokenized infrastructure is changing market operations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 5, 2026 | Last Updated October 3, 2026 | NCFA Financial Innovation Map
Financial innovation is creating new language faster than most teams can absorb it.
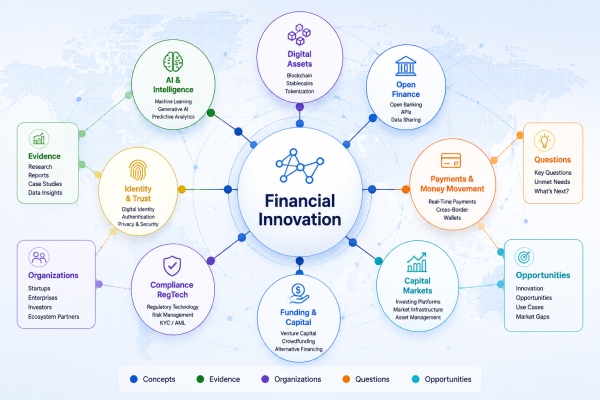
The National Crowdfunding & Fintech Association of Canada's Financial Innovation Map connects concepts, use cases, featured organizations, evidence, questions, and innovation opportunities across fintech, funding, AI, digital assets, open finance, payments, capital markets, compliance, cybersecurity, and trust.
Select a category, choose a concept, and explore how the idea works, who is involved, and where practical opportunities may emerge.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 5, 2026 | NCFA Insight | Artificial Intelligence And Data
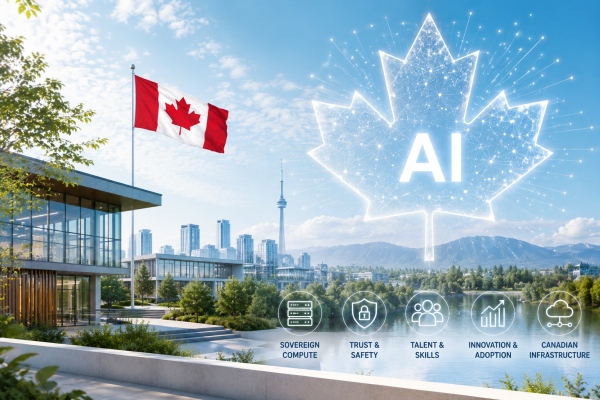
On June 4, 2026, Prime Minister Mark Carney launched AI for All, Canada’s new national artificial intelligence strategy. It targets $200 billion in additional economic growth, 250,000 new AI related jobs over five years, and a rise in AI adoption from just over 12% today to 60% by 2034.
The strategy also aims to create up to 90,000 AI related jobs and work placements for young Canadians. It supports AI skills, trust and safety, sovereign compute and cloud infrastructure, and Canadian company scale up. Canada’s AI challenge is no longer research. It is deployment.
Canada helped build the modern AI era. The country has three National AI Institutes, Vector Institute in Toronto, Mila in Montréal, and Amii in Edmonton. It also has a long record of public investment in AI research and talent.
Yet the harder problem is in the AI economy. The federal government says Canada remains among the slowest countries to adopt AI at scale. Only slightly more than 12% of Canadian businesses use AI today. AI for All sets a target of 60% adoption by 2034.
Canada has AI credibility, but it lacks broad deployment. Research output can attract talent and capital. Still, productivity gains only show up when companies redesign workflows, train workers, improve operations, and build commercial products around the technology.
This connects directly to Canada’s AI adoption gap. The next phase depends less on model breakthroughs and more on whether firms can put AI to work across finance, healthcare, manufacturing, energy, agriculture, transportation, and public services.
AI for All is a strategy with announced investments, but it’s not positioned as one simple funding package. It sets out an implementation plan built around trust, opportunity, and sovereignty.
The plan includes stronger privacy and online safety rules, AI transparency measures, expanded AI Safety Institute capabilities, entry level AI training for all Canadians, trusted AI agents for post secondary students, SME adoption support, and an AI Missions Program that starts with health.
Canada needs more firms, workers, and public institutions using AI in ways that raise productivity, improve services, and create Canadian owned economic value.
For fintech leaders, the strategy reads like an implementation roadmap. AI adoption will depend on infrastructure, skills, procurement, privacy rules, data governance, and trust. These are the same issues affecting open finance, digital identity, fraud prevention, payments modernization, and smart data infrastructure.
Financial services may offer one of the clearest adoption tests. Banks, credit unions, insurers, wealth management firms, payment companies, and fintechs already run data heavy businesses. They also rely on repeatable workflows, compliance controls, customer records, and risk systems.
AI can support fintech use cases from fraud detection and credit assessment to investment research and operational risk monitoring. That creates an opening for Canadian regtech firms, AI infrastructure companies, payment providers, lending platforms, and wealthtechs that can help institutions move from pilots to production.
The same issue appears in AI and non traditional data in financial services. Financial institutions can use AI to improve decisions, but they need governance that protects consumers and supports regulatory trust.
The strategy pushes AI into national competitiveness policy. It names compute, cloud, connectivity, data, and talent as foundations of sovereign Canadian AI.
At the company level, that infrastructure question reaches down to practical decisions about where applications and workloads run. A VDS server / virtual dedicated server can provide dedicated virtual computing resources for businesses that need greater control over hosting configurations, performance and resource allocation.
Canada’s national AI strategy also says the federal government will continue delivering more than $2 billion in existing investments in Canadian AI compute capacity, including through the AI Compute Challenge. This isn't a single new $2 billion package in the Prime Minister’s release. It's an existing compute investment stream tied to Canada’s wider sovereignty strategy.
It also connects directly to Canada’s recent debate over cloud concentration and AI sovereignty. Compute capacity and cloud control can determine whether domestic firms can scale without deeper platform dependence.
Countries don’t capture AI value only by producing researchers. They capture value when companies scale, retain key talent, own intellectual property, and sell into global markets from a domestic base.
For Canadian fintechs and investors, sovereign AI infrastructure affects who controls data, how firms access compute, how procurement supports domestic companies, and whether Canadian AI companies can scale before larger foreign markets pull them away.
AI for All sets ambitious targets. The proof will come from adoption, scale, productivity, and trust.
Can Canadian business adoption rise from just over 12% to 60% by 2034? Can Canadian AI firms scale while keeping meaningful operations, talent, and intellectual property in Canada? Can regulated sectors deploy AI with enough transparency and accountability to earn public trust?
Canada already proved that it can build AI research strength. Yet it hasn’t proved that it can turn that strength into widespread productivity gains and globally scaled companies at the same pace as larger markets.
For NCFA members, the opportunity lies in execution. Founders can build AI tools that solve costly financial sector problems. Investors can look for firms with real workflow adoption, not only technical claims. Policymakers can reduce friction where regulation, procurement, data access, and capital formation slow responsible deployment.
AI for All is a clear shift in Canada’s AI policy. Ottawa now looks at AI as an adoption, productivity, sovereignty, and scale up challenge, not just a research agenda. Canada’s AI advantage will come from helping more Canadian firms use AI, sell AI, govern AI, and keep more of the value created by AI in Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016