




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Open Banking in Canada | Nov 26, 2025

Canada is moving into a new phase of financial services with the Consumer Driven Banking Act. Budget 2025 confirms that open banking is officially moving forward, with a clear sequence for how the system rolls out. Legislation and technical standards in focus throughout 2025. The Bank of Canada receives new funding to supervise Canada's Open Banking Framework, and the government commits that people will not face fees when they access or share their financial data. The Real Time Rail to be launched in Q3 2026. Full open banking functionality including payment initiation is expected by mid 2027.
People will soon gain the right to share their financial data safely, securely and at no cost with accredited providers (which is highly important given the JPMorgan data fee backlash in the US). This functionality creates room for new products and new revenue models. It also pushes banks, fintechs and API platforms to rethink how they plan to commercialize the framework and grow. Since providers cannot charge fees for in scope data, the value sits in the tools and services built on top of that shared information.
Huw Davies puts useful ideas on the table in a recent Ozone API article, 'show me the money' about treating open banking APIs as real commercial channels. His thinking sparks a closer look at how those ideas land in Canada, where the rules, accreditation structure and staged rollout create a different set of opportunities. When you look at the Consumer Driven Banking Act through a commercial lens, the roadmap becomes clear. This article provides an overview of some models that could work in the read only phase. Other models unlock once write access arrives in phase 2, and a few ideas won't fit the Canadian framework at all.
Open banking in Canada begins with safe, consented data access, but the first year focuses on building the foundation rather than running a live system. Through 2025, the government works on legislation, technical standards, accreditation, supervision and security. The Bank of Canada receives $19.3 million over two years to lead this work, and the government redirects $36.9 million previously assigned to the Financial Consumer Agency of Canada to support the transition. Cybersecurity receives new funding as well, including $25.7 million over five years and an ongoing $5 million allocation for CSIS and the RCMP.
Read only data-sharing is expected to take shape in 2026 once the technical and operational framework is ready. In this stage, accredited providers can only read in scope data that a person approves. They cannot trigger payments or update any accounts. Revenue can be generated from insight, identity, developer experience and onboarding support. These components create value without charging for the data itself. Below is an overview of some models that can work during the read only stage.
| Type | Model | Viability | Why It Works | How It Generates Revenue |
| Enrichment and Analytics | Categorization and personal finance tools | High | Turns raw data into clear insight for users | Subscriptions or bank partnerships |
| Small business cash flow dashboards | High | Helps business owners manage money and plan ahead | SaaS pricing | |
| Spending and savings insights | High | Gives people visibility and confidence | Consumer upgrades | |
| Identity and Compliance | Identity verification and KYC | High | Accreditation increases demand for strong identity tools | Per verification fees |
| Fraud detection and risk scoring | High | Supports trust across the ecosystem | Event based fees | |
| Consent and audit logging | High | Helps accredited providers meet compliance requirements | Platform fees | |
| API Performance | High throughput tiers | High | Monetizes reliability and speed instead of raw data | Tiered usage |
| Extended transaction history | Moderate | Depends on regulatory interpretation | Premium tier | |
| Enhanced sandbox and developer tools | Moderate | Developers value better testing environments | Developer subscriptions | |
| Acquisition Flow | Data driven onboarding | High | Improves conversion and lowers friction | Better product economics |
| Account comparison and switching | High | Read access supports more transparent experiences | Customer acquisition gains |
The early phase rewards companies that help users understand their financial picture, help institutions manage compliance and help developers work with clean, reliable data. These models feel simple on the surface, but they will create the foundation for the expanded market activity that follows in phase 2. They also align fully with the principle that in scope data must be free for users.
Write access becomes possible once the Real Time Rail operates across Canada. Budget 2025 confirms that the RTR is expected to become operational in Q3 2026, and as a result, full consumer functionality under open banking, including payment initiation, is expected by mid 2027. This next phase turns open banking into a high value service layer, where accredited third parties can initiate transactions, open accounts, trigger lending and handle real time flows with user permission.
This stage unlocks the commercial engine most people associate with open banking. Money moves. Accounts open. Platforms become financial channels. Merchants cut payment costs. Developers build financial workflows inside the tools people already use.
| Type | Model | Viability | Why It Works | Revenue Trigger |
| Payments | Payment initiation for merchants | Very High | Direct bank payments reduce card fees and settlement time | Per payment fees |
| Invoice and bill settlement tools |
High |
Helps small businesses streamline payment operations | Transaction fees | |
| Embedded Credit | Loan origination APIs | Very High | Supports real time underwriting with live data | Origination fees and credit margin |
| Short term credit or BNPL tools | High | Easily integrates into digital journeys | Revenue share | |
| Modular Banking | Deposit account creation | High | Platforms control user experience while banks manage account infrastructure | Per account fees and float |
| Card issuance APIs | High | Works well for vertical software platforms | Interchange share | |
| Onboarding flows and identity orchestration | High | Smooth onboarding drives product adoption | Per onboarded user | |
| SME and Enterprise Services | Treasury and cash management | High | Real time rails enable automation and control | Subscription and volume fees |
| Payroll linked payments | Moderate | Depends on broader ecosystem readiness | API usage fees |
This is the phase where open banking becomes a full commercial channel where many parts of the value chain becomes programmable.
The companies that build trust, reliability and encourage developer adoption during the read-only phase will enter this phase with a strong advantage.
Canada's open banking rules are set to ensure people have the right to access and share their financial data without paying fees. So certain business models do not align with these requirements. If a model creates barriers or charges for in scope data, it won't fit in the current framework.
| Model Type | Viability | Why It Fails In Canada |
| Charging consumers for access to their own data | Very Low | Conflicts with the rule that in scope data must be free |
| Charging fintechs for raw data | Low | Creates unfair access for smaller players |
| Per call pricing for basic data | Low | Undermines competition and equal participation |
| Proprietary or closed APIs | Low | Goes against interoperability requirements |
| Monetizing derived data without clear consent | Low | Creates privacy and liability risk |
| Charging fintechs for mandated data access | Low | Conflicts with the goals of the framework |
Canada wants an open and competitive ecosystem that rewards companies for the value they create, not the data they gate. If a business model depends on tolls, walls or restrictions, it sits outside of Canada’s open banking structure.
Budget 2025 sets a clear timeline and path towards open banking commercialization. Standards and supervision take shape in 2025. The Real Time Rail becomes operational in 2026. Full functionality arrives in 2027. Phase one rewards companies that focus on insight, identity, compliance and developer experience. Phase two rewards companies that plan for payments, embedded credit, modular banking and real time financial workflows. Some models won't work as they conflict with the rules of the framework.
While it took Canada half a decade to get here, it's approach to Consumer Driven Banking balances innovation with protection. The phased rollout also encourages companies to build strong foundations early and to prepare for the more substantial opportunities when write access arrives. The organizations that engage with phase one now will be in the strongest position once the full system becomes available.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Nov 26, 2025
Image: Unsplash/Morthy Jameson
Crypto-based betting platforms have sparked new discussions in compliance and digital finance. As activity grows, industry participants are paying closer attention to how identification standards, data practices, and risk controls operate across different models.
Platforms that operate without identity-verification steps rely on alternative methods to manage access, transactions, and limits. Experts from Bitedge.com note that interest in no kyc betting sites in Canada often relates to speed and privacy, but these features also prompt questions about oversight and accountability. When traditional verification checkpoints are removed, other forms of monitoring tend to become more prominent, including blockchain-based tracking tools and automated controls.
Supervision frameworks for digital assets typically emphasize transparency, reporting, and safeguards against misuse. Models that reduce identity requirements still fall under these expectations. The team at Bitedge.com highlights that regulators increasingly consider how different crypto platforms apply risk-based controls, especially when transactions move across multiple providers. Clear standards for recordkeeping, transaction thresholds, and dispute procedures remain key points of attention.
In Canada, regulatory landscapes can vary by province. Ontario has embraced a regulated iGaming market with explicit crypto gambling guidelines, while British Columbia’s BCLC integrates crypto within its PlayNow platform, offering retail sportsbooks and online services under close oversight. Quebec leverages blockchain technology for enhanced transparency in gambling regulation. These provincial nuances illustrate the dynamic compliance environment providers must steer through.
Some platforms apply tiered verification, where certain features require additional screening. Others focus on on-chain analytics, allowing them to review transaction patterns without conventional documentation. Each model presents its own compliance considerations, especially around consistency and auditability. Industry specialists often discuss how automated tools can help maintain internal controls even when user data collection is limited.
Crypto betting faces growing legal scrutiny in 2025, including unclear jurisdictional rules, AML enforcement, and licensing gaps. Platforms must tackle risks around anonymous participation, transaction monitoring, and tax reporting. Establishing sound legal strategies and compliance frameworks is critical to avoid sanctions and sustain operations.
Cybersecurity continues to be central in digital finance, regardless of verification method. Platforms that do not collect extensive personal data still need strong protection for deposits, withdrawals, smart contracts, and operational systems. Multi-signatures, cold-storage practices, and third-party audits are widely used to support reliability. According to analysts referenced by Bitedge.com, clear communication about these measures helps users and partners understand how risks are managed.
Privacy-forward models typically reduce stored personal information, which can lower exposure in a breach. However, this does not remove the need for secure handling of transaction data, logs, and system access records. Transparent data-governance policies help clarify retention periods, access protocols, and methods for responding to technical issues.
Discussions around identification requirements continue to shape digital-asset policy. As more service providers explore crypto-based betting, industry groups, legal advisors, and technology teams are reviewing how different models align with reporting expectations and operational standards. The team at Bitedge.com often observes how these conversations advance when providers, developers, and compliance experts work together to define practical approaches.
In the context of ongoing sector development, many professionals follow educational sessions, roundtables, and regulatory briefings to stay current. Those seeking timely updates can review NCFA’s upcoming events, which often cover trends in digital finance, compliance practices, and emerging technologies.
As crypto betting continues to evolve, monitoring tools, audit mechanisms, and governance practices remain central topics. Providers that adopt no-KYC models frequently explore ways to combine privacy-protective features with rigorous oversight. Open dialogue between platforms, technical specialists, and policy groups helps maintain clarity as new methods gain attention.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Stablecoins | Nov 25, 2025

Image generated by AI
On November 25 2025, Klarna Group plc announced the launch of KlarnaUSD, and enters a global stablecoin market that McKinsey estimates now processes more than US$27 trillion in annual transactions and sits inside a cross border payments system that produces about US$120 billion in yearly fees.
Klarna brings 114 million customers and US$118 billion in annual gross merchandise value to its launch. The company already operates as a licensed bank in Sweden through Klarna Bank AB, and the company continues to expand its banking services beyond that market as it builds new digital payment and settlement tools. Klarna now moves beyond buy now pay later in the US and steps into the stablecoin market with an infrastructure level product designed for scale.
KlarnaUSD runs on the Tempo blockchain that Stripe and Paradigm created that's designed for payments. Tempo supports fast and low cost transfers which gives the company a quicker way to move money than traditional bank systems.
The stablecoin is issued through Open Issuance by Bridge explained by Stripe. Bridge connects Tempo to apps, wallets and bank accounts so KlarnaUSD can move across the app, the merchant portal and settlement tools.
Klarna's stablecoin keeps a one-to-one value with the US dollar, and its reserves sit off chain so the service can follow local rules.
KlarnaUSD runs on Tempo’s testnet today and moves to mainnet in 2026 which gives the company time to test and build before public availability.
Sebastian Siemiatkowski, co-founder and CEO of Klarna:
"Klarna has the scale to change payments globally: with Klarna’s scale and Tempo’s infrastructure, we can challenge old networks and make payments faster and cheaper for everyone,”
Klarna presents KlarnaUSD as a faster and cheaper settlement tool but the likely impact will reach further and impact how payments and value move inside Klarna’s ecosystem.
Klarna can settle payouts through KlarnaUSD which avoids long clearing cycles and reduces FX friction. Merchants that receive faster settlement at lower cost usually send more business volume to the service that provides those results because it improves cash flow and reduces operational friction. So Klarna can also expect more volume.
Shoppers can complete international purchases with KlarnaUSD and avoid the delays and FX fees that occur on card and bank networks. Merchants that convert international shoppers at lower cost often strengthen their margin and rely more on the service that supports those outcomes.
Refunds, reversals and buy now pay later corrections can move across KlarnaUSD flows with fewer delays.
Consumers that receive faster refunds tend to return to the service that resolves issues quickly which supports higher repeat use.
KlarnaUSD can support balances, rewards and saving style tools inside the app without the company building full banking infrastructure in each region. Users that keep balances inside a single platform often deepen their engagement because their financial activity stays in one place.
Fintech companies can use KlarnaUSD for their own settlement flows which reduces cost and increases speed. Platforms that provide reliable settlement rails often become part of a partner’s operational stack which expands the platform’s role in the broader ecosystem.
Stablecoin issuance introduces new responsibilities for Klarna. Regulatory risk matters because stablecoins sit under active review and issuers must meet rules on reserves, redemption and consumer protection.
Reserve management brings risk because Klarna must maintain high quality USD backing and manage liquidity for redemptions.
Technology risk also exists because KlarnaUSD depends on the Tempo blockchain and Stripe’s Bridge framework which must perform under load and remain secure.
Reputation risk matters because any issue with redemption, reserves or outages can affect trust across Klarna’s full product suite.
Klarna operates in Canada today through its app and merchant partners. According to NCFA’s Canadian market overview in “Klarna’s Meteoric Rise in the Canadian Financial Ecosystem” (Aug 2023), Klarna gained 640,000 active Canadian consumers within 18 months of its Canadian launch.
Klarna notably also went public this past September 2025 on the New York Stock Exchange, IPO priced at US$40 per share and opened with a 16% jump, as outlined in the NCFA analysis of Klarna’s IPO pop. This debut placed Klarna’s valuation near US$17.5 billion and signalled strong early investor interest. The stock now trades near US$29.92 (KLAR), according to the latest public market price. Maturing crypto markets, Klarna's digital bank growth plans, and recent IPO all help explain why Klarna is investing in new digital settlement tools, and let's not forget investor expectations.
While Klarna hasn't announced a Canadian launch timeline for KlarnaUSD. The confirms that KlarnaUSD is in testnet and planned for mainnet in 2026. Plus, a Canadian rollout depends on the completion of Canada’s new stablecoin rules of which the first draft of the national stablecoin act has just been released. Also worth reviewing is the FCAC's national survey on Canadian stablecoin use and views.
KlarnaUSD highlights how fintech companies can advance when they control both the customer network and the settlement rail. Klarna improves speed, lowers cost and gains room to build new financial services without relying on legacy systems. For Canada the timing is important. Stablecoin settlement is now moving into commercial use and companies that adopt token based rails can gain real cost and speed advantages. Canada’s stablecoin work gives local innovators a chance to compete as global fintechs introduce faster settlement tools.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Productivity | Nov 25, 2025

A founder at a Canadian fintech reviewed a routine workflow and noticed something important. The company had recently replaced several older tools with newer AI powered systems, and remarkably the new configuration could complete multi step tasks that used to require manual effort. The system gathered information, applied rules and moved the case forward without constant human prompts. Nothing unexpected happened. The work simply flowed from step to step. In that moment the team recognized that they were no longer working with simple tools. They had introduced capabilities that belonged in the agent category, even if no one had used that word yet.
The realization opened a larger conversation inside the company. That is the new AI systems didn't behave like single purpose tools like before. They behave more like assistants that can move through a workflow once they understand the goal. The team had not changed the work. The technology had changed what the work could look like, and recent research confirmed this realty of how teams are coordinating autonomous systems across full processes.
A tool performs a single action only when prompted. It behaves like a calculator or a search bar. Tasks such as summarizing documents, extracting fields, drafting support replies or classifying transactions remain inside this zone. A person decides each step. The system never chooses what to do next.
An agent behaves differently. It acts. It moves through a journey, maintains context, decides the next step and continues until it reaches a point where it needs help or completes the goal. Take a look at these AI use cases by haptik, such as CASHe credit flow where a conversational system guides a borrower from authentication to instant approval, or how Zuri improves efficiency and customer experience at Global insurance leader Zurich without human involvement. Both examples highlight AI agent behaviour, and not tools.
The practical 'acid test' for fintech teams is simple. Ask who chooses the next step in the workflow. If the human chooses, it remains a tool. If the system decides, it behaves as an agent. This distinction matters because agents require supervision, governance and ownership. They influence outcomes and customer experience. Treating an agent as a tool leads to blind spots.
Evidence from global surveys explains why this distinction matters for performance. The findings on workplace AI usage show that 88% of employees use AI at work but only 5% use it in ways that change their roles. Organizations also lose more than 40% of potential productivity gains (opportunity cost) when talent, workflows and governance do not align with the technology.
When fintech leaders understand the moment when tools become agents, they gain the vision needed to build high performing hybrid teams.
Once a fintech organization recognizes that its systems behave like agents, the nature of work begins to change. People no longer complete tasks in isolation. They supervise agents that perform sequences. The work becomes a blend of human judgement and systems execution. See this research on end-to-end agentic workflows, which analyzes how a few people can guide a large number of agents across full processes. These supervisors focus on results rather than steps. They correct behaviour, interpret outputs and refine the system. The work becomes less about completing tasks and more about guiding outcomes.
Check out this practical example describing an agentic fraud systems showing how agents monitor transactions, test controls and highlight anomalies. Human analysts review these exceptions, approve responses and explain logic to regulators. The agent carries out the first layer of work. Humans perform higher judgement. This structure changes daily routines.
A hybrid team begins the day by reviewing the agent log. They scan escalations, exceptions, unexpected patterns and customer interactions. The team also discusses where the agent needs correction, where it performed well and where rules need refinement. This daily rhythm feels closer to coaching a junior colleague than running a piece of software.
Changing structural workflows and shifting from doing to supervising can have cultural effects. Some feel replaced while others feel empowered. Leadership determines the direction.
When leaders explain that supervising agents is a higher judgement role, employees view it as progression. When leaders fail to explain, they view it as displacement.
Managing hybrid teams requires clarity, structure and shared visibility. A hybrid team succeeds when the agent behaves predictably, the humans supervise confidently and both sides contribute to results.
When no one owns the behaviour of an agent, the system drifts. Fintech leaders need to assign a small group of people to own a journey end to end. Strong supervision with the authority to adjust prompts, thresholds and workflow logic.
Every action taken by an agent must appear in a shared log. Without this, the team can't diagnose issues or maintain trust. The shared log becomes the anchor of the hybrid team.
When a human intervenes, the reason appears in the same log. When an agent acts, the outcome appears there as well. This shared view prevents confusion.
Teams must review the agent’s behaviour frequently. The review cycles in studies of agentic processes show that continuous improvement drives results. In practice, teams meet weekly to adjust rules, refine decision boundaries and align the agent with policy. These refinements keep the system current and adaptive.
Agents cannot handle every scenario. Hybrid teams need clear rules for human intervention. They must know when to stop the agent and how to redirect it. Regulatory environments require this clarity. Fintech companies that operate in regulated sectors must explain why the agent acted and when a human stepped in.
Leaders need to measure the hybrid team as one unit. The work of the humans and the work of the agent form one system. Outcomes such as customer satisfaction, approval speed, fraud reduction and error rates reflect joint performance. When both sides improve together, results accelerate.
Hybrid teams succeed when leaders treat the agent as a teammate with responsibilities and supervision rather than as a simple tool or gadget.
Canadian fintech companies operate inside a competitive global environment. Research from major international surveys positions AI as critical infrastructure for financial systems. Productivity gains increasingly come from the interaction between humans and agents rather than from models alone.
Tools help people work. Agents help the company run. Those that treat AI only as a set of single purpose tools are at risk of falling behind. Fintech leaders who understand this difference, and who build hybrid teams around it, will gain an advantage in scale, efficiency, and risk management. They also build trust with regulators and partners. A company that can explain how its agents behave, why they behave that way and how humans supervise them will become a more reliable and stronger participant.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Economy and Trade | Nov 24, 2025
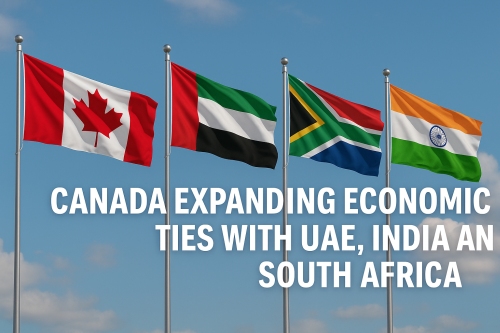
Image generated by AI
On November 23 2025, Canada announced a raft of cross-border trade partnerships after Prime Minister Carney spent the past week securing commitments in the United Arab Emirates, South Africa and India as part of a wider push to reduce reliance on the United States and expand global economic partnerships. These new openings create opportunities for Canadian fintechs and the wider innovation economy.
Carney used the G20 forum to reinforce Canada’s broader diversification strategy, pointing to U.S. tariffs and market uncertainty as direct pressures on Canadian growth, costing Canada an estimated 1.8% of GDP or the the equivalent of $50 billion or $1300 per individual. The PM's strategy aims to double exports to non-U.S. markets over the next decade, using new investment frameworks and economic partnerships to anchor that growth.
The strategy is aligned with NCFA's own cross-border initiatives to foster education, partnerships, and build economic and investment opportunities for regional fintech networks, which now sits directly on top of new trade corridors Canada is formally building. A couple of recent examples alone are NFCA Canada's collaboration with the 2025 Canada-Africa-Fintech-Summit, as well as an educational partnership with TheBlock, a Dubai-based virtual assets association, to focus on tokenization and real world assets (RWA) education.
On November 21 2025, during a visit to Abu Dhabi, Canada signed a new Foreign Investment Promotion and Protection Agreement. The UAE also signalled plans to invest up to approx $70 billion CAD (US$50 billion) in Canadian projects focused on artificial intelligence, clean energy, mining and infrastructure, according to the government’s UAE investment announcement.
The two countries also launched negotiations toward a Comprehensive Economic Partnership Agreement, which would cover services, goods and digital trade and give Canadian firms a more stable foothold in Gulf markets.
On November 23 2025, at the G20 Leaders Summit in Johannesburg, Canada announced new investment-protection talks with South Africa and confirmed the completed Nuclear Cooperation Agreement. These developments were highlighted in the government’s South Africa investment readout.
Canada also confirmed that FinDev Canada will open a Cape Town office in 2026, expanding its financing presence in African markets where digital financial services and early-stage business activity continue to grow.
Canada and India agreed to restart talks on a Comprehensive Economic Partnership Agreement after a two-year pause. This decision was confirmed in the India–Canada CEPA update issued during the G20 meetings.
Both governments signalled interest in expanding trade through improved access in goods, services, investment and digital sectors, with a a longer term goal of increasing two-way trade toward the US$50–70 billion range by 2030 depending on final terms.
These agreements, while they don't specifically mention fintech directly, they will impact the trading environment and structural conditions that matter for financial technology and funding innovation firms in the following ways:
More global capital in play. The UAE’s multibillion-dollar investment envelope creates new demand for financing platforms, risk systems, payments infrastructure and digital tools that support large scaling AI, energy and infrastructure projects.
New markets with strong digital finance adoption and upside. South Africa and broader African regions continue to scale mobile money, SME finance and digital identity rails. India remains one of the world’s largest digital payments ecosystems. Canadian fintechs offering compliance, embedded finance, alternative credit, and capital formation tools can explore more predictable and supported entry routes.
Trade agreements that impact digital rules. Investment treaties and CEPAs often influence data standards, dispute resolution, digital services access and treatment of financial technologies. Early engagement ensures fintech and alternative finance models are not overshadowed by incumbent only positions.
NCFA encourages fintech founders, investors and innovators to take advantage of these expanding global routes. Connect with us to discuss Africa and UAE partnerships, participate in upcoming trade related roundtables, and support policy and outreach work, as Canada negotiates new digital trade and investment frameworks. These government agreements create real openings, and NCFA’s global bridge network is ready to help Canadian fintechs move into these markets.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Stablecoin Regulation | Nov 21, 2025

Image generated by AI
On November 18 2025, the federal government of Canada released its first draft of the Stablecoin Act when introducing the Budget 2025 Implementation Act through Bill C 15. The legislation appears in Division 45 of Part 5 and establishes Canada’s first national framework for stablecoins. The official text published in the Bill C 15 First Reading record explains that the Act sets duties for stablecoin issuers, outlines the role of the Bank of Canada and introduces rules for reserves, redemption and governance. The full clause-by-clause level rules appear in the Draft Stablecoin Act document, now moved to a dedicated page on the Department of Finance's website under Canada's Stablecoin Framework.
The Act explains that if a company issues a stablecoin and follows this new federal law, the company is not treated like a bank for certain parts of the Bank Act, the Insurance Companies Act or the Trust and Loan Companies Act. In simple terms, if a company issues a stablecoin under this law, it is not treated as if it is taking deposits like a bank. This helps make sure that stablecoin issuers are regulated, but not in a way that turns them into banks.
The draft Act also says that if a company issues a stablecoin and follows this law, it is not treated as if it is dealing in securities for the specific federal rules listed in the Act.
The Act gives the Bank of Canada the job of keeping a public list of approved stablecoin issuers. An issuer must not give false or misleading information to the public.
The Act also places limits on what issuers are allowed to do. An issuer cannot use regulated words or symbols in a way that breaks future rules. An issuer cannot pay interest or any form of yield to stablecoin holders. This means stablecoins covered by this Act cannot look or act like investment products.
The Act also says an issuer cannot offer a stablecoin if it is treated as official money anywhere in the world. The issuer cannot offer a stablecoin if it is viewed as a bank deposit, if it is insured by a government deposit insurance program or if it is guaranteed by a government.
The Act has strong rules for how issuers must hold reserves. An issuer must hold enough assets to match the full value of all stablecoins in circulation. These assets can only be used to redeem stablecoins. They cannot be used for anything else.
The reserve must consist of the same currency the stablecoin is tied to or high quality liquid assets in that currency. Only the Bank of Canada or future regulations can approve other reserve assets.
The Act protects these reserves from being pledged, used as collateral, or borrowed against. The issuer cannot let anyone else have a claim on them.
The issuer must keep reserve assets with qualified custodians. The custodian must hold these assets separately from their own. The assets must not be available to satisfy the debts of the custodian or the issuer. They exist only to support redemptions. This helps keep customer value safe even if something goes wrong with the issuer or the custodian.
The Act makes clear that stablecoins must be redeemable at face value in the official currency they track. The issuer must follow this rule in line with future regulations. This protects users who want to convert stablecoins back into regular money.
Issuers must have a governance policy that sets out who is responsible for what. This includes the responsibilities of the governing body and senior management, how accountability works, how third party service providers are managed and how conflicts of interest are handled. This pushes issuers to run stablecoin operations with clear oversight and internal controls.
The Act explains where stablecoins fit into the wider regulatory world. A compliant stablecoin issuer is not considered to be dealing in securities or taking deposits for certain sections of federal prudential laws.
The Act also says that a stablecoin issuer counts as a business dealing in virtual currency under Canada’s anti-money laundering and anti-terrorist financing laws. This means the issuer must follow all federal AML and ATF rules, just like any other virtual currency business.
The draft Act must still move through Parliament. Many details will depend on future regulations written by the Minister and guidance from the Bank of Canada. Provinces will continue to have their own rules, including securities and consumer protection laws. The restriction on interest and yield pushes stablecoins towards payment and settlement functionality rather than investment use. The reserve and custody rules help protect customers. The governance requirements ensure that issuers treat stablecoins as serious financial products with clear oversight.
This draft law provides clear rules on reserves, custody, redemption and governance. It also clarifies how stablecoins fit within Canadian financial law, which helps fintechs design products, build payment systems and plan compliance with confidence. Earlier this year in July 2025, EY published a report on various approaches to global stablecoin regulation
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulation | Nov 21, 2025
Image: Freepik/jannoon028
On November 19, 2025, the Ontario Securities Commission announced the launch of its Research Grant Competition. This is a pilot initiative that provides up to five (5) grants of $30,000 each to support research on the competitiveness of Ontario capital markets.
The purpose of the competition is to invite proposals from researchers to examine how Ontario capital markets can stay efficient, innovative, and globally competitive as outlined in the Competition Details.
The program is open only to researchers who work at or are enrolled in a Canadian academic institution and who have not been employees or directors of the OSC during the past five years. Applicants must also confirm that they aren't involved in any unresolved regulatory or criminal findings. The OSC will award up to five grants of thirty thousand dollars with submissions due February 27 2026, winners notified April 17 2026, and final papers due August 14 2026.
Grant Vingoe, CEO of the OSC:
“The OSC Research Grant Competition is seeking to tap into Canada’s brightest minds to undertake the challenge of delving into the competitiveness of Ontario’s capital markets. In light of the current global geopolitical and economic challenges, it is increasingly important that we look at ways to help Ontario’s capital markets remain competitive, and we welcome the fresh thinking that the competition will bring, as we look ahead and plan future initiatives.”
The OSC will review proposals based on alignment with its mandate, originality, feasibility, academic support, and public benefit. Successful researchers will have their papers published on the OSC website and may present findings directly to senior leadership.
The competition currently limits eligibility to academic researchers. Wider participation from industry experts, innovators, and market practitioners could provide applied evidence on real operational friction such as registration, compliance, cost, access to capital, and technology adoption.
Numerous experienced practitioners who work on the front line encounter daily competitive pressures and could offer insights that complement academic analysis but unfortunately grant funding appears tied to researchers in academia.
Ensuring Ontario's capital markets remain competitive plays a key role in Canada's economic strength. While the research supported by this OSC initiative could influence future policy decisions related to capital formation, market structure, and investor confidence, if the goal is truly to benefit Ontario's capita markets one wonders why participation is restricted to researchers. The bottom line is that whatever insights are produced, if the OSC is to implement any of the ideas into practice it must be done swiftly, especially insights that help identify (quantify) structural barriers that affect the ability of Canadian firms to grow and compete globally.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016