




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


January 30, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Payments And Money Movement, Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization, Open Banking Open Finance And Data Sharing

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026)
Payment activity, API demand and recurring use increased while system performance remained stable. The figures establish an operating benchmark for countries building open banking around data access, payment initiation and commercial services. The later one billion payment milestone shows how quickly that base continued to expand.
Once a PSP can join the payments club directly, it can cut onboarding friction, tighten settlement and reconciliation, and show stronger operational maturity to banks, enterprise buyers, and regulators. Founders that treat membership readiness as an operating system will move faster when big partners demand proof. Investors should watch which PSPs turn access into volume and repeatable unit economics, not just press.
This is a planning signal for how the UK approaches AI in retail finance. Firms that sell into regulated buyers win time if they can show who owns outcomes, how models get tested, and how controls work across vendors and data flows. Teams that cannot evidence that quickly will find AI work slows down at the point of trust, not the point of build.
This matters to fintechs that sell into regulated buyers because coordination changes the buyer checklist. The winners standardize controls and reporting across spot, derivatives, custody, and settlement workflows so they do not rebuild the stack every time definitions and boundaries tighten.
This takes tokenization out of the hype lane and into build discipline. If you sell tokenized security rails to real institutions, you win deals when you answer the hard questions fast, who controls the record, how transfers stay legally effective, and where the product plugs into broker dealer, transfer agent, and clearing and settlement expectations.
This move embeds regulated stablecoin issuance directly into a global payments platform instead of leaving it at the edge. When stablecoins sit inside licensed EMI rails, settlement, liquidity management, and compliance become part of the core payments stack. Founders building wallets, FX, treasury, or cross border infrastructure should expect buyers to favor platforms that combine regulated issuance with distribution at scale.
A federal trust structure offers nationwide reach, clearer supervision, and stronger institutional credibility. Fintechs selling custody, settlement, compliance, or risk tooling should prepare for customers that operate under bank grade expectations. Investors should watch which applicants can survive the supervision burden that comes with federal status.
This pulls crypto compliance into product planning. Teams that want UK market access move faster when they convert these rule areas into workflows early, especially safeguarding, reporting, and accountable ownership across senior roles.
Payments access expands in Canada while regulators in the UK and US push firms toward clearer accountability in AI, crypto, and tokenized securities. The common thread is execution readiness. Buyers now ask who owns the record, who controls outcomes, and how a platform proves it can operate under supervision without slowing down. Fintechs that build for audit, governance, and market access early earn trust faster and avoid costly rebuilds when rules tighten around custody, settlement, and consumer outcomes. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jan 26, 2026 | NCFA Fintech Market Activity | Payments and Consumer Finance
Image: Freepik
On January 14 2026, Klarna launches instant peer to peer payments in 13 European countries, letting customers send money to friends and family directly inside the Klarna app for everyday moments like splitting a bill or gifting cash.
Klarna says the rollout is part of its wider push into day to day banking. The company links this launch to Klarna Balance accounts and to early traction for Klarna Card, where it reports over 4 million sign ups in four months.
Sebastian Siemiatkowski, Co Founder and Chief Executive Officer, Klarna:
“Customers are sick of the friction and fees of traditional banking, which is why millions signed up to Klarna Card within a few months of launch. With peer to peer payments we’re making it even easier to manage all of your payments through Klarna, now including small transfers, making managing your money quicker, easier, and cheaper.”
The product mechanics stay simple. Users pick a recipient by phone number, email address, QR code, or saved contact. Klarna then runs fraud and eligibility checks before it sends the payment. Klarna starts with transfers between Klarna users and says it plans to expand to transfers to non Klarna users and to cross border payments.
The country list makes the scale concrete. Klarna launches the feature in Belgium, Denmark, Finland, France, Germany, Italy, Netherlands, Norway, Poland, Portugal, Spain, Sweden, and the United Kingdom.
Klarna also ties the rollout to momentum in its banking products. It reports that global deposits increased from $9.5bn to $14bn by September 2025 after the introduction of Klarna Balance in August 2024. It also reports that card payments now make up 15% of total volume.
This release reads like a straightforward product launch, but it carries a deeper operating message. When a consumer finance app adds instant transfers, it moves closer to becoming the place users keep returning to. That changes how a brand competes. Users start comparing it less to checkout tools and more to whatever they use as their default money app.
When more consumer fintechs add peer to peer transfers, what keeps trust intact, clear fees, clear limits, clear recourse, or something else?
Klarna says its peer to peer payments run on traditional banking rails today, and it also says its exploring stablecoin-based options to improve speed, reach, and efficiency. The short term litmus test is whether Klarna can make transfers feel effortless without introducing new confusion around eligibility, disputes, and consumer expectations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 26, 2026 | NCFA Fintech Market Activity | Personal Finance and Consumer Savings
Product image of the GeniusCash app
Image courtesy of GeniusCash via CNW Group
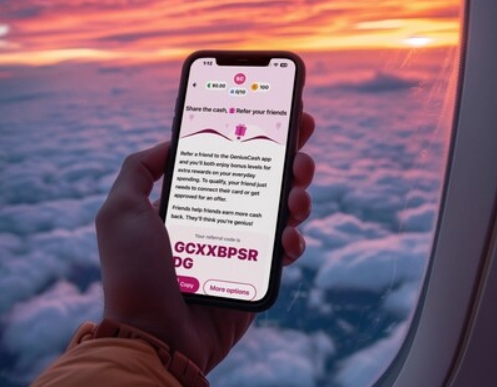
On January 15 2026, GeniusCash announced a $100M cash back pledge for Canadians and positioned it as a longer term push to expand cash rewards tied to everyday financial product decisions.
The company says it has already paid out close to $5M in cash back rewards. It frames the pledge as a public goal to scale that payout total to $100M over time, with progress updates planned.
GeniusCash describes a model that pays rewards as cash deposits rather than points. The release gives a simple example. A user can earn a $100 bonus for signing up for a selected credit card or bank account, and that reward contributes to the $100M target.
The pledge also expands the company’s product coverage. The release says GeniusCash plans to add more exclusive cash back offers across banking, credit cards, insurance, and other personal finance products, and it plans to increase financial education content tied to saving opportunities.
Stephen Weyman, Co-Founder of GeniusCash:
"We know every dollar counts right now for Canadian households. Groceries, gas, rent, it all adds up. We started GeniusCash to be a trusted friend to Canadians, the one that tips you off on how to get money back on your everyday expenses. Since setting this goal we have crossed the $5 million dollar mark in cash back paid, and we're just getting started. By pledging to give back $100 million, we're doubling down on our commitment to help families thrive and help stretch their budgets. This isn't hype, it's a mission. And we're inviting everyone to join us."
Cash back platforms live or die on trust and clarity. When consumers chase bonuses across multiple products, what guardrails will keep the experience transparent and prevent reward-marketing from turning into regret later?
This announcement is as a growth play that leans on two pressures Canadians feel every month. Prices stay high, and households keep looking for small wins that add up. The pledge sets a measurable target. The next validation point is whether the platform scales payout volume while keeping product selection clean and consumer outcomes easy to understand.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 26, 2026 | NCFA Fintech Market Activity | Scale and Leadership

Emily Roccheggiani, Chief Sales Officer, VersaPay
On January 26 2026, VersaPay named Emily Roccheggiani as chief sales officer and tasked her with leading the company’s sales organization and commercial growth strategy.
VersaPay describes itself as an accounts receivable platform focused on removing friction in B2B collections and reconciliation. The company reports 10,000 customers, more than 5M companies transacting, more than 110M transactions, and $260B in annual payment volume.
Roccheggiani brings a payments background that fits a scale role. The release says she spent more than eight years at Adyen and joined as the sixth member of the North American sales team during a major expansion period. She later served as chief revenue officer at Forma, where she built and led go to market teams.
The appointment matters because AR automation often wins or loses on distribution. In B2B payments, product capability rarely carries the deal on its own. Sales execution, partner reach, and repeatable deployment inside finance teams decide whether a platform becomes a standard tool or a niche add on.
Carey Kolaja, CEO of Versapay:
"Emily has spent her career inside some of the most important growth stories in modern fintech. She knows what it takes to build, scale, and win--from the earliest days of category creation through global expansion. As Versapay enters a new chapter of product innovation, partner-led distribution, and vertical market acceleration, Emily is exactly the leader we want at the helm of our revenue engine."
VersaPay puts a senior revenue leader in place while it pushes deeper into AR modernization. When CFOs choose AR platforms to improve cash flow visibility and controls, what evidence will actually influence enterprise buying decisions in 2026?
The release positions this hire as part of the company’s next growth stage across verticals and partnerships. The near term test is simple. VersaPay must convert market interest in AR modernization into repeatable wins with measurable cycle time and working capital outcomes.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 23, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Payments And Money Movement, Digital Assets Blockchain And Tokenization, Open Banking Open Finance And Data Sharing, Risk Compliance And Regtech
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026)
This lands in the middle of a problem every operator knows. AI stops being a feature once it touches credit, pricing, advice, fraud decisions, or customer outcomes. Buyers and supervisors ask one thing first. Can you prove how it behaves, who owns the decision, and what happens when it fails. Founders who build strong logs, clear accountability, and testable controls keep momentum when scrutiny rises. Investors should back teams that can ship AI inside regulated environments without betting on fuzzy governance.
Travel payments stay messy because suppliers, currencies, fraud controls, and reconciliation collide in one workflow. When a travel platform embeds issuing plus FX plus collections, it turns payments into a default layer that buyers adopt without a separate vendor decision. Fintechs that sell cards, FX, or payables into travel win faster when they integrate into the platforms that already control inventory and supplier routing, and when they ship audit ready controls that finance teams can trust at scale.
Private bank adoption changes buyer expectations fast. Once a top tier wealth manager treats crypto as an investable asset inside the core private bank, every crypto vendor selling into wealth has to meet private bank standards on suitability, controls, reporting, and operational discipline. Founders that sell custody, execution, portfolio reporting, or risk tooling should expect tougher diligence and longer lists of required evidence. Investors should watch for picks and shovels that fit inside existing wealth compliance rather than products that need new rules to work.
Cross border CBDC linkage puts sovereign governed interoperability back on the table as an operating roadmap. Fintechs that sell wallets, settlement tooling, compliance rails, and treasury workflows should plan for rule dense governance, shared operating standards, and audit grade traceability that can survive multi jurisdiction scrutiny.
A serious push for a US banking licence tells the market Revolut wants durable US distribution, not a light footprint. Once a global fintech commits to supervised rails in the United States, competitors face a tighter clock on product depth, compliance maturity, and funding strategy. Founders that sell infrastructure into banks and fintechs should expect more demand for audit ready controls, clean reporting, and resilient operations that hold up under US supervision.
Public markets put custody under a harsher light than private capital. Reporting cadence, risk controls, and operational proof start becoming the product. Founders selling into custody, compliance, and settlement stacks should expect tighter vendor scrutiny and cleaner evidence demands. Investors can treat this as a live benchmark for how the market values regulated digital asset infrastructure once it sits in plain view.
This deal pulls a modern fintech spend platform directly inside a large US bank instead of leaving it at the partnership layer. Once a bank owns the full card, payments, and spend stack, pricing pressure increases and distribution advantages compound fast. Founders building expense management, treasury, or commercial card tooling should expect tougher competition from vertically integrated banks. Investors should treat this as another signal that late stage fintech exits increasingly come through acquisition by incumbents that want product control, not just vendor relationships.
Tokenization stops looking like a side experiment once a core exchange puts its matching engine and brand behind it. The winners don't come from who talks loudest about crypto. The winners come from who can run clean market structure under supervision, with settlement, custody, funding, and controls that broker dealers and clearing members can defend. Founders building post trade, custody, reconciliation, collateral, and stablecoin treasury tooling should treat this as a buyer signal. Regulated infrastructure buyers want fewer moving parts, stronger audit trails, and reliable operating hours that match global capital flows.
Data modernization rarely feels exciting until it hits production. When a supervisor modernizes filing rails, every regulated team ends up rewriting workflows, data mapping, controls, and audit evidence. Fintechs that sell reporting, data, regtech, or infrastructure should treat this as a near term buying trigger. Institutions will pick vendors that reduce change risk and make compliance proof simple, not vendors that add another layer of complexity.
Charter expansion at scale. When a global fintech pursues full licenses market by market, it raises the competitive bar on compliance execution, local product depth, and funding strategy. Competitors feel pressure through faster distribution, tighter pricing room, and regulators expecting stronger controls across the category.
The firms that win are the ones that control where money moves and can prove they run a tight and compliant shop. Payments and treasury are getting built into the software people already live in, not sold as a separate product. Big fintechs keep chasing full licenses so they can offer more, price tighter, and rely less on partners. Governments keep pushing cross border settlement ideas that bring more rules, more reporting, and more scrutiny.
Founders should treat three things as product work. First, build evidence into the workflow so every action leaves a trace you can explain. Second, design for partner and regulator questions before they show up, not after. Third, sell into distribution points that already own the customer and the switching moment, because that's where adoption actually happens. Investors can use the same filter. Back teams that reduce operating risk while keeping shipping speed. Avoid models that need regulatory fog, fragile partners, or perfect market timing. The upside concentrates in infrastructure and platforms that buyers can trust at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 21, 2026 | Report Insights
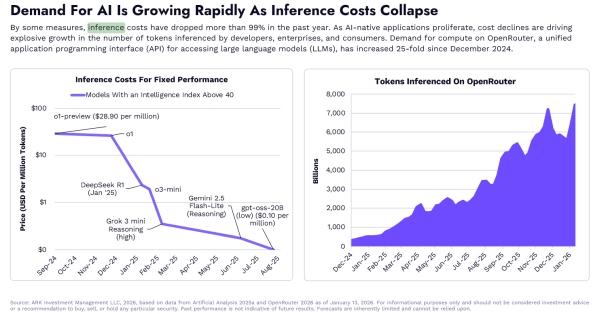
Image: ARK Invest, Big Ideas 2026 report. AI inference cost data reproduced for commentary and analysis.
In January 2026, ARK Invest released its annual research report Big Ideas 2026, building on trends first measured in Big Ideas 2025. The 111 page report spans artificial intelligence, tokenized assets, decentralized finance, Bitcoin, consumer AI platforms, and what ARK describes as the Great Acceleration. Rather than summarizing each theme in isolation, this article focuses on how these technologies accelerate change together inside financial systems.
What felt experimental in 2024 and operationally strained in 2025 now shows up as baseline reality in 2026. AI costs collapse, investment capital concentrates in infrastructure, digital assets move closer to settlement rails, and consumer AI platforms compress decision cycles. These forces do not arrive sequentially. They compound. The result is technically a financial system that no longer needs to pause between decisions.
ARK’s data on collapsing AI inference costs explains why this shift becomes unavoidable. At the same time, investment capital continues to concentrate in infrastructure designed for continuous operation. Together, these forces change how money moves, settles, and gets controlled.
Finance is AI-native by design. It already runs on software, explicit rules, and constant feedback. As AI becomes cheap enough to run continuously, software acts directly inside financial systems instead of waiting for human input.
ARK’s Big Ideas 2026 research shows AI inference costs dropped more than 99% in the past year. That single data point explains why continuous operation becomes economically viable at scale for the first time.
When inference costs fall that far, AI stops being something teams consult occasionally. It becomes something that runs all the time. Human prompts, batch reviews, and periodic decision cycles turn into friction rather than safeguards.
In financial systems, this breaks a long standing boundary. AI no longer stops at scoring, forecasting, or recommendations. It initiates actions. Payment routing adjusts automatically. Exposure limits rebalance in real time. Liquidity thresholds enforce themselves continuously. Software no longer waits for approval at every step.
Founders experience this when systems stay busy all the time instead of spiking occasionally. Investors see it when infrastructure costs stop falling as predictably even while revenue continues to grow. Operating leverage behaves differently because systems no longer rest between decisions.
ARK’s capital analysis shows where investment capital flows as systems scale. In 2025, annual investment in data center systems reached roughly $500B, nearly 2.5 times the long term average from 2012 through 2023. Since the ChatGPT moment, ARK shows growth accelerating from about 5% to 29% annually. The report projects this category of investment could approach $1.4T by the end of the decade.
That level of spending signals where long term value accrues. Capital is not chasing surface automation features. It is concentrating where compute, data availability, uptime, and recovery determine whether systems can operate continuously without failure.
For fintech teams, this breaks a familiar assumption. Products designed for occasional use face redesign pressure. Infrastructure built for constant operation gains structural leverage. Cost structure, resilience, and throughput now shape competitive advantage more than feature differentiation.
Traditional payment systems assume a person initiates the transaction. AI breaks that assumption. Software now initiates payments, manages balances, and settles obligations automatically as conditions change.
This pushes pressure into liquidity management, fraud controls, and settlement logic. Batch review fails quietly when systems never pause. ARK’s analysis of AI driven transaction flows emphasizes sustained throughput and recovery under stress rather than peak performance.
Founders building payment infrastructure encounter this pressure early. Systems designed for bursts now operate under constant load, and cost curves change accordingly. Reliability becomes a competitive feature rather than an operational afterthought.
ARK’s 2026 research frames consumer AI as an operating layer rather than a feature. AI models converge into a consumer operating system, and adoption accelerates faster than earlier digital platforms. As these systems take on purchasing, allocation, and coordination tasks, decision making shifts closer to software execution.
Wallets evolve alongside this change. They function less as interfaces and more as control layers for software driven financial activity. Identity, permissions, and payment logic compress into the same layer.
Investors familiar with earlier platform cycles recognize this pattern. Control consolidates where decisions execute, not where they are merely displayed.
ARK frames tokenized assets as market infrastructure moving trillions of dollars in asset value onto blockchains. Tokenization matters because assets move and settle automatically. DeFi matters because financial rules run on software without manual steps.
ARK’s data shows digital asset application revenue reaches roughly $3.8B in 2025, with around one fifth generated in January alone. The report also notes that about 70 applications generate more than $1M each in monthly recurring revenue. Value capture shifts from base networks toward platforms that control execution, coordination, and user interaction.
For fintech builders, this exposes a structural mismatch. Systems designed for batch reconciliation struggle when assets move continuously.
ARK’s research treats stablecoins as payment and settlement rails, not alternative products. Transaction activity reaches record levels because stablecoins can now move value automatically and clear obligations without waiting for manual steps.
Bitcoin functions as a monetary network with predictable issuance and global settlement. In 2026, its relevance aligns with the same requirement driving stablecoin use. When systems run continuously, money must move at software speed.
This doesn't remove banks, payment firms, or regulators. It changes how settlement works underneath them, reflected in Canada’s Stablecoin Act draft, which outlines how programmable settlement rails are governed.
ARK's analysis points to convergence. Continuous systems expose the limits of oversight built around delayed reporting and human initiated workflows. Design, auditability, and real time visibility matter more because systems no longer pause between decisions.
For policymakers, this changes where effective oversight begins. Rules written for periodic review struggle when financial activity runs continuously. Payments oversight, digital asset policy, and AI governance increasingly overlap because the systems themselves overlap.
Teams that design for transparency and control early reduce downstream risk. Regulators that focus on system behaviour rather than product labels gain clearer visibility and fewer surprises.
Big Ideas 2026 highlights what happens when AI inference costs collapse by more than 99%, investment capital concentrates at unprecedented scale, digital assets mature into settlement rails, and consumer AI platforms compress decision cycles at the same time. Finance changes faster because it already runs on rules, incentives, and software.
AI systems now run continuously. Many teams still model for peak usage instead of sustained operation. The gap appears in compute, monitoring, compliance operations, and incident response long before it shows up in customer metrics.
Infrastructure intensity rises faster than application revenue. ARK’s capital data shows control and throughput capture value before features do. Margins do not scale linearly during infrastructure transitions.
Human initiated workflows. Cost per transaction and average response time lose meaning when systems never pause. Sustained throughput and recovery time under stress become the binding constraints.
Frameworks assume discrete events. Continuous systems blur those boundaries. Risk appears as operational mismatch rather than enforcement action.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Stablecoins | January 20, 2026
Image: FCA Stablecoin sprint participation pack, March 4-5, 2026
The UK Financial Conduct Authority is hosting a Stablecoin Sprint on March 4 and 5, 2026 in London. Applications are open until February 4, 2026. The Sprint feeds directly into the FCA’s work to finalize stablecoin payment rules later in 2026 and focuses on retail payments and remittances, including point of sale payments, ecommerce, domestic transfers, and cross border payments. A smaller roundtable planned for May will focus on trade payments, including trade finance and B2B payment flows.
The Stablecoin Sprint follows a series of FCA consultations in 2025 covering stablecoin issuance, safeguarding of cryptoassets, prudential capital and liquidity requirements, disclosure for UK issued qualifying stablecoins, and application of the FCA Handbook to regulated crypto activities. The FCA has also opened a stablecoins cohort within its Regulatory Sandbox to allow issuers to test UK issued stablecoins.
The FCA has structured the Sprint around three policy questions that go directly to how stablecoin payments would operate in practice. Full details are set out in the 16 page PDF, FCA Stablecoin Sprint participation pack.
The first problem statement asks what business models firms could use to deliver stablecoin payment use cases. Participants are expected to map payment flows end to end and explain how roles and responsibilities sit across issuers, wallets, payment providers, banks, and infrastructure firms.
The second problem statement examines where opportunities and risks arise within those models. This includes identifying where consumer harm, financial crime exposure, operational failure, or business weakness could appear, as well as where stablecoin payments could offer real improvements over existing payment systems.
The third problem statement focuses on priorities. Participants are asked to consider what regulation is needed, what may not be needed, and where risks could be addressed through business practices or technical design rather than new rules.
Across all three problem statements, the FCA asks participants to test stablecoin payment models against cost, speed, interoperability, certainty of settlement, and consumer protection.
Canadian regulators have already consulted publicly on payment functions through the Retail Payment Activities Act and on stablecoins through federal and securities frameworks. What the FCA Sprint adds is a use case driven exercise that brings those questions together around live payment flows. For Canadian fintechs, it offers a clear view of the practical issues regulators may still need to address as stablecoins move from trading into everyday payments.
As stablecoins move from trading and settlement into everyday payment use, regulators are under pressure to explain how these models fit within existing payment rules. The FCA Stablecoin Sprint shows that key questions around business models, risk ownership, and consumer protection remain open. For fintechs, payment firms, and infrastructure providers, the Sprint offers a clear view of where policy attention now sits and where practical clarity will matter most as stablecoin payment rules take shape. Apply Now
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016