




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Payments | Oct 2, 2025
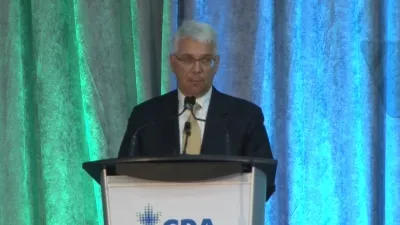
Image: Ron Morrow, Executive Director, Bank of Canada (CPA The One Conference Sep 18, 2025)
On September 18, 2025, Ron Morrow, Executive Director of Payments Supervision at the Bank of Canada, delivered a speech at the CPA The One conference titled, "Making change Accelerating payments innovation". He spoke about a vision for Canada’s payments future, one where innovation, oversight, and competition intersect. Stronger oversight and modern payment rails will make the system more competitive and inclusive.
This article unpacks select key quotes and and highlights two sides of the coin for stakeholders to see both sides and the trade-offs that come with it. For Canada, the task now is not whether to act, but how to add momentum and keep pace in a global race.
“Almost 1,500 payment service providers are now required to register with the Bank under the Retail Payment Activities Act.”
For the first time, nearly fifteen hundred retail Payment Service Providers (PSPs) are being pulled into the regulatory fold. Supporters argue that this gives consumers and businesses more confidence when using new services and helps fintechs compete on equal footing with banks. By ending the perception that startups operate in a grey zone, it could make investment in the sector more attractive.
But compliance comes with costs, and many small firms run lean without a large legal or regulatory staff like banks. What may feel like light reporting to a large bank can feel like a heavy lift for a ten person startup. In the worst case, it could drive consolidation that narrows competition instead of expanding it.
“Our job is to make sure that innovation in the payments system can proceed in a way that is safe, sound and reliable.”
Safe to say that Canadians will only embrace new forms of payments if they trust them to work without interruption and to protect their money. Regulation that sets clear expectations can provide certainty for innovators, giving them a stable foundation to build on.
Yet safety can lead to an abundance of caution that could slow innovation. Other countries, from the UK to Singapore, have shown that regulators can allow pilots and sandboxes to move quickly while still managing risk. If Canada puts too much emphasis on stability, we'll fall behind in a global race where trust and speed both matter.
“We are working to expand access so that more providers can offer services directly through Canada’s core payment systems.”
Direct access to national infrastructure is potentially transformational. If fintechs can gain access without going through a big bank, they can offer faster and cheaper payments. This would lower costs for consumers, ignite competition, and open the door for creative new services in areas like cross border transactions.
The flip side is that these core systems were designed with large, well capitalized institutions in mind. Smaller entrants may not have the same buffers to handle liquidity shocks or technical breakdowns. One major failure could undermine confidence across the entire network. The challenge is designing an access model that widens competition without weakening stability. Payments Canada who is overseeing Canada's payments modernization has delayed implementation numerous times, and industry is frustrated. In May 2025 however, they announced that the technical build will be completed by Q3 2025 and they plan to test the system throughout 2026.
“Through our work with the BIS Innovation Hub, we are exploring the potential of new technologies such as tokenization and artificial intelligence.”
Engaging with international financial innovation hubs allows Canada to stay connected to the latest fintech and payments research, including stablecoins and tokenization. It also helps Canadian fintechs align with emerging global standards, making cross border scaling easier. Last June 2024, the BIS and Bank of Canada Launched the BIS Toronto Innovation Centre.
The real risk lies in harmonization at home. Canada’s financial system is driven by a concentrated banking sector and diverse regional economies, where inter-provincial differences can create barriers to trade and investment. If newly adopted financial technologies and related reforms aren't designed to work seamlessly across all provinces and territories, Canadian markets could become further fragmented with unwanted barriers and compliance costs. Canada needs to strengthen its internal market with more competition and innovation to be able to complete with strength globally.
“Payments innovation cannot be separated from broader efforts like open banking.”
If Canada completes payments modernization while also enabling consumers to share their financial data securely (open banking, consumer driven finance), the market could see a boon of new service models and tools that bring real competition to a system long dominated by incumbents.
Skepticism is very real though with Canada lacking the political will to finally implement open banking after promising it and studying it for years. Without binding timelines, many in the industry hear speeches like this one but actions speak louder the words. For fintechs, the question remains whether it is worth investing in solutions that depend on open banking when political momentum has not yet delivered results, or opt for new pathways. The latest is that open banking in Canada will land in 2026., with further delays will have significant consequences for innovation and consumer choice in Canada.
Ron Morrow’s speech delivers a clear vision and direction for modernizing Canada’s payments landscape. Expanded oversight, broader access to rails, and participation in global innovation networks all point to a more open and competitive future. If open banking also arrives in 2026, these reforms could unlock real benefits for consumers and fintechs alike. But the devil’s advocate cannot be ignored. Here's a streamlined version of Morrow's speech, 'Cashing in on Payments Innovation' (fingers crossed)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Digital Asset Regulation | Oct 1, 2025

Image: Freepik
On September 29, 2025, the U.S. Securities and Exchange Commission (SEC, Corporate Finance Division) issued a no action letter for DoubleZero that addresses how decentralized physical infrastructure networks (DePIN) should be treated under securities law.
The SEC's staff concluded that tokens earned by providing infrastructure services did not need to be registered as securities. Commissioner Hester Peirce reinforced this position in a follow-up statement, where she described DePIN tokens as rewards for real work rather than investments reliant on others’ managerial efforts.
DePIN refers to decentralized physical infrastructure networks where people contribute bandwidth, storage, mapping, or energy and receive tokens in return. These networks create open marketplaces for infrastructure and reduce reliance on centralized ownership.
Peirce (aka Crypto mom) described this approach as a new way to organize services using blockchain technology. She argued that tokens functioning as rewards for services are economically distinct from securities and that forcing all blockchain models into securities law could suppress innovation.
DoubleZero avoided the pitfalls of speculative fundraising from token sales marketed with profit expectations. Instead of pre-selling tokens to investors, its 2Z token was earned by participants who contributed infrastructure services, such as bandwidth, storage, and node operation.
The SEC staff stated that it would not recommend enforcement if tokens were distributed under the programmatic model presented by counsel. The relief granted was narrow and applied only to the programmatic model where tokens were distributed automatically to contributors per present conditions.
The letter also made clear that different facts could lead to a different outcome. You can read DoubleZero's response to the no-action letter here.
In the vein of avoiding token fundraising and keeping distributions tied to real services, networks that reward participants for sharing unused internet bandwidth, provide hard drive capacity, or feed energy into microgrids could potentially align with this reasoning. Other applications might include mapping and geospatial services, where users are rewarded for validated data contributions.
By contrast, projects that conduct presales or ICOs with promises of speculative returns, rely heavily on centralized managerial efforts, or direct most tokens to investors rather than active participants are less likely to qualify. The SEC emphasized that the economic reality must be compensation for work or services, not profit expectations.
While Canada hasn't yet issued specific guidance for DePIN tokens, the DoubleZero letter offers a comparison that Canadian entrepreneurs and policymakers can evaluate when distinguishing between functional reward tokens and investment contracts.
It's another clear acknowledgement from the SEC that not all tokens should be treated as securities. For builders, it shows how models tied to infrastructure participation can be designed to avoid speculative classification.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Blockchain | Sep 29, 2025
On September 29, 2025, Swift announced its blockchain-based ledger at Sibos 2025. The initiative brings together more than 30 financial institutions worldwide, including Royal Bank of Canada and TD Bank, to design and test a prototype with Consensys. The project is aimed at enabling real time, 24/7 cross-border payments to more than 200 countries and territories.
Javier Pérez-Tasso, Swift CEO:
“We provide powerful and effective rails today and are moving at a rapid pace with our community to create the infrastructure stack of the future. Through this initial ledger concept we are paving the way for financial institutions to take the payments experience to the next level with Swift’s proven and trusted platform at the centre of the industry’s digital transformation.”
Swift’s prototype will provide a secure log of transactions between banks that is updated in real time. The ledger will validate and sequence payments while using smart contracts to enforce agreed rules automatically. Unlike a public blockchain, this shared ledger is a permissioned infrastructure operated by Swift and its member banks. While it's blockchain-based in design, drawing on distributed ledger technology for resilience and transparency, it's not an onchain network like Ethereum.
Rather than creating new tokens itself, Swift’s role will be to provide the infrastructure for financial institutions and central banks to settle regulated tokenised value. By focusing on interoperability, Swift is designing the ledger so that it can operate alongside both traditional rails and emerging blockchain networks to reduce fragmentation and help financial institutions transition smoothly.
Also as a separate blockchain track, Swift is also experimenting with onchain migration of its messaging system using Ethereum Layer 2 Linea, as reported by The Block, which includes banks such as BNP Paribas and BNY. Swift is undergoing a parallel strategy to both upgrade existing rails while also preparing future digital rails.
The direct participation of RBC and TD gives Canada a seat at the table in Swift's financial infrastructure modernization initiatives. Their involvement means that Canadian banks intend to remain competitive globally as tokenised settlement gains traction. For Canada, the implications could be far reaching, making it easier for businesses to manage international trade and for capital to move efficiently across borders.
Swift’s work comes at a time when market forecasts suggest rapid growth in tokenised payments. Citi’s GPS report on stablecoins 2030 projects that stablecoin issuance could reach $1.9 trillion under a base case and as high as $4 trillion in a bull case by 2030, with transaction volumes approaching $100 trillion if stablecoins circulate at payment velocity.
The report also says stablecoins will likely coexist with tokenised deposits and bank-issued tokens, which may surpass them in scale.The question is whether Swift’s infrastructure approach will become the primary neutral rails that digital assets need to move securely across borders, or not.
After years of blockchain push-back denial, the launch of Swift’s blockchain ledger prototype is a key milestone in the modernization of global financial infrastructure. With RBC and TD among the participants, Canada is positioned within the group to contribute to the design and development of standards from the start. Digital assets and traditional financial networks seem to be converging at a global scale.
Other reads you may like:
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI | Sep 29, 2025
Image: Freepik AI
On September 24, 2025, Canada's AI darling Cohere announced a second close to their latest round with an additional $100M added to their coffers, valuing the company at approx $7B, positioning the company at the center of secure enterprise deployments while Ottawa launched a 30 day consultation to reset the national AI strategy.
Cohere’s new funding builds on traction with its Command A models and the North platform, both designed for private solutions across finance, healthcare, and government.
Alongside the capital, the technical story is about compute diversity. On September 24, 2025, AMD and Cohere expanded their global AI collaboration for enterprise and sovereign deployments while also adopting North internally. The widens buyer choice and lowers total cost of ownership for organizations handling sensitive data.
Cohere’s Nick Frosst said customers now have ‘significantly greater flexibility’ in how they use Cohere’s AI, while AMD’s Vamsi Boppana noted they benefit from better cost efficiency and energy performance.
On September 26, 2025, the federal government launched an AI Strategy Task Force with a 30 day consultation window from October 1-31 to set priorities around safety, sovereignty, and procurement readiness, with the goal of moving quickly toward digital sovereignty and economic adoption.
Hon. Evan Solomon, Minister of Artificial Intelligence and Digital Innovation and Minister for FedDev Southern Ontario:
“The Government of Canada is moving quickly toward our vision for AI and digital sovereignty. The AI Strategy Task Force and the ideas gathered through our national sprint will generate bold, pragmatic and actionable recommendations to guide Canada’s next AI strategy. This strategy will accelerate the development of nation-building AI and data infrastructure, drive economy-wide adoption and help build the strongest economy in the G7.”
FedNor confirmed $595,400 across three projects in Northern Ontario, spanning powerline mapping, healthcare automation, and First Nations training. One example is a $500,000 repayable contribution to CircuitIQ for a live powerline mapping tool, which will support hospitals and transport infrastructure. The same program provides $67,200 for Waive to automate healthcare forms and $28,200 for Ontario First Nations Technical Services Corporation to prepare training for more than 50 communities.
PwC Canada’s Value in Motion analysis projects that if Canada accelerates AI adoption, the economy could reach $3.65T by 2035 (up from $2.89T in 2023). The study stresses that faster uptake depends on capital investment, access to compute, and clear policy direction the very areas now in motion with Cohere’s new funding, AMD’s infrastructure partnership, and Ottawa’s task force.
The alignment of capital, computing power, and policy confirms that Canada’s AI story is entering an execution phase. Growth and success will depend on measuring real productivity gains in the near term."
For institutions that handle sensitive data, having more choice in computing power and proven enterprise models lowers risk and gives them more leverage. For policymakers, the inclusion of regional funding shows that AI adoption isn't just an urban story.
For fintechs, October is the time to prove that their models are reliable, that data stays in Canada when required, and that costs are clear enough for procurement teams to sign off.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
CBDC and Stablecoins | Sep 29, 2025
Image: Freepik
On September 19, 2025, EU finance ministers reached a compromise on the digital euro roadmap, designed to reduce dependence on Visa and Mastercard. The plan gives governments a stronger role in any launch decision and sets limits on how much citizens can hold. For official policy context, see the EU Council’s digital euro page, which outlines objectives and implementation steps.
Just six days later, nine major European banks formed a consortium to launch a MiCA-compliant euro stablecoin, targeting a 2026 launch. The group includes ING, UniCredit, CaixaBank, Danske Bank, SEB, Raiffeisen Bank International, KBC, DekaBank, and Banca Sella. Their goal is to deliver instant payments, programmable settlement, and a regulated alternative to unbacked crypto tokens.
By anchoring the stablecoin in Europe’s MiCA framework, the banks are moving early to define how regulated tokenized money will work. MiCA sets clear standards for issuers on capital, governance, and reserve management. That clarity is drawing incumbents to commit capital and credibility.
The digital euro and the bank consortium stablecoin initiative both look to rebalance power in Europe’s payments market. Today, Visa and Mastercard process around two‑thirds of all European card transactions. Policymakers want to ensure Europe can clear and settle payments domestically without relying on foreign schemes.
The central bank digital currency (CBDC) and stablecoin initiatives also intersect with Wero, the new retail wallet developed under the European Payments Initiative. Wero is designed to give merchants and consumers a unified tool for instant payments across the euro area, and a tokenized euro would strengthen its value proposition. This alignment mirrors the Canadian Real‑Time Rail project, though Europe is tying its upgrades more explicitly to digital money.
A further motivation is market share. Euro stablecoins currently total only about €620 million outstanding, compared to nearly $300 billion for U.S. dollar stablecoins. Europe risks being sidelined if it does not accelerate adoption, as global trade and DeFi increasingly rely on dollar‑based tokens.
For fintechs, these initiatives open a regulated path to experiment with programmable money, cross‑border settlement, and retail wallets. Startups may be able to integrate stablecoin rails into remittances, treasury management, or point‑of‑sale services with legal certainty.
For banks, the picture is mixed. Deposit flight is a risk if customers shift balances into tokenized wallets. Yet the banks launching the consortium also stand to gain by controlling issuance, custody, and compliance, capturing value from tokenization.
Canada has taken a more cautious approach. The Bank of Canada has said there is “no compelling case” for a retail digital dollar and is prioritizing upgrades to payment infrastructure. Policymakers are also examining how to regulate stablecoins, with oversight currently split between federal and provincial authorities. See NCFA's analysis of Canada's stablecoin race entering a critical phase for a more detailed analysis.
Europe’s actions highlight lessons for Canada. Their dual‑track model of a CBDC combined with a bank‑led stablecoin consortium shows how sovereignty and innovation can be balanced. A digital loonie could serve as a public anchor, while regulated Canadian bank or fintech stablecoins could deliver speed and programmability. Equally important, MiCA demonstrates the power of legislative clarity, something Canada lacks as fragmented oversight slows momentum.
Europe’s urgency also stems from the fact that euro stablecoins represent a tiny fraction of the global market. Canada faces the same risk if stablecoin use grows but domestic frameworks stall, Canadians may increasingly rely on U.S. dollar tokens for payments, weakening monetary sovereignty. Europe is also linking its initiatives to Wero, its new retail wallet.
Canada could also add experiments to the rollout of its Real‑Time Rail, ensuring token‑based payments integrate with domestic upgrades. Although Canadians and payment stakeholders can't afford any more delays.
If Canada followed a similar approach as in Europe, payments could become faster and cheaper, and fintechs would gain new opportunities in programmable settlement and remittances. Banks could face pressure on deposits but would gain new business in custody and compliance. If Canada hesitates for much longer, the country risks dollarization via U.S. stablecoins, reducing control over payments and data governance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 29, 2025

Image: Freepik/Rawpixel.com
Commercial insurance is a topic that every small business owner must eventually face. Is it worth the investment?
For many, commercial insurance can seem like just another expense on a list already filled with costs.
But look closer, and it becomes clear that commercial insurance is much more than a routine budget item; it is a vital safeguard that can secure the future of a small business against unexpected setbacks.
Small businesses operate with limited resources, which makes them especially vulnerable to unforeseen events. From lawsuits and accidents to theft and cyberattacks, a single incident can cost more than a business can afford to pay out of pocket. Small business insurance like commercial insurance steps in to absorb these shocks, covering legal fees, property repairs, settlements, and medical costs, so business owners aren’t left stranded during emergencies.
Running a small business without insurance is risky. Many entrepreneurs underestimate how frequently claims happen. A customer slipping on a wet floor, a fire damaging inventory, data theft from a cyberattack, these are real scenarios that occur more often than most people realize. Claims like these can easily spiral into six-figure costs, threatening the survival of any business without insurance protection.
One of the most compelling reasons to carry commercial insurance is financial security. Even a minor accident or lawsuit can drain years of savings or hard-earned profits. But there is more: operating without required coverage may expose a business to legal fines, penalties, or even forced closure, depending on local laws and industry regulations. Insurance helps businesses stay compliant, protect their assets, and avoid personal liability, meaning creditors can’t go after owners’ personal property to settle business debts.
Beyond direct financial protection, commercial insurance offers peace of mind that allows owners to focus on growth, rather than worrying about what could go wrong. The right insurance policy signals professionalism and reliability, reassuring clients, partners, and lenders. Many large clients or landlords won’t enter contracts unless a business can show proof of adequate coverage. This trust factor is essential for winning new deals and maintaining long-term relationships.
Additionally, working with an insurance broker can provide valuable support during claims. These experts help navigate paperwork and negotiations, ensuring fair treatment and speedy resolutions. With their guidance, business owners can get back to work faster after a loss and avoid costly mistakes.
Every small business faces unique risks. A restaurant might be concerned about fire or food safety, while a consultancy might worry about professional errors. Common types of commercial insurance include general liability, property protection, and professional liability. It’s important to map risks and buy policies tailored to actual exposures, rather than relying on generic plans or picking coverage based solely on price.
Regular reviews and updates are critical, as coverage should reflect business growth and changes. What worked when a business started may become inadequate as revenue and staff increase. Annual check-ins with a broker can help keep insurance aligned with current needs.
It’s important to know what commercial insurance does not cover. Most policies exclude routine wear and tear, intentional acts, criminal activities, and government fines. Some disasters, like major floods or earthquakes, require separate endorsements. Understanding exclusions allows business owners to add extra protection as needed and avoid surprises during a claim.
For small businesses, commercial insurance is not just worth it; it’s essential. It protects years of hard work and investment, ensures legal and financial security, enhances credibility, and offers expert support in times of crisis. Investing in the right coverage isn’t just good business sense; it’s the key to long-term stability and peace of mind.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulation | Sep 24, 2025

Image: Freepik
On September 13, 2025, Thailand froze approximately 3 million bank accounts in a sweeping anti-scam campaign. Authorities targeted around 177,000 mule accounts linked to fraud. Wisit Wisitsora of Thailand’s Digital Economy and Society Ministry stated:
“We urge the public not to panic. The suspension is only temporary.”
Banks imposed daily transfer caps ranging from 50,000 to 200,000 baht (approx. $2164 CAD - $8657 CAD at today's forex rates) and froze flagged transactions.
Commercial banks could suspend funds for three days, with police empowered to extend freezes up to seven days. While designed to curb online fraud, many individuals and small businesses described being locked out of their only source of funds, leaving households unable to pay for food or bills.
Facing backlash, regulators introduced safeguards. Innocent users can now expect restoration within hours to one day. Banks are required to notify customers of freezes via SMS or mobile banking and to unfreeze wrongly blocked funds proactively. Officials emphasized that disputed amounts are suspended, not entire balances.
Around the world, regulators from the EU to the U.S. and Canada are grappling with similar challenges as regulators expand digital fraud controls. What the Thailand case shows is that the credibility of financial systems depends not only on the strength of anti-scam tools but also on transparent safeguards.
If freezes become a blunt instrument, they risk driving people out of regulated channels and weakening financial inclusion. For fintechs and policymakers, the global lesson learned is that fraud prevention must be paired with due process to preserve trust.
Fraud-related losses in Thailand exceed 6 billion baht annually (approx $200M CAD), but freezing millions of accounts without due process undermines trust in banking.
"The Thai case clearly shows the risk when rapidly scaled enforcement collides with consumer rights. Without transparent criteria, real-time notifications, and clear appeals, innocent users face financial harm."
Legal experts warn this could expose authorities to civil claims and property rights challenges. What if citizens turn to cash, crypto, or unregulated channels instead?
Canada faced a similar backlash during the 2022 trucker protests, when the government invoked the Emergencies Act and froze over 200 bank accounts containing nearly $8M CAD without court orders. The measures were lifted within days, but the incident triggered several knee jerk reactions and lasting debate about transparency, due process, and the role of financial institutions in enforcing emergency powers.
Similar debates are underway in other regions, such as the United States with proposals like the Fairness in Banking Act, which NCFA has examined for its consumer protection impact. The common challenge is ensuring that stronger enforcement powers don't override due process or weaken trust in financial systems.
Both the Thailand crackdown and the Canadian freeze highlight how well intentioned interventions can spiral into government overreach if consumer safeguards are weak. Independent oversight, transparent criteria, communication protocols, and effective redress mechanisms are essential.
As fintechs use AI to spot fraud, regulators need to keep rules fair and accountable. Protecting consumers while keeping trust in financial services is key to Canada’s future growth and inclusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016