




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


January 30, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Payments And Money Movement, Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization, Open Banking Open Finance And Data Sharing

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026)
Payment activity, API demand and recurring use increased while system performance remained stable. The figures establish an operating benchmark for countries building open banking around data access, payment initiation and commercial services. The later one billion payment milestone shows how quickly that base continued to expand.
Once a PSP can join the payments club directly, it can cut onboarding friction, tighten settlement and reconciliation, and show stronger operational maturity to banks, enterprise buyers, and regulators. Founders that treat membership readiness as an operating system will move faster when big partners demand proof. Investors should watch which PSPs turn access into volume and repeatable unit economics, not just press.
This is a planning signal for how the UK approaches AI in retail finance. Firms that sell into regulated buyers win time if they can show who owns outcomes, how models get tested, and how controls work across vendors and data flows. Teams that cannot evidence that quickly will find AI work slows down at the point of trust, not the point of build.
This matters to fintechs that sell into regulated buyers because coordination changes the buyer checklist. The winners standardize controls and reporting across spot, derivatives, custody, and settlement workflows so they do not rebuild the stack every time definitions and boundaries tighten.
This takes tokenization out of the hype lane and into build discipline. If you sell tokenized security rails to real institutions, you win deals when you answer the hard questions fast, who controls the record, how transfers stay legally effective, and where the product plugs into broker dealer, transfer agent, and clearing and settlement expectations.
This move embeds regulated stablecoin issuance directly into a global payments platform instead of leaving it at the edge. When stablecoins sit inside licensed EMI rails, settlement, liquidity management, and compliance become part of the core payments stack. Founders building wallets, FX, treasury, or cross border infrastructure should expect buyers to favor platforms that combine regulated issuance with distribution at scale.
A federal trust structure offers nationwide reach, clearer supervision, and stronger institutional credibility. Fintechs selling custody, settlement, compliance, or risk tooling should prepare for customers that operate under bank grade expectations. Investors should watch which applicants can survive the supervision burden that comes with federal status.
This pulls crypto compliance into product planning. Teams that want UK market access move faster when they convert these rule areas into workflows early, especially safeguarding, reporting, and accountable ownership across senior roles.
Payments access expands in Canada while regulators in the UK and US push firms toward clearer accountability in AI, crypto, and tokenized securities. The common thread is execution readiness. Buyers now ask who owns the record, who controls outcomes, and how a platform proves it can operate under supervision without slowing down. Fintechs that build for audit, governance, and market access early earn trust faster and avoid costly rebuilds when rules tighten around custody, settlement, and consumer outcomes. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jan 30, 2026 | NCFA Fintech Market Activity | Funding and Ecosystem
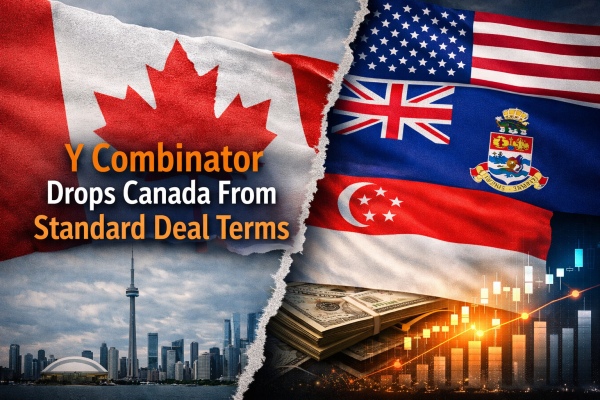
On January 26 2026, Y Combinator updated its standard deal terms to limit eligible investment jurisdictions to the United States, Cayman Islands, and Singapore. Canada no longer appears as a jurisdiction where YC will invest directly under its standard structure.
The financial terms remain unchanged. YC continues to offer $500,000 per company, split between $125,000 for a fixed 7% equity stake and $375,000 on an uncapped MFN SAFE. YC also states it can assist founders with incorporation if they have not yet formed a company.
The practical impact for Canada based founders is immediate. Teams can still apply to YC, but a Canadian incorporated startup must now establish a parent company in one of the eligible jurisdictions before YC completes the investment. That moves incorporation decisions forward in the startup lifecycle, often before product market fit or initial customer traction.
This matters because corporate structure is not a paperwork detail. It affects ownership control, intellectual property placement, option plans, investor rights, tax exposure, and the mechanics of future fundraising. What was once handled after a seed round now sits directly on the path to accelerator participation.
YC’s decision also highlights how early stage capital increasingly flows through standardized structures. Accelerators and seed funds optimize for speed and repeatability. When jurisdiction narrows, founders adapt by default, even if their teams, customers, and operations remain Canadian.
When access to top accelerators depends on jurisdiction first and execution second, how early should founders be forced to trade structural flexibility for capital velocity?
This is not a withdrawal from Canadian talent. It is a capital routing decision. But when global accelerators set the defaults, those defaults shape where companies incorporate, where value accrues, and how national ecosystems compete for long term upside.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 27, 2026 | NCFA Fintech Market Activity | Capital and Funding
Image: Freepik AI
On January 27 2026, CVCA and the Government of Canada’s Trade Commissioner Service released the 2026 edition of The 50, an annual guide that presents Canada’s venture capital market to international investors, strategic partners, and market participants.
The release makes two practical points that matter for founders and fund managers. First, The 50 does not rank firms. It profiles venture managers across sectors including software, applied artificial intelligence, life sciences, and advanced technologies. Second, it is built to travel. CVCA says the guide supports engagement through the Trade Commissioner Service global network spanning more than 160 cities worldwide.
That distribution detail is the real asset. Canadian venture often struggles with visibility outside the usual circles. A guide that is designed for outbound use changes how conversations start with foreign limited partners, corporate partners, and co investors. It also helps founders understand which managers actively shape the market today, not just who raised a big fund last cycle.
Brenda Hogan, Chief Investment Officer, Venture Ontario, and Chair, The 50 Committee:
“Canada’s venture market is defined by managers who combine discipline with the ability to support companies as they scale across markets. The firms included here reflect that reality. They are backing businesses that operate globally, manage capital carefully, and deliver outcomes investors can underwrite with confidence.”
If you want the working version, CVCA hosts the guide online. You can explore The 50 2026 edition directly.
The timing also ties into deal flow and capital conversations in 2026. CVCA notes that international investors and partners can engage with Canada’s private capital community at Invest Canada ’26, taking place May 26 to 28 2026 in Halifax, Nova Scotia.
If Canada wants more cross border capital and more late stage wins, what changes first, the number of global investor relationships, or the quality of proof points that keep them coming back?
This release is akin to market infrastructure for capital. When more global investors can quickly understand who deploys capital in Canada and how those managers operate, founders get more shots at the right conversations, earlier.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 29, 2026 | NCFA Fintech Market Activity | Insurtech and Automation
Image: Freepik/rawpixel.com
On January 29 2026, Manulife Canada announced changes to its life insurance application process that allow eligible applicants to receive automated approvals in as little as two minutes.
The update combines a redesigned digital application with enhancements to Manulife’s AI driven underwriting engine, MAUDE. According to the release, the new workflow eliminates many manual steps that previously added days or weeks to approval timelines for straightforward policies.
Manulife reports that the updated process now supports instant decisions for a broader set of low risk applicants. In cases that still require review, the system routes applications more efficiently by pre screening risk factors before human involvement.
The operational impact is material. Life insurance underwriting traditionally relies on paper based forms, medical questionnaires, and extended back and forth with applicants. Compressing approvals to minutes reduces abandonment, shortens sales cycles, and lowers per policy acquisition costs.
The release also highlights that Manulife’s digital life insurance business has grown steadily as customers shift toward online purchasing. Faster approvals support higher conversion rates while reducing pressure on underwriting teams as volumes scale.
This is not a cosmetic change. Automated underwriting at this speed requires confidence in data quality, model governance, and exception handling. Errors scale as fast as efficiency. That makes oversight, auditability, and fallback paths just as important as speed.
Karen Cutler, Chief Underwriter, Manulife Canada:
"Since launching last fall, advisor adoption has been strong. By December, more than half of eligible cases – 58% had approvals processed automatically through MAUDE, a 56% increase from pre-launch. By combining smarter questions with advanced AI, we're delivering a faster, more intuitive experience – without compromising on quality or protection."
If two minute approvals become the baseline for simple policies, where do insurers deliberately slow the process to manage risk, trust, and regulatory expectations?
Manulife’s update shows how artificial intelligence in insurance has moved past pilots. The competitive gap now sits between firms that embed automation directly into core underwriting and those still layering digital tools on top of legacy processes.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 29, 2026

Сontinuous assessment education is one of the defining features of the Canadian school system and a major reason why its graduates adapt so successfully to university life. Unlike exam-centric models that concentrate performance into a single high-pressure test, Canadian schools evaluate students continuously through coursework, projects, presentations, and teacher feedback. This approach mirrors how learning is measured at universities and helps students build confidence, consistency, and independence long before they begin higher education. Schools such as Toronto Imperial School apply this model within the Ontario Secondary School Diploma (OSSD), giving international learners a structured pathway that aligns closely with university expectations worldwide.
At its core, continuous assessment education shifts the focus from memorization to mastery. Students are encouraged to demonstrate understanding over time, refine their thinking through feedback, and apply knowledge in practical contexts. For families planning international education pathways, this difference matters: universities increasingly look for applicants who can manage complex workloads, communicate clearly, and sustain academic performance across a semester. The Canadian approach develops these qualities by design.
The Canadian school assessment system is built around ongoing evaluation rather than a single end-of-year exam. In OSSD programs, students earn grades through a balanced mix of assignments, quizzes, essays, projects, and presentations. Teachers provide regular feedback, allowing students to improve their work and deepen understanding as the course progresses. This structure encourages responsibility and time management—skills that are essential once students enter university.
Toronto Imperial School follows Ontario’s standards to deliver this system online, ensuring that international students experience the same expectations as learners studying in Canada. Coursework is carefully sequenced so students build skills incrementally: researching sources, structuring arguments, collaborating on tasks, and presenting ideas clearly. Because assessment is continuous, students learn to plan ahead and meet multiple deadlines—an everyday reality in higher education.
Although lists are used sparingly, it helps to clarify the types of learning activities commonly assessed:
These components collectively reflect how universities assess students, making the transition smoother and more predictable.
The OSSD assessment model is particularly effective at preparing students for academic life after high school. Universities expect learners to synthesize information, argue positions with evidence, and manage long-term projects. Because the OSSD emphasizes these tasks throughout secondary education, students are not encountering them for the first time at university.
At Toronto Imperial School (https://torontoimperial.com/), continuous assessment is paired with mentorship and academic guidance. Students receive support in organizing workloads, understanding evaluation criteria, and responding constructively to feedback. This combination fosters resilience and self-reflection—qualities that help students adjust to the independence of university study. Rather than relying on last-minute revision for a final exam, students practice sustained effort and iterative improvement, which closely matches university grading practices.
Another advantage is transparency. Continuous assessment provides a detailed academic record that shows progression over time. Admissions teams can see not only final grades but also the rigor of coursework and consistency of performance. This clarity strengthens applications and reassures universities that applicants are prepared for demanding programs.
Continuous assessment education creates a learning environment where progress is measurable, feedback is actionable, and improvement is expected. Graduates accustomed to this system arrive at university ready to engage with complex material, manage competing priorities, and take ownership of their learning. These outcomes are not accidental; they are the result of a deliberate assessment philosophy embedded in Canadian education.
By delivering the OSSD through an online platform aligned with Ontario standards, Toronto Imperial School extends these benefits to international students. Learners can access structured coursework, receive timely feedback, and develop university-ready skills regardless of location. This portability, combined with rigorous assessment, makes the Canadian model especially attractive for families planning global education pathways.
In an era where universities value consistency, critical thinking, and adaptability, continuous assessment stands out as a proven preparation method. It equips students with the habits and competencies they need to thrive beyond high school, turning assessment into a tool for growth rather than a single moment of judgment. For students aiming to succeed in higher education, the Canadian approach offers a clear advantage built on continuous assessment education.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 26, 2026 | NCFA Fintech Market Activity | Payments and Consumer Finance
Image: Freepik
On January 14 2026, Klarna launches instant peer to peer payments in 13 European countries, letting customers send money to friends and family directly inside the Klarna app for everyday moments like splitting a bill or gifting cash.
Klarna says the rollout is part of its wider push into day to day banking. The company links this launch to Klarna Balance accounts and to early traction for Klarna Card, where it reports over 4 million sign ups in four months.
Sebastian Siemiatkowski, Co Founder and Chief Executive Officer, Klarna:
“Customers are sick of the friction and fees of traditional banking, which is why millions signed up to Klarna Card within a few months of launch. With peer to peer payments we’re making it even easier to manage all of your payments through Klarna, now including small transfers, making managing your money quicker, easier, and cheaper.”
The product mechanics stay simple. Users pick a recipient by phone number, email address, QR code, or saved contact. Klarna then runs fraud and eligibility checks before it sends the payment. Klarna starts with transfers between Klarna users and says it plans to expand to transfers to non Klarna users and to cross border payments.
The country list makes the scale concrete. Klarna launches the feature in Belgium, Denmark, Finland, France, Germany, Italy, Netherlands, Norway, Poland, Portugal, Spain, Sweden, and the United Kingdom.
Klarna also ties the rollout to momentum in its banking products. It reports that global deposits increased from $9.5bn to $14bn by September 2025 after the introduction of Klarna Balance in August 2024. It also reports that card payments now make up 15% of total volume.
This release reads like a straightforward product launch, but it carries a deeper operating message. When a consumer finance app adds instant transfers, it moves closer to becoming the place users keep returning to. That changes how a brand competes. Users start comparing it less to checkout tools and more to whatever they use as their default money app.
When more consumer fintechs add peer to peer transfers, what keeps trust intact, clear fees, clear limits, clear recourse, or something else?
Klarna says its peer to peer payments run on traditional banking rails today, and it also says its exploring stablecoin-based options to improve speed, reach, and efficiency. The short term litmus test is whether Klarna can make transfers feel effortless without introducing new confusion around eligibility, disputes, and consumer expectations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Risks | Jan 28, 2026
Image: Freepik
On January 27, 2026, a landmark trial begins in Los Angeles Superior Court that forces major tech companies to explain how their algorithms work. The defendants include Meta and YouTube, as both TikTok and Snap reached a settlement just before trial, leaving Meta and YouTube to proceed before a jury.
Hundreds of families, teens, and school districts accuse social media platforms of intentionally designing products that keep young people addicted. The scale is hard to ignore. The coordinated cases include roughly 1,600 plaintiffs, more than 350 families, and about 250 school districts.
The first trial focuses on a 19 year old identified as KGM and is expected to last six to eight weeks. It is the first of about 22 test cases that will guide how thousands of similar lawsuits proceed. A separate federal case involving more than 235 plaintiffs, including attorneys general from nearly three dozen U.S. states, is scheduled to begin in San Francisco in June 2026.
This isn't just a social media story. Courts are no longer looking only at what people post. They are looking 'under the hood' at how systems are built to see if and how algorithms are influencing behaviour at scale.
For years, technology companies leaned on Section 230 of the Communications Decency Act, passed in 1996 to avoid liability tied to online activity. That protection still exists for user generated content. What changes here is the focus. Judges are allowing these cases to proceed because the claims target design choices.
Plaintiffs argue that features like infinite scroll, video autoplay, notifications, and recommendation systems encourage compulsive use. In a November 2025 ruling, the judge ruled that jurors must examine platform design choices rather than focusing only on user generated content.
That opens the door to evidence most companies prefer to keep internal. Product research, feature testing, internal discussions, and decision making around engagement will now move into public view. The question's are simple and uncomfortable. Why did the system work this way?
The plaintiffs seek more than damages. They also ask the court to order changes to how the platforms operate, which could set safety rules for the whole industry. If courts agree that algorithm design causes harm, the impact reaches far beyond a single verdict.
Executives from the biggest platforms may testify, including leaders from Meta, YouTube, Instagram, and Snap. Plaintiffs openly compare their strategy to tobacco cases from the 1990s, where internal documents and sworn testimony changed how courts and the public viewed addiction.
Recent settlements highlight the pressure cooker. Snap settled shortly before trial in one lead case. TikTok settled hours before jury selection began. Financial terms stay confidential, but the timing confirms risks companies would prefer not to explain in court.
These trials are taking place at a time when algorithms do more than recommend content. They adapt, learn, and optimize constantly. Modern systems adjust in real time based on user behaviour. Reinforcement loops scale instantly.
In January 2026, Anthropic chief executive Dario Amodei warns that AI risks are arriving faster than governance can keep up. In a 19,000 word essay called, 'The Adolescence of Technology", he writes:
“Humanity is about to be handed almost unimaginable power, and it is deeply unclear whether our social, political, and technological systems possess the maturity to wield it.”
Courts are now peering into that gap. When rules lag and impact grows, litigation becomes a way to force transparency. Judges and juries start asking questions regulators have not yet answered.
Financial services already run on algorithms. Credit decisions, fraud detection, transaction monitoring, pricing, robo advice, and nudges all rely on systems that influence user behaviour. These lawsuits do not accuse fintechs of wrongdoing, but they can change how accountability works.
If courts see algorithm design as a product choice that predictably affects people, then how those systems are built really matters. Why a system pushes certain outcomes, what it favours, and where it slows users down can end up being questions for a judge or jury, not just a product team.
For founders and institutions, it's about building systems you can explain. Clear design goals, documented tradeoffs, and guardrails reduce exposure and build trust with users, partners, and regulators.
As plaintiffs’ attorney Matthew Bergman puts it, “The fact that a social media company is going to have to stand trial before a jury … is unprecedented.” Courts now ask companies to explain their design decisions in plain language, under oath, and in public. That expectation will not disappear. Innovation keeps moving fast. Accountability now moves with it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016