




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 26, 2026 | NCFA Feature | Digital Assets Blockchain And Tokenization
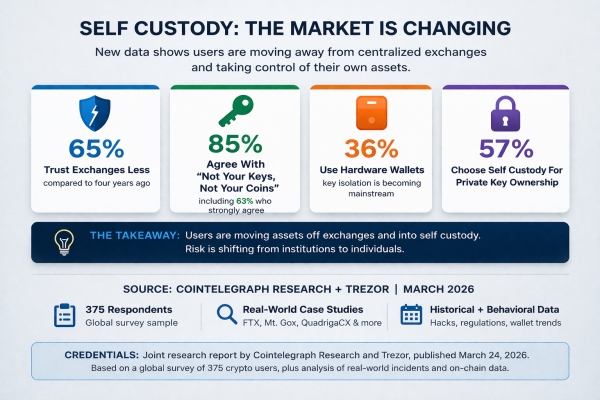
On March 24 2026, a Cointelegraph Research and Trezor report on self custody behaviour put hard numbers behind the trend that's been building for years. Trust in centralized platforms keeps falling. At the same time, self custody is moving out of the expert corner of crypto and into the mainstream for serious users.
The report draws on 375 survey responses and pairs that data with real world exchange failures, wallet design analysis, and a sober look at where users still get hurt. People have watched enough platforms fail, and now they're changing how they hold assets.
A combined 65% of respondents say they trust centralized exchanges less than they did four years ago. Of that group, 45% say they trust them much less and 20% say they trust them a bit less
33% point to exchange hacks as the main driver. 27% point to collapses such as FTX. Another 26% point to regulatory restrictions.
The trend matches the market’s recent history. FTX exposed an estimated $8B hole in customer funds. QuadrigaCX collapsed amid fraud and broken internal controls. Mt. Gox lost about 850,000 BTC after years of theft and system failures.
The deeper issue is structural. Centralized platforms gather large pools of assets behind a small number of operational and administrative control points. That concentration makes them efficient in good times, but it also makes them attractive targets when something goes wrong. One breach, one fraud, one breakdown in controls, and the damage can spread fast.
Users aren't just frustrated. They're acting on it.
A striking 85% of respondents agree with the phrase “not your keys, not your coins.” That includes 63% who strongly agree. It's becoming standard thinking for people who want lasting control over digital assets.
When asked why they use self custody, 57% say private key ownership is the main reason. Another 24% say maximum security drives the decision.
Most respondents say they would not leave assets on a custodial exchange for more than one month, even without an immediate panic event. In practice, exchanges are starting to look less like vaults and more like temporary access points.
One of the clearest data points in the report is that 36% of respondents actively use hardware wallets.
A hardware wallet keeps your private keys off your phone or computer. You set up a transaction on your device, then confirm and sign it on the hardware wallet. The keys never leave the wallet. This lowers the risk of malware, hacks, and common theft methods.
Hardware wallets protect your keys, but they don’t protect your decisions. They can confirm a transaction comes from your device, but they can’t always tell if you fully understand what you’re approving.
Phishing is still one of the biggest risks. Attackers copy real wallet brands, fake support messages, and trick users into giving up their recovery phrase. Once that’s exposed, the funds are usually gone.
Blind signing is another major issue, especially with smart contracts. Users approve transactions without fully understanding what they do. The report highlights a real case where a malicious approval led to a $1.4B loss. That alone shows self custody is not just about buying a device and feeling safe.
Supply chain risk is also real. Some people buy wallets from unofficial sellers and receive devices that have been tampered with or come with preset seed phrases. It compromises the user before self custody even begins.
Physical security is becoming more serious as well. The report cites 74 publicly reported physical attacks on crypto holders in 2025, with at least 9 already recorded in January 2026. These are real world attacks tied to visible holdings and weak operational privacy.
Then there is the quieter problem that rarely gets enough attention, which is backup failure. The report estimates that roughly 10% of circulating Bitcoin supply may already be lost because users mismanage recovery material or lose access entirely. It reminds the market that the biggest long term risk in self custody may not be theft alone. It may be preventable self inflicted loss.
Another useful part of the report is its treatment of regulatory risk. Users are not only responding to hacks and insolvencies. They are also responding to the fact that access to funds can be interrupted, such as payment rail seizures, exchange shutdowns, withdrawal suspensions, and enforcement actions that cut off access to custodial accounts. Different cases arise from different legal and operational reasons.
Users who worry about counterparty exposure, platform freezes, or policy driven restrictions increasingly want a self custody setup they can control directly.
Digital wallets are becoming core control layers in digital asset finance. That assumes customers will keep meaningful balances on platform for long periods of time.
The next real product gap is not only stronger key storage, but clearer intent verification. Users need to know what they are signing, why they are signing it, and what will happen next. That means readable transaction flows, better simulation tools, stronger warnings, clearer address handling, and far less dependence on users interpreting raw contract data on the fly.
Security is central to the user experience. The firms that reduce confusion, expose hidden risk, and make recovery practices easier to manage will offer a match better product experience than companies that assume security begins and ends with cryptography.
Finally, distribution and engagement models will keep changing as assets move off centralized platforms and into user controlled environments. Markets are evolving toward wallet centered ecosystems, service layers, and infrastructure that works with user sovereignty rather than around it.
Ownership does not create security on its own. Security comes from repeated good practice. Users need to verify transactions carefully, protect recovery material, source devices properly, and think through physical as well as digital threat models. Put differently, self custody is not a static product state. It is an operating discipline.
Self custody is no longer a niche behaviour reserved for maximalists, techies, and power users. It is becoming a natural response to broken trust in centralized custody. It moves responsibility away from institutions and toward individuals, which means the next generation of financial products must do more than secure assets. They must help people operate safely in a digital finance world.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 26, 2026 | NCFA Fintech Market Activity | Banking And Credit, Digital Assets And Tokenization
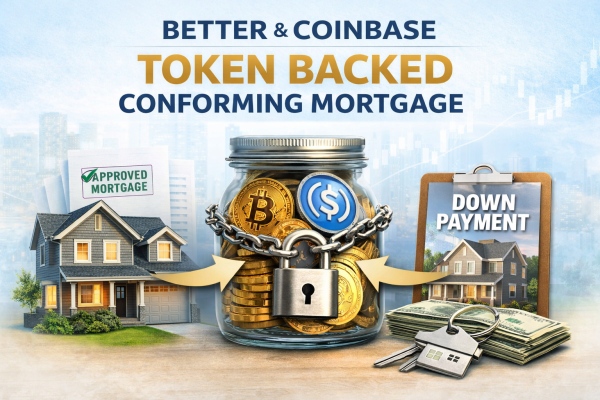
On March 26, 2026, Better and Coinbase launched the first token backed conforming mortgage. Qualified borrowers can pledge Bitcoin or USDC to fund a cash down payment while still taking out a standard mortgage that meets Fannie Mae rules. The structure lets borrowers use digital assets without selling them first and without automatically triggering a taxable sale event.
The product targets a large and growing borrower base. Better and Coinbase put the addressable market at 52 million Americans who own digital assets, equal to 20% of American adults. They also mention quite an age split, with 45% of younger investors holding crypto versus 18% of older investors. That age gap means it's much harder for younger buyers to meet traditional down payment cash requirements, yet many already hold part of their savings in digital assets.
There are no margin calls and no required top ups if Bitcoin falls in value. Price moves alone do not trigger liquidation. Collateral comes into play only if a borrower becomes 60 days delinquent, under the same treatment applied to standard conforming mortgages. Borrowers using USDC can also earn rewards on pledged balances, which may offset mortgage payments and lower the net effective rate.
The buyer profile is also broader than a luxury crypto niche. Better and Coinbase said 67% of token holders are 45 or younger and 26% earn less than US $75,000 a year. They also pointed to Redfin data showing 12.7% of Gen Z and Millennial homebuyers have already sold tokenized assets to fund a down payment, versus 3.5% of Gen X and 0.5% of Baby Boomers.
Digital assets are now included in standard mortgage structure, not just a trading or investment account. Token holdings now help fund a conforming mortgage down payment without forcing a sale first. As this model grows, digital assets will look less like something borrowers need to liquidate and more like collateral lenders may be willing to work with.
Better and Coinbase also plan to expand eligible collateral over time to include tokenized equities, fixed income, and tokenized real estate assets. If that happens, the story will not stop at mortgages. It will continue to proliferate into which consumer lending products can absorb token backed collateral and under what terms.
If digital assets can now help fund a conforming mortgage, which standard lending products could be next to accept token backed collateral?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 25, 2026 | NCFA Fintech Market Activity | Digital Assets And Tokenization
On March 25, 2026, BitGo added qualified custody support for USDCx and cBTC on the Canton Network. This expands its role on Canton beyond Canton Coin and into CIP-56 assets, the token format Canton uses for regulated financial markets.
The CIP-56 token standard supports private transactions, built in KYC and AML controls, delivery versus payment settlement, and final settlement within seconds. Those features give institutions the controls they need to use tokenized assets in real collateral and settlement workflows.
Canton describes itself as a privacy enabled blockchain network for institutional assets, with about 600 validators live and more than 15 million monthly transactions using Canton Coin in their flows. That's why BitGo's expansion is interesting because it plugs additional assets into a network that's already being built for regulated financial activity, not retail token trading.
USDCx already serves as the settlement currency for out of hours repo settlement and tokenized collateral workflows on Canton. It is issued through Circle’s xReserve framework. cBTC adds bitcoin backed liquidity to the same environment, giving firms another asset they can use across collateral and settlement activity. This isn't just broader token support. It makes the settlement layer more usable.
Qualified custody for Canton Coin launched in October 2025, and token support followed in less than six months. The work is no longer just about putting assets onchain. It is about building the custody, collateral, and settlement stack that institutions need around them.
Canton is also drawing in more institutional infrastructure, including tokenized money market fund infrastructure from Goldman Sachs and BNY. This BitGo move adds another piece to the same buildout. If tokenized finance is going to work at scale, firms need more than issuance. They need custody that institutions trust, settlement assets they can use, and compliant rails that hold up under real volume. That's where commercial value is starting to concentrate.
As tokenized markets add stablecoin settlement, bitcoin backed liquidity, and qualified custody, which firms become hardest to replace?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 25, 2026 | NCFA Fintech Market Activity | Payments And Money Movement
On March 25, 2026, Chexy closed a $14M Series A led by Khosla Ventures. Co-founder and CEO Liza Akhvledziani Carew said the company started by helping renters earn rewards on their biggest monthly expense, then grew into “something much bigger: a new way for money to move in Canada.”
Chexy’s own numbers speak for themselves. The company says it now supports 5,000+ businesses, $1B+ in annual payments, and $20M in rewards value. That's certainly not a narrow rent rewards story and points to a scaling payments company for businesses.
The company has already shown that rent can work as an entry point. In its first year, the company said it processed $30M in rental payments and generated $1M in rewards value. Now Chexy’s business offering has expanded considerably, including supplier payments, commercial rent, payroll, corporate tax, GST and HST remittance, payroll remittance, and property tax. This wider mix of recurring payments gives the company more ways to increase usage and build a deeper payments relationship.
While Chexy is part of the trend where rent and housing payments pull more fintech models into consumer finance, it's broadening it's model built around payments rather than point of sale credit. And the capital gives the fintech more runway to build and grow.
If rent brings users in, which payment flows give Chexy the best chance to become a durable Canadian money product?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 25, 2026 | NCFA Insight | Regulation And Policy, Capital Markets And Market Infrastructure
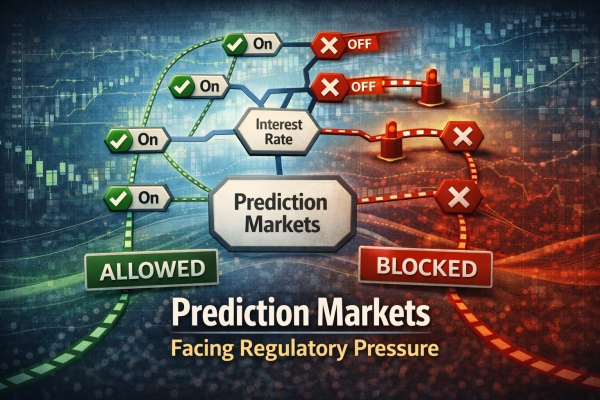
Sports volume built the business. Now rules, surveillance, and product limits will decide who lasts. On March 23, 2026, a bipartisan Senate bill moved to ban sports and casino style contracts on CFTC registered prediction market venues. The Senate release said a March Madness winner contract had already passed $100M in trading volume and that Super Bowl prediction market volume topped $1B in 2026.
Those numbers explain why prediction markets are now under direct pressure from lawmakers. Prediction markets are no longer fringe. They now sit in a fight over who regulates them, which contracts stay allowed, and whether the business still works under tighter rules.
Sports helped prediction markets reach a wide audience fast, but that same growth put them in direct competition with state regulated sportsbooks and tribal gaming interests. The Prediction Market Senate bill to ban sports contracts is aimed straight at that overlap. It would prohibit any CFTC registered entity from listing contracts that closely resemble a sports bet or a casino style game. If it advances, sports contracts would be the first part of the business to take a hit. That in itself wouldn't kill prediction markets, but it would force a reset around contracts that look more like economic, financial, or commercial forecasting and less like entertainment wagering.
Sports contracts brought scale, attention, and league partnerships. NCFA looked at that earlier when the NHL partnered with Kalshi and Polymarket. Sports now look like the part of the business most likely to trigger a stronger federal and state response.
Polymarket and Kalshi tightened their controls on the same day. On March 23, Polymarket tightened its market integrity rules across both its DeFi venue and its CFTC regulated US exchange. The updated rules ban trading on stolen confidential information, illegal tips, and outcomes a trader can influence.
Kalshi added candidate and athlete trading bans covering political candidates, athletes, referees, coaches, and team staff, and introduced a whistleblower feature to tighten insider risk controls.
These aren't minor changes. They prove Kalshi and Polymarket understand that insider risk is now a live issue. Prediction markets want to be treated as financial infrastructure, but financial infrastructure has to show it can police insiders, document rules, and respond fast when abuse appears. NCFA covered that tension earlier when prediction markets started pricing geopolitical events.
Canada is taking a narrower approach. The Globe and Mail reported today that Wealthsimple cleared a regulatory hurdle to offer forecast contracts in Canada, but only for economic indicators, financial markets, and climate trends. Sports and election contracts are out. Wealthsimple is the second firm to receive this approval in Canada, after Interactive Brokers Canada.
Interactive Brokers Canada has positioned contracts around government, economic, finance, and climate events, not sports books in a different wrapper. The product is already live in Canada on that basis.
Wealthsimple now brings local retail distribution, stronger brand reach, and a better chance of testing whether forecast contracts can find a market here without leaning on the sports volume that pushed the US fight into the open.
Can a prediction market still grow once sports contracts face a ban, insider screening gets tighter, and compliance costs rise? Some firms may adapt by leaning into macro, rates, inflation, climate, earnings, and other information markets. Others may find that the most profitable contracts were also the ones most likely to trigger a crackdown.
The CFTC is also reviewing the rules. On March 12 2026, the CFTC opened an Advance Notice of Proposed Rulemaking on prediction markets and asked for public comment on which event contracts may be contrary to the public interest, how current rules apply, and what changes may be needed. That means this fight is not limited to one Senate bill or one week of headlines. The federal rule in the U.S. is now under review.
For Canadian dealers, fintechs, and market operators, there is room to build forecast products here, but the lane is narrower than in the US.
Prediction markets already proved they can attract users and volume. The next test is whether prediction markets can still grow once product limits tighten, regulators draw a harder line around what is allowed, and compliance demands rise.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 26, 2026
Airbnb was founded by Brian Chesky and Joe Gebbia in 2008. They started their business on a shoestring budget, offering air mattresses on the floor for rent during a conference in San Francisco. The pair placed an advert offering a cheap room or ‘bed space’ with breakfast. As a result, they made a decent profit, which allowed them to pay the rent.
Money was needed to maintain the website offering mattresses for overnight stays. At the time, the election campaign was in full swing. The main frontrunners were Barack Obama and John McCain. The budding entrepreneurs bought cheap cereal and boxes and released limited-edition ready-made breakfasts with a personalised number and a high price tag of $40. The cereal cost just $1 per box. Thanks to media coverage and social media, the Obama boxes sold out in three days. The idea brought in $20–30,000.
It was from such a simple idea that the story of a company began, one that is now familiar to literally everyone.
Take a break from work and ideas – have some fun here Voltage Bet - online sportsbook
Oculus was founded in 2012 by Palmer Luckey, who created the first prototype of a virtual reality headset. By the age of 22, he was already worth $500 million. Out of curiosity, he collected a range of outdated virtual reality devices. One day, Laki managed to buy a headset that had once sold for $97,000 for just $87. To expand his collection, Laki taught himself electronics: he bought broken iPhones, repaired them and sold them on at a higher price. That’s how he made $30,000.
These unsuccessful older models became the basis for new developments. Palmer was simply an enthusiastic teenager who loved video games and science fiction films. It was solely through his enthusiasm and passion that the young man was able to create what experienced engineers had been trying to do before him.
Slack was created in 2013 as a tool for internal company communication. Tiny Speck, a company founded by Stewart Butterfield, developed the game Glitch, which flopped. However, in the process, a communication tool was created that became the foundation for Slack. The messenger with advanced functionality was launched in 2014. The platform quickly gained popularity by solving the problem of fragmented workplace communications.
Key factors in its success were word of mouth, an open platform with an API for integrating apps and bots, and a focus on organisational transformation. Slack works with competitors and offers integrations with various services: Google Calendar, Zoom and Microsoft Teams.
The company considers building an ecosystem to be a successful model for growth and meeting user needs. So it turns out that, by solving its own problems and challenges, the team created a service that many companies need.
The brand’s history began in 1965, when its founder, Fred DeLuca, opened a sandwich shop in Connecticut at the age of 17. This was how the future businessman decided to earn money to pay for his medical studies.
Peter Buck, a friend of his father’s, helped Fred open his first eatery, providing $1,000 to develop the business. Fred and Buck became business partners and were ‘fired up’ by the idea of creating a chain of restaurants across the state. DeLuca put his dream of becoming a doctor on hold and began learning the ropes of running a business. It is worth noting that in the early days, Fred made the sandwiches himself and managed to cope with the large flow of customers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 24, 2026
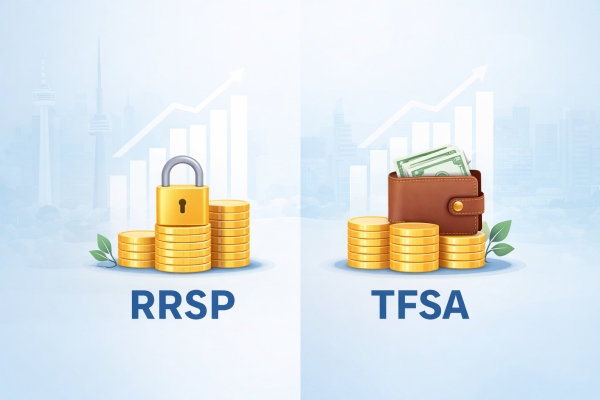
If you're a high-earning Canadian trying to build wealth, you've likely been told to "max out your RRSP" or "use your TFSA first." The advice often sounds definitive - but rarely accounts for your actual situation. Both accounts offer powerful tax advantages, yet they work in fundamentally different ways. Choosing between them isn't just a tax question; it's a behavioral and strategic one that depends on your income trajectory, spending patterns, and psychological relationship with money.
Understanding how RRSPs and TFSAs actually function - and how your brain responds to each - can help you make smarter decisions that stick.
The Registered Retirement Savings Plan (RRSP) is a tax-deferred account. Contributions reduce your taxable income in the year you make them, and your investments grow tax-free inside the account. You pay tax only when you withdraw, ideally in retirement when your income - and tax rate - are lower. For 2024, the contribution limit is 18% of your previous year's earned income, up to $31,560. [1]
The Tax-Free Savings Account (TFSA) works differently. You contribute with after-tax dollars - no immediate deduction - but all growth and withdrawals are completely tax-free, forever. The 2024 contribution limit is $7,000, with cumulative room of $95,000 if you've been eligible since the TFSA launched in 2009. [2]
Both accounts shelter investment gains from annual taxation, which is their shared superpower. The difference lies in when you pay tax and how withdrawals affect your future finances.
The classic rule of thumb: if your tax rate is higher now than it will be in retirement, the RRSP wins. If your rate will be the same or higher later, the TFSA is better. [3]
For high earning $150,000+ in provinces like Ontario, the combined federal-provincial marginal rate can exceed 43%. [4] An RRSP contribution at that rate delivers an immediate, substantial tax refund. If you withdraw in retirement at a 30% rate, you've effectively earned a permanent tax arbitrage.
But here's where it gets nuanced. RRSP withdrawals count as income, which can trigger clawbacks of Old Age Security (OAS) benefits and affect other income-tested programs. The OAS recovery tax kicks in once your income exceeds approximately $90,000, reducing benefits by 15 cents for every dollar over the threshold. [5]
TFSA withdrawals, by contrast, are invisible to the tax system. They don't affect OAS, GIS, or any means-tested benefit. For retirees who want flexibility and predictability, this can be worth more than the upfront RRSP deduction. [6]
Tax optimization assumes you'll actually invest the RRSP refund - not spend it. Research on windfall spending shows that unexpected money, including tax refunds, is often treated as "found money" and spent rather than saved. [7]
If you contribute $10,000 to your RRSP and receive a $4,000 refund, the math only works if that $4,000 goes back into investments. If it funds a vacation or lifestyle upgrade, you've diluted the RRSP's advantage significantly.
There's also the mental accounting problem. Behavioral research shows that people treat money differently depending on which "mental account" it sits in. [8] RRSP funds feel locked away (and largely are, due to withholding taxes on early withdrawal), which can be protective. TFSA funds feel more accessible, which can lead to premature withdrawals for non-emergencies.
Research from the Financial Consumer Agency of Canada found that many TFSA holders use their accounts primarily for short-term savings rather than long-term investing - missing the compounding benefits the account was designed for. [9]
Rather than treating this as an either/or question, most HENRYs benefit from using both accounts strategically. Here's a simplified decision framework:
Prioritize RRSP when: your marginal tax rate is high (above 40%), you're confident your retirement rate will be lower, and you have the discipline to reinvest the refund. Also consider RRSP contributions if you're planning to use the Home Buyers' Plan (HBP), which allows first-time buyers to withdraw up to $60,000 tax-free for a home purchase. [10]
Prioritize TFSA when: you're in a lower tax bracket now but expect higher earnings later, you want flexibility for mid-life goals (since withdrawals don't trigger tax or penalties), or you're already maximizing RRSP contributions and have additional savings capacity.
Use both when: you can afford to maximize contributions to each. The combined annual room (RRSP + TFSA + the newer FHSA for first-time home buyers) can exceed $40,000 - a powerful wealth-building engine if used consistently. [11]
Contributing to RRSP in a low-income year. If you're between jobs or earning less than usual, the deduction is worth less. Consider contributing to your TFSA instead and saving RRSP room for higher-earning years.
Ignoring employer matching. If your employer offers RRSP matching, that's an immediate 50–100% return on your contribution. Always capture the full match before directing money elsewhere.
Using TFSA as a savings account. Parking TFSA funds in a low-interest savings account wastes the tax shelter. Long-term data shows that diversified equity portfolios dramatically outperform cash over decades - and the TFSA's tax-free growth makes it ideal for higher-return investments. [12]
Over-contributing. The CRA charges a 1% monthly penalty on excess TFSA contributions. Track your room carefully, especially if you've made withdrawals (which restore room the following year, not immediately).
How PsyFi helps you optimize - and stick with - your strategy
Knowing the difference between RRSPs and TFSAs is one thing. Consistently making the right contributions - and avoiding the behavioral traps that derail good intentions - is another.
Personalized nudges: Reminders to contribute before deadlines, prompts to reinvest refunds, and alerts when you're approaching contribution limits.
Behavioral insights: Understand your money personality and how it affects decisions like "Should I tap my TFSA for this expense?"
Progress tracking: See how your registered accounts are growing over time, with visual cues that reinforce consistent behavior.
The best tax strategy is the one you actually follow. https://www.psyfiapp.com/ helps make that easier.
3: https://www.wealthsimple.com/en-ca/learn/rrsp-vs-tfsa
4: https://www.taxtips.ca/taxrates/on.htm
6: https://www.wealthsimple.com/en-ca/learn/oas-clawback-explained
7: https://www.nber.org/digest/mar09/did-2008-tax-rebates-stimulate-spending
8: https://www.behavioraleconomics.com/resources/mini-encyclopedia-of-be/mental-accounting/
12: https://www.rbcgam.com/en/ca/learn-plan/investment-basics/the-hidden-cost-of-too-much-cash/detail
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016