




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Apr 3, 2026 | NCFA Innovation Perspective | Moonshot Thinking

On April 1, 2026, Canada’s Artemis II mission reaches launch as Canadian astronaut Jeremy Hansen boards NASA’s Orion spacecraft, becoming the first Canadian and first non American on a mission beyond Earth orbit to the Moon.
It’s the first crewed Moon mission since 1972, and the 10 day flight around the Moon is designed to carry humans further from Earth than any mission before. For Canada, it’s proof that bold ambition still counts when a country backs talent, engineering, and strategic partnerships over a long stretch of time.
Artemis II isn’t the result of a quick push or a short funding cycle. It reflects decades of work in robotics, advanced systems, and international collaboration. Canada didn't get this seat by accident. It earned it. More founders, investors, institutions, and policymakers should stop and think about that.
Big outcomes rarely appear overnight. By the time the world sees the launch, the hard part has already been building quietly for years. Artemis II carries four astronauts around the Moon and back. Hansen’s place on that crew shows that Canada still plays a meaningful role in one of the most important technology programs now underway. That role is tied to long term Canadian contributions in space robotics, including the Canadarm legacy and Canada’s Canadarm3 commitment to the Lunar Gateway.
Ambition on its own is cheap. Everyone says they want to build big things. What matters is whether people keep going when the payoff is far away, the standards stay high, and the result is still uncertain. Artemis II shows what can happen when the mission stays clear and people stay committed.
This reaches far beyond aerospace. In fintech, financial infrastructure, artificial intelligence, and other serious technology sectors, people often talk about transformation. But real transformation asks for something uncomfortable. It asks for patience from backers, fellow builders and community. It asks for coordination. It asks for institutions that can think beyond the next quarter.
If Canada wants stronger digital identity systems, better financial infrastructure, more globally competitive AI companies, deeper capital markets, and more durable domestic champions, it can’t keep thinking small and expect outsized results. Those goals take time. They take conviction. They take leadership that sticks with the work long enough for the advantage to build.
Artemis II gives Canada a live example of what that looks like when the bet is real, the timeline is long, and the standard doesn’t drop.
Canada has talent. It has real technical depth. It has researchers, engineers, operators, and builders who can compete globally. What it often lacks is the willingness to place bigger bets and stay with them long enough. Artemis II is important for at least one key moonshot innovation reason. It exposes a familiar Canadian habit. We talk like a country with big potential, then act like one that is afraid to commit.
This mission shows that Canada can still contribute at the highest level when it decides to stay in the game. It also shows that credibility is earned over time. You don’t get invited into missions like this because people are being polite. You get there because your contribution is important and your capability is trusted. That should sound familiar to anyone trying to build a serious company in a serious market.
Moonshot thinking does not mean reckless thinking. It means taking on problems that are hard enough to matter and important enough to justify sustained effort. In practical terms, that could mean building financial infrastructure that removes friction across the system, creating AI tools that solve real regulated workflow problems, or designing funding models that help strong Canadian companies scale here instead of leaving early.
At first, that kind of ambition can look expensive, slow, or unrealistic. Later, it often looks obvious. That’s how breakthroughs actually play out. Artemis II is a reminder that countries don't build lasting relevance by backing lots of small bets. t’s built by committing to the work that defines what comes next.
Jeremy Hansen’s flight around the Moon gives Canada a rare public moment people can feel right away. The deeper value sits underneath that moment. This mission shows what long horizon ambition looks like when people actually follow through. It shows younger builders what serious technical achievement looks like. It shows investors and policymakers that long cycle bets can produce real global relevance. And it shows that Canada still has the ability to achieve moonshots when it chooses to commit.
The question now is whether Canada treats Artemis II as a celebration or as a standard. One gives us a proud moment. The other gives us something much more valuable. It gives us permission to think bigger, build longer, and stop pretending that incremental ambition will somehow produce exceptional results.
If this is what Canada can build over decades, what are you building today that is worth the same commitment?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Apr 2, 2026 | NCFA Fintech Market Activity | Wealth Investing And Trading
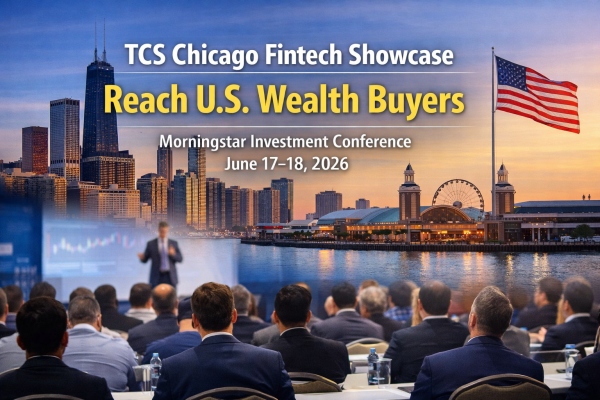
The Trade Commissioner Service at the Consulate General of Canada in Chicago is inviting Canadian fintech companies to apply for a Fintech Showcase focused on accessing U.S. institutional wealth and asset management buyers.
The showcase takes place during Morningstar’s June 17 and 18 investment conference in Chicago. The conference brings together advisors and other investment professionals. The agenda covers AI, private markets, retirement, and portfolio strategy. Those topics line up with current demand for better research, portfolio insight, and advisor productivity tools. View the agenda.
Selected companies will present in a four minute format to a senior audience across wealth and asset management. Evaluation focuses on business model, market opportunity, impact on wealth and asset management, investor outcomes, and presentation quality. Companies need a clear wealth use case, defined buyer, and measurable impact on investor outcomes.
This is best suited for Canadian wealthtech and investment technology firms that help advisors, asset managers, and investment platforms research, manage, personalize, or report on investments, or expand access and reduce friction for investors. It is a weaker fit for broad consumer fintech, horizontal infrastructure, or products without a clear link to wealth, asset management, or investor outcomes.
The application deadline is May 17, 2026. Apply now if your product is revenue ready and built for institutional wealth and asset management buyers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 2, 2026 | NCFA Fintech Market Activity | Banking And Credit, Regulation And Policy
Image: Freepik/rawpixel.com
On April 2, 2026, Italy’s competition authority (AGCM) fined Revolut group €11 million for unfair commercial practices tied to investment disclosures, payment account restrictions, and communication around Italian versus Lithuanian IBANs.
These fines come at a time when Revolut has grown into a bigger and more profitable company, and trying to look more like a primary banking platform than a fast growing fintech. In late March, Revolut reported $2.3B in profit before tax for 2025 with 68.3 million customers and $6B in revenue. Regulators expect more from a company with that type of scale; clarity, conduct, and professional account handling.
Regarding the IBAN issue,, the AGCM said Revolut didn't provide clear and exhaustive information on the requirements and timing for obtaining an Italian IBAN instead of a Lithuanian one. Revolut’s Italy account documentation now identifies Revolut Bank UAB Italian branch details and says the information sheet took effect on March 30, 2026. For a fintech trying to become more embedded in everyday banking, local account setup and customer communication are not side issues, and are important for trust and primary account use.
Revolut said it strongly disagrees with the findings and plans to appeal in the Italian courts. The company said the decision would have no impact on operations or its financial position. That response may settle investors in the short term, but its a sign that once a fintech reaches bank like scale, regulators stop looking only at growth and product breadth. They look much harder at how claims are framed, how restrictions are handled, and whether customers understand what they are actually getting.
Fractional investing, account controls, and local account migration can look like product details when a company is small. At scale, they become conduct risk. Italy’s decision shows how quickly those details can become costly once a fintech evolves deeper into the center of consumer finance.
When a fintech starts to look more like a primary bank, which becomes harder to defend at scale: aggressive growth tactics or unclear customer communication?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 2, 2026

Online casinos have changed a lot in recent years. The biggest shift involves the rise of crypto casinos, which allow players to bet with digital currencies like Bitcoin and Ethereum instead of regular money. These sites work differently from traditional online casinos in several important ways.
Crypto casinos offer faster payments, more privacy, and different bonus structures compared to traditional online casinos, though they also face unique regulatory challenges and learning curves for new users. Traditional sites use standard money and follow strict government rules, while crypto sites use blockchain technology to process bets and withdrawals. Each type has its own strengths and weaknesses that matter to different types of players.
The choice between crypto and traditional online casinos depends on what matters most to each player. Some people value speed and privacy, while others prefer the familiar systems and stronger legal protections of regular sites. This article explores how these two types of sites differ, what advantages crypto casinos provide, and what challenges they face in the current market.
Crypto casinos and traditional online gambling sites operate on different foundations that affect how players deposit funds, withdraw wins, and protect their personal information. The currency type, transaction speed, privacy levels, and access restrictions vary significantly between these two sites.
Traditional online casinos accept fiat currencies like dollars, euros, and pounds. Players deposit funds through bank transfers, credit cards, or e-wallets like PayPal. These methods connect directly to financial institutions and require verification of bank accounts or cards.
Crypto casinos accept digital currencies such as Bitcoin, Ethereum, and other cryptocurrencies. Players need a crypto wallet to store and transfer their digital assets. For example, sites like www.biggerz.com/, www.betpandacasino.io/, or others, allow users to gamble with various cryptocurrencies instead of traditional money.
The payment infrastructure differs substantially. Traditional sites rely on payment processors that charge fees for each transaction. Crypto sites use blockchain technology, which removes middlemen from the process. This means crypto casinos often have lower fees or no fees at all for deposits and withdrawals.
Traditional online casinos process withdrawals slowly. Bank transfers can take three to seven business days to complete. Credit card refunds may require five to ten days. E-wallets are faster but still need one to three days in most cases.
Crypto casinos process transactions much quicker. Deposits appear almost instantly in player accounts. Withdrawals typically complete within minutes to a few hours, depending on the blockchain network traffic. Bitcoin transactions might take longer than other cryptocurrencies, but they still beat traditional methods.
The speed difference comes from the verification process. Traditional casinos must verify transactions through banks and payment processors. Crypto transactions only need confirmation on the blockchain network. This removes delays caused by bank hours, holidays, or manual review processes.
Traditional gambling sites require extensive personal information. Players must provide their full name, address, date of birth, and phone number. They also need to submit identification documents like passports or driver's licenses. Banks and payment processors add another layer of data collection.
Crypto casinos offer more privacy. Many sites only ask for an email address and username to create an account. Players can gamble without submitting identity documents in most cases. Cryptocurrency transactions don't reveal personal details since they only show wallet addresses.
However, complete anonymity isn't guaranteed. Some crypto casinos still require verification for large withdrawals or to comply with regulations. The blockchain itself is public, so anyone can trace transaction patterns if they know which wallet belongs to a specific person.
Traditional online casinos face strict geographic restrictions. Many countries ban or heavily regulate online gambling. Payment processors often block transactions to and from gambling sites in restricted regions. Banks may decline deposits or freeze accounts linked to gambling activities.
Crypto casinos offer broader access. They can serve players in countries where traditional online gambling faces restrictions. The decentralized nature of cryptocurrency makes it harder for authorities to block transactions. Players can access these sites with fewer geographic barriers.
Regulations still apply in many jurisdictions. Some countries prohibit all forms of online gambling, whether crypto or traditional. Players remain responsible for following their local laws. Additionally, some crypto casinos choose to block certain countries to avoid legal complications.
Crypto casinos bring unique benefits like fair game verification and faster payments, but they also face hurdles with regulation and security concerns that players need to understand.
Provably fair gaming stands as one of the most significant features that sets crypto casinos apart from traditional sites. This technology uses blockchain and cryptographic algorithms to let players verify each game outcome independently. Players can check the fairness of every bet or spin through a hash function that proves the casino didn't manipulate results.
The system works through a process where the casino generates a random seed, and the player also contributes a seed. These seeds combine to create the game result. After each round, players receive all the information needed to verify that the outcome was truly random and not altered.
However, this advantage comes with a learning curve. Many players find the verification process confusing at first. The technical nature of hash verification requires some basic understanding of how blockchain works. Despite this challenge, provably fair systems offer a level of transparency that traditional online casinos cannot match.
Blockchain technology provides strong security features for crypto casino transactions. Every deposit and withdrawal gets recorded on a public ledger that cannot be changed or deleted. This creates a permanent record that both players and casinos can reference.
Players gain more control over their funds because cryptocurrencies eliminate the need for banks or payment processors. Transactions happen directly between the player's wallet and the casino. This direct transfer reduces the risk of payment fraud and chargebacks.
The transparency of blockchain also means players can verify casino reserves in some cases. Smart contracts can automate payments and enforce rules without human intervention. These features reduce the possibility of disputes over winnings.
On the other hand, cryptocurrency security depends heavily on proper wallet management. Players who lose their private keys lose access to their funds permanently. There is no customer service team that can reset a forgotten password or recover lost crypto. This responsibility shifts more risk onto the player compared to traditional casinos, where account recovery options exist.
Crypto casinos operate in a complex legal environment that varies widely between countries. Many jurisdictions have not yet created clear rules for cryptocurrency-based sites. This regulatory uncertainty creates risks for both operators and players.
Traditional online casinos typically hold licenses from established authorities that enforce player protection standards. Crypto casinos may operate with fewer restrictions, but this also means less oversight. Players might have limited recourse if disputes arise with unlicensed operators.
Some crypto casinos obtain licenses from recognized jurisdictions to build trust with players. However, the licensing requirements for crypto sites often differ from traditional casino regulations. This creates a patchwork of different standards across the industry.
Tax implications also present challenges for crypto casino players. Many tax authorities require individuals to report cryptocurrency gains, but tracking winnings and losses across multiple transactions can be difficult. Players bear the responsibility to understand and comply with their local tax laws.
Both crypto and traditional online casinos offer distinct advantages that appeal to different types of players. Crypto casinos provide faster transactions, more privacy, and lower fees, which attract those who value speed and anonymity. Traditional sites offer more established regulations, familiar payment methods, and a sense of security through licensed oversight.
The right choice depends on what matters most to each player. Those who prioritize quick withdrawals and privacy may prefer crypto sites, while players who want regulated environments with consumer protections might choose traditional sites.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 1, 2026 | NCFA Insight | Innovation Policy And Funding
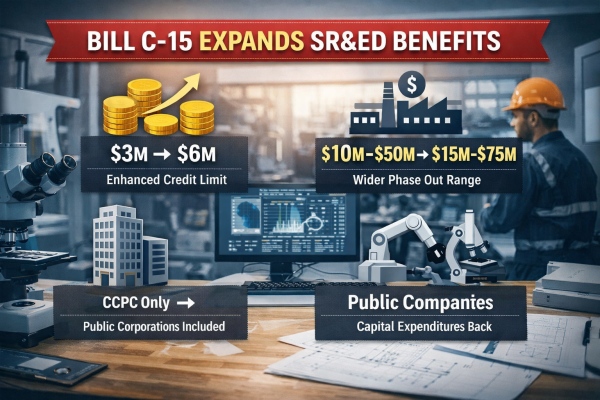
On Mar 26, 2026, Bill C-15 received Royal Assent. Alongside Canada’s new digital finance framework, it also puts major Budget 2025 SR&ED changes into law. The enhanced 35% SR&ED credit now applies on up to $6M of qualifying expenditures, up from $3M. The taxable capital phase out range widens to $15M to $75M, up from $10M to $50M. Eligible Canadian public corporations can now access the enhanced credit, and capital expenditures become eligible again.
| Change | Before | After | Why It Matters |
|---|---|---|---|
| Enhanced 35% expenditure ceiling | $3M | $6M | Companies can keep the higher credit rate on another $3M of qualifying work, which improves cash flow for teams already spending heavily on product and engineering. |
| Taxable capital phase out range | $10M to $50M | $15M to $75M | More growing firms can qualify for the enhanced regime longer instead of losing support too early. |
| Enhanced credit access | Mainly CCPC focused | Includes eligible Canadian public corporations | Some listed Canadian firms with real product and R&D intensity can now claim richer support instead of falling outside the enhanced lane. |
| Capital expenditures | Not eligible | Eligible again | This impacts firms that need equipment, testing environments, and technical infrastructure, not just payroll, to build. |
The biggest gains go to qualifying companies already spending heavily on development and infrastructure. That may include payments firms building fraud and risk systems, regtech firms developing compliance tooling, AI firms training and testing models, and data infrastructure companies investing ahead of revenue. Early stage teams with smaller claims still benefit, but the larger payoff goes to companies that were already hitting the old ceiling or losing support as they grew.
The program is stronger, but it still rewards discipline. Claims still depend on technical records, project detail, and the ability to show eligible experimental work. Companies with weak documentation simply won't capture the full benefit.
Two simple examples:
A Canadian payments company with $5M in eligible SR&ED spending used to reach the enhanced ceiling at $3M. Under the new rules, another $2M of that spend qualifies for the enhanced rate. That doesn't fix product market fit, but it can reduce cash burn and make it easier to keep engineering teams in place.
A public company building AI driven compliance software may now benefit in two ways at once. It can access the enhanced credit if it qualifies, and it can include eligible capital costs tied to technical build out. That makes the program more relevant to how software and infrastructure firms actually spend.
Bill C-15 makes SR&ED more useful for companies with real development spend. The ceiling doubles to $6M, the phase out range widens, public company access expands, and capital costs come back into scope. For Canadian fintech and AI builders, that can extend runway and support more product development work.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 1, 2026 | NCFA Fintech Market Activity | Embedded Finance Platforms And Partnerships, Payments And Money Movement
On March 31, 2026, Reuters exclusively reported TikTok's Brazil license applications. The company applied for one license to issue electronic money for prepaid accounts and payments and another to operate as a direct credit company, enabling lending without taking public deposits.
TikTok already has the reach with more than 131 million users in Brazil. Most fintechs spend years trying to build that kind of distribution. TikTok already has it. The harder part is turning that audience reach into payment, wallet use, and trust in a credit product.
Brazil's payment system also gives TikTok a strong foundation to build on. Pix reached nearly 170 million users and BRL 11 trillion in transactions in 2024. The domestic payment rail is already there so the battleground is who controls checkout, the wallet, the customer relationship, and eventually the credit layer inside social commerce.
If TikTok can connect discovery, commerce, payments, and lending into a single flow, it starts to look less like a social app with a wallet and more like a commerce platform with financial rails built in. The upside is clear. Payments can reduce checkout friction. Credit can lift conversion, change seller economics, and pull more transactions into the platform.
The trust question is harder. A social platform can add financial rails faster than a normal fintech can add distribution, but it still has to prove that users, merchants, and regulators trust the same platform to handle money as well as attention. That challenge is real when, especially when platforms can face backlash after changing how users think abut their service scope, data usage or activity will be used, as seen in Bluesky’s data use backlash.
The old approach was to build a financial product and then fight and claw for users. TikTok is trying the reverse. It already has the users. Now it wants the financial plumbing, much like Elon Musk's super app push for X. That in itself makes the licensing outcome worth watching for fintech founders, banks, acquirers, and payment firms already operating in Brazil.
The open question is whether a social platform can turn payments and credit into a real commerce edge without drawing heavier scrutiny as it grows. If it can, Brazil may become a clear example of platform distribution beating out traditional financial distribution.
When a platform already reaches 131 million users, does the edge in finance come from the product itself or from owning the customer before the first payment starts?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 1, 2026 | NCFA Fintech Market Activity | Cross Border Payments And FX
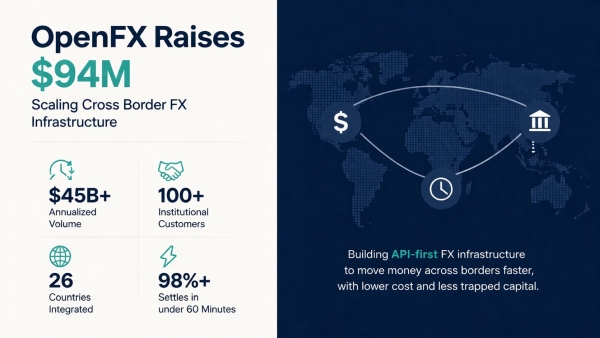
On March 31, 2026, OpenFX raised $94M to expand across Southeast Asia and Latin America. Two years after launch, the company says it now has 105 employees across four continents, handles more than $45B a year in cross border volume, and has onboarded more than 100 institutional customers.
The operating numbers are hard to ignore. OpenFX says 98% of transactions settle in under 60 minutes. In May 2025 the company said it had already integrated 26 countries and 7 major FX pairs, and that one newly onboarded client reached $100M in transaction volume in 17 days, with all of that settling within 60 minutes.
The product vision is more specific than a generic stablecoin pitch. Founder and CEO Prabhakar Reddy wrote that OpenFX didn't want to be “a crypto company moving Stablecoins,” but “a FX company moving money across the globe.”
OpenFX has built the hardest part of cross border payments first, including liquidity, cost, and settlement mechanics. It's tech stack offers collections, FX, payouts, banking, yield, compliance, and liquidity, delivered through API based infrastructure that runs 24/7.
That focus helps explain the customer base. OpenFX says it serves fintechs, neobanks, remittance providers, and payroll platforms, including MoneyGram, Yellow Card, and alfred. The company also says there's more than $200T in money movement that still relies on slow and fragmented cross border infrastructure.
OpenFX isn't selling speed on its own. Its announcement post argues that legacy cross border payments still hide fees inside exchange rates, trap capital in pre funded accounts, and leave businesses waiting days for settlement. OpenFX says stablecoins let value cross borders in seconds while sender and recipient still use local fiat. That reduces idle capital, compresses settlement time, and gives payment firms a cleaner way to handle large transfers.
There is a useful lesson here for founders and investors. OpenFX didn't try to fix every payment problem at once. It picked a part of the market where delay is expensive, built around API access and 24/7 settlement, then pushed that model into live institutional volume. If that keeps working, expect pressure to build around flows based on old economics andslow settlement, trapped liquidity, and wide spreads on large transfers.
If large ticket FX settles in under an hour, which parts of the old cross border fee stack get hardest to defend?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016