




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 31, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data
On March 28, 2026, Bluesky introduced Attie in invite only closed beta, it's first agentic social product built on atproto. It's interesting because Bluesky built part of its appeal on taking a more cautious public approach on generative AI and user content than larger platforms.
Attie is a standalone AI assistant for custom feeds and app building. Users can describe what they want in natural language, build their own algorithm, create custom feeds, and over time build social apps on the protocol without needing to code.
In late 2024, Bluesky had already set expectations around how it saw AI and user data. The company said it had “no intention” of training generative AI on user posts.
Then in 2025, the company published a data reuse proposal that would let users set preferences across generative AI, protocol bridging, bulk datasets, and web archiving. That debate got heated because it didn't create a hard block on scraping or data reuse. For many users, it crossed a data use line that Bluesky already said it wouldn't cross. They said they wouldn't train AI on post data but now it was building a system around opt outs and reuse preferences, creating friction with its users.
By March 30, Attie had become one of Bluesky’s most blocked accounts. More than 125,000 users had blocked it within days. Users didn’t wait for a long policy debate. They reacted to what the launch seemed to mean.
Bluesky didn't announce that it would now train generative AI on user posts. But in trust based markets, users don’t separate product utility, data use, and company intent as neatly as product teams do. Once those concerns merge, the launch stops being just a product story. It becomes a consent and brand story too.
For founders and investors, there's a practical and commercial lesson here. AI features and products are getting easier to ship, but clear boundaries aren’t. In fintech, payments, digital identity, and any other business built on sensitive data, that gap (or buffer) can backlash and get expensive fast.
What did Bluesky launch?
Bluesky launched Attie as an invite only closed beta app built on atproto. It helps users create custom feeds with natural language prompts and is designed to support broader app building over time.
Why did users push back so quickly?
Because many users already saw Bluesky as more cautious on AI than rival platforms. A branded AI app raised immediate questions about whether that line of mutual trust was starting to change.
Did Bluesky say it will now train AI on user posts?
No verified source tied to this launch shows Bluesky announcing that change. The concern comes from how users connected the launch to earlier debates over AI training and scraping.
Why does this matter for fintech?
Because the same problem appears in any trust based product. If users are unsure what an AI tool does, what data it uses, or what clear policies the company will not cross, adoption can weaken before the product gets a fair chance.
What makes this commercially important?
This isn't just a social media story. It shows how fast a useful AI feature can become a trust and brand problem. That risk applies to consumer finance, digital identity, payments, and any business built on sensitive data.
As AI tools spread across digital platforms, will users reward the company that ships first, or the one that makes the boundary clear before launch?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 31, 2026 | NCFA Insight | Artificial Intelligence And Data
A Toronto quantum company reaches public markets, but the real test starts now with capital, manufacturing, and a long road to commercial scale.
On March 26, 2026, Xanadu completed its business combination with Crane Harbor Acquisition Corp. and confirmed that its shares would begin trading on Nasdaq and the Toronto Stock Exchange on March 27 under the ticker XNDU. The listing gives Canada a relatively rare public market deep tech story in advanced computing. It also puts a hard spotlight on a bigger challenge confronting the country.
Can Canada fund and keep the hardware, manufacturing, and technical talent needed to compete in the next compute cycle?
Xanadu builds photonic quantum computing technology and argues that photonics offers a more scalable route by operating at room temperature and fitting more naturally into semiconductor and networking supply chains. The listing gives public investors exposure to a Canadian company building core compute infrastructure at a time when the market is paying closer attention to the physical layer behind AI and advanced computing. It's a live test of whether public markets still have room for an ambitious Canadian deep tech company with long build cycles and heavy capital requirements.
Xanadu opened at $10 and closed its first day at $11.50 but the harder question is how much cash the company actually secures for a long commercialization runway. Earlier materials pointed to about $500 million in gross proceeds under a no redemption scenario. By March 19, the company updated that to about $302 million, a figure confirmed again in its March 26 closing release.
It's still meaningful capital, but 40% below below the early figure. Deep tech plays live or die on balance sheet strength, engineering execution, manufacturing progress, and how long they can keep building before commercial revenue catches up.
On March 11, Xanadu said it entered negotiations toward up to C$390 million in support from the governments of Canada and Ontario for Project OPTIMISM, a proposed initiative tied to quantum and photonic manufacturing. The company said the buildout could strengthen domestic capacity not only in quantum, but also in telecommunications, sensing, semiconductors, and AI hardware.
Canada often talks about AI leadership, productivity, and economic competitiveness. Those goals depend on more than software. They depend on whether Canada can finance, build, and retain parts of the compute stack itself. Xanadu is now a central entity in the middle of that question.
Xanadu’s own roadmap sets the tone. In its March 4 analyst day presentation, the company targets customer commercialization in 2029 and beyond and outlines a goal of up to 500 logical qubits in 2029. That means public investors get liquidity now while the core commercial outcome still sits years away.
Investors aren't buying a scaling revenue engine. They are backing a technical architecture, a manufacturing plan, and a long duration commercialization thesis. Public market access gives Xanadu more visibility and more pressure at the same time.
Xanadu’s transaction materials do not hide the challenge. The company discloses historical net losses, limited operating history, revenue concentration in government or state funded contracts, material weaknesses in internal control over financial reporting, and substantial doubt about its ability to continue as a going concern. Those disclosures do not erase the opportunity, but they do set the terms for how this company should be judged.
The Xanadu listing reaches the market with strong ambition, real technical credibility, and visible policy support. It also reaches the market with the risks that usually come with frontier hardware businesses. Investors now have both sides in front of them.
That's why this is not just a quantum story, but also a Canadian compute story. If future advantages in AI, cryptography, modelling, secure infrastructure, and advanced enterprise systems depend on access to more specialized hardware, then the financing and ownership of that hardware matters. Xanadu gives Canada a public company tied to that future. The market will now decide how much patience it has for that build cycle.
The listing also reopens a harder national question. Can Canada create a repeatable route for deep tech companies to reach public markets and keep building here, or will most companies still need to sell early, move abroad, or rely on foreign capital to finish the job. Xanadu doesn't answer that question yet, but it makes it impossible to ignore.
Xanadu’s debut goes well beyond a one day stock pop or standard IPO listing. It comes to market through a SPAC transaction, closes with lower expected gross proceeds than early headline numbers suggested, ties part of its future to government backed manufacturing support, and targets meaningful commercialization years from now. That combination means this is one of the more important Canadian technology listings in years. The bigger issue is whether Canada has the capital depth, policy follow through, and market confidence to support companies building the next layer of compute infrastructure before someone else does.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 31, 2026 | NCFA Fintech Market Activity | Payments And Money Movement
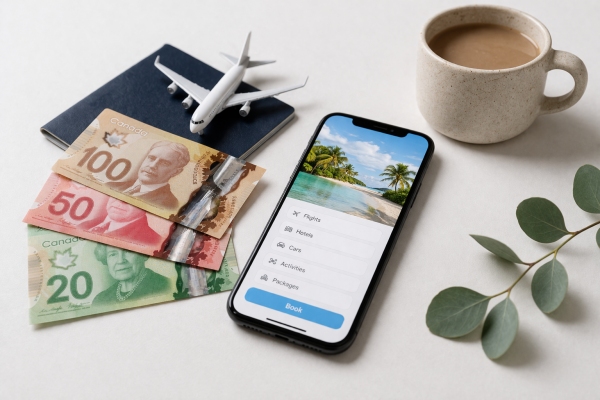
On March 30, 2026, RBC and HTS launched a long term travel collaboration that brings Hopper Technology Solutions into Avion Rewards. The new booking portal goes live later this year for all Avion Rewards members, including Avion credit cardholders.
RBC is not just adding another travel partner. It's bringing search, booking, pricing, and redemption deeper into its own rewards product. Members will be able to use points across flights, accommodations, car rentals, activities, and packages. The platform also adds price insights built on historical and predictive data. Avion cardholders keep fixed points pricing on any airline, any flight, any time, with no blackout dates or seating restrictions.
That's the fintech angle. Travel stops being only a redemption feature at the end of the card relationship. It becomes part of the card experience itself. The bank gets more control over where travel spend happens, how rewards get used, and what it learns from search, booking, and redemption behaviour.
Avion Rewards already describes itself as Canada’s largest bank owned loyalty program. HTS brings the software behind the experience. Its 2026 travel commerce report draws on $6B in travel sales, 410M reachable cardholders, and 2.2M annual fintech purchases. RBC is adding travel commerce software, pricing intelligence, and a tighter booking flow to a large existing rewards base.
If other banks follow, rewards programs will start competing on more than points. Cardholders may start comparing how easy it is to search, book, and use rewards, not just how many points they earn. Customers stand to benefit if booking gets easier, pricing gets clearer, and redemption works with less friction. Banks benefit if more travel activity stays inside their own platform.
The booking layer may be just the start. Once search and rewards are part of the same experience, the bank can add instalments, insurance, trip support, and targeted offers at the point of booking. Ultimately, that turns travel rewards into more than a marketing perk. It starts to look like a real financial service channel.
If banks bring booking deeper into rewards, what's more important over time: the points currency, the booking layer, or the customer data that sits between them?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 31, 2026
Crypto casino gaming now moves billions of dollars every year. Many players prefer these sites because they use provably fair technology, allow fast blockchain withdrawals, and offer games designed specifically for cryptocurrency betting. With the right site and game, players can verify outcomes and track exactly what happens to every wager.
The online gambling market is projected to surpass $100 billion by 2026, and crypto casinos continue to gain market share. Players are increasingly drawn to transparent systems, quick withdrawals that settle in minutes rather than days, and games whose outcomes can be verified.
Some of the most popular crypto casino games today include crash multiplier games, provably fair Plinko, high-volatility themed slots, modern 3D slot titles, and live dealer roulette with multiplier bonuses. Each offers a different style of gameplay and risk level.
This guide covers five of the most popular crypto casino games in 2026. All of them appear on licensed sites with fairness verification systems, fast crypto withdrawals, and active player communities.
Choosing the right crypto casino game requires understanding a few key factors.
The following five games are widely played by crypto casino users in 2026:
Each represents a different type of gameplay, from multiplier betting to slots and live dealer experiences. Let’s start:
Best for: Players who enjoy fast rounds and transparent outcomes.
Standout feature: A very low house edge combined with provably fair verification for every round.
Best for: Players seeking frequent payouts and unique slot mechanics.
Standout feature: A rare slot format where characters appear from underground instead of spinning reels.
Best for: Players looking for a high-volatility slot with the possibility of large multiplier wins.
Standout feature: Stacking multipliers combined with cascading reels and a maximum payout exceeding 21,000x the original bet.
Best for: Players who prefer simple gameplay with strong transparency.
Standout feature: Flexible risk settings combined with high RTP and full outcome verification.
Best for: Players who enjoy live dealer experiences combined with high multiplier potential.
Standout feature: Random lightning multipliers that dramatically increase payouts on selected numbers.
A trustworthy license ensures player protection and fair payouts. Always confirm the casino is regulated before depositing cryptocurrency.
High-volatility games may produce huge wins but also long losing streaks. Select games that fit your budget and risk tolerance.
Provably fair technology allows players to verify that outcomes were generated before the wager was placed, improving transparency.
One advantage of crypto gambling is fast payouts. Choose sites that process withdrawals quickly so winnings can be accessed without delays.
Some bonuses exclude certain games from wagering contributions. Reading the rules first prevents unexpected restrictions.
Transparency is one of the main reasons crypto casino gaming continues to grow. Provably fair algorithms and publicly listed RTP values allow players to analyze games before placing bets. This level of accountability is uncommon in traditional online casinos.
Selecting the right game involves more than choosing the biggest bonus or flashiest design. The most important factors are volatility, bankroll compatibility, fairness verification, and withdrawal reliability.
Before depositing, always confirm the site’s license and payout speed. Those checks ensure that when you win, your funds are secure and accessible.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 30, 2026 | NCFA Insight | Payments And Money Movement
On March 25, 2026, the FCA opened the door to regulatory changes for agentic AI payments, placing a policy question mark related to artificial intelligence. If software can autonomously initiate and execute payments, the industry needs to better understand the answer to a basic legal question. Who actually gives consent?
Under UK payment consent requirements, a payment transaction counts as authorized only if the payer has given consent, and that starts from a human payer. The FCA’s approach to payment services goes further and requires that consent is clear, specific, and informed. That framework works for card payments, standing orders, recurring mandates, and merchant initiated transactions. It becomes much harder to apply when an AI agent interprets a goal, selects a payee, and decides when to act.
The real question is whether current rules can still pinpoint when consent actually happens. Today’s framework assumes a person is involved at the moment a payment is made. The FCA says authentication confirms the user is legitimate and has approved the transaction. It also requires strong customer authentication when someone initiates a payment or takes an action that could increase fraud risk. That logic breaks down when software makes decisions on its own. Current payment authentication guidance does not fit well with autonomous AI agents.
This becomes clearer when you look at how mandates work today.
Once a user sets up a mandate, some payments can go through without repeated authentication. But there is a limit. If a payment falls outside what the user originally approved, it becomes unauthorized unless the user steps in and updates the mandate. That gives fintech builders a clear boundary. The safest near term model for agentic payments is not full autonomy. It is controlled delegation. Users set the rules, and the AI operates inside them.
If a payment goes beyond what the user approved, it is treated as unauthorized. Under UK payment consent requirements, a payment provider needs the customer’s consent. Under unauthorized payment refund rules, providers must refund those transactions quickly, usually by the next business day, unless they have reason to suspect fraud. That puts pressure on payment firms, wallets, and embedded finance providers. If the approval model is weak, liability grows quickly and these rules leave very little room for error.
This affects Canadian fintech operators too. The UK is not just talking about AI in payments. It is updating the rules around it. In February 2026, the UK published a three year UK payments modernization plan, and UK payments roadmap for fintechs shows how regulators are lining up changes across retail payments, open banking, and digital assets. Agentic AI payments are now part of that wider regulatory perimeter push.
What's the takeaway for founders and product leaders? Don't present agentic AI as something that can give consent on its own. Build systems where the user sets clear limits, can cancel approval easily, and can trigger extra checks when a payment falls outside the rules. That fits much better with how regulators already treat mandates, authentication, and unauthorized payments. It also lowers risk as these systems grow.
For regulators, as AI agents start handling payments, the issue is not the activity itself, but how decisions are made. The FCA is now considering whether existing rules need to change, as some uses fit within current frameworks, while others raise questions around consent, authentication, and liability.
First, consent. Today’s framework requires a clear moment where the user approves a payment. If an AI decides when and how to pay, that moment becomes unclear. Regulators need to define what counts as valid consent when software acts on its own.
Second, authentication. Strong customer authentication is built around a user actively approving a transaction. If payments happen without that step each time, regulators need to decide when authentication still applies and when it can rely on pre-approved rules in the age of agentic payments.
Third, liability. If a payment goes wrong, current rules say the provider must refund unauthorized transactions quickly. But if an AI acts within a system the user set up, it is not always clear who is responsible. Regulators need to decide who pays when an agent acts outside what the user intended.
If AI agents start making payments at scale, who actually controls the money flow? The user, the platform, or the system that defines the rules behind it?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 30, 2026 | NCFA Fintech Market Activity | Payments And Money Movement
On March 30, 2026, Wirex and Crossmint launched an integrated stablecoin card stack. The product connects stablecoin wallets to card spending in one setup. According to the companies, crypto card volume has grown 106% a year since 2023 and reached an $18B annualized market by late 2025.
The bigger market is still early. Real stablecoin payments ran at about $390B annualized in 2025, or roughly 0.02% of global payments volume. That leaves a lot of room for growth, but it also shows how far the market still has to go before stablecoin spending becomes mainstream.
The main problem isn't demand alone. Stablecoin card programs usually need separate wallet, card, and compliance infrastructure. In earlier work with Wirex, Crossmint said it cut six months of internal development time, opened a path toward support for 20+ networks, and helped support a platform serving more than 7 million customers, processing more than $20B annually across 130 countries.
Daniel Rowlands, General Manager, Onchain Finance at Wirex:
"This is what it looks like when two pieces of infrastructure are built to fit together. Fintechs can now give their users a Wirex debit card funded directly from a Crossmint wallet, and as they grow, the full BaaS stack is there when they need it."
That is the stronger business case behind this launch. Stablecoin balances are getting easier to hold. The harder part is turning them into everyday spend in a product that launches fast, works across markets, and stays compliant. This stack goes after that build problem directly.
For founders and investors, the commercial question is straightforward. If stablecoin cards keep growing, the advantage may sit less with another wallet feature and more with the firms that can package wallet infrastructure, card issuance, compliance, and distribution into one launch path.
How big is the real stablecoin payments market?
Most headline stablecoin volume does not reflect real payments. A recent stablecoin payments reality gap analysis shows why the market needs more careful measurement. The best current estimate for actual stablecoin payments is about $390B annualized in 2025.
Why do stablecoin cards matter?
They turn wallet balances into spend at existing merchant acceptance points. That makes cards a clear current solution to go from holding stablecoins to using them in daily payments.
What slows product launches today?
Fintechs often have to assemble the wallet layer, card program, and compliance stack separately. That adds engineering time, raises launch cost, and slows distribution.
Why does this launch stand out?
It does not start from zero. Wirex already has user scale and card infrastructure. Crossmint already cut build time in its earlier Wirex integration. That gives the launch a stronger operating base than a typical partnership announcement.
As stablecoin cards grow, which layer gains the stronger position: the wallet, the issuer, or the firm that can package both into one launch stack?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 30, 2026 | NCFA Insight | Regulation And Policy

On Mar 26, 2026, Bill C-15 received Royal Assent. The law completes Canada’s consumer-driven banking legislative framework and creates a regulated space for stablecoins. The Department of Finance confirms that directly. The Bank of Canada also confirms it will take on two new mandates, including the supervision of stablecoin issuers and oversight of the framework for consumer-driven banking.
The real change isn't that Canada suddenly discovered digital finance, but rather that political will has now cleared the legislative hurdle.
Canada now has a clearer institutional map for three linked parts of digital finance: payment service providers, stablecoins, and consumer-directed data sharing. Payment supervision was recently already in place under the Retail Payment Activities Act.
That reduces one kind of uncertainty. Companies no longer need to guess whether Canada intends to regulate these areas. The answer is yes. The remaining uncertainty is operational, so how the rules will work, how supervision will be applied, how fast the framework will be implemented, and whether the final design is practical enough for real products and real users.
The law is in force, but the working rulebook is still being built. The Bank of Canada will help develop regulations, supervisory policies, and operational frameworks, while engaging industry as the system moves toward implementation.
The core stablecoin model is already visible. Issuers are expected to operate with 1:1 reserves in high quality liquid assets, support at par redemption, and meet ongoing supervisory and disclosure expectations. The remaining uncertainty is how these requirements translate into daily compliance, reporting, and supervision.
Consumer-driven banking is going forward under a split structure where the Financial Consumer Agency of Canada handles accreditation, participant oversight, and consumer protection, while the Bank of Canada sets and oversees the technical standards that systems will need to meet. The direction is clear, but execution depends on how these layers work together. Companies will need to meet accreditation requirements while building to technical standards at the same time. The risk is not uncertainty about the framework, but having to clear more than one gate before a product can go live.
Lastly, the execution risk is how quickly outstanding detailed rules take to arrive, and how difficult they are to meet in practice. If those answers come slowly, Canada will have a legal framework but real momentum will take a hit. If they come quickly and cleanly, related Canadian fintech models will become easier to build, partner, and price.
Good for competition and investment. Clearer rules helps more than vague ambition does. Foreign firms, infrastructure providers, and capital partners can assess Canada more easily when they can see which activities are in scope, who supervises them, and what the implementation path looks like. That alone doesn't guarantee a wave of new investment. Market size, compliance cost, tax treatment, and speed of execution still matter. But a clear regulatory perimeter is better than a half-built one.
For fintechs, the upside is clarity. The cost is higher discipline. Stablecoin and consumer-data products will need stronger controls, cleaner records, and more formal partner arrangements earlier in the build process. This helps firms that already build for regulated environments. It slows firms that rely on loose structures or hope to sort out compliance later. The gap between policy design and real payment usage is already visible in stablecoin data showing a payments reality gap, where payment use still lags trading and treasury activity.
For banks and larger financial institutions, the law creates a more defined path to engage with stablecoins and consumer-driven banking under a supervised framework. That helps internal decision-making. It also raises responsibility. Institutions will need stronger oversight of how these products connect to payments, treasury, customer channels, and third-party infrastructure.
For infrastructure and vendor firms, this raises the standard for what counts as a viable solution. Auditability, resilience, data controls, and supervisory readiness become buying criteria, not optional features. Vendors that cannot support regulated deployment will struggle to win larger Canadian mandates.
For Canada’s financial services landscape, the likely effect is a clearer split between firms that can operate under supervision and firms that cannot. That may improve trust and reduce noise. It will also be an advantage for participants that already have stronger governance, legal support, and operational depth.
The priority is to prepare, not wait. Companies should identify where payment stablecoins and consumer-directed data already sit in their products, map the third parties those flows depend on, and test whether those setups can meet supervision. The detailed rules are still coming, but teams that engage early will understand the direction sooner and adjust faster.
For years, progress in stablecoins and consumer-driven banking depended on political will. Bill C-15 clears that hurdle. The framework is now in law.
Canadian digital finance is now onto execution. Regulations, supervisory expectations, and operating standards will decide whether firms can build and scale in Canada without delay. Bill C-15 sets the direction. Execution will decide how much actually gets built.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016