




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


March 30, 2026

In recent years, Canada has stopped treating sport merely as a matter of identity or social policy. Increasingly, it is viewed as a full-fledged economic sector: a lever to attract tourism, redevelop urban areas, support employment, strengthen regional brands, and mobilize both public and private capital. The numbers clearly reflect this shift. According to Statistics Canada, in 2023 the sport-related GDP reached 7.56 billion Canadian dollars, growing by 9% compared to the previous year, with organized sport rising to 2.1 billion and surpassing 2019 levels for the first time. In the same year, the sports sector accounted for 0.3% of the national economy.
The economic snapshot reveals an ecosystem that goes well beyond major professional clubs. In Canada, sport connects grassroots participation, high-performance competition, international events, infrastructure, media, sponsorships, and emerging digital platforms. The growth of sport GDP in 2023 indicates that the rebound was not limited to spectators returning to venues, but involved the entire value chain. On the social side, there is also a broad base supporting these investments: Statistics Canada reported that 55% of people aged 15 and over said they had participated in a sport in the previous 12 months.
This critical mass matters, as it makes public spending more justifiable and private strategies more sustainable. Where participation exists, there is demand for facilities, competitions, services, broadcasting content, and commercial products. Canada, in other words, is not investing in a vacuum: it is capitalizing on a widespread sports culture, although disparities remain across regions, income levels, and gender.
On the public side, federal efforts have focused on three main areas: inclusion, safety, and high performance. In 2023–24, Sport Canada distributed 266.8 million Canadian dollars to national sports organizations, elite athletes, and initiatives aimed at increasing participation and strengthening safe sport practices. Additional federal measures included 15 million over two years for the Community Sport for All Initiative, 16 million over two years for the Sport Support Program, and an enhancement of the Athlete Assistance Program under the 2024 budget, bringing its annual funding to 40 million.
This is not merely a technical detail. It shows that the Canadian government has chosen to spread investment across the entire sports pyramid: grassroots access, athlete protection, and international competitiveness. In March 2025, the government also announced 10.5 million over two years for 13 national organizations through the Community Sport for All Initiative, aiming to reduce barriers for underrepresented groups. On the integrity front, Ottawa allocated 12 million annually from 2024 to 2026 for safe sport initiatives.
However, a structural tension remains: while the system is growing, many federations continue to report fragile infrastructures and rising costs. Public debate in Canada has highlighted that the key issue is not only how much is invested, but where and with what consistency.
The project that has most significantly scaled up sports investment in Canada is the FIFA World Cup 2026. The country will host 13 matches across Toronto and Vancouver: six in Toronto and seven in Vancouver. Toronto will stage the first men’s World Cup match ever played on Canadian soil on June 12, 2026, featuring the national team, while Vancouver will host two Canada matches along with knockout-stage games.
The expected economic impact is one of the main arguments supporting the investment. FIFA has estimated that the tournament could generate 3.8 billion Canadian dollars in economic output for Canada, with an average GDP contribution of around 155 million per match and approximately 1,850 jobs created or supported for each game. For cities like Toronto, the event is not only about tourism and spending, but also about long-term legacy in infrastructure, youth participation, and organizational capacity.
Naturally, the issue of costs remains open, and in Canada political debate around budgets, governance, and returns is far from marginal. Yet this very discussion confirms a key point: sport is now treated as a driver of urban and economic development, rather than a secondary sector. The scale of the 2026 World Cup is pushing cities, provinces, commercial operators, and institutions to think in long-term strategic terms.
While public investment has strengthened the foundation, private capital has raised the stakes. A clear example came in 2024, when Rogers announced the acquisition of Bell’s 37.5% stake in Maple Leaf Sports and Entertainment for 4.7 billion Canadian dollars, reinforcing the central role of live sport in media and entertainment. The signal to the market was clear: broadcasting rights, live events, and major sports brands remain strategic assets.
Perhaps the most interesting development, however, concerns women’s sport, which in Canada has entered a more structured phase. In 2024, the WNBA awarded Toronto its first franchise outside the United States, later named Toronto Tempo. Between 2025 and 2026, the project attracted new investors and high-profile partners. At the same time, professional women’s soccer gained a national platform with the launch of the Northern Super League, featuring six founding clubs and backed by major sponsors such as BMO and Toyota Canada.
This shift is not only symbolic. Investment in women’s sport reflects a broader recognition of untapped revenue streams: ticket sales, media rights, commercial partnerships, community engagement, and local activation. It aligns with a system aiming not just to grow in size, but also to diversify.
Another important piece of Canada’s evolving sports ecosystem is the regulated digital market, particularly in Ontario. Here, operators offering sports and event betting must be registered with the Alcohol and Gaming Commission of Ontario (AGCO) and, except for OLG, operate through agreements with iGaming Ontario. In 2024–25, Ontario’s iGaming market recorded 82.7 billion Canadian dollars in total wagers and 2.9 billion in gross gaming revenue, marking growth of over 30% compared to the previous year. While these figures include multiple gaming products, not only sports betting, they highlight the economic scale of the regulated market.
With the World Cup approaching, this topic is expected to re-enter public discussion, especially due to odds published by authorized platforms and Canada’s participation as a host nation. In this context, referencing a Canada sports betting site only makes sense within a regulated, transparent framework subject to oversight, as part of the broader commercialization of sport rather than as an independent driver of its growth.
The broader picture, however, goes beyond odds and platforms. In recent years, Canada has approached sport as a strategic sector: with targeted public funding, major events used as accelerators, multi-billion-dollar corporate transactions, and increasing attention to new audiences and emerging competitions. The real wager—economic rather than recreational—is that this infrastructure will deliver long-term returns. And for now, the signals suggest that Canada is fully committed to that path.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
March 29, 2026

Image: Unsplash/Priscilla Du Preez
Retail shrinkage — the industry term for inventory loss through theft, fraud, and administrative error — costs global retailers hundreds of billions of dollars annually. Within that figure, return fraud has grown into one of the most consistently underestimated line items. Unlike shoplifting, which is immediately visible and operationally disruptive, return fraud is quiet. It enters through the customer service desk, processed by a staff member under time pressure, usually accepted to maintain a positive customer interaction, and absorbed as a cost of doing business. Organized retail crime operations have identified this as a reliable revenue stream, and the scale of exploitation has grown accordingly.
The technology capable of changing this dynamic is retail identity verification: a systematic process of confirming the identity of customers at specific transaction touchpoints — most critically the returns desk — using automated document scanning rather than relying on staff judgment or paper-based log systems. When a fraudulent returner knows their identity is captured and matched against a return history database, the economics of the fraud change. The deterrent effect operates before any individual transaction is evaluated, and the audit trail it creates enables pattern detection that no manual system can replicate at the speed or scale required.
What is also important here is that return fraud does not operate in isolation. The same individuals and organized groups responsible for fraudulent returns are frequently responsible for the theft that enables those returns. Stolen merchandise returned for cash or store credit creates a clean revenue cycle for organized retail crime. That’s why identity verification at the returns desk intercepts not just the return itself but the downstream incentive that makes the preceding theft financially worthwhile.
Retail identity verification is the practice of confirming a customer’s identity at a point-of-sale or service transaction using a machine-readable identity document. In the returns context specifically, it means capturing the returning customer’s name and identity document details — typically via OCR, or Optical Character Recognition, the technology that extracts text from photographed documents — and recording that data against the return transaction in the retailer’s system.
In other words, it replaces the manual alternative — a staff member writing a customer’s name and address on a paper return form, or typing it into a terminal — with an automated scan that is faster, more accurate, and creates a structured, searchable record. The identity data captured is not used to authorize or deny the individual transaction in isolation. Its value lies in the cumulative pattern it reveals: a single customer attempting multiple no-receipt returns across locations, or a rotating group of individuals returning the same high-value items across store clusters.
Apart from this, retail identity verification in the age-restricted sales context serves a different but related function. Capturing identity at the point of sale for alcohol, tobacco, vaping products, or lottery tickets creates a documented compliance record that protects the retailer in the event of a licensing inspection or underage sale allegation. Thanks to this, a single scanning infrastructure can serve both loss prevention and compliance functions simultaneously, reducing the cost per use case when deployed across a multi-function retail operation.
The most widely used document capture methods are MRZ reading — the Machine Readable Zone, a standardized two-line strip at the bottom of passports and many national identity cards — PDF417 barcode scanning from the reverse of driving licences, and front-of-card OCR for documents without machine-readable zones. A capable retail scanning solution should handle all three, covering the range of documents customers are likely to present across the retailer’s operating region.
Understanding why manual return controls consistently fail is essential context for designing an effective automated alternative. The failure modes are structural, not simply the result of inadequate staff training.
The majority of return fraud operates through the no-receipt return pathway. Retailers offering goodwill returns without a receipt — a policy designed to serve legitimate customers who have lost their proof of purchase — inadvertently create a channel through which stolen merchandise can be converted to cash or credit without any connection to the original transaction. From a financial perspective, restricting no-receipt returns too aggressively damages customer satisfaction and increases returns friction for honest customers. Capturing identity at the no-receipt return point resolves the dilemma: the policy can remain customer-friendly while the identity record creates the accountability that deters systematic abuse.
Organized retail crime groups exploit the siloed nature of most retail loss prevention systems. An individual executing multiple returns at different store locations generates no alert in any single store’s records, even if their cumulative return volume is clearly abusive. Identity capture linked to a centralized return history database changes this dynamic entirely: the pattern that is invisible store-by-store becomes immediately visible at the network level. These mechanics boost the detection rate for organized cross-location fraud without requiring any change to individual store return policies.
Return desk staff are typically trained to prioritise customer experience and process transactions efficiently. Challenging a customer on a suspicious return requires judgment, confidence, and a willingness to create conflict — qualities that vary significantly across individuals and that diminish under queue pressure. Automated identity capture removes the judgment element: the scan is a standard part of the process applied to every return, not a discretionary challenge that a staff member must decide to initiate. This positively affects consistency and removes the interpersonal friction that causes staff to avoid challenging transactions they should be questioning.
Identity verification at the point of sale delivers its strongest returns in specific retail contexts. Here’s when the investment is most clearly justified:
When evaluating identity verification solutions for retail deployment, pay attention to the following criteria:
Implementing identity verification in a retail returns workflow requires attention to three dimensions simultaneously: the technical integration, the operational process design, and the customer communication approach. Neglecting any one of these dimensions will limit the effectiveness of the others.

Image Unsplash, Simon Hattinga Verschure
Before any technology is deployed, it is crucial to define precisely when identity capture is required: all returns without a receipt, all returns above a defined transaction value, all returns in specific high-risk product categories, or some combination. This policy decision shapes the entire implementation — the workflow design, the staff training, and the customer communication. We recommend starting with a narrowly defined scope — no-receipt returns above a value threshold — rather than attempting to capture identity on every return transaction from the outset, as this allows the team to refine the process before extending it.
The most operationally sensitive element of identity verification at the returns desk is not the technology — it is how staff present the requirement to customers. A customer who understands that identity capture is a standard policy applied consistently to all no-receipt returns is significantly more likely to comply without conflict than one who perceives it as a personal accusation. Staff training should include a specific, practiced script for introducing the scan request, handling common objections, and escalating to a supervisor when a customer refuses. It will be helpful to role-play these interactions during training rather than relying on written guidance alone.
Displaying clear signage at the returns desk indicating that identity may be required for no-receipt returns serves two functions simultaneously. First of all, it sets customer expectations before the interaction begins, reducing the likelihood of conflict when the scan is requested. Secondly, it functions as a deterrent in its own right: a fraudulent returner who sees that identity will be captured may elect not to proceed with the transaction before any staff interaction occurs. Given this, the signage itself delivers measurable loss prevention value at zero incremental operational cost.
Return fraud and organized retail theft are not problems that goodwill policies and staff vigilance can solve at scale. The economics favour the fraudster in any system where returns are processed on trust, where no identity record is created, and where pattern detection requires manual cross-referencing of paper logs. Retail identity verification changes those economics by creating a structured identity record at the transaction point, aggregating that data centrally, and making cross-location and cross-time patterns immediately visible to loss prevention teams.
The implementation investment is modest relative to the shrinkage it addresses. A well-deployed system pays for itself within the first promotional season it covers by reducing the no-receipt return abuse that concentrates around high-value product launches and seasonal promotions. Apart from this, the compliance value it delivers for age-restricted product categories converts what might otherwise be a single-purpose loss prevention tool into a shared infrastructure investment with returns across multiple operational functions. Given this, retailers evaluating their loss prevention strategy should treat identity verification at the returns desk not as a future consideration but as a near-term priority.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 27, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Regulation And Policy, Payments And Market Infrastructure, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026).
The RBA is moving past short pilots. The focus now is how tokenised money works with existing settlement systems and what holds up under real use.
The SEC is narrowing one regulator facing CAT access path in the name of cost savings while keeping other query methods in place. That doesn't change trading rules, but it can change how efficiently regulators search market activity and build surveillance cases, and to that extent there are some concerns around reduced oversight.
Fully paid lending goes from exemption based programs to a standard rule set. Dealers need to update inventory funding structures and controls before the effective date.
Tokenization is now being discussed inside the core U.S. capital markets policy process, with major market infrastructure and exchange voices at the table. That raises the odds that tokenized securities will be treated as a market structure question tied to trading, clearing, settlement, and custody, not only as a digital asset issue.
Lynn Martin, President, NYSE Group: “As we explore how tokenization can enhance capital markets, it is critical that new infrastructure is developed in a way that preserves the trust, transparency, and protections investors expect. Securitize brings deep experience in digital asset infrastructure and transfer agency, making them a strong partner in helping design this next generation of market structure.”
India is moving from payment expansion to payment control. Fraud liability, cyber resilience, cross border authorisation, and switching now sit closer to the centre of the next build cycle for banks, payment firms, and fintech infrastructure providers.
Visa is getting into the infrastructure layer. Privacy has been one of the main blockers for banks and large financial institutions using shared blockchain systems. If that barrier starts to fall, onchain payments, settlement, and treasury activity can move closer to core financial market infrastructure.
FMI oversight expectations set the operating floor for payments and clearing infrastructure, which can flow through to participant requirements, vendor controls, and resilience planning.
This brings tokenized cash into live institutional money movement. It's a major Canadian bank using tokenized cash to support real margin, collateral, and settlement flows on a continuous basis. Tokenized money is moving deeper into market infrastructure and gives regulated institutions a way to move value when markets need it 24/7, not only during banking hours.
Deloitte and Stablecorp are building integration paths for financial institutions to use QCAD inside existing systems. The work targets clearing, treasury, and cross-border flows, but no deployments or pilots have been confirmed yet. Treat this as a signal that stablecoin infrastructure is being wired into bank workflows ahead of regulatory clarity.
This closes a multi phase refresh and sets a new baseline for dealer compliance interpretation across UMIR topics, which can flow into policy mapping, training, and vendor rule logic.
Bill C-15 puts stablecoins, payments, and consumer-driven banking under a more unified central bank structure. Firms now need to plan for supervision across digital money and data-sharing models, not treat them as separate tracks.
Event contracts are now included in a defined Canadian dealer framework. Firms need to clear product design, compliance, and notification before going live.
AI assisted authorisations and automated reporting feeds can shorten approval timelines and change how supervision picks up issues from live data.
Sarah Pritchard, Deputy Chief Executive, Financial Conduct Authority: “We want to see more people getting supported, who aren’t currently, and a market that innovates and offers tailored services to meet differing consumer needs.”
Dealers and fintech vendors that support eDiscovery, recordkeeping, surveillance, and investigation response workflows now have a clear CIRO baseline for data handling, metadata preservation, and production process design.
Courts are beginning to test whether engagement led product design itself can create liability at scale. If that theory survives, the impact reaches beyond social media. Any digital product that depends on compulsive use patterns, especially where minors or vulnerable users are involved, faces legal scrutiny and compliance costs.
August 6 update: A New Mexico court ordered Meta to establish a US$567M abatement fund, bringing the financial remedies in the case to US$942M, and imposed youth-safety requirements covering age assurance, teen usage and notifications, adult-minor contact controls and AI-chatbot interactions involving minors. Meta plans to appeal.
As more execution flows move through automated and intermediated channels, CIRO is making it clearer who is responsible, how orders must be marked, and what supervision has to look like. That raises the operating standard for dealers, trading desks, legal and compliance teams, and firms providing marketplace access. Electronic access remains open, but responsibility for supervision, order marking, and control cannot blur as more parties exist between the client and the marketplace.
This raises the risk that sports prediction markets face a direct statutory limit before the category settles into a stable regulatory path. Congress is now testing whether these contracts belong inside federal market infrastructure or back inside state gambling rules. Important for exchanges, prediction market operators, legal teams, and investors betting on event contracts as a durable product category.
This series puts AI governance in focus for banks and fintechs, especially around model risk, cybersecurity controls, and how supervisors assess AI driven decisioning inside core workflows.
China is using tax data, regulated data sharing, and specific technologies to push more SME credit through banks. That is a lending infrastructure signal, not just a blockchain headline.
Regulators are setting clearer boundaries, and infrastructure is moving into production at the same time. That combination raises the cost of getting it wrong and shortens the window to get it right. Teams need working controls, real vendor oversight, and systems that hold up under load before scaling anything customer facing. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 27, 2026 | NCFA Fintech Market Activity | Payments And Money Movement
Image: Freepik
On March 27, 2026, CoinPayments partnered with OSL Group to expand in APAC. The deal gives CoinPayments access to local payment rails and fiat off ramps across the region.
APAC is already a large and fast growing crypto market. Chainalysis' 2025 global crypto adoption reported that APAC transaction volume increased to $2.36T, up from $1.4T in a 12 month period ending June 2025. Crypto payments need merchants for local conversion, payout, and settlement that works in the market they serve.
CoinPayments brings real scale into that push. The company said earlier this month that it has processed more than $50B in crypto transactions and supports more than 250,000 merchants globally.
OSL brings a different advantage. After completing its Banxa acquisition in January 2026, OSL said its regulatory footprint expanded to more than 40 trading and payment licenses and registrations across the United States, Canada, the European Union, the United Kingdom, and Australia.
That gives the partnership a clear commercial logic. CoinPayments brings merchant reach. OSL brings regulated payout and conversion infrastructure. The March 27 announcement also builds on CoinPayments’ existing work with Banxa, so the operating link was already there before this APAC push.
In crypto payments, which creates more leverage over time: merchant reach or control of local payout and off ramp infrastructure?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 26, 2026 | NCFA Insight | Artificial Intelligence And Data
On March 1, 2026, CodeWall, a security research firm focused on AI systems, privately reported security gaps to McKinsey. The firm said its agent found 22 unauthenticated endpoints, then chained a SQL injection issue and other weaknesses to gain read and write access across the production environment. CodeWall said the reachable data included 46.5 million chat messages, 728,000 files, 57,000 user accounts, 384,000 AI assistants, and 94,000 workspaces. It also said prompts, model configurations, and RAG related data were reachable.
On March 2, 2026, McKinsey acknowledged the findings and patched the unauthenticated endpoints the same day.
On March 9, 2026, CodeWall publicly shared research on vulnerabilities in McKinsey’s internal AI platform Lilli.
On March 11, McKinsey released this statement about the vulnerability and that a third party forensic review found no evidence that unauthorized parties accessed client data or client confidential information.
Public API documentation appears to have exposed a map of the system. Some endpoints reportedly required no authentication. One of them allegedly allowed database manipulation through JSON keys, which opened the door to SQL injection. From there, CodeWall said it could determine live production data and reach much deeper parts of the platform.
This incident doesn't point first to a model failure. It points to ordinary application security weaknesses around an AI system that had become deeply embedded in internal work.
McKinsey didn't confirm the full scale of the researcher claims. Instead, it focused on the response. The company said it fixed the issue quickly and found no evidence that unauthorized parties accessed client data or client confidential information.
Having said that, the reported scale of reachable internal material was large enough to raise questions about internal knowledge exposure, employee work patterns, and intellectual property concentration in one system.
CodeWall said prompt and configuration layers were reachable. If true, it means a bad actor could have potentially altered how the system retrieves information or generates answers. In an internal AI tool, that can create wrong outputs that look normal to staff.
That's where this type of incident becomes more useful for fintechs and financial firms. A publicly visible outage gets noticed whereas quietly altered outputs may not. In regulated environments, that can affect approvals, reviews, client treatment, policy interpretation, and internal decision support before anyone spots the pattern.
Banks, lenders, insurers, wealth firms, and fintechs are building similar internal AI layers right now. They connect those tools to policy documents, research, support logs, internal files, and customer related workflows because it saves time and helps staff move faster.
But that convenience comes with risk given that AI often pulls sensitive access into one place. If permissions are weak, endpoints are exposed, or prompt controls aren't protected, one internal tool can become a wider point of failure.
A key lesson founders and operators should take from this case, is to ask whether the application around it is locked down, whether prompts and retrieval rules are treated as sensitive assets, whether permissions are tight, and whether anyone has tested the system the way an attacker would.
Enterprise AI doesn't erase old security mistakes. It can magnify them by concentrating data, access, and trust inside a single interface.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 26, 2026 | NCFA Fintech Market Activity | Banking And Credit, Digital Assets And Tokenization
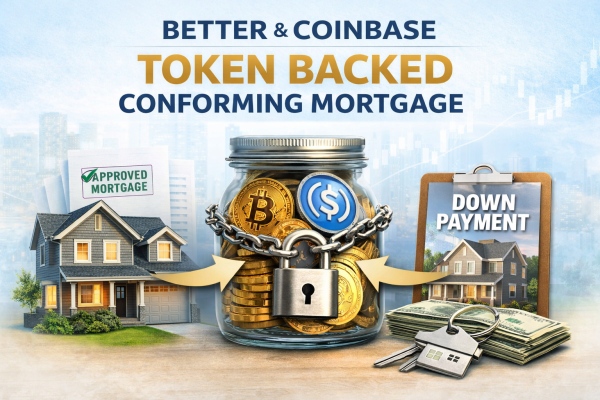
On March 26, 2026, Better and Coinbase launched the first token backed conforming mortgage. Qualified borrowers can pledge Bitcoin or USDC to fund a cash down payment while still taking out a standard mortgage that meets Fannie Mae rules. The structure lets borrowers use digital assets without selling them first and without automatically triggering a taxable sale event.
The product targets a large and growing borrower base. Better and Coinbase put the addressable market at 52 million Americans who own digital assets, equal to 20% of American adults. They also mention quite an age split, with 45% of younger investors holding crypto versus 18% of older investors. That age gap means it's much harder for younger buyers to meet traditional down payment cash requirements, yet many already hold part of their savings in digital assets.
There are no margin calls and no required top ups if Bitcoin falls in value. Price moves alone do not trigger liquidation. Collateral comes into play only if a borrower becomes 60 days delinquent, under the same treatment applied to standard conforming mortgages. Borrowers using USDC can also earn rewards on pledged balances, which may offset mortgage payments and lower the net effective rate.
The buyer profile is also broader than a luxury crypto niche. Better and Coinbase said 67% of token holders are 45 or younger and 26% earn less than US $75,000 a year. They also pointed to Redfin data showing 12.7% of Gen Z and Millennial homebuyers have already sold tokenized assets to fund a down payment, versus 3.5% of Gen X and 0.5% of Baby Boomers.
Digital assets are now included in standard mortgage structure, not just a trading or investment account. Token holdings now help fund a conforming mortgage down payment without forcing a sale first. As this model grows, digital assets will look less like something borrowers need to liquidate and more like collateral lenders may be willing to work with.
Better and Coinbase also plan to expand eligible collateral over time to include tokenized equities, fixed income, and tokenized real estate assets. If that happens, the story will not stop at mortgages. It will continue to proliferate into which consumer lending products can absorb token backed collateral and under what terms.
If digital assets can now help fund a conforming mortgage, which standard lending products could be next to accept token backed collateral?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 25, 2026 | NCFA Fintech Market Activity | Digital Assets And Tokenization
On March 25, 2026, BitGo added qualified custody support for USDCx and cBTC on the Canton Network. This expands its role on Canton beyond Canton Coin and into CIP-56 assets, the token format Canton uses for regulated financial markets.
The CIP-56 token standard supports private transactions, built in KYC and AML controls, delivery versus payment settlement, and final settlement within seconds. Those features give institutions the controls they need to use tokenized assets in real collateral and settlement workflows.
Canton describes itself as a privacy enabled blockchain network for institutional assets, with about 600 validators live and more than 15 million monthly transactions using Canton Coin in their flows. That's why BitGo's expansion is interesting because it plugs additional assets into a network that's already being built for regulated financial activity, not retail token trading.
USDCx already serves as the settlement currency for out of hours repo settlement and tokenized collateral workflows on Canton. It is issued through Circle’s xReserve framework. cBTC adds bitcoin backed liquidity to the same environment, giving firms another asset they can use across collateral and settlement activity. This isn't just broader token support. It makes the settlement layer more usable.
Qualified custody for Canton Coin launched in October 2025, and token support followed in less than six months. The work is no longer just about putting assets onchain. It is about building the custody, collateral, and settlement stack that institutions need around them.
Canton is also drawing in more institutional infrastructure, including tokenized money market fund infrastructure from Goldman Sachs and BNY. This BitGo move adds another piece to the same buildout. If tokenized finance is going to work at scale, firms need more than issuance. They need custody that institutions trust, settlement assets they can use, and compliant rails that hold up under real volume. That's where commercial value is starting to concentrate.
As tokenized markets add stablecoin settlement, bitcoin backed liquidity, and qualified custody, which firms become hardest to replace?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016