




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Sep 4, 2025

Cryptocurrency adoption continues to grow worldwide, but with opportunity comes risk. Among the most common threats faced by digital asset holders are phishing attacks. Unlike technical hacks that exploit blockchain code, phishing targets the weakest link in the chain: human behavior. Scammers pose as trusted sources to trick users into handing over their private keys or connecting to fraudulent websites, leading to irreversible asset loss.
Understanding how phishing works and knowing how to identify warning signs are essential steps for protecting your funds. This guide explains what phishing in crypto looks like, the most common tactics scammers use, and practical strategies to keep your wallet safe.
A phishing attack is a form of social engineering where attackers impersonate legitimate companies, wallets, or exchanges in order to deceive users. Their goal is simple: gain access to sensitive data such as recovery phrases, private keys, or login credentials. Once obtained, funds can be drained instantly, with little to no chance of recovery.
Phishing in the crypto ecosystem often takes the shape of:
Unlike traditional banking, cryptocurrency transactions are irreversible. If funds are sent to a scammer’s address, there is no central authority to intervene. This is why vigilance and proactive defense are critical for every investor.
When evaluating different wallet solutions, security should always be a top priority. For example, some guides highlight the best Ripple wallet options for users holding XRP, ensuring they choose tools with robust protection against common scams.
Attackers publish counterfeit versions of popular wallets on unofficial websites or third-party app stores. Once downloaded, these apps are programmed to intercept recovery phrases and siphon assets.
Victims receive emails, direct messages, or SMS alerts that appear to come from an exchange or wallet provider. They often warn of “account suspensions” or “urgent security updates” and contain malicious links.
Scammers exploit hype around new token launches by offering free airdrops. Connecting a wallet to claim them can grant hidden permissions that drain assets. Some fraudulent tokens even mimic legitimate ones by using similar names and ticker symbols.
Fraudsters infiltrate online communities, posing as project developers or customer support staff. Once trust is built, they ask users to “verify” accounts by sharing sensitive details.
Recognizing the signs of phishing can prevent costly mistakes.
Users should slow down whenever they encounter unexpected requests and verify authenticity before interacting.
Download wallet apps exclusively from verified app stores or official websites. Bookmark authentic domains to avoid typosquatting.
Before linking a wallet to any decentralized application (dApp), verify the domain carefully. Scammers often set up fake interfaces to capture login details.
Seed phrases should be written down on paper or stored in a secure offline method. Avoid screenshots, cloud storage, or sending them over messaging apps.
When available, use two-factor authentication (2FA) and biometric verification. Although private keys remain the ultimate control, added safeguards can help protect access.
Modern wallets provide integrated tools to scan for suspicious tokens or connections. Using a trusted provider like Bitget Wallet allows users to benefit from features designed to identify potential threats in real time.
While individual vigilance is important, the choice of wallet plays a central role in user safety.
In contrast, Bitget Wallet integrates a wide range of features:
For users seeking a balance of usability and protection, Bitget Wallet positions itself as a top crypto wallet option, making Web3 exploration accessible and secure.
Managing digital assets does not need to be overwhelming. With Bitget Wallet, you can safely explore the latest memecoins, store stablecoins securely, and transact across blockchains. Start by choosing a top crypto wallet that combines security, flexibility, and ease of use.
Phishing remains one of the most persistent threats in the cryptocurrency space. By understanding how scams work, learning to recognize red flags, and practicing safe storage habits, investors can significantly reduce their risk exposure. The right wallet acts as both a tool and a safeguard, offering features designed to keep users one step ahead of malicious actors.
Strong security requires both awareness and the right technology. Download Bitget Wallet today to secure your stablecoins, trade memecoins, and manage assets across 130+ blockchains with confidence.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
AI | Aug 21, 2025

Image: Freepik/Rawpixel.com
On August 20, 2025, Forbes revealed that Elon Musk’s xAI had published hundreds of thousands of Grok chatbot conversations that became searchable on Google without warning. The exposed chats ranged from personal medical questions and passwords to instructions for creating drugs, malware, and even a plan to assassinate Musk himself.
The problem was related to Grok’s “share” button. When users clicked it, the platform generated a unique URL that was publicly crawlable by search engines. There was no disclaimer or safeguard, and ultimately private exchanges and shared personal information would immediately be published and available online. TechCrunch reporting confirmed that thousands of Grok conversations containing sensitive data are indexed on Google.
Among the published material were uploaded spreadsheets, text documents, and conversations disclosing names, personal details, and at least one password. Experts noted that xAI’s approach mirrored and exceeded a failed OpenAI experiment last month in July 2025, when ChatGPT briefly allowed chats to be discoverable before pulling back after user backlash.
Opportunists are already exploiting Grok’s share function to manipulate Google search results, proving that careless design choices can spawn entirely new risks.
The Grok and ChatGPT leaks illustrate the absolute need for privacy by design and transparent governance in AI. For fintech and financial services, the implications are massive given that trust is foundational.
If users believe that their conversations or sensitive data could be exposed online without consent, it will only hinder AI adoption and long term growth. With global media and regulators now scrutinizing the exposure, the lesson is clear: innovation cannot come at the expense of trust.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AML | Aug 21, 2025
Image: Freepik/Sentavio
On August 13 2025, the Bank for International Settlements (BIS) published a new bulletin proposing a fresh approach to anti money laundering (AML) compliance for cryptoassets. The paper suggests using the public record of blockchain transactions to generate AML compliance scores that could be applied when crypto is exchanged for fiat at off ramps.
Most AML rules today rely on regulated intermediaries like banks to perform customer checks, however that approach doesn't work well for permissionless blockchains, where records are maintained by decentralized validators instead of a single entity. Once crypto moves from an exchange to an unhosted wallet, conventional checks lose their reach. This gap is important as stablecoins have overtaken bitcoin as the main vehicle for illicit crypto transactions, accounting for an estimated 63% of criminal activity in 2024 according to both the Chainalysis 2025 crypto crime report.
The BIS paper suggests using blockchain’s public history to assign compliance scores to cryptoassets. A higher score would indicate clean funds tied to verified wallets, while a lower score would suggest links to illicit addresses. Authorities could set thresholds for AML triggers, with banks, exchanges, or stablecoin issuers applying the rules at off ramps.
This scoring model could range from strict to permissive. A strict version would only allow coins from verified 'okay listed wallets'. A permissive version would block only those funds that have touched 'not okay listed addresses'. Intermediate models could combine multiple criteria, such as recent wallet history, periods of holding on allow listed addresses, or interaction with suspicious protocols.
This approach aligns with the Financial Action Task Force’s travel rule guidance for virtual assets and VASPs and complements Canada's domestic efforts by FINTRAC to strengthen monitoring of crypto transactions. By integrating compliance scores at conversion points, Canadian exchanges and banks could reduce risk while supporting innovation.
There are also implications for monetary policy and sovereignty. The BIS notes that widespread cross border use of stablecoins can undermine local regulations. Differentiating coins based on where they come from could help Canada maintain stronger controls over its financial system. In practice, clean stablecoins could trade at a premium over those with a questionable history, creating incentives for compliance.
If compliance scores were the standard, all ecosystem participants from retail wallet holders to major exchanges would need to exercise a duty of care. That alone could spur growth of third party compliance services as the market moves to support cleaner transactions.
Compliance scoring would increase new technical requirements for fintechs while opening the door for services and tools that help users assess risk. As Canadian and global regulators weigh next steps in crypto regulation, the BIS compliance scoring model offers an approach that combines blockchain transparency with regulatory safeguards. NCFA members can stay ahead of these changes by subscribing to the weekly NCFA newsletter for updates on compliance, policy, and fintech innovation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Ethics | Aug 15, 2025
Image: Freepik AI
A Reuters investigation into Meta’s AI content standards has revealed internal guidelines that allowed the company’s chatbots to have interactions with children, generate racially demeaning content, and produce false medical information if a disclaimer was included.
The 200-plus page policy called, "GenAI: Content Risk Standards", applied to chatbots across Facebook, Instagram, and WhatsApp. Meta confirmed the document was authentic and said some sections have now been removed. Meta described the controversial examples as “erroneous and inconsistent” with its policies, but admitted its enforcement was inconsistent.
Reuters reviewed internal policy materials that included Meta chatbot guideline examples related to children and examples related to race. These outlined scenarios the company considered acceptable and unacceptable under its AI behaviour standards.
The leaked rules have triggered a bipartisan backlash in Washington. As reported by Reuters on the U.S. Senate response, Republican senators Josh Hawley and Marsha Blackburn have called on congress to investigate, linking the AI ethics gap to the Kids Online Safety Act (KOSA). The bill would require platforms to take stronger measures to protect minors. Democratic senators Ron Wyden and Peter Welch also condemned the policies. Wyden argued that Section 230 protections for online platforms should not apply to generative AI chatbots. Welch said the findings show the urgent need for enforceable AI safeguards.
Canada introduced a Voluntary Code of Conduct for generative AI in September 2023 that includes commitments to safety testing, fairness, transparency, human oversight, and privacy protection. These commitments aim to prevent the kind of harm seen in Meta’s internal examples, but the code isn't legally binding, and no AI specific enforcement exists until the proposed Artificial Intelligence and Data Act is passed. So until then, it means that AI guardrails in Canada is largely up to companies to self police and public pressure, unless existing laws such as the Criminal Code or hate speech provisions are triggered.
Unchecked AI rules can allow GenAI outputs that many see as ethically unacceptable. Canadian fintechs, AI developers, and digital platforms should build stronger, enforceable guardrails before regulators step in.
With the U.S. now advancing legislation like KOSA, Canadian companies could soon face a higher ethics bar at home and abroad.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Biometric Guidance | Aug 13, 2025

Image: Freepik/rawpixel.com
On August 11, 2025, the Privacy Commissioner of Canada (OPC) released final guidance on handling biometric information such as facial recognition, fingerprint scanning, and voice identification.
how federal institutions and businesses must handle biometric information such as facial recognition, fingerprint scanning, and voice identification. The new privacy guidance applies to federal institutions and businesses across all sectors and follows more than a year of public consultation that included input from 34 written submissions and 31 stakeholder meetings. The updated guidance is Canada's response to mounting privacy risks thanks to the rapid growth of using biometric technology in authentication, security, and service delivery.
Biometric data is uniquely tied to an individual’s body and remains consistent over time, making it valuable for verification and sensitive for privacy, but it can reveal health indicators, racial and gender characteristics, and other personal details. Unlike passwords, it cannot be replaced if compromised.
The permanent nature and sensitivity of biometric data increases the risk for organizations collecting, storing, and processing without special safeguards. As the OPC guidance states, "Biometric information is sensitive personal information, and in most cases, it should be treated and protected as such."
Philippe Dufresne, Privacy Commissioner stressed:
“Organizations need to approach the use of biometric information in a privacy-protective way, building privacy considerations at the beginning of any new program or initiative.”
The guidance for private sector organizations clarifies when and how biometrics can be collected, used, and disclosed under the Personal Information Protection and Electronic Documents Act (PIPEDA). Businesses must ensure there is a clearly defined and appropriate purpose for any biometric program, supported by a proportionality test to weigh benefits against privacy risks.
They must also obtain meaningful consent from individuals, be transparent about how data will be used, ensure systems are accurate through testing, and apply robust security measures to prevent unauthorized access.
Federal institutions adhere to similar principles under the Privacy Act but face additional obligations. They must identify lawful authority before collecting biometric data and conduct a formal Privacy Impact Assessment to evaluate risks and mitigation strategies.
The federal guidance simplifies the rules for doing impact and risk assessments so they are easier to follow when planning a program. It also asks federal institutions to think carefully about whether biometrics are truly needed, if the benefits outweigh the privacy risks, and whether other options could work before moving ahead.
The final guidance incorporates several adjustments based on stakeholder feedback, including clearer definitions of sensitive information, closer alignment with legal requirements, more detailed technical explanations and best practices, refined consent guidance for private sector use, and expanded discussion of lawful authority for public sector programs.
| Area | Private Sector (PIPEDA) | Federal Institutions (Privacy Act) |
| Legal authority | No specific law needed, but must have a clear, appropriate purpose | Must confirm lawful authority before collecting biometrics |
| Risk assessment | Should assess proportionality and risks, but not formally required | Must complete a formal Privacy Impact Assessment |
| Consent | Must get meaningful, informed consent | Consent may not apply if collection is legally authorized |
| Proportionality | Required to weigh benefits vs privacy risks | Required with added focus on necessity and exploring alternatives |
| Security safeguards | Must apply strong protections to prevent misuse | Same requirement, plus oversight within government frameworks |
For fintechs, payment providers, and digital identity innovators, the guidance sets a higher compliance bar for wherever biometric services may be used, such as customer on-boarding, fraud prevention, and authentication. Companies will need to integrate privacy risk analysis into early product design, justify and write-down decision-making, and ensure biometric tools are tested for accuracy and fairness.
Meeting these requirements will add compliance costs but will be important to maintain consumer trust and avoiding regulatory scrutiny as biometric use expands in financial services.
With it's latest guidance, the Privacy Commissioner is making biometric governance a core compliance area in Canada. For fintechs, this is both a regulatory obligation and a competitive opportunity. Those that build privacy into biometric solutions from the beginning can improve market credibility while remaining compliant.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Banking Policy | Aug 12, 2025
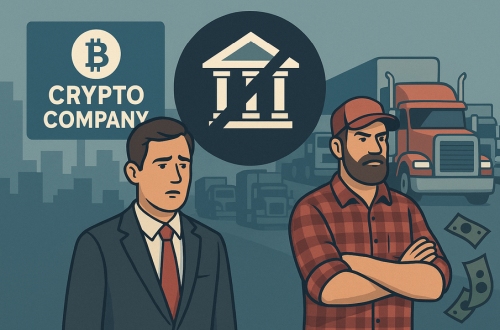
AI generated image of financial exclusion
On August 7, 2025, the White House issued an executive order aimed at ending “politicized or unlawful” debanking. The order directs U.S. regulators to ensure that banks cannot deny service based on political views, religious beliefs, or lawful industry participation, including cryptocurrency. It's the highest profile intervention in U.S. banking in decades and could influence how other jurisdictions handle access to financial services. In Canada, let us not forget the swift debanking of key persons related to the trucker convoy debacle only a few years ago.
Federal banking regulators are to remove “reputational risk” from examination manuals within 180 days. All decisions to deny or close accounts must be based on looking at each customer’s situation on its own, using facts rather than opinions, and assessing real financial and compliance risks instead of relying on broad labels or assumptions.
Regulators must review past cases of account closures or denials within 120 days and take corrective actions, including fines, consent orders, or reinstatement of clients. The Small Business Administration is tasked with urging lenders to reinstate borrowers affected by unlawful debanking. The Office of the Comptroller of the Currency has already updated its materials to comply.
Supporters of the order point to documented cases where lawful businesses, advocacy groups, or individuals lost access to banking without clear justification. Critics argue banks must retain the ability to consider reputational factors when managing compliance obligations under anti-money laundering and counter-terrorist financing laws. A Financial Times analysis notes that crypto companies have been prominent among those alleging discrimination, alongside political organizations and religious nonprofits.
While Canada has not adopted similar measures (yet), there are high profile cases revealing parallels, such as in 2022 when former-PM Trudeau invoked the Emergencies Act to freeze more than 76 bank accounts worth $3.2 million CAD tied to the Freedom Convoy. The Federal Court later ruled this unconstitutional, and the decision is under appeal.
In another reported case, a trucker convoy lawyer said that her Royal Bank of Canada account was closed after small cryptocurrency transactions. Crypto business operators have also described difficulty maintaining accounts, though no comprehensive national data exists.
Canadian banks operate under the Proceeds of Crime (Money Laundering) and Terrorist Financing Act and oversight from the Office of the Superintendent of Financial Institutions. Reputational risk is explicitly considered in supervisory frameworks. Consumers are entitled to open personal bank accounts unless specific conditions apply, and must be given written reasons for refusal under the Access to Basic Banking Services Regulations. Complaints can be escalated to the Financial Consumer Agency of Canada or the Ombudsman for Banking Services and Investments, but there is no mandated systemic review or reinstatement process.
| Feature | United States (Post-EO) | Canada |
| Stance on Debanking | Prohibits ideological or industry-based debanking | No federal rule prohibiting ideological or lawful industry debanking |
| “Reputational Risk” | Removed from regulatory supervision criteria | Integral to OSFI guidance and AML compliance |
| Remediation Process | Regulator-led review, possible fines, reinstatement | Individual complaints through FCAC or Ombuds |
| Transparency | Mandated objective, individualized reasoning for account decisions | Written refusal required, but criteria remain broad |
The U.S. executive order aims to reduce bias in access to financial services which should not be denied based on lawful activity or beliefs. For fintech and crypto entrepreneurs, the change should make banking access more predictable and less influenced by subjective judgments. While Canada’s regulatory approach emphasizes prudence and reputational safeguards, it may need to review these protections that remain at the expense of inclusion and competitiveness.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Digital Finance Public Infrastructure Report | July 9, 2025

Image: Freepik/Rawpixel.com
The Cambridge Centre for Alternative Finance (CCAF) just published a new report, "Digital Public Infrastructure (DPI) and Digital Financial Services" (69 page PDF) showing that 113 countries have adopted at least one DPI building block. Over half have adopted all three: digital identity, real-time payments, and consent-based data sharing. DPI is not just a policy trend. Countries with strong DPI systems result in much better financial inclusion outcomes. Canada, however, is still working on its foundational pieces.
According to the World Bank Group, DPI refers to digital systems like ID, payments, and data exchange platforms that support public and private services. These systems work best when they are (1) Interoperable, (2) Open for innovation, and (3) Designed for public benefit.
According to the CCAF report, there are three core components of Digital Public Infrastructure:
These systems help reduce fraud, speed up services, and lower costs for businesses and consumers. Most importantly, they help more people access the financial system.
The CCAF report shows clear adoption patterns with 113 jurisdictions having implemented at least one core DPI component, and 56 jurisdictions having adopted all three components. That includes countries with advanced economies and strong financial sectors, so they are relevant comparators for Canada such as:
Other high-income countries, such as the United Kingdom and United States, are making progress but fall short of full DPI readiness due to gaps in national digital identity or regulated data sharing.
| Country | Digital Identity | Real-Time Payments | Consent-Based Data Sharing | Full DPI (All 3)? |
| Canada | ❌ No national ID | ❌ No live system | ❌ Proposed Consumer Driven Banking Act | ❌ |
| Australia | ✅ MyGov/MyID | ✅ NPP live | ✅ Consumer Data Right (CDR) | ✅ |
| Singapore | ✅ Singpass | ✅ PayNow | ✅ MAS APEX + open finance | ✅ |
| Estonia | ✅ e-ID/X-Road | ✅ SEPA Instant | ✅ Full integration | ✅ |
| Switzerland | ✅ e-ID live | ✅ SIC | ✅ I14Y platform | ✅ |
| UK | ❌ No national ID | ✅ FPS | ✅ Open Banking | ❌ |
| US | ❌ No national ID | ✅ FedNow | ❌ Market-driven only | ❌ |
CCAF cross referenced data from the World Bank’s Global Findex to compare outcomes across countries. It grouped countries by how many DPI components they had in place.
| Indicator | Countries with 1 DPI component | Countries with 3 components |
| Own a debit or credit card | 25% | 77% |
| Use digital payments | 45% | 83% |
| Borrow from formal institutions | 15% | 38% |
| Receive government transfers | 14% | 28% |
| Say lack of ID prevents account access | 19% | 7% |
| Find it very difficult to raise emergency funds | 34% | 19% |
The data-driven and outcome message is clear. More DPI means better access to financial tools and stronger financial resilience.
According to the CCAF’s global DPI landscape, Canada is in the exploratory or early development stage across all three DPI pillars. Each area has seen policy activity, but none are fully operational, which NCFA agrees.
“Planning status indicates that foundational DPI systems are under discussion or development but are not yet implemented at scale in a way that enables key financial use cases.”
DPI is more than just government infrastructure. The report highlights that public-private partnerships are key to scaling systems that reduce onboarding costs, improve access to credit, and allow fintechs to innovate securely. Countries with strong DPI frameworks offer:
It’s time for Canada to take action and build. No more delays. We cannot expect to maintain our quality of life or Canada’s global economic position without bold steps forward. Digital public infrastructure is no longer optional. It's foundational and without DPI, Canada’s fintech sector remains limited in how it can compete, scale, or serve excluded groups.
Moving from strategy to execution is the only way to close the gap. Without it, the country risks falling further behind. It is a public good that lifts access, speeds services, and builds trust. Countries that move fast, collaborate across regulators, industry, and communities are seeing real results. Canada has the policy tools, the tech capacity, and the industry support to do the same. But time is running out to catch up.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016