




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 4, 2026 | NCFA Fintech Market Insight | Regtech And Identity And Privacy

On Feb 16 2026, an interesting post at The Local Stack conducted a recent LinkedIn identity verification analysis via a real user experience of a larger fintech issue: modern identity checks now collect far more than most people expect, and the privacy tradeoff is becoming harder to ignore as regulated onboarding expands across financial services, platforms, and digital marketplaces.
Persona’s identity verification policy shows the scale of that collection. The policy lists government ID images, selfies, biometric information, NFC chip data, device data, geolocation, usage data, and checks against third party data sources. It also states that uploaded ID images may be used to train or improve the service, and that information may be shared with service providers, data partners, affiliates, and government authorities in some circumstances.
1. Identity verification now reaches well beyond document review. A current verification flow can combine document capture, face matching, biometric analysis, device signals, location data, and external database checks in one session. That means the onboarding event is no longer just a fraud control. It is a multi layer data collection workflow that carries legal, operational, and reputational risk.
2. The trust layer often sits with a specialist vendor, not the brand the user sees. A customer may think they are verifying with LinkedIn, a bank, or a fintech app. In practice, the verification is often run by a third party with its own privacy terms, data sources, subcontractors, retention rules, and model improvement rights. That gap between front end trust and back end processing is where privacy friction starts.
3. Privacy design now affects conversion. When users feel overexposed, abandonment risk rises. Firms that explain what's collected, why it's needed, who processes it, and how long it's kept are more likely to keep trust intact through onboarding. In identity verification, transparency is becoming part of product design.
Map every data field in the verification flow, not just the front end prompts. Disclose which vendor runs the check and what that vendor can do with the data. Remove optional collection that doesn't improve the actual risk decision. Review training, retention, and subcontractor clauses in vendor contracts. Put the plain language explanation before the scan starts, not after the user has already submitted a passport and selfie.
These steps become more important as Canada moves toward broader data portability and consumer directed finance. NCFA has already covered the wider privacy backdrop in North America privacy trends and the policy direction in CSA data portability consultation. Canada’s consumer-driven banking framework and the Consumer-Driven Banking Act push the market toward safer, permissioned data sharing. As that framework matures, identity credentials may become more reusable across providers, which could reduce repeated document collection while increasing pressure for stricter consent controls, narrower data use, and clearer liability when verification vendors sit in the middle.
Identity verification is moving from a hidden compliance step to a visible trust product. More onboarding flows will combine biometrics, device intelligence, and third party data. More enterprise buyers will ask whether vendors can use customer data to improve models. More regulators will look at whether the scope of collection matches the actual risk being assessed. The firms that win will not be the ones that collect the most data. They will be the ones that collect the least data needed to deliver a defensible result.
When identity checks collect more than most users expect, do the firms with the clearest privacy design earn more trust than the firms with the most aggressive control stack?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 4, 2026 | NCFA Fintech Market Insight | Digital Assets And Policy And Regulation
Image: Freepik/diana.grytsku
On February 27 2026, the FCA set the application window for UK cryptoasset permission under the Financial Services and Markets Act 2000. The window opens on September 30 2026 and closes on February 28 2027. FCA webinar guidance also points to October 25 2027 as the date the new regime goes live.
This confirms the UK is moving crypto firms into the same permissioned structure used across traditional financial services (UK draft crypto rules). A firm that already operates under anti money laundering registration now faces a full authorisation process, a narrower transition path, and a higher standard on governance, controls, safeguarding, financial resources, and senior accountability.
The UK model prioritizes integration with established financial regulation. It raises the operating bar and can favour firms with stronger compliance infrastructure, clearer ownership structures, and the capital to support ongoing supervision. That can improve institutional credibility, but it also increases readiness cost and raises the threshold for smaller firms.
The EU model is different. MiCA creates a dedicated crypto rulebook, and that structure supports cross border expansion through one member state authorisation and EU passporting. One licence can open access across the single market. NCFA has already covered that operating advantage in MiCA licence unlocks EU access.
Canada has a domestic passport framework, but it's not the same as EU style passporting across sovereign countries inside a single massively connected market. CSA regulatory cooperation reduces duplication across participating provinces and territories, but Ontario does has not formally adopted the passport rule despite Canada's need to reduce duplication and regulatory burden. Ontario's passport status still emains outside MI 11-102, with Ontario using an interface and reliance model instead.
A Canadian crypto platform can use the passport process to expand across much of Canada, but of course it doesn't get the scale benefit that MiCA passporting provides across the EU with market access to 450 million. The compliance cost can still be high, while the addressable market remains much smaller. Canada also continues to raise the operating bar through supervision and custody expectations, including CIRO’s digital asset custody framework. See: NCFA’s Weekly Fintech Intelligence Jan 31-Feb 6, 2026.
Collectively this puts Canada's approach to crypto regulation closer to the UK on operating discipline than to the EU on market scale. Also worth noting varying consumer differences between UK and Canada crypto consumers.
These models now reward different business strategies. The UK offers deeper integration with traditional financial supervision and may suit firms that want institutional positioning, bank grade credibility, and a tighter regulatory perimeter.
The EU offers faster regional scale through passporting and may suit firms that need broader customer reach across multiple markets.
Canada offers a more controlled path, but one that can be slower to scale and more operationally demanding relative to market size.
For exchanges, brokerages, wallets, custody providers, and compliance firms, this is now a jurisdiction choice with direct consequences for licensing cost, expansion speed, product sequencing, and capital planning. For investors, it changes where operating leverage may be easiest to achieve. The question is not whether crypto gets regulated. The question is which regulatory architecture creates the best conditions for durable growth.
When the UK raises the authorisation bar, the EU offers passporting scale, and Canada keeps a tighter supervised path, which model attracts more builders, more capital, and more long term market share?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 4, 2026 | NCFA Fintech Market Activity | Regtech And Financial Crime Compliance
AI image robot analyzing financial data in office
On March 4 2026, UK based Vivox AI raised £1.3 million to scale AI agents built for AML, KYB, and KYC workflows inside regulated financial institutions.
Vivox AI ties the raise to current deployment claims across enterprise customers operating in more than 100 countries, including the UK, Europe, the United States, and Singapore. The release says complex compliance case processing time falls from about six hours to about 30 minutes, false positive screening alerts fall by up to 86%, and straight through processing reaches up to 50% for selected onboarding and due diligence workflows.
AML, KYC, and KYB work is repetitive, document heavy, and costly. Time per case, alert volume, and exception handling drive staffing levels and backlog risk. The goal is to target those exact cost drivers. Less time per case reduces analyst hours. Lower false positive rates reduce review load. Higher clean through processing reduces manual touch rates.
The product is described as separate task agents rather than one general AI layer. That design fits regulated workflows more closely because onboarding, due diligence, screening, and case handling can be controlled, tested, monitored, and audited as separate processes. In practice, compliance teams need faster file handling, cleaner audit trails, and fewer manual reviews that do not add risk insight.
Canada recently updated its Canada anti fraud policy and continues to raise expectations on prevention, detection, and reporting. That pushes more pressure through AML, KYC, and KYB operations while boosting financial crime compliance innovation.
Vivox AI is entering a category where established Canadian and Canada connected firms already cover adjacent parts of the stack. Trulioo identity verification supports global KYC and KYB onboarding. iComply compliance automation covers modular AML, KYC, KYB, and KYT workflows. Nasdaq Verafin financial crime controls serves financial institutions with AML, fraud, and investigation tools. Vivox AI’s stated position is narrower and more execution focused: task specific agents inside case work, screening, and due diligence workflows.
For operators key metrics such as time saved per case, false positive rates, exception rates, audit evidence quality, and post approval error rates will determine whether automation lowers cost or adds a second layer of review.
If compliance automation cuts a six hour case to 30 minutes and reduces false positives by up to 86%, does workflow design replace compliance team size as the main scaling lever?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 3, 2026 | NCFA Fintech Market Insight | Small Business Performance And Payments
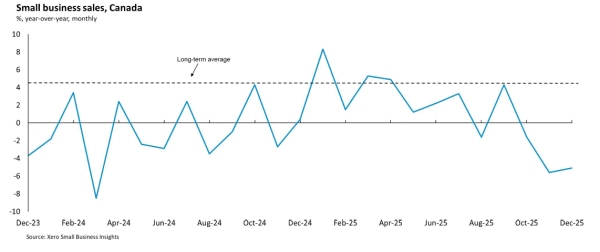
Image: Small Business Sales, Canada (Xero Small Business Insights, Canada Oct Dec 2025)
On February 26 2026, Xero released its Small Business Insights Canada Update for October to December 2025, based on aggregated and anonymized small business accounting data from its small business accounting platform, not survey responses. The dataset reflects real invoicing and payment activity captured within the Xero system. The December quarter closed with a clear revenue reversal while payment discipline strengthened. The numbers provide an operating baseline for fintech lenders, payments firms, and financial institutions serving the small business segment, as we move deeper into 2026.
Quarterly Sales Growth 2025
Q1: +5.0%
Q2: +2.8%
Q3: +2.0%
Q4: −4.1%
Q4 Monthly Breakdown
October: −1.6%
November: −5.6%
December: −5.1%
A nine percentage point swing from Q1 to Q4, with the December quarter decline the largest since September 2020. The Q4 reversal showed how fast small business demand can change. Sales moved from solid growth early in the year to a sharp contraction by December.
That kind of swing compresses reaction time. For lenders and platform providers, continuous revenue monitoring is more important than backward looking ratios. Fintechs that track live invoicing flows and cash inflows gain earlier warning signals. Banks that still rely on periodic reporting will be reactive. The risk is no longer just default, it's also speed.
During periods of weaker revenue, founders focus on cash flow and credit, but they also need to review commercial insurance coverage options as risk exposure increases.
Full Year 2025 Average: +1.4%
Long Term Average: +4.5%
A sustained three percentage point gap versus historical norms. Not a single weak month but a structural softness across the year. When growth slows, small businesses focus on managing timing. They want certainty around receivables, payables, and liquidity buffers. Expansion plans move to the background. This changes product priorities. Tools that shorten receivable cycles, automate reconciliation, and provide flexible liquidity become core operating infrastructure. Working capital solutions that assume growth acceleration may miss the mark. Fintechs that help stabilize cash flow, and not amplify growth, may align better in this cycle.
Late Payment Days
June Quarter: 11.3 days
September Quarter: 9.8 days
December Quarter: 9.7 days
Long Term Average: 11.7 days
Time To Be Paid
June Quarter: 27.7 days
September Quarter: 26.3 days
December Quarter: 26.8 days
Revenue slowed, but businesses tightened receivables management. Payment behaviour improved into year end. Settlement timing held steady despite volatility in topline growth. This means payment behaviour data may now offer stronger forward insight than topline growth alone. If a business collects faster, even during a slowdown, that tells you something about discipline, customer quality, and internal controls. Fintech lenders that weight verified payment performance can price risk more precisely.
Q4 Sales Growth By Province
British Columbia: −8.2%
Alberta: −4.0%
Ontario: −1.7%
Q4 Time To Be Paid
Ontario: 28.4 days
British Columbia: 27.5 days
Alberta: 26.6 days
Regional sales outcomes and liquidity conditions diverged materially. National averages masked local differences. The December quarter showed wide variation across provinces. Some regions contracted far more than others. That gap changes the risk profile of a portfolio. National averages smooth out reality. A lender with concentrated exposure in a weaker province carries different forward risk than one diversified across stronger regions. Regional segmentation should move from a reporting exercise to a pricing and limit setting discipline. Portfolio steering needs to reflect local operating conditions, not national headlines.
Q4 2025 showed a structural split: weaker sales, stronger collections, and widening regional differences. For fintech leaders, the opportunity is not just reacting to the decline. It's in building systems that continuously read revenue direction, payment velocity, and geographic exposure at a granular level. Firms that can master these variables in real time will support small businesses more effectively in lower growth environments.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 3, 2026 | NCFA Fintech Market Activity | Wealthtech And AI Operations

On March 3 2026, Canadian wealthtech based in Calgary OneVest launched its Agentic Wealth Operating System, a new platform built to automate core wealth management workflows across onboarding, account opening, fund movements, fee billing, document handling, and multi step operational tasks.
The launch is a product and workflow infrastructure improvement. OneVest’s own platform pages already position the company around advisor experience, client experience, home office tools, compliance, and workflow automation. The new operating system pushes that model further into direct task execution across the middle and back office. OneVest describes it as 'a unified intelligence layer that proactively connects advisors, operations teams, and clients'. OneVest recently closed $20M Series B to Lead Wealthtech.
OneVest is aiming at the operational layer of wealth management. Wealth firms still lose time and margin in areas such as onboarding, account setup, approvals, data re entry, billing, and document processing. These are repeatable workflows where automation can cut labour time, reduce handoff friction, and improve operating consistency.
The new launch adds an AI native execution layer on their stack which is designed to streamline execution and reduce manual steps, duplicate tasks and improve faster completion of advisor and operations work. If firms can automate account opening, fund movement workflows, billing processes, and document extraction inside the operating system, then labour cost, processing time, and error rates all become addressable.
For operators, the key test is measurable workflow impact. How much onboarding time will be saved, manual touches removed, billing accuracy, exception rates, and the number of workflows that move from staff handled to system executed.
Firms that control workflow execution inside wealth infrastructure can become harder to replace than firms that only improve the interface. If OneVest can move from software layer to operating layer, the product value and switching costs both get stronger.
As wealthtech moves from dashboards to workflow execution, does the next valuation premium go to firms that automate operations instead of firms that only modernize the front end?
Wealthtech is evolving from digital interfaces to operational automation. Client portals and advisor dashboards improved the front end. The next competition layer sits behind the screen in workflow engines, approvals, data flow, and execution control. That is where firms either scale cleanly or absorb more overhead as assets and client counts rise.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 3, 2026 | NCFA Fintech Market Activity | Payments And Market Infrastructure

On March 3 2026, Hanna Zaidi, VP Payments Strategy and COO of Wealthsimple announced on LinkedIn that Wealthsimple just became the first Canadian fintech to earn direct access to Swift, and the second non-bank fintech globally to gain direct access. The Globe and Mail reported that Wealthsimple will be offering cheaper international money transfers than larger Canadian competitors and a spring launch for the new service.
From reviewing WS's website, Wealthsimple wire fees lists CA$15 for outgoing CAD wires (US$15 for outgoing USD wires), while inbound wires will have no fee on Wealthsimple’s side. There's also a per transfer limit of up to CA$1,500,000 or US$1,500,000.
Swift membership rules explain why direct access is hard to secure. Applicants must qualify under Swift’s user categories and Swift's onboarding requires mandatory security controls and a security attestation before a new member can go live. Meaning WS earned a direct network membership milestone, not a reseller arrangement.
Swift's network scale connects 11,500+ institutions across 220+ countries and territories, handles 53 million+ FIN messages each day on average, and routes 75% of payments to destination banks within 10 minutes.
The table below highlights the price gap Wealthsimple is attacking, compared with TD fees and RBC fees for incoming/outgoing wire transfers which are more expensive. Wealthsimple enters the wire market below the published outgoing wire fees at both banks and below the published incoming wire fees in both schedules.
| Comparison | Wealthsimple | TD | RBC |
|---|---|---|---|
| Outgoing international wire | CA$15 CAD wire / US$15 USD wire | $50 | Starting at $45 |
| Incoming wire | $0 (WS's side) | $15 | Starting at $17 over $50 |
| Published transfer limit | Up to CA$1.5M / US$1.5M | Not stated in cited fee schedule | Not stated in cited fee page |
| SWIFT Access | Direct member access as a fintech | Direct bank member access | Direct bank member access |
The strategic value goes beyond a wire product though. In addition to direct Swift access, Wealthsimple has also earned direct participation in Payments Canada, Interac, and the Bank of Canada’s coming real time rail. That gives one non-bank platform direct reach across more of the domestic and global payment stack that sets pricing, speed, and settlement.
For Canada, from a competitive perspective, when a fintech now has direct entry into the same global messaging network used for bank wires and is attaching a lower listed fee to that access, consumers benefit. That puts direct pressure on wire pricing and strengthens Wealthsimple’s position in cross-border money movement services.
When a non-bank fintech gets direct Swift access and lists lower wire fees than major banks, does the competitive edge move to firms that control the rail instead of firms that only package the service?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 2, 2026 | NCFA Fintech Market Activity | Funding Access And Market Structure
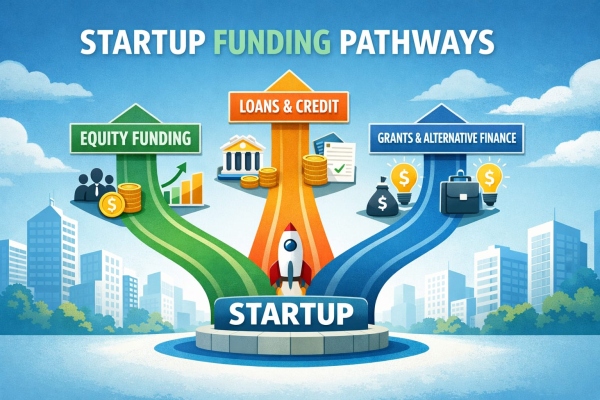
On March 2 2026, FrontFundr and Swoop launched a funding partnership that brings equity, debt, and specialized financing into one coordinated path for Canadian startups.
FrontFundr enters the partnership with more than 69,000 investors, more than $336 million in processed investments, more than 35,000 transactions, and more than 285 successful raises.
Peter-Paul Van Hoeken, Founder & CEO of FrontFundr:
“Raising capital is rarely straightforward, and founders shouldn’t have to navigate fragmented options alone. By partnering with Swoop, we’re giving startups a single, coordinated path to financing, so they can focus on building their business instead of managing complexity.”
Swoop Finance, launched in the UK in 2018, adds a broader financing reach with more than $2.5 billion in completed funding for more than 282,000 global customers. Together, that combines community based equity access with a wider range of debt and structured funding options.
Daire Burke, Head of Swoop North America
“Canadian startups need access to both capital and guidance to grow efficiently. Working together with FrontFundr allows us to combine our expertise in loans, grants, and financing solutions with FrontFundr’s equity crowdfunding platform, creating a seamless funding experience for founders.”
Founders rarely use one funding tool from start to scale. Equity can fund product development and early traction. Loans, lines of credit, grants, asset-backed financing, acquisition finance, and other structured products can support working capital, expansion, and specific transactions. A combined and simplified path can reduce friction at a time when founders still lose time moving between separate funding providers.
For Canada, this points to a more connected funding stack at a time when Canadian venture funding pressure continues to make capital access one of the hardest constraints on startup growth. The stronger platforms offer more than one product, and help founders match the right capital to the right stage with less delay and less administrative drag.
For founders and investors, access to capital is becoming a workflow issue as much as a supply issue. Platforms that combine investor reach, financing options, and execution support can become more valuable than standalone marketplaces.
As startup funding gets harder to piece together, does long term value move to platforms that control more of the capital journey, not just one part of it?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016