




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Nov 5, 2026
A crypto price feed is fresh when it delivers the latest relevant observations for the market it claims to show. A flashing number or a “live” badge cannot establish that. Check what the price represents, when the underlying event occurred, and whether newer events are reaching the display. An unchanged quote can be correct in a quiet market; an animated dashboard can still be behind. You can investigate these differences using visible records, although locating the precise fault may require access to the provider's systems.
Several events happen between a trade and your screen. The exchange records the trade, a data service receives it, an application processes the update, and your browser displays it. Each stage can have a timestamp. A page refreshed at 14:00 may still be displaying a trade from 13:55. The refresh time describes the page, while the trade time describes the observation.
Start with the definition beside the number. A last-traded price is the price of a completed transaction. A best bid or ask describes an available order at a moment. An index combines selected observations according to a method. A derivatives mark serves the contract's valuation rules. These numbers may update differently even when the systems are functioning normally.
When comparing cryptocurrency prices live, align the asset, quote currency, venue or aggregation method, and market type before interpreting a difference. Two tickers with the same asset name may refer to different pairs. A dollar-denominated aggregate and a stablecoin pair are also distinct observations. A mismatch is a reason to investigate the definition before diagnosing a delay.
Look for an event timestamp and its timezone. If the page provides only “last updated,” read its explanation rather than assuming this means the latest exchange trade. The label might refer to a scheduled database update. Where the meaning is undisclosed, record freshness as uncertain; the absence of an explanation does not establish either a fault or a current feed.
Your own clock can complicate comparisons. A device with an incorrect time setting can make a valid event look delayed or even appear to come from the future. Before calculating apparent latency, check automatic time synchronization and timezone settings. A screenshot should preserve the displayed timezone so another reader can understand what the observation means.
An inactive last-trade price is often unsurprising. If nobody has traded the pair recently, the latest completed trade remains the same even while orders change. Check whether the market is open and whether the feed reports trades, orders, or a scheduled reference value. Looking only for a moving last price confuses activity with delivery.
Connection indicators need interpretation too. Coinbase Exchange's WebSocket documentation describes heartbeat messages that include a sequence number and last-trade identifier. These fields can help check continuity. Other services may expose only a connection signal. “Connected” therefore has different evidential value depending on the documented message content; it cannot be treated as a universal freshness certificate.
Here is a compact comparison for a last-trade display:
| What you observe | Possible explanation | Useful next check |
|---|---|---|
| Price unchanged, no newer trades on the same venue | Quiet instrument | Market status and latest trade time |
| Price unchanged, newer trades in the venue's own record | Delayed display or subscription | Event identifiers and app update time |
| Price differs across two venues | Separate order books | Compare matched pairs and timestamps |
| Many old events arrive together | Recovery or buffered delivery | Event time versus arrival time |
These are hypotheses, not diagnoses. A public webpage rarely reveals which stage failed. If a provider offers a status notice, check whether it covers the affected product and time. A general “operational” status can coexist with an isolated problem. Conversely, a notice about one network or service need not describe every market on the platform.
Try a controlled comparison rather than repeatedly refreshing every tab. Keep one instrument visible, note its event time, and compare it with the original venue's corresponding record when accessible. Reopening a page may restore a subscription, but it can also erase the evidence of a recurring interruption. Preserve the observation first if you intend to report the issue.
Check the page's own controls as well. A chart may be paused, displaying a historical cursor, or showing a completed candle while a quote panel updates normally. Resolve those states before blaming the source. If the displayed value changes after returning to the latest candle, the problem was the selected view, rather than necessarily a stale incoming feed. This is a useful first check because it requires no inference about systems you cannot inspect.
Imagine a hypothetical feed that stops reaching a browser at 12:00. The source continues recording trades at 12:01 and 12:02. At 12:03, the browser receives both events close together. The screen may jump through several prices in a second even though the market moved over three minutes. Arrival time compresses the visible story.
That distinction matters for rankings as well as charts. A refreshed biggest crypto gains list shows percentage changes over its stated window. A sudden rearrangement may combine actual market changes with delayed delivery or recalculation. To investigate one row, inspect its underlying price history and update information. The ranking movement alone cannot tell you how quickly the trading occurred.
Missing messages create a related problem. Coinbase's Exchange documentation warns that sequence gaps and out-of-order messages can occur. For a developer, recovery may require the channel's documented synchronization procedure. For a reader, the implication is simpler: a connection that resumes is not proof that the application reconstructed every missed event correctly.
Avoid inferring a tradable opportunity from an old quote. An order placed after the connection recovers is subject to the current market, available liquidity, and order instructions. A stale screen does not reserve the earlier price. Even a market order submitted from a fresh interface can execute at several prices when available depth is limited.
Displayed precision can disguise this uncertainty. Six decimal places may look authoritative, but they tell you how the value is formatted, not how recently it was observed. Likewise, a page that changes color on every update can appear more active than one that refreshes quietly. Freshness depends on the data path and relevant event, not presentation effects.
Use the same sequence each time an important decision depends on a feed:
Video adds another clock. A livestream can include capture, encoding, distribution, and playback delays, while the presenter may display a chart with its own update interval. In crypto market analysis, check the chart's observation time before comparing the host's explanation with your quote page. A clear account of an earlier move remains useful without being a current price reference.
A useful incident report contains the instrument, source, event time, time you observed it, timezone, and a description of the mismatch. Add a screenshot with the relevant labels visible. Exclude account identifiers, access tokens, balances unrelated to the issue, and private browsing details. A reproducible description helps support investigate without turning a public complaint into an account-security risk.
There is no universal number of seconds that makes every crypto feed safe or unsafe. A daily research summary and an order-routing system have different needs. Even a fast feed cannot remove execution risk, source errors, or market volatility. Decide what information your task requires, then assess whether the source actually supplies it.
Freshness is a relationship between an event, its delivery, and your use of the observation. Read the price definition, identify the clock, and compare like with like. When a feed reconnects, check continuity before trusting the apparent jump. If those details are unavailable, uncertainty is the correct finding; extra decimal places cannot repair it.
Yes. It preserves an observation or extraction time rather than a continuing connection. Label the export with its source, time, and relevant window. Reopening the file later does not refresh its contents unless a documented data connection actually runs.
Keep both the original observation and the dated correction when the change affects your analysis. Recalculate dependent results and explain the revision. Replacing one number silently can leave earlier charts or conclusions inconsistent with the corrected data.
No. They may share a data vendor, venue, or cached source. Agreement is more informative when the underlying sources and methods are known. If both reuse the same feed, their matching numbers may reproduce the same delay or error.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
November 5, 2026 | Market Activity | Cross Border Payments And FX, Payments Infrastructure And Money Movement, Regulation And Policy
On November 4, 2026, Whish Money announced its first Canadian operating location in Montreal, starting with money transfers between Canada and Lebanon. The branch had already been reported open in late October. Whish says more Canadian financial services are planned and enters Canada with an established international payments business. The company reports more than 2.5 million app users, operations across 160+ countries, more than $40 billion in historical gross payment value and more than one million cards issued. Jad Koussa CEO called Montreal “a defining step in Whish Money’s global expansion.”
Whish already has more than 1,000 locations in Lebanon, including 40 main branches, plus international transfer connections through Ria, Mastercard, TerraPay, Visa, Taptap Send and Sendwave. That gives the company established distribution and payout reach on the Lebanon side while Montreal adds direct access to Canadian senders.
The confirmed Canadian service today is remittance, with Canadian bank accounts being connected to Whish for wallet funding and transfers. Whish’s Canada and Lebanon transfer FAQ says customers can send and receive money directly between Whish branches in the two countries.
Whish already offers wallets, cards, merchant payments, payment links and other services in markets where those products are supported. Canada begins with one corridor giving Whish a practical way to test demand, pricing and repeat use before spending more to add products or destinations.
Whish’s international transfer fee schedule says charges to bank accounts and wallets vary by partner and corridor. It hasn't published a Canada specific exchange rate or complete transfer fee schedule. Customers will compare the final amount received, transfer cost, payout choice and delivery speed against providers they already use.
Montreal gives Whish direct access to one of Canada’s largest Arab communities and strong ties to Lebanon. Statistics Canada counted 290,070 Arabs in Montréal in 2021, equal to 36.5% of Canada’s Arab population. Among Arab Canadians born in Lebanon, 41% lived in Quebec.
Money sent from abroad also plays a large role in Lebanon’s economy. World Bank data show remittances reached 33.3% of Lebanon’s GDP in 2023, the latest year reported for that series. For many families, these transfers support regular household spending rather than one time purchases.
Whish can use its existing branches and payout relationships to make delivery easier at the receiving end, while its Montreal location gives customers a physical place to send, receive and ask for help. Trust, price and speed will all matter in winning repeat business.
RemitBee Expands Payments With Adyen and TerraPay gives a useful Canadian comparison. Local providers are extending international reach through outside processing and payout networks. Whish enters with an established Lebanon network and is now building the Canadian customer relationship directly.
Whish’s global expansion and compliance strategy says the company has secured Canadian Money Services Business registration and is working toward regulatory requirements in the U.S., UK and EU. Its wider international business already includes physical locations, an app, cards, wallets, merchant services and payment partners.
A September extract of FINTRAC registry data identifies Whish Money Canada, Inc. as an active money services business under registration number C100000616, first registered in June 2025 for activities including money remittance, currency exchange and payment services. The November launch announcement uses Whish Money Services Financiers for the Canadian operation. NCFA could not confirm through a primary corporate record that the two names refer to the same legal entity, so we haven't treated them as interchangeable. FINTRAC registration is not a banking licence or regulatory endorsement.
Global remittance brands already compete hard on price, speed and convenience, while Canadian providers keep improving payout options and delivery times. If enough Canada Lebanon customers use the service again, Montreal gives the company a stronger case for adding more corridors and bringing more of its wider payments products to Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 5, 2026
A comparison of Canadian review-removal services, pricing and practical fit for small businesses.
A single suspicious review can cause real concern for a small business. For a restaurant, clinic, contractor or local retailer, online feedback is often one of the first things a prospective customer reads. Yet a negative review is not automatically a policy violation, and a third-party agency cannot simply delete it. The useful question is whether a review breaks Google’s rules and what support a business needs to present its case.
For Canadian entrepreneurs evaluating paid assistance, ReviewsBoost and ReviewRemoval offer per-review services, while Reputation.ca provides a broader, ongoing reputation-management approach. These models have different costs and serve different needs.
ReviewsBoost is aimed at Canadian businesses seeking assistance with potentially policy-violating Google reviews. Its service model emphasizes a review assessment, managed reporting support and updates on progress. For owners facing an isolated questionable review, its simpler per-review pricing may be appealing.
Pricing: CAD $45 upfront per review, plus CAD $95 upon successful removal, for a total of CAD $140 per removed review before applicable taxes.
Best fit: cost-conscious small businesses seeking specialist help with a specific review and a clear per-review fee structure.
ReviewRemoval serves Canadian businesses seeking managed help with reviews that may breach Google’s policies. Its website describes reviewing the circumstances, preparing the case, handling reporting follow-through and explaining any steps that must be completed through the business owner’s own Google account.
Pricing: CAD $50 upfront per review, plus CAD $125 upon successful removal, for a total of CAD $175 per removed review before applicable taxes.
Best fit: business owners looking for a structured case assessment and ongoing support throughout the review-removal process.
Reputation.ca offers broader reputation services, including review monitoring, customer feedback programs and efforts to flag or challenge reviews that may violate platform policies. This can suit organizations looking for ongoing support rather than help with one disputed review.
Its publicly listed Essential Reviews Management package is CAD $499 per month with a six-month minimum, or at least CAD $2,994 over that term before applicable taxes. Its pricing page also lists reviews-management offerings in a CAD $299 to $999 monthly range. These are ongoing management packages, not a per-review Google deletion fee, so they are not directly comparable to the one-off prices above.
Best fit: organizations seeking ongoing review monitoring and broader reputation management. Main drawback: a six-month package can be costly for a small business seeking help with just one or two reviews.
| Comparison | ReviewsBoost | ReviewRemoval |
| Upfront per review | CAD $45 | CAD $50 |
| Success fee | CAD $95 | CAD $125 |
| Total if removed | CAD $140 | CAD $175 |
| Primary appeal | Lower total fee | More case-focused positioning |
Both specialist services use an upfront payment and a separate fee payable upon successful removal. For businesses comparing providers, the key differences are total cost and the level of case management offered.
For Canadian small businesses seeking professional help with disputed Google reviews, the right provider depends on the number of reviews involved, the budget and the amount of support needed.
ReviewsBoost offers the lowest listed per-review price in this comparison at CAD $140 upon successful removal. ReviewRemoval provides another targeted option at CAD $175. Reputation.ca offers a broader monthly service, but its longer commitment and higher overall cost may make it a less practical choice for businesses focused on individual reviews.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 4, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy, Capital Markets Infrastructure And Funding
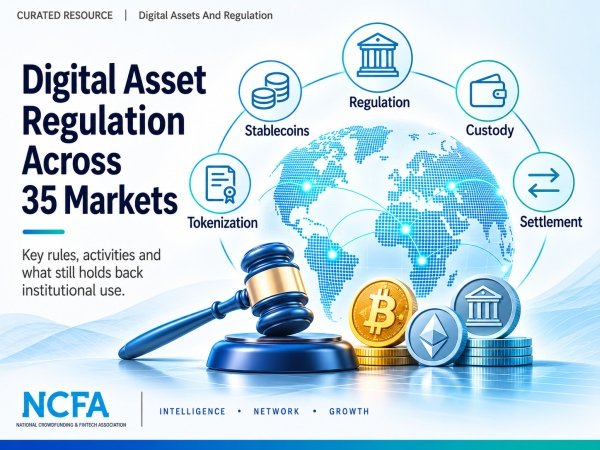
On October 28, 2026, the World Economic Forum and Boston Consulting Group published Regulation of Digital Assets in a Shifting Global Landscape, based on regulatory developments across 35 jurisdictions and more than 25 digital asset activities. The research includes interviews with 50 public and private sector experts, workshops and input from more than 100 participants. Digital assets can be legal and regulated while still being difficult for banks, asset managers and other institutions to use at scale.
More than 70% of the jurisdictions studied regulate the activity being performed rather than relying only on the form of the asset. Trading venues, custodians and payment providers are supervised in more than 75% of the sample. Progress still varies widely within individual countries. A market can have clear rules for tokenized securities while its stablecoin, custody or settlement rules are still incomplete. For a company deciding where to operate, the rules for its actual business matter far more than a country's overall reputation for digital assets.
The 38 page resource compares rules for token issuance, exchanges, wallets, custody, payments, lending, staking and the infrastructure behind digital assets. It also looks at whether institutions can legally own the assets, protect clients, settle transactions, use digital money and meet capital requirements. The activity matrix shows where each part of the market is regulated, partly regulated, unregulated or prohibited.
Cryptoassets account for roughly $3 trillion in market value, stablecoins about $300 billion in circulation and tokenized real world assets about $30 billion. One scenario cited in the research puts tokenized real world assets at approximately $88 trillion by 2035, equal to around 16% of global investable assets. BlackRock's BUIDL fund had reached about $2.6 billion by July 2026, while Euroclear and Banque de France are working on moving a €310 billion commercial paper market onto distributed ledger infrastructure.
Tokenization is already moving into financial infrastructure because issuing the asset is only the beginning. Ownership records, custody, settlement, collateral and servicing all have to work after that. Faster settlement can cut counterparty exposure but may require more cash at the time of settlement. Easier collateral movement doesn't help much if institutions cannot price the asset, pledge it or enforce their claim.
Five barriers can stop institutional adoption even after regulators permit the activity. Leaving one unresolved can keep a legal market small.
Digital assets won't make every middleman disappear, but they can make some existing fees harder to defend. Faster settlement and shared records mean less reconciliation, fewer manual steps and lower servicing costs. Businesses that depend on slow transactions, fragmented records or closed distribution may feel that pressure first. Liquidity, trusted custody, access to customers, risk capacity and market access are harder to replace.
For example, putting a fund onchain doesn't solve pricing, investor records, compliance, redemption, distribution or settlement. Tokenized fund operations after issuance still need all of those functions to work before investors get much benefit from the technology.
There is also money to be made connecting systems that don't yet work well together. Digital money needs places where it can be spent or settled. Tokenized assets need custody and financing. Banks and asset managers need reliable access to both. A company that solves one of those connections may have a better business than one issuing another token or building another closed network.
For founders and investors, a company can have excellent tokenization software and still struggle if customers cannot settle, finance or distribute the asset efficiently. Firms with control over liquidity, distribution, custody or an important connection between systems may have much stronger economics.
Not every part of a country's digital asset market develops at the same speed. Switzerland has established legal treatment for tokenized securities and distributed ledger market infrastructure while still developing its stablecoin rules. WEF and BCG state that “The relevant comparison is therefore by activity, not by jurisdiction overall.” A company choosing where to launch needs to examine the rules for its product and business model rather than rely on a broad label such as crypto friendly.
A country with heavy retail trading may need stronger platform supervision and customer protection first. Heavy use of foreign stablecoins can make reserves, redemption and currency risk more urgent. A financial centre trying to build tokenized capital markets may need clear custody, settlement and collateral rules sooner. Copying another country's approach can leave the biggest local problem untouched.
Cross border business doesn't require every country to have identical rules. Institutions need to trust the legal rights, customer protections and settlement outcomes in the other market. Countries can recognize each other's rules where those protections are comparable and avoid repeating the same work. That becomes much harder when supervision, enforcement, data or infrastructure cannot be trusted across borders.
Even the same rule can produce different results. Two firms may follow the same financial crime requirement but use different transaction histories, risk thresholds or blockchain analytics. One may accept a wallet that another rejects. Similar differences can affect collateral values, transaction data and controls. When that happens often enough, legitimate business gets slower and liquidity can break into smaller pools.
Canada now has several parts on the go at once. Proposed federal stablecoin rules cover reserves, redemption, custody and Bank of Canada supervision, while Canada's six largest banks are exploring Canadian dollar tokenized deposits. Tokenization is also expanding across funds, securities and settlement. All of these products eventually run into many of the same payment, custody, capital and infrastructure questions.
Canada's stablecoin rules won't create an institutional market on their own. Banks still need practical ways to hold and settle the assets. Custody has to be clear. Collateral has to work inside financing markets. Financial crime controls have to work across different networks. A stablecoin can meet its reserve requirements and still see limited institutional use if the rest of the transaction is difficult or expensive.
Tokenized securities and deposits face the same reality. Faster settlement can force treasury teams to keep more cash available during the day. Tokenized collateral only helps when lenders can recognize it, value it and enforce the claim. Systems can connect technically while ownership, privacy or compliance problems remain unresolved. A digital asset becomes commercially useful when the whole transaction works, not simply when one part has moved onchain.
The 35 country comparison is useful because it covers more than 25 activities and nine areas of regulation, making it easier to see exactly where a market is ready and where something is still missing. It also connects regulation to funding, collateral, settlement, custody, payments and business economics rather than treating compliance as a separate exercise.
The regulatory matrix mainly reflects conditions as of February 2026, and rules are changing quickly.
Digital Assets Regulation Insights from Jurisdictional Approaches (WEF comparison of nine jurisdictions published in 2024)
Stablecoin Regulations In Canada (current NCFA reference for Canada's federal stablecoin rules and implementation)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 4, 2026 | NCFA Story Intelligence | Sustainable Finance And ESG, Regulation And Policy, Competition And Market Structure
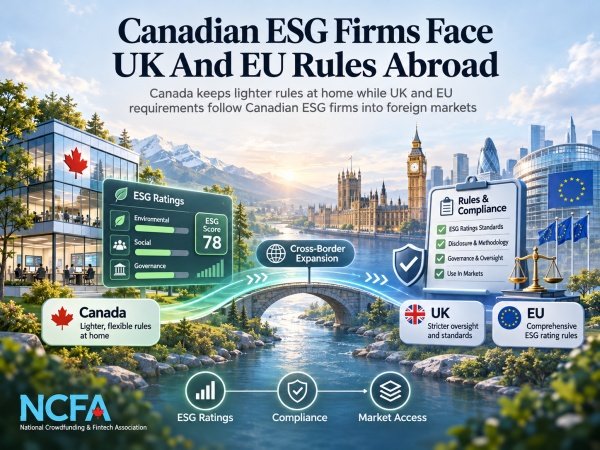
ESG ratings promised investors a shortcut.
Instead of digging through climate data, labour records, governance practices and supply chains themselves, they could buy a score and put it to work.
Then the scores started disagreeing.
The same company could look strong through one provider and much weaker through another. Nobody had to be cheating or doing bad work. One firm might care more about carbon exposure. Another might put more weight on labour practices, board governance or supply chains. Even when they looked at the same issue, they weren't always using the same data.
Investors were left with a problem. They had bought a shortcut and now had to check the shortcut.
In Britain, thousands of financial firms eventually built their own checks around ratings they were already paying for. The FCA estimates that extra work now costs about £495 million every year.
Regulators eventually made a choice that wasn't obvious at the start. They didn't force every provider to use the same formula. They started regulating the firms producing the ratings.
The EU rules have applied since July 2, 2026. On November 3, 2026, the UK Financial Conduct Authority published its final ESG ratings rules. From June 29, 2028, firms caught by the UK regime need FCA authorisation.
Canada hasn't followed them.
That gives a Canadian startup more breathing room at home.
Then it lands a customer in London, Paris or Frankfurt.
The Canadian rules haven't changed. The business suddenly has.
One provider knocks a company down for carbon exposure. The investor sees the score fall and assumes climate risk is driving the result. But that number also reflects choices about which indicators were used, which data was trusted and how the provider turned those inputs into a score.
Another barely moves on carbon but cuts the same company for governance or labour practices. The company itself hasn't changed between the two ratings. What changed is the lens used to judge it. Same company. Same ESG label. Different story.
Providers sign up, publish more detail and tighten their controls. They still get to build their own methods and scores. That keeps room for different models to compete, but it also leaves customers comparing very different ways of measuring the same company.
Customers keep doing their own checks anyway. Banks, asset managers and other users still have to decide whether the provider's data, methodology and controls are strong enough for their own decisions. More disclosure helps, but the doubt doesn't go away.
A rating only saves time if the buyer trusts the data, methodology and controls used to produce it. By this point, many firms aren't simply reading the score. They're reviewing the provider, checking the method and sometimes changing their own systems before the rating can be used.
By 2025, thousands of firms have built their own second opinion inside the company. Some are spending months onboarding providers and assigning staff just to close information gaps or resolve concerns before a rating can be trusted. The shortcut has created another job.
Before, a provider could follow the voluntary code and convince customers that its controls were good enough. The customer could accept that explanation, ask for more or walk away. The regulator wasn't deciding whether the provider could stay in the market.
Under FCA rules, that choice disappears. Firms in scope have to meet requirements around governance, conflicts, systems, data and disclosure, and they need authorisation to keep serving the market. If the firm is caught by the regime, meeting the standard becomes part of staying in business.
A smaller Canadian provider can still reach European customers without waiting for Canada to create its own ratings licence. Recognition can give qualifying foreign firms a way in when equivalence isn't available, so the market isn't closed to an independent Canadian provider.
But it still has to meet European requirements. Depending on the route, that can mean a legal representative, added documentation and direct accountability to ESMA. The company can stay Canadian, but its European business can't simply run on Canadian rules. Getting into the market is possible. Getting in on Canadian terms isn't.
A Canadian startup can build an ESG scoring product, test it and sell it at home without first getting a dedicated ratings licence. That leaves more of its early budget for product, data, hiring and customers instead of a new authorisation process.
Then it signs a foreign customer. New legal work, documentation, controls and regulatory relationships can arrive with the contract even though the product itself is unchanged. The product hasn't changed. The cost of selling it may have.
The Canada EU digital trade deal can make contracts, permitted data transfers and online delivery easier for smaller Canadian companies. That can remove friction from how a digital service is sold and delivered across the Atlantic.
If the product is an ESG rating, ESMA's rules still apply. A smoother digital sale doesn't replace recognition, endorsement or any other requirement that applies to the provider itself. The sale may get easier. The regulatory work doesn't disappear.
Providers still get to disagree and build different models. One can give climate more weight while another puts more emphasis on governance, and the FCA doesn't try to choose the winner.
What changes is how much of the work behind the score has to stand up to scrutiny. Providers have to explain more about the data, methods, conflicts and controls that produced the result. The rating can stay subjective. The process can't stay hidden.
UK applications begin in 2027. Firms expecting at least £500,000 in ESG ratings revenue over the following 12 months apply first. Smaller providers follow. For a Canadian exporter, the size and timing of the sales pipeline can therefore affect when the FCA application work starts.
A firm serving both the UK and EU can reuse some people, controls and documentation. That should keep the second market from starting entirely from zero, but the two regimes remain separate and each still has its own entry requirements. It can reuse the work. It can't reuse the permission.
Canada gets a real benefit from staying lighter.
A young ratings or analytics company can spend more of its first dollars on product, hiring and customers instead of building a licence around a market that may still be small.
That works well while Canada is the market.
Then the company wants to scale.
A UK customer can bring FCA requirements into the sales process. A European customer can bring ESMA. The Canadian company starts hiring compliance staff, changing contracts, documenting methods and adding controls that Canada never asked it to build.
Copying the UK or EU isn't an obvious answer either.
A Canadian licence would cost money. Plenty of firms may never need one. Large global providers can spread that cost across thousands of customers. A startup can't.
But staying different isn't automatically free.
If every Canadian firm with global ambitions has to build around foreign rules anyway, Canada's lighter model starts saving less than it first appears.
Canada hasn't crossed that line by law. Some Canadian firms may cross it much sooner.
At what point does regulatory divergence stop saving Canadian firms money and start making international expansion more complicated?
Ottawa hasn't answered that question. Canadian firms trying to sell abroad may answer it first.
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 4, 2026
Image: Unsplash/Luis Fallas
A winning bet is great, but getting your money into the account shouldn't be the hard part. Canadian payment technology is getting faster and smarter, with some interesting developments already underway. The question is whether sportsbooks can put those improvements to work where their customers will actually notice them.
Online sports betting is a pretty slick operation these days. You can watch a hockey game, check the odds on your phone and place a bet before the next face-off. But there's a fair amount of financial technology doing the work behind that simple transaction. Your money has to reach the sportsbook, your account needs to be verified, and everything has to happen quickly enough to keep up with the game.
A sportsbook account is effectively a digital wallet. You deposit money, the balance appears in your account, and you can use it to place bets. The process looks simple because the payment technology handles most of the work without asking you to get involved.
There's plenty of money moving through these systems. Ontario recorded CA$11.4 billion in sports and other betting wagers during the 2024–25 financial year. That includes esports and novelty betting, but it gives you an idea of the workload behind Canada's regulated betting industry.
Welcome bonuses add another job for the software. A sportsbook needs to recognise an eligible deposit, apply the correct promotion and keep track of the conditions attached to the bonus. Sportsbook Review provides information about information about the Stake Bonus Code, including Stake's first-deposit match, promotional code and wagering requirements.
It's a good illustration of how much work happens behind the account balance you see on your screen. The customer makes the deposit, and the software handles the calculation.
Moving money between a bank and a sportsbook takes more than a working internet connection. Payment processors have to authorise transactions and keep accurate records, even when thousands of customers are using the service.
Canadian financial businesses are spending money on the technology that makes this possible. Peoples Group and Fiserv are modernising payment infrastructure, improving the systems that financial services use to process transactions.
There's also a regulatory side to the business. Canada's Retail Payment Activities Act brought new requirements into effect on September 8, 2025.
Payment service providers covered by the legislation must manage operational risks and protect customer funds where applicable. Those obligations concern the businesses handling payments, rather than every sportsbook directly.
A betting operator needs dependable payment connections because customers expect their deposits to arrive and their withdrawals to be processed correctly.
Waiting for a bank transfer to clear is nobody's favourite pastime, particularly when you're trying to fund an account before a match starts.
Canadians are interested in faster alternatives. Payments Canada found that 52% of consumers considered real-time payments appealing, and 34% said they would likely switch to them when available.
Canada's Real-Time Rail is intended to make account-to-account transfers possible around the clock. Its planned introduction in the fourth quarter of 2026 would give participating financial institutions another way to move money electronically.
The benefit for sports betting is easy to understand. Faster payment confirmation could allow deposits to reach betting accounts sooner, assuming the operator supports the relevant payment method.
Withdrawals are slightly different. A sportsbook may need to verify an account or complete other checks before releasing the money. Real-time payment technology can speed up the transfer once those checks are finished, but it cannot do away with the checks themselves.
Nobody wants to miss the opening minutes of a match because their deposit is still making its way through the banking system.
Financial technology is also getting better at checking information. Secure connections between systems allow businesses to verify details without asking customers to enter the same information repeatedly.
Open banking is taking this further. Decision intelligence uses connected financial information to help businesses assess transactions and make automated decisions.
A sportsbook can apply similar technology to account verification. Payment details that don't match the registered customer, for example, can be flagged for closer inspection.
That leaves staff to investigate transactions that genuinely need attention, rather than manually checking every deposit that comes through the system.
Sportsbooks have become very good at making complicated transactions look simple. You open an account, deposit money and get on with watching the game, without having to understand what the payment processor is doing.
That convenience depends on reliable financial systems. Faster transfers can reduce waiting times, and better account verification helps operators handle transactions accurately.
There's still plenty of room for improvement, particularly as Canadian payment technology develops. The next useful innovation might have nothing to do with the odds on your screen. It could simply mean your money gets where it needs to go without keeping you waiting.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 3, 2026
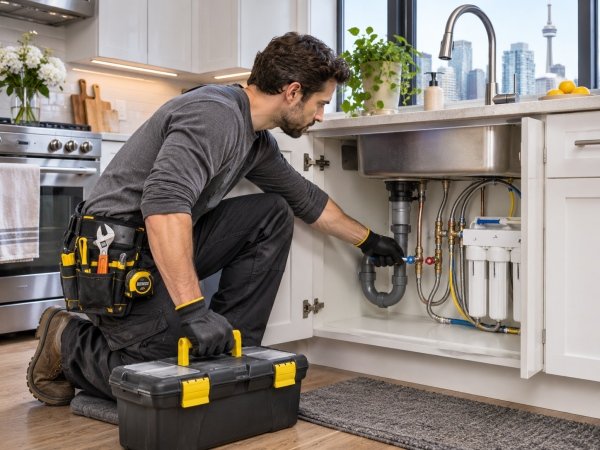
Plumbing problems tend to appear at the worst possible time, whether that is a pipe that starts leaking on a holiday weekend or a basement floor drain that fills with wastewater in the middle of the night. Knowing which problems call for an emergency plumber Toronto homeowners can reach at any hour, and which ones can wait for a regular appointment, helps a household act quickly and limit water damage in the first few minutes.
Some plumbing problems get worse with every minute. A burst pipe or a leak that sprays or pours water across the floor is the clearest example, since water travels under flooring, into walls, and down to lower levels quickly. Sewage rising through a basement floor drain, a toilet, or a tub is equally urgent, because it signals a blocked or backed-up sewer line and brings health risks into the home.
Other urgent cases include a toilet that keeps overflowing after the water supply is turned off, a water heater leaking from the tank itself, a sump pump that has stopped working while water rises in the pit, and a sudden loss of water to the whole house. In each of these cases, the help of an emergency plumber Toronto residents trust is worth arranging right away rather than the next business day.
Not every plumbing issue is a plumbing emergency. A single slow drain, a dripping faucet, or a toilet that runs after flushing is inconvenient, but these problems seldom cause damage overnight. If one fixture is clogged while the rest of the house drains normally, it is usually safe to stop using that fixture and book a regular visit.
The simplest way to decide is to ask two questions: is water escaping where it should not be, and does wastewater have nowhere to go? If either answer is yes, the situation should be treated as urgent, while a problem that is contained and stable can generally wait for a scheduled appointment.
The most useful step in any plumbing emergency is stopping the flow of water. In most homes, the main shut-off valve sits in the basement or utility room, close to where the water line enters the house and often next to the water meter. Turning the handle clockwise closes it and stops water from reaching every fixture.
Many fixtures also have their own valves. A shut-off valve under a sink or behind a toilet can isolate a single leak without cutting water to the whole house, and the cold-water valve above a water heater stops the tank from refilling. Locating these valves before anything goes wrong, and checking that they turn freely, saves valuable time later. A simple tag on the main valve helps every member of the household find it quickly.
A sewer backup calls for a different response from a clean-water leak. The first priority is to stop all water use in the house, since every flushed toilet, running tap, or load of laundry adds to the volume that has nowhere to go. Everyone in the home should hold off on using water until the plumber has cleared the line.
Sewage can carry harmful bacteria, so it is best not to touch it. Children and pets should be kept away from the affected area. Belongings can be moved to higher ground if it is safe to do so. Pouring chemical drain cleaners into a backed-up line is best avoided, as they rarely clear a main-line blockage and can make the work more hazardous for the technician.
Standing water near outlets, extension cords, or appliances is a serious hazard. If the electrical panel can be reached without walking through water, switching off power to the affected area reduces the risk. If it cannot be reached safely, it is better to stay out of the flooded space and wait for help.
Once the source of water is under control, removing what can be saved, opening windows for airflow, and taking photographs of the damage are sensible next steps. Wet drywall, carpet, and insulation can develop mould within a few days, so drying the area promptly matters as much as the repair itself.
Typing “emergency plumber Toronto” into a phone late at night is usually the first step. The call that follows goes more smoothly when the caller explains what happened, where the water is coming from, whether it is clean water or sewage, and whether the main valve has been closed. Mentioning the age of the house, the location of the problem, and any access issues, such as a locked side gate or a finished basement ceiling, helps the plumber arrive prepared.
Keeping the phone close after the call is also wise, so the plumber can share an arrival update or ask a quick question about access. If the situation changes while the household waits, for example water spreading into another room or a second fixture backing up, a follow-up call keeps the plumber informed.
The first task for the emergency plumber Toronto homeowners call in is to confirm that the source of water is stopped and the area is safe to work in. From there, the plumber assesses the cause, which may be a failed fitting, a split pipe, a blocked sewer line, or a worn-out appliance.
Some problems can be repaired on the spot, while others need a temporary fix to make the home usable until parts or additional work can be arranged. When a sewer line keeps backing up, a camera inspection may be recommended to find the cause. A clear explanation of what failed and what comes next allows the household to plan with confidence.
Many emergencies are preceded by warning signs that are easy to overlook. Drains that slow down repeatedly, gurgling sounds from fixtures, damp patches on ceilings, and a water bill that rises without explanation are all worth investigating before they turn into a crisis.
A simple meter test can reveal hidden water leaks. Turning off all the water in the home, recording the reading on the water meter, and checking it again after at least twenty minutes is all it takes. If the reading has changed, water is escaping somewhere. Testing the sump pump before spring, keeping grease out of kitchen drains, and protecting exposed pipes in unheated areas all reduce the chance of needing an emergency plumber Toronto families depend on at an inconvenient hour.
Drain Express provides emergency plumbing services across the Greater Toronto Area twenty-four hours a day, seven days a week, including holidays. Its highly qualified plumbers serve both residential and commercial clients, the work comes with a warranty, and the team has completed more than 5,000 jobs.
A little preparation makes every plumbing emergency easier to manage. Knowing where the shut-off valves are, recognizing which problems cannot wait, and having the number of an emergency plumber Toronto households can count on all help turn a stressful night into a problem that is contained, repaired, and behind them.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016