




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Funding | July 16, 2025
Image courtesy of Quandri
Vancouver and Boston-based insurtech Quandri has raised US$12 million to accelerate the rollout of its AI-powered Renewal Intelligence Platform across the Canadian and U.S. insurance markets. The round was led by Framework Venture Partners, with follow-on investments from FUSE and Defined Capital, and strategic backing from Intact Ventures. To date Quandri has raised over US$20 million since founding in 2021.
The new capital will fuel a hiring push, deepen AI engineering capacity, and support the opening of a new U.S. office in Boston alongside the expansion of its Vancouver headquarters.
"We’ve had strong conviction in our vision from day one, but having new investors like Framework and Intact supporting our journey adds real momentum," said Jackson Fregeau, co-founder and CEO. "Their support affirms the value we’re delivering to brokerages and agencies, and gives us the insight and fuel we need to keep pushing the industry forward."
In a recent interview with the National Crowdfunding and Fintech Association (NCFA), Quandri co-founder and CEO Jackson Fregeau shared additional insights on the company’s platform, market traction, and future plans.
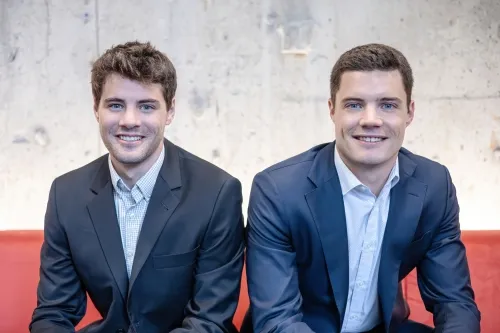
Image: Quandri Co-founders, Jackson Fregeau (CEO) and Jamieson Fregeau (President)
Quandri’s Renewal Intelligence Platform is designed specifically to automate renewal servicing workflows for insurance brokerages and agencies. It stands out in a crowded insurtech space due to its deep contextual understanding of insurance data, its focused product design, and its high degree of configurability.
Jackson Fregeau, co-founder and CEO:
"What differentiates us as a business is threefold.
First, deep intelligence. We ingest millions of insurance policies every month, and our AI has a deep understanding of underwriting guidelines across all regulatory environments in North America. This means we have a deep insurance context and can apply this to the automation of a process — taking it all the way to communication with a client, thanks to the trust our customers have in us.
Second, focus. We chose a clear focus area and spent our time driving as much value as possible. With renewals as an example, we aren’t just automating the process — we’re driving additional revenue through cross-selling and upselling, while also increasing retention rates.
Third, a high degree of configurability. Our AI can analyze hundreds of variables on a single renewal to surface insights and deliver action. Our customers can configure all of this if they want, to build a highly personalized and relevant experience for their clients."
Brokerages using Quandri have reported major productivity and revenue improvements.
"We’ve seen customers save over 6,000 hours a year by automating their renewal review process — work that previously required full teams to manually review documents," said Fregeau. "For example, one of our customers repurposed over 5% of their workforce — 10 of 200 employees — shifting experienced team members into higher-impact roles that support growth and improve the client experience.
"In another case, one brokerage reported a 350% return on investment in just a few months — proof that this isn’t just about saving time. It’s about unlocking a more resilient, scalable way to run a brokerage. And the benefits go beyond operational efficiency; one brokerage reported a 2% increase in client retention, driven by the ability to proactively reach out to customers with consistent, value-based renewal conversations."
Quandri has been operating in the U.S. for the past two years, but has seen significant acceleration over the last 12 months.
"The biggest learning has been about market dynamics. It’s 50 different markets, with a high degree of fragmentation and regionalism," said Fregeau. "Understanding how this all worked, and ensuring our platform could support this complexity was very important.
"What we did find consistent across the board is that brokers and agents are facing the same core challenges: shrinking margins, excessive manual work, and insufficient time for clients. If anything, the urgency for AI-powered solutions feels even greater in the U.S., where scale and complexity make these pain points harder to ignore."
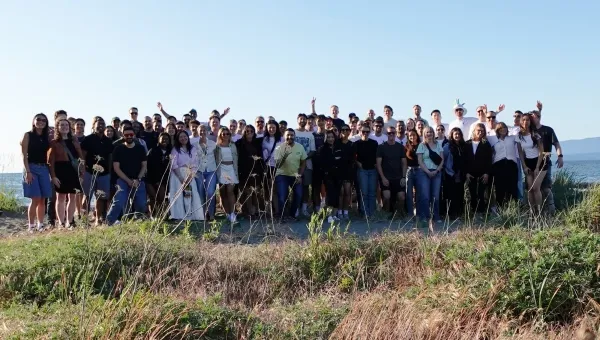
Quandri team June 2025
The company plans to hire more than 40 people before the end of 2025 and has opened a new 15,000-square-foot office in Vancouver to support its growth.
"Our priorities are expanding our integrations so we can serve more customers across the U.S. who want to use our platform," said Fregeau. "We’re also hyper-focused on growing our engineering team to drive deeper AI capabilities and scale our impact across the broker and agent servicing stack."
Fregeau also offered reflections on scaling a fintech business into the U.S., especially for Canadian startups.
"While there is work when it comes to data localization, regulatory alignment, and compliance, those aren’t significant hurdles to overcome. The larger barriers are related to your product-market fit (PMF). Don’t assume PMF in one market will translate to the other — even though they may look similar, they are different.
"Do your due diligence, interview prospects, understand the real pains in the market and what’s different from your home market. It will take time to learn this, and that's okay, because it's worth it. However, we initially underestimated the differences and could have made better decisions had we been more open-minded in the beginning."
Fregeau added:
"There’s massive opportunity, so go for it. Getting to 70% operational isn’t that hard — the hard part is taking something that works in 70% of cases, and making it work in the enterprise 95% of the time, predictably and consistently. Otherwise, you won’t get adoption, renewals or expansions. Listen to your customers, but also know when you need to give them something that they aren’t asking for that will solve the root of their problem. There is no secret formula besides hard work and doing the gritty things right, day in and day out, over a long period of time."
Quandri's recent financing round highlights the demand for specialized, AI powered tools built for legacy industries. By focusing on renewals and customer engagement in a data-drien environment, Quandri is helping clients boost operational gains and capture longer term strategic value. Expanding product suite and footprint across North America, Quandri's stack could become foundational infrastructure for insurance broker operations.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Agentic AI | July 14, 2025
Image: Freepik AI
Last Friday several outlets reported that Goldman Sachs is now using an AI software engineer named Devin. Now it may seem like what's the big deal here, everyone is using AI engineers, but this is a major U.S. bank, and Goldman says some developer teams using Devin are already producing 3x to 4x more output.
This is not a trial in a lab. It is a working system inside the bank. According to AInvest, Goldman has about 12,000 developers deployed across hundreds of teams (read 'at risk'). It's one of the first major publicly known cases of a major financial institution putting AI to work in a coding production environment.
Devin can complete full software tasks. It can set up development environments, run scripts, write and test code, and fix bugs on its own. It's agentic AI and can do these things without being told what to do at each step.
Having said that, it doesn't mean it always works (just yet). As reported by Fast Company, when Cognition Labs tested Devin, it only succeeded 3 out of 30 GitHub problems. That’s why Goldman still needs human developers to supervise the output currently. Teams check the code for accuracy and make sure it’s secure, and reviewed before it gets deployed.
Goldman is sending a clear message that AI tools are delivering measurable gains. Some software teams are producing three to four times more than before, and tools like the GS AI Assistant are already being used by 10,000 employees at Goldman for non-coding tasks. Any company that ignores AI now, seemingly will only fell behind on speed, output, and efficiency.
With Devin handling routine tasks, developers are now spending more time reviewing code, planning architecture, and testing fringe use cases, which are all tasks more valuable to the final product experience than basic coding (warning to junior developers).
So, companies must rethink how they hire, train, and structure their technical teams to focus on oversight and system integration.
Devin is currently a closed, proprietary tool unavailable to the public. It's also expensive and under NDA. That leaves smaller firms with0ut access and at a disadvantage. Canadian fintechs should be piloting open or commercial agent-based tools or partner with AI providers that offer more access to remain competitive.
AI code can fail spectacularly if unreviewed by a human currently. This can lead to security holes and/or logic gaps. Canadian companies also need human engineers to oversee similar governance, such as audits, version controls, quality assurance gates, and compliance reviews.
Not too long ago, we said the 'robots were here'! Well now Goldman is using AI to write their banking production code. Productivity is rising but it comes with new risks. Roles are changing, and oversight and governance is critical. Canadian financial technology companies must not fall too far behind. Those that jump in now will likely be in a better position to compete later.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto | July 11, 2025

Image: BTCUSD Tradingview
Bitcoin just printed a massive green candle, BTC reaching a new all-time-high (ATH) of USD $118,000, boosted by institutional inflows, constrained supply, and regulatory momentum in global markets. At the same time, Canada is working to finalize long awaited rules to bring clarity to crypto exposure for funds and federally regulated financial institutions. Collectively, it's a rare convergence of events that are pushing up price. It's a timely opportunity for Canadian fintechs, fund managers, and policymakers to assess their positioning and prepare for what's next.
Global capital flows into Bitcoin are accelerating, as international financial markets interact with the asset.
U.S. spot Bitcoin ETFs have attracted over $51 billion USD in net inflows since January 2025. These products are managed by firms like BlackRock and Fidelity, are offering institutional investors direct and regulated access to Bitcoin at scale. On July 9 alone, daily flows exceeded USD $1.18 billion.
Bitcoin balances held on exchanges have fallen to their lowest levels since 2017, according to Glassnode data. It means long term hodlers are accumulating and there are fewer sellers which tightens liquidity and pushes prices upwards during surges.
Roughly $1 billion USD in short positions were liquidated in early July, forcing traders to buy back positions at higher prices, creating momentum that further boosts demand and additional institutional entry.
The GENIUS Act cleared the Senate with a bipartisan 68–30 vote on June 17, 2025, establishing the first federal framework for stablecoins (see SEC Issues Covered Stablecoin Statement, Risks Remain), including issuer registration, reserve and audit rules, and oversight. Next up is a House vote during “Crypto Week” starting July 14. In March, the White House issued an executive order creating a Strategic Bitcoin Reserve stocked with seized BTC and a broader digital assets stockpile, which aims to treat Bitcoin as a national reserve asset.
Major asset managers like Fidelity and BlackRock are incorporating Bitcoin as a foundational allocation. In May, U.S. spot Bitcoin ETFs saw a net inflow of $9.209 billion USD in just one week led by BlackRock’s IBIT and Fidelity’s FBTC. While global forces are transforming financial markets, what matters for Canadian fintechs and financial institutions is how Canada is responding.
In February 2025, the Office of the Superintendent of Financial Institutions (OSFI) published its final guideline on crypto-asset exposures. Taking effect later this year, the new framework applies to all federally regulated banks and insurers. According to Norton Rose Fulbright, it establishes:
These rules are an important step in integrating crypto within Canada’s prudential regulatory system, and they provide institutions with clearer guardrails to support innovation while managing systemic risk.
On April 17, 2025, the Canadian Securities Administrators (CSA) finalized amendments to NI 81-102, the national rule governing mutual funds and investment products. These changes come into force on July 16, 2025.
As detailed by McMillan and McCarthy Tétrault, the new rules say that:
The OSFI and CSA frameworks are opening clearer paths for new crypto products and more diversified portfolios. Fund managers can now launch Bitcoin-focused vehicles with defined rules around eligibility, custody, and risk.
Banks and insurers must begin planning for capital and governance policies that align with OSFI’s exposure thresholds.
Fintech platforms have more certainty when adding Bitcoin related features, with legal and compliance expectations now taking shape.
These changes also raise the bar for investor protection, requiring firms to strengthen disclosures, improve internal oversight, and adopt secure custody practices.
Another Bitcoin ATH is worth celebrating but the deeper trend is about normalization. Not too long ago, crypto assets were speculative but they are now moving to regulated infrastructure.
Canada is positioning itself to participate in a more stable and credible digital crypto future, and there's growing alignment between global investment flows and domestic regulatory action, providing fintechs and capital providers with greater clarity and confidence than ever before.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
BC Fintech Tax Credit | July 8, 2025
Image: Freepik
British Columbia is making perman Interactive Digital Media Tax Credit (IDMTC) and raising the rate to 25%, effective September 1, 2025. The expanded credit applies to qualified salaries and wages for the development of video games, virtual reality (VR) applications, educational software and simulators.
The IDMTC was first introduced in 2010. The 25% rate was recently put on the table as a temporary increase under Budget 2025 which is now being made permanent. It replaces the earlier 17.5% baseline rate and is aimed at helping creators retain staff, attract capital, and grow jobs in the province’s interactive digital media sector. According to CreativeBC, the industry contributes over $1 billion to provincial GDP and supports over 20,000 jobs.
David Eby, BC Premier, said that it will boost long term investment:
“This tax credit will help game developers hire, attract new investment and keep building some of the best games in the world.”
Brenda Bailey, Finance Minister and former game developer, emphasized the impact on both indie and enterprise studios:
“Whether they are a software engineer at a VR developer or an artist at an independent game studio, we stand by our developers.”
The province also announced:
There are currently 161 video game companies and 230 immersive tech firms operating in BC, many of them with fewer than 10 employees. Global developers with a presence in the province include Microsoft, Nintendo, EA, Take-Two, and CD Projekt Red.
This permanent tax credit increase will strengthen the planning outlook for studios, venture funds, and fintechs financing interactive media. Companies using revenue-based financing or IP-backed lending models now will be operating in a more stable tax environment.
Investors and lenders can model developer cash flow with improved accuracy, especially for VR and immersive media startups that operate on tight burn rates. For full details, visit the official IDMTC program page.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Banking | July 7, 2025
Ripple has officially applied for a national bank charter from the US Office of the Comptroller of the Currency (OCC). The company is also seeking a Federal Reserve master account to support direct access to US payment rails.
CEO Brad Garlinghouse confirmed the news on X:
True to our long-standing compliance roots, @Ripple is applying for a national bank charter from the OCC. If approved, we would have both state (via NYDFS) and federal oversight, a new (and unique!) benchmark for trust in the stablecoin market.
Earlier in the week via… https://t.co/IdiR7x3eWZ
— Brad Garlinghouse (@bgarlinghouse) July 2, 2025
If approved, Ripple would bypass correspondent banks by settling payments directly with the Fed and holding dollar reserves without intermediaries. This is designed to support Ripple’s push to offer a compliant, enterprise-grade stablecoin and accelerate global payments. These objectives align with new federal rules proposed under the GENIUS Act, which sets clear reserve and disclosure standards for stablecoin issuers.
Ripple’s approach mirrors that of Anchorage Digital and Circle, which operate under national trust bank charters regulated by the OCC. Ripple may use its regulated subsidiary, Standard Custody & Trust, to separate digital asset exposure from its core balance sheet. This structure could help the firm meet Basel III capital requirements by keeping volatile assets like XRP off its banking books.
Following the announcement, XRP surged above $2.28 as trading volume spiked. Analysts said the rally was driven by rising confidence that Ripple’s regulatory strategy will boost its long-term institutional credibility.
If Ripple is granted the charter and Fed account, it will become one of the few crypto-native firms operating fully within the traditional banking system. It's a significant and growing trend among major fintechs like Circle, Wise, and others seeking deeper integration with regulated payment rails. For Canadian fintechs and regulators, Ripple’s move could accelerate the need to clarify stablecoin policy, custody standards, and access to domestic settlement infrastructure. Regulatory certainty is a competitive advantage today and quickly becoming the norm.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Tokenization | July 3, 2025

Image: Freepik
On June 30, 2025, Robinhood announced a major expansion into tokenized assets and crypto infrastructure during an event in Cannes. The company’s official release detailed its launch of tokenized U.S. equities for EU users, new staking and derivatives products, and the development of a proprietary Layer 2 blockchain designed to support real world asset (RWA) tokenization. It's a clear pivot and global crypto strategy that could define the future of hybrid investing platforms.
Robinhood will allow European Economic Area (EEA) users to buy and sell tokenized versions of over 200 U.S. stocks and ETFs. These digital assets come with no commission, no spread, and include dividend payments, mirroring their traditional equivalents while trading continuously during the week. The tokens are initially issued on Arbitrum but will transition to Robinhood’s newly announced Layer 2 blockchain, which is being developed specifically to support RWA tokenization, self-custody wallets, and instant settlement.
The EU rollout aims to open access to U.S. equities for hundreds of millions of crypto-enabled users. The goal is to create a multi-asset investment experience that spans stocks, ETFs, and digital currencies all on one unified platform.
Robinhood’s expansion also includes the launch of crypto perpetual futures contracts for Bitcoin and Ethereum. These will be offered with up to 3× leverage across eligible EU users, with order routing handled through Bitstamp’s regulated platform. At the same time, Robinhood has introduced staking support for Ethereum and Solana. Staking is already live in the EU and will expand to U.S. users where legally permitted.
Robinhood is also offering deposit incentives, including bonuses of up to 2% on incoming crypto transfers, with the company targeting up to $500 million in new crypto inflows.
Robinhood confirmed that it is building its own Layer 2 blockchain. The network will enable fractional ownership of stocks and ETFs, wallet-native asset recovery, smart contract interoperability, and real time cross-chain bridging. It will also provide the infrastructure for on-chain settlement of financial instruments such as tokenized equities and derivatives. Having it's own blockchain will reduce dependence on third parties while positioning Robinhood to eventually become the protocol layer for its own assets and services, including digital custody and regulated RWA trading.
Robinhood also launched a crypto rewards credit card, allowing users to automatically convert cashback into digital currencies. In addition, the company now lets users choose which crypto or stock purchases to sell first for tax purposes, smart order routing, and high frequency charts designed to support more active traders. A new AI assistant called Cortex is being integrated into the app, offering personalized alerts, market trend recognition, and portfolio analysis for premium users.
All of these updates are part of Robinhood’s broader strategy to become a comprehensive investing ecosystem that spans traditional equities, digital assets, and blockchain infrastructure.
Robinhood’s stock rose by more than 12% following the announcement. As reported by MarketWatch, the SEC also sent market signals that may be interpreted as supportive. Robinhood has taken advantage of the EU's open approach towards digital finance and pilot models that aren't yet permitted in Canada, raising an important question: if tokenized equities are safe and functional for the EU, what regulatory barriers continue to hold back innovation in Canada?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto | July 2, 2025

On June 27, 2025, the U.S. Securities and Exchange Commission (SEC) officially approved the conversion of Grayscale’s Digital Large Cap Fund (GDLC) into a spot exchange traded fund (ETF). The fund is now listed on NYSE Arca, offering investors access to five major crypto assets in one regulated product. It's the first time that a U.S. spot ETF includes not just Bitcoin and Ethereum but also Solana, XRP and Cardano, establishing a new precedent for how diversified crypto products can be structured and approved under SEC oversight.
The Grayscale Digital Large Cap ETF largely follows the CoinDesk Large Cap Select Index, which rebalances monthly. As of July 1, 2025, the fund holds:
GDLC now offers direct access to these assets through a public listing.
Prior to this approval, GDLC operated as a closed-end trust on OTC markets. It lacked daily liquidity and tradeed at a discount or premium to the fund’s net asset value. The new ETF lets large investors swap crypto directly for shares in the fund, and vice versa, which helps align market prices with the actual value of the crypto held.
Grayscale completed the conversion of approx $775 million USD in assets by the SEC’s July 2 compliance deadline, making the ETF now the largest multi-crypto fund of its kind in the United States.
This is the first time U.S. investors can now access a range of large-cap crypto assets, beyond just Bitcoin and Ethereum, through a regulated spot ETF. It reduces the need to manage separate holdings or rely on offshore exchanges.
Analysts now estimate a 95% likelihood that ETFs for XRP, Solana, and Litecoin will be approved in the U.S. later this year. Major firms including Bitwise and Franklin Templeton have already submitted filings.
This approval reinforces legal and regulatory precedent and build's on Grayscale’s 2023 legal victory, which challenged the agency’s rejection of a Bitcoin ETF. That ruling continues to impact how the SEC responds to ETF applications. It also highlights the SEC's evolving policy on crypto including assets that were previously under regulatory scrutiny such as XRP. The SEC is now clearly willing to consider broader crypto exposure in compliant funds, even while legal classification questions remain up in the air.
The door to broader index-based crypto products is likely to follow, such as new ETFs tied to crypto indices, sector themes, and/or platform categories. See NCFA’s article on the crypto ETF battle intensifying with XRP, Solana, and Dogecoin.
Canada continues to lead with crypto ETF adoption. The Purpose XRP ETF launched on the TSX on June 18, 2025, while Canadian investors already have access to ETFs for Bitcoin, Ethereum, and Solana. See also NCFA’s report on Canada’s first Solana spot ETF with staking.
For Canadian fintechs and investors, growing alignment in North American regulation signals an opportunity to expand services built around compliant digital asset products. As U.S. markets open up to a wider mix of crypto ETFs, Canadian firms offering custody, compliance, or portfolio tools will be well positioned to support cross-border demand and deepen product innovation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016