




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


M&A | June 16, 2025
Image: Freepik
Another high growth Canadian founded tech startup exits on foreign soil. U.S. giant Qualcomm has agreed to acquire Toronto-founded semiconductor designer Alphawave Semi (Alphawave) for US$2.4 billion. The acquisition strengthens Qualcomm's data center and AI capabilities but also raises recurring questions about Canada's ability to retain and scale its homegrown innovators.
Alphawave was founded in Toronto in 2017 by Canadian engineer Tony Pialis. The company builds technology that helps computers move large amounts of data quickly and efficiently. Qualcomm plans to use Alphawave's technology alongside its own processors to support the growing demand for AI and energy efficient data centers.
In 2021, Alphawave chose to go public on the London Stock Exchange instead of listing on a Canadian stock exchange like the TSX. The decision was widely viewed as a sign that Canada's capital markets were not deep enough to support large scale semiconductor or hardware IPOs. At the time, Alphawave raised roughly US$500 million in its debut, validating London as a preferred launchpad for global visibility.
Alphawave is legally incorporated in the United Kingdom as Alphawave IP Group plc (AWE.L), with its official registered office in Leeds, England. The company is listed on the London Stock Exchange and governed by UK corporate law.
However, since the firm was founded in 2017 in Toronto, it maintains significant operations in Canada. Its main office still remains in Toronto, and it continues to operate major engineering and R&D facilities in Kanata, Ottawa, employing over 250 staff in the country. Alphawave recently opened a 20,000 square foot R&D lab in Kanata and actively recruits from Canadian universities.
So, while the public listing and legal structure are based in the UK, Alphawave's tech development and leadership talent are deeply rooted in Canada. The decision to list in London was based on the availability of semiconductor capital and deeper markets for advanced technology, according the company's leadership.
Alphawave is one of the most prominent Canadian-founded technology firms to exit internationally in recent years. The company's core IP and chiplet designs power data centers, AI infrastructure, and cloud platforms, foundations for fintech, e-commerce, and cybersecurity services, which are increasingly built with low latency, high performance hardware.
For policymakers and Canadian fintech leaders, it's clear that without stronger later stage funding mechanisms, global scale listings, and/or targeted supports, more Canadian firms are at risk of scaling elsewhere and being acquired prematurely.
Alphawave's story is another wake up call that Canada needs to continue to invest in Canadian tech companies to be globally competitive, from capital to commercialization, or risk a further drain of companies that need to look elsewhere to support their growth and success.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Stablecoins | June 13, 2025
On June 12, 2025, Shopify announced that USDC stablecoin payments will be made available to its global merchant base via a new partnership with Coinbase and Stripe. So merchants can now accept USD Coin via Coinbase' Base Blockchain. This new payment feature is available in early access and will expand over time to offer fast, borderless payments without foreign exchange fees and integrated support for crypto wallets through Stripe.
Merchants using Shopify Payments can now accept USDC from supported crypto wallets through guest checkout and Shop Pay. By default, they receive payouts in their local currency, with no foreign exchange fees. Alternatively, they can choose to retain USDC in their own wallets. Transactions are processed using a bespoke smart contract system on the Base network, jointly developed by Shopify and Coinbase. This new payment layer is purposely built to offer similar functions as traditional card networks, allowing features such as delayed capture, tax finalization, and inventory reservation to work natively with stablecoin payments. So stablecoin checkout process will act just like normal e-comm payments but with the benefits of being faster and global.
Shopify recently acquired Privy which gives Shopify access to a wallet layer that integrates smoothly with both new and existing platforms. Stripe acquired Bridge, which provides the stablecoin rails needed to connect wallet payments to practical merchant settlements. So thanks to Stripe's backend capabilities, merchants won't have to manage blackchain infrastructure but payments will appear on their dashboard as any other transaction would.
Stablecoins offer three major benefits which allow small businesses to access global markets, receive payments quickly, and reduce reliance on expensive or delayed banking infrastructure:
Stablecoins have been all the rage recently, but there should be no doubt now that they've moved beyond hype and being adopted in real world scenarios at scale. The confluence of proven technology, incentives, and aligning regulations make stablecoin payments ready for prime time, and everyday merchants.
Shopify has widespread reach, serving millions of businesses globally every day from startups to large brands. It's somewhat clever to mimick existing card payment flows because it reduces learning curves and some friction points for retails.
Stripe's wallet to fiat infrastructure removes the complexity of crypto for every day merchants.
Stablecoin policies in the U.S. are moving forward, creating a legal pathway for this type of integration to work. The landscape was vastly different only a year ago. The GENIUS Act aims to provide clear rules for dollar-backed stablecoins like USDC.
This move will add significant competitive pressure to competing payment processors, and e-commerce merchant ecosystems. Expect Meta, Apple Pay, PayPal, Walmart, and Amazon to follow soon. Oh look, they already have started to move.
This is no longer a pilot. I repeat, this is no longer a pilot. Stablecoin infrastructure is being released into production at scale.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Financing | June 12, 2025

Image: Freepik/rawpixel.com
On June 6, 2025, Gemini announced that it confidentially submitted a draft registration statement to the U.S. Securities and Exchange Commission (SEC) for a proposed IPO of its Class A common stock. The SEC will now review the statement subject to market conditions.
According to Coingecko, the total global crypto market cap has reached $3.5 trillion with Bitcoin holding above $107,000. Stablecoin issuer Circle's IPO debuted on the NYSE in early June with a over 170% on the first day. Coinbase joined the S&P 500 in May.
Gemini’s IPO intent follows the resolution of enforcement matters with both the SEC and CFTC, positioning itself as one of the first fully compliant crypto exchanges to go public since the FTX collapse in 2022.
If Gemini clears the IPO gate in the U.S., the flood gates will be open for a reset of crypto's place in public markets but only for compliant and credible digital asset firms that prove they are ready for institutional trust (and capital) - not just the hype.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech Product Launch | June 12, 2025
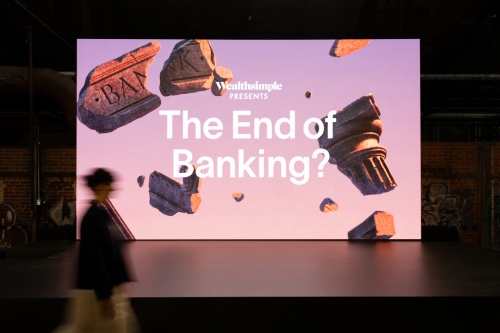
Image: Wealthsimple Presents: The End of Banking (WS Newsroom)
On June 11, 2025, Wealthsimple hosted their first 'Wealthsimple Presents: The End of Banking?" public event in Toronto where they announced the launch of two new financial products that will compete head-on with Canada's largest banks and financial institutions. (1) No fee 2% cashback credit card; and (2) Instant access low rate line of credit starting as low as 4.45%.
These offerings are for anyone who is currently paying banks and credit card companies higher interest rates and fees for the same services, and everything is online and available without having to visit a physical branch. This is healthy competition that will only benefit consumers, and the Canadian government and regulators should take notice.
The company also highlighted a series of upgrades to its hybrid chequing/spending account and teased new cash delivery pilots that could soon offer same day cash drop-offs to users' doorsteps.
Michael Katchen, Co-founder and CEO of Wealthsimple:
“Canadians don’t need another bank. They need something better. We’re removing friction, fees, and outdated experiences.”
The new Wealthsimple credit card is the most requested product in the company’s history. It offers:
Sam Newman-Bremang, Senior Product Director at Wealthsimple:
“This isn’t just another credit card, it’s the one Canadians have been asking for. As the most requested product in our history, it’s clear people want a smarter and more rewarding way to use credit. So that’s what we built: a card that puts humans first, with unlimited cashback, no foreign transaction fees, and no hidden charges.”
Wealthsimple will also roll out a line of credit product by the end of 2025 with rates starting at 4.45%, depending on collateral and client profile. The current Bank of Canada prime rate is 4.95% source, which means Wealthsimple’s offering could undercut many traditional unsecured personal loan products, such as unsecured credit card APRs (20-24%+) or home equity LOC rates (typically 5.5-5.7%).
Unlike typical credit lines, Wealthsimple clients will be able to use their investment or chequing balances at Wealthsimple as collateral, enabling lower risk and faster approval.
Plus, because Wealthsimple is not a federally regulated bank, it partners with 10 Canadian banks to hold deposits and qualify customers for up to $1 million in CDIC protection, which is much more than the standard $100,000 protection one would get by banking at a single institution.
Wealthsimple now offers a type of chequing account that pays 2.75% interest, 1% cashback on debit purchases, no monthly fees, and no ATM or FX fees. Over one million clients or approx 33% of Wealthsimple’s user base has already adopted the spending account.
The company estimates that in 2024, its users saved more than $100 million in fees they would have paid to traditional banks source.
Recent additions include:
Wealthsimple’s growth strategy is grounded in public dissatisfaction with incumbent financial institutions. In a 2025 Angus Reid survey commissioned by Wealthsimple:
Despite this, the Big Six banks still dominate with over 90% of banking assets under management in Canada. But no doubt that Wealthsimple is on a growth pathway that will chip away at the bank's dominant share by competing with seamless design, lower fees, higher yielding accounts and integrated financial tools built for mobile first customers.
Canada's fintech sector continues to face significant barriers to scale, including regulatory delays around open banking and digital ID. Despite that, leading scale-up fintechs like Wealthsimple are demonstrating how digital platforms can expand their value propositions without becoming a formal bank or acquiring a banking license.
Its model has scaled without a banking licence by partnering with regulated banks and embedding services within a single mobile platform. Wealthsimple now has over 3 million clients and manages over $70 billion in assets, up from $18 billion in 2021. If/when opening banking arrives in Canada, platforms that blend investments, borrowing, payments on a single interface will be game-changing for Canada's financial economy.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Policy | June 11, 2025
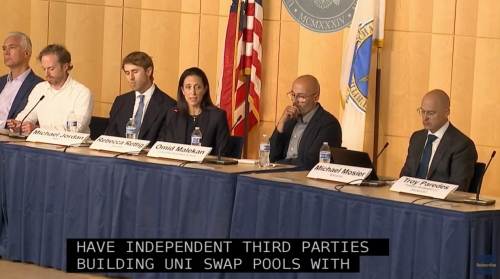
Image: June 9, 2025 DeFi Crypto Roundtable (Coindesk via youtube)
On June 9, the U.S. Securities and Exchange Commission (SEC) hosted another crypto task force roundtable series session called, "DeFi and the American Spirit", bringing together together regulators, legal experts, DeFi protocol developers, and investors to discuss how to the potential of regulating decentralized financial systems in ways that protects users without stifling innovation.
From the get-go, Chair Paul Atkins set the tone by opening the event by clearly stating that publishing code should not be treated as a crime:
“We will not regulate the act of writing open-source software. We do not prosecute the author of a hammer manual when someone misuses a hammer.”
The rest of the session built on this idea and focused on how the SEC can provide safe ways for DeFi projects to operate legally while still addressing investor risks.
In his remarks, Chair Atkins introduced the idea of a “conditional exemptive relief framework” which would allow DeFi innovators to build and launch on-chain products under limited conditions without triggering enforcement right away. This type of framework is similar to a regulatory sandbox that provides time-bound relief as long as participants meet specific safeguards.
“We are exploring a conditional exemptive relief framework that would allow experimentation under defined boundaries, similar to an innovation safe harbor.”
Commissioner Hester Peirce (aka Crypto mom) echoed this sentiment saying without a structured pathways to compliance, many innovators will either operate in legal uncertainty or offshore their projects out of the United States.
“Without a clear, conditional pathway, we are telling innovators you are on your own. That is not a message we want to send if we value the benefits of decentralized systems.”
In addition to the DeFi safe harbour, Chair Atkins also called upon his staff to modernize the current SEC rules to accommodate traditional issuers and intermediaries who want to use on-chain infrastructure.
This move shows that the SEC is looking to facilitate both new DeFi entrants and existing market players who are building tokenized products or using smart contracts to manage trading, issuance, or custody.
“I have asked the staff to consider whether amendments to the Commission’s rules and regulations would be better suited to provide needed accommodation for issuers and intermediaries who seek to administer on-chain financial systems.”
Atkins also discussed that on-chain systems can bring real benefits to the market, such as lower transaction costs, faster settlement, broader access, and the ability to create entirely new asset classes.
“I also am excited about the use of on-chain software systems by issuers and intermediaries to eliminate economic frictions, increase capital efficiency, enable new types of financial products, and enhance liquidity.”
It's clear support and endorsement of blockchain as a tool for economic growth, not just a solution for compliance challenges.
Several panelists, including Rebecca Rettig of Polygon Labs, warned that some of the most serious risks in DeFi happen off-chain. These include hidden liquidity deals, token allocations to insiders, or governance control partnerships.
“It is not always what is on-chain that creates the risk. It is often what is not disclosed, like side agreements, control over governance tokens, or preferential liquidity deals.”
Panelists argued that DeFi projects need better disclosure on how protocols are governed, how tokens are distributed, and whether any third parties receive special treatment or not.
Legal and industry experts said regulators should stop focusing on whether a token is a security and start regulating based on what the product or service actually does.
Angela Angelovska-Wilson of DLx Law said:
“We waste enormous energy litigating over whether X token is a security. The better path is regulating the activity, such as staking, custody, or lending, regardless of the label.”
Michael Jordan of the Digital Dollar Foundation agreed, saying:
“If we regulate the technology, someone will build around it. If we regulate the activity, we have a chance at real consumer protection.”
Important to understand the growing consensus that rules should distinguish between different types of financial behaviour even when the technology is similar.
Josh Garcia of Ketsal pointed out that some interfaces like custodial front ends that take custody of user funds or routes trades on behalf of users may require stricter oversight whereas protocols without admin control may require lighter regulation. Advocating for a layered regulatory approach that differentiates on function and control.
“A protocol with no privileged admin keys is not the same as a custodial front end that routes retail funds. The obligations differ, and so should the rules.”
After several Crypto Task force roundtable sessions, the SEC and participants are finally getting on the same page while focusing on conditional exemptions, regulatory modernization, and functional oversight. All together, it's a series effort to balance investor protection with lawful DeFi innovation. For fintech founders and digital asset platforms in Canada and globally, it's an important benchmark. If the U.S. begins providing clear compliance pathways and policy support for tokenized systems, then other jurisdictions will need to keep up or risk flight of builders and capital.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Policy | June 11, 2025
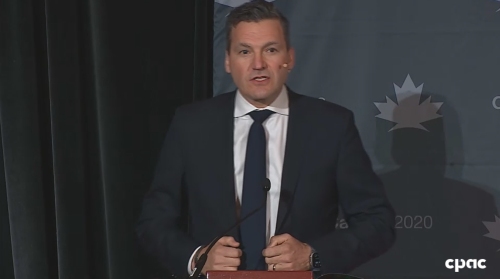
Image: Canada's Minister of AI and Digital Innovation, Solomon Evans Keynote at Canada 2020 event Ottawa (CPAC)
Prime Minister Mark Carney recently appointed Solomon Evans as Canada's first ever Minister of artificial intelligence and digital innovation to lead AI policy development and scale industry, trust and adoption. Solomon just delivered his first public remarks saying that the federal government will prioritize economic growth from artificial intelligence over advancing strict new rules. This new approach follows the collapse of Bill C-27’s AI framework, which failed to pass before the election and left Canada without a federal AI law.
Delivering a key note at a Canada 2020 event in Ottawa on June 10, 2025, Solomon said regulation must protect privacy and personal data but should not constrain innovation. Solomon confirmed that the previous governments AI regulation bill is currently under review.
“We’re not here to throw a saddle on the bucking bronco of AI but we do need to make sure it doesn’t kick anyone in the face.”
Feeling the heat of competition, even governments feel FOMO, and the global trend currently is moving from AI safety messaging towards AI adoption strategies. At the AI Action Summit in Paris, U.S. Vice President JD Vance pushed back on Europe’s regulatory overreach, while President Trump’s draft 'One Big Beautiful Bill' includes a proposed ten-year ban on state-level AI rules. Solomon seems aligned with this shift suggesting that global coordination is difficult, and Canada “won’t go it alone”.
NCFA Canada supports a speedy, focused rollout of AI investments that prioritize open access and trust, especially for smaller firms. Without clear guidance, shared tools and integrate support, SMEs will fall behind. Most do not have the internal capacity to evaluate or safely integrate AI, and that puts Canada’s productivity and innovation milestones in jeopardy. Canada's new AI czar, Solomon, acknowledged this gap, saying big companies are adopting AI, but “small and medium enterprises are not.”
Solomon also emphasized government support for Canadian champions like Cohere. In cases where specialized technical leadership is required to build national AI infrastructure, such as secure compute environments, working with proven domestic firms can make strategic sense. But NCFA cautions that these partnerships must be transparent, based on merit, and designed to benefit the broader ecosystem. The priority must remain funding open infrastructure and access, not enabling a sustainable advantage to a select few. Without transparency on this front, Canada risks loss of investment, talent, and IP.
The reality is that Canada’s innovation economy simply can't afford red tape bottlenecks or further restrictions that slow AI growth, especially since its hoping that broad adoption of the technology will turn the countries productivity woes around.
Canada also can't afford regulatory ambiguity that raises red flags for domestic and global firms alike. Solomon says he wants to “crank up commercialization” and support IP protection. That will only work if firms trust the environment they’re entering. For that, Canada needs smart policy, not just encouragement.
Canada is in a global race to lead in responsible AI and having a dedicated AI minister is a positive step, but evolving Canada into a trusted AI economy depends on speed, clarity and inclusion among other things. NCFA calls for the government to boost support for SME adoption, ensure rules are clear and fair, and build national infrastructure that attracts global innovators without sidelining local ones.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Canada-Africa | June 10, 2025

Image courtesy of the Canada-Africa Fintech Summit, Aug 5-8, 2025 | Toronto
Foreign aid to Africa is in rapid retreat but this is not the end of growth. It is the beginning of a new investment cycle, one that's not built on charity but on returns. As Mo Ibrahim recently wrote in the Financial Times:
"Africa’s future will depend on capital raised and deployed through smarter governance, stronger ecosystems, and financial innovation."
Fintech is driving growth in digital payments, lending, and cross-border services from Cairo to Cape Town. Now, global and diaspora investors are stepping up to high growth opportunities by backing key ventures changing the future of African finance.
Mo Ibrahim points out that the long decline in international development assistance has reached a critical point. Countries can no longer rely on donor budgets to fund health, infrastructure, or economic growth. He sees this as a call to action.
Mo Ibrahim, Founder and Chair of the Mo Ibrahim Foundation:
“Africans should not mourn the end of international aid. Now is the time to look inside our own borders and make African-led investment the cornerstone of African development.”
So what does this turning point actually mean? For African governments and businesses, it means doubling down on transparency and efficient capital deployment. For global investors, it is an entry point into a rising market with 1.4 billion consumers, one of the world’s fastest growing digital economies, and with real demand for services. And for global governments including Canada, its time to develop and mobilize an African strategy.
To unlock investment, licensing needs to be transparent, policy clear, and legal trust required. But even the best regulated and efficient fintech markets can't grow without capital. Africa's fintech sector is maturing, and the next phase will be defined by the scale and speed of investment into the continent.
In 2024, African start‑ups raised US $3.2 billion in equity and debt funding. Financial tech companies represented about 60% of the total equity funding (US $1.3–1.4 billion), and 47% of all startup funding, with a 16% increase in deal volumes despite global headwinds .
African fintech firms have proven they can scale, and many now require structured growth capital to extend beyond major metro financial hubs. This is where hybrid models are gaining ground.
Flutterwave, one of Africa’s most prominent fintechs, was co-founded by Nigerian entrepreneurs with deep local ties but its rise to a $3 billion post series D valuation was powered by a hybrid of diaspora and global capital.
Backed by firms like Tiger Global, Visa Ventures, and B Capital, Flutterwave also benefited from early African and diaspora networks. Co-founder Iyinoluwa Aboyeji, who now runs Future Africa, helped establish a model of reinvesting diaspora wealth into African ventures.
This combination of local knowledge and global capital is the emerging model. Diaspora fund managers, global venture capital firms, development finance institutions, and regional investors are increasingly working together to back companies with global ambitions and capacity to scale.
Africa is not waiting; they are expanding and forming strategic fintech partnerships, and its fintech leaders are already building the future of digital finance. What they need now is capital to scale. CAFS provides the connection point between Canadian and African fintech opportunities.
CAFS inaugural summit aims to connect African and Canadian fintech innovators, leaders, start-ups, digital finance and trade experts, investors, partners and policymakers to unlock and diversify cross-border opportunities, scalable fintech solutions, investment, and drive inclusive economic growth.
To learn more, get involved, and explore how you and your organization can participate, visit CAF Summit.

The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016