




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Crowdfunding Regulation | June 23, 2025
Image: Freepik/rawpixel.com
As reported by Crowdfund Insider, on June 11, 2025 the U.S. House Financial Services Committee voted unanimously (51-0) to progress the ACCESS Act (H.R. 3645), a bipartisan bill seeking to modernize and expand Regulation Crowdfunding (Reg CF). The legislation would crease the cap on Reg CF offerings and reduce costly compliance obligations for early-stage businesses. Supporters say these changes are urgently needed to make equity crowdfunding more viable for smaller companies struggling with capital access and high review costs.
Rep. Dan Meuser, House Financial Services Committee:
“America’s entrepreneurs shouldn’t have to choose between raising the capital they need and paying accountants more than they plan to raise. The ACCESS Act updates outdated thresholds so the next great neighborhood brewery, tech start-up, or Main Street retailer can spend its first dollars on growth—not paperwork.”
Small businesses and startups often say that raising capital is a top barrier to growth. In the U.S., Regulation Crowdfunding allows private companies to raise money from the general public through SEC-registered broker-dealer platforms but expensive compliance costs can limit use of the pathway. According to everyone who unanimously voted for the bill on the House Financial Services Committee, increasing the exemption threshold for reviewed statements will reduce costs, improve the uptake of Reg CF, and provide early-stage smaller firms a fairer path to funding.
On the other hand, invest advocates like NASAA, warn that loosening reporting requirements could raise investor risk, but supporters say platforms and disclosure rules already provide sufficient baseline protection.
Given the current economic climate and the unanimous and the fact that both major parties support the bill means there's a good chance of being approved. If adopted by the full U.S. House and Senate, the ACCESS Act could significantly increase the use of equity crowdfunding by small businesses across the U.S.
The Canadian equivalent to Reg CF in the U.S. is National Instrument 45-110 (startup crowdfunding), which has a $1.5 million issuer cap per 12 month period without any requirement to provide reviewed or audited financial statements.
The ACCESS Act is a rare bipartisan effort to reduce friction in Reg CF capital formation for small businesses, and if passed, could significantly boost the utility of the instrument and reduce compliance burdens holding back many early stage fundraising efforts in the U.S. Canadian regulators and industry should be closely following these changes to see how they can strengthen their own equity crowdfunding frameworks under Ni 45-110.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Fintech Partnership | June 19, 2025
Image: Freepik
Canadian fintech platform Zūm Rails has partnered with Western Union Canada to offer real time global money transfers. Using Interac e‑Transfer and Zūm’s API infrastructure, Canadian users can now send money to recipients in over 200 countries from their bank accounts, with funds delivered in minutes.
The partnership combines Zūm’s compliance and payment engine with Western Union’s international remittance network. Funds move through Interac e‑Transfer in Canada, then settle globally through Western Union’s infrastructure. The result is faster payouts, a simplified user experience, and improved access for both individuals and small businesses.
The new money transfer system allows customers to use a familiar Interac e‑Transfer interface, with Zūm Rails acting as the engine behind the scenes. Its role includes API routing, onboarding, compliance, and settlement integration. The entire experience is designed to run seamlessly on mobile or desktop.
For Canadian fintechs, this type of architecture demonstrates how open APIs and established networks can combine to deliver immediate value without needing to rebuild global infrastructure from scratch.
Craig Asano, NCFA Founding CEO:
“Zūm Rails’ API‑first approach and Western Union’s global network show how Canadian fintechs can lead in both innovation and scale.”
Many Canadian Small to Medium Sized Enterprises (SMEs) rely on global suppliers, freelance talent, or overseas partners but traditional international transfers can take several days and often carry high fees or lack transparency. So the ability to send or receive cross-border payments instantly delivers major benefits.
By moving funds in real time, companies enjoy faster access to working capital, can pay contractors on time, and support better financial planning. Moving money faster also improves the customer experience for refunds or disbursements, which all helps to build trust.
This partnership is in line with broader trends in Canadian payments. The federal government is advancing Open Banking through the Financial Consumer Agency of Canada, while Payments Canada continues to develop the real time rail (RTR) system.
Although those frameworks are still being finalized, Zūm Rails and Western Union are already showing what real time payments can look like in action.
The use of Interac e‑Transfer as a launchpad demonstrates the importance of maintaining open access to Canada’s core infrastructure. As global money movement becomes faster and faster, financial institutions are turning to fintechs for agile solutions.
Real time global payments are here, and they are being built in Canada. Zūm Rails and Western Union have shown how fintech can unlock new speed and scale by using trusted domestic rails and global infrastructure.
This partnership could impact open payments in Canada and offers a live case study of innovation already in market, and is a good example of how large players can approach platform collaboration, embedded finance, and cross-border transaction design.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI | June 19, 2025
Omage: Freepik/PVProductions
OpenAI has released a major new feature called ChatGPT Record, currently only available on Mac desktop app for Pro, Team, Enterprise, and Education users. It can capture your meetings, create organized notes, and follow up with questions afterward, all without a bot joining your call (just make sure you get permission from participants you are speaking with so they know they are being recorded).
Record mode is rolling out today in ChatGPT to Pro, Enterprise, and Edu users.
Available on macOS desktop app. https://t.co/xmReUOx473
— OpenAI (@OpenAI) June 18, 2025
No external bots or tools join the meeting, and the audio is processed directly on your machine using Whisper, then deleted right after. Team, Enterprise, and Education workspaces keep control of transcript retention, and admins can turn Record off completely.
Each session can last up to 120 minutes.
AI action bots like Otter, Fireflies, or Avoma typically join meetings as participants to record and analyze conversations. ChatGPT Record does all of that on your device without joining the call. It will then produce a complete summary, provide timestamped notes, list action items and even unresolved questions. The fact that it doesn't rely on a third party bot to connect externally streamlines the entire experience. Everything is integrated in ChatGPT.
You can ask follow-up questions after the meeting to Record, such as '“What did we agree on about timelines during yesterday’s call?”.
This is better than action bots that normally email follow-up summaries or assigned tasks to call participants because the recorded context stays within ChatGPT and remains available for ongoing reference.
Record is designed for privacy so it's safer for sensitive industries like legal, finance or healthcare where current bot participation can trigger compliance issues. Record processes audio locally and deletes files after transcription. It also aligns with your workspace's retention rules and excludes enterprise data from training by default. No training data is collected from your conversation if on a managed plan. Admins can disable Record completely at the team level.
But here's the kicker. ChatGPT's new feature Record could quite easily replace entire software categories (killing a bunch of startups in the process), such a transcription service providers, call recorders, meeting and note taking assistants, and AI action bots designed to facilitate similar functions.
ChatGPT Record is a major feature upgrade that combines privacy, productivity, and automation in a format that makes dozens of existing apps obsolete. Assuming it's safe and as promised, Record could be the default way meetings are captured and understood going forward for regulated industries, startups, and remote teams.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Tokenization | June 18 2025

As covered by Retuers, Coinbase is officially asking the U.S. Securities and Exchange Commission (SEC) to approve tokenized equities (or stocks), a new class of financial product. These would be blockchain representations of traditional equities, such as Apple or Tesla, designed to trade 24/7 with almost instant settlement and lower overhead. Coinbase is seeking a no-action letter or regulatory exemption from the SEC, and if they grant it, Coinbase would be the first major U.S. exchange operating with such tokenized products, evolving well beyond just a standard crypto trading exchange.
The tokenized equity model would allow retail and institutional users to access fractional ownership of blue-chip stocks via a blockchain interface and operate largely without the constraints of traditional brokerage platforms. For example transactions could take place globally, 24 hours a day, without relying on legacy clearing infrastructure. It could mean significant improvements in market efficiency, reduce settlement risk and include new financial products natively on-chain.
While Coinbase looks to break new ground in American markets, other jurisdictions are already operating. Rival exchange Kraken has launched tokenized stock trading for non-U.S. customers through its partnership with Swiss-based Backed Finance. For example, tokenized versions of Apple and Tesla stock, bAAPL and bTSLA respectively, are live pioneering examples of tokenized equities executed issued on the Solana blockchain, backed by 1:1 real shares held in custody, and tradeable with no minimum investment size and operate legally under global regulatory frameworks with blockchain flexibility, and 24/7 trading.
Europe is ahead of the curve on regulation. The EU’s MiCA framework was fully implemented as of 2024, providing legal clarity for tokenized securities across 27 member states. In Asia, Hong Kong is piloting tokenized gold, bonds, and equities under regulatory supervision. These jurisdictions are showing that comprehensive tokenization frameworks can unlock innovation while still preserving investor protection and market integrity.
Tokenized securities may require broker-dealer registration, SEC exchange approval, and compliance with the Investment Company Act. Since, Coinbase is not currently licensed as a broker-dealer, it may need a partner or entirely new structure to support these offerings legally.
There are also questions about liquidity. The World Economic Forum has identified low secondary market trading volumes and lack of standardization as persistent challenges in real-world asset tokenization.
While the tech stack can actually enforce compliance rules directly within smart contracts using standards for Real World Assets (RWA) like ERC-3643, adoption of these instruments will depend on regulators aligning globally and investors gaining trust.
If the U.S. and EU formalize tokenized security frameworks, capital will flow toward platforms offering speed, access, and interoperability, leaving slow movers behind. Companies should be exploring how to integrate tokenized equities into their product roadmaps while remaining compliant. NCFA and its members can play a leadership role in what responsible tokenized finance, launch educational initiatives, and collaborate with global infrastructure providers. At the of the day, tokenized assets are poised to become a competitive advantage or missed opportunity.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech | June 18, 2025
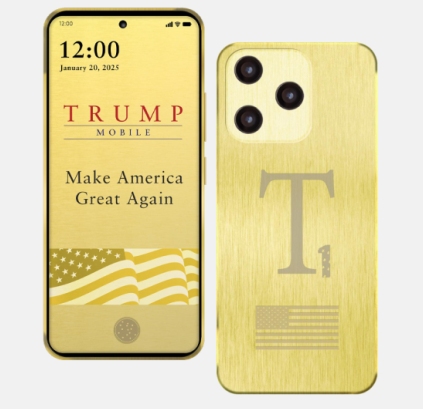
Image courtesy of Trump Mobile website
On June 18, 2025, Fortune reported that Trump Mobile is entering the U.S. wireless market with a $47.45 per month prepaid plan and a smartphone built by Chinese device maker Unihertz. Beyond the political optics, the announcement is interesting from a fintech perspective since Trump Mobile plans to use a telecom backbone to bundle lifestyle services in a way that mirrors embedded finance strategies seen in a variety of global fintech ecosystems.
The T1 smartphone is priced at $499 with a $100 down payment, and is scheduled to ship in late summer 2025. Trump Mobile is powered by Patriot Mobile, an MVNO that leases infrastructure from existing carriers. The business model relies on branding and licensing rather than owning physical networks. This setup closely resembles the way fintechs white label financial infrastructure through APIs and software platforms.
Eric Trump, EVP Trump Organization on Trump Media:
“I'm incredibly excited to step into this new digital space, hard-working Americans deserve a wireless service that's affordable, reflects their values, and delivers reliable quality they can count on. We're especially proud to offer free long-distance calling to our military members and their families — because those serving overseas should always be able to stay connected to the people they love back home. ”
The flagship product is the “47 Plan” offered at $47.45 per month. According to Trump Mobile’s website, it includes unlimited talk, text, and data, plus international calling. The bundled services also include 24/7 telehealth access and roadside assistance, which are traditionally sold separately or through insurance providers. Packaging them into a single mobile bill is a similar approach of fintech super apps.
The T1 phone has midrange specs: a 6.8-inch AMOLED 120 Hz screen, 12 GB RAM, 256 GB storage, a 50 MP triple camera setup, Android 15, a 5,000 mAh battery with 20 W fast charging, USB-C, a headphone jack, and biometric unlocking. The phone is manufactured by Unihertz in China, despite political framing that implied U.S. manufacturing. It unveils global hardware supplier realities that fintechs face when bringing physical devices to market.
According to The Wall Street Journal, the Trump family licenses its name to Patriot Mobile, which operates the network. This approach is similar to how fintech startups offer debit cards, wallets, and investment tools without becoming licensed financial institutions. The infrastructure is external, but the customer relationship is owned by the brand.
There is also a digital asset component. Reuters reported that Trump Media is applying for a cryptocurrency ETF made up of 75% Bitcoin and 25% Ethereum. Even though the potential crypto ETF isn't directly tied to the phone plan just yet, it highlights the Trump brand's ambition to combine lifestyle, media, and financial products.
Ironic as you get that earlier in 2025, the Trump administration slapped a raft of reciprocal tariffs, including a baseline 20% tariff on Chinese-made consumer electronics. According to Al Jazeera, the administration later exempted certain chips and phones but it's unknown which specific products currently qualify. If the T1 is subject to tariffs, the cost could be absorbed by Unihertz, passed to Patriot Mobile, or used to justify higher retail pricing.
Trump Mobile offers a live case study in how embedded services can be sold through telecom. For Canadian fintechs, it opens a conversation about how telcos and startups might partner to deliver subscription-based insurance, health care, or financial tools to underserved communities. Packaging multiple services into a mobile plan can improve customer stickiness, adding to predictable revenue, as also seen in bundled offerings by Koho, Neo, and other Canadian fintechs.
There should be policy concerns however, with potential conflicts of interest involving Trump's family ties to regulatory agencies. Also combining telco infrastructure with consumer finance triggers questions around cross-sector regulation, as regulators will need to consider the risks of a converging telco-fintech model as it grows.
For NCFA members, this launch offers insight into how bundled, cross-platform models can scale quickly with the right partnerships. As Canada expands open banking and explores new models of service delivery in underserved markets, this example shows how telecom-fintech convergence could work, assuming regulators allow it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto | March 18, 2025

On June 17, 2025, a watershed moment for digital finance and crypto with the U.S. Senate passing the GENIUS Act, bipartisan 68-30 vote, establishing the country’s first federal regulatory framework for stablecoins. This legislation is the most significant digital asset policy breakthrough to date in the United States.
The GENIUS Act stands for 'Guiding and Establishing National Innovation for U.S. Stablecoins'and lays out clear rules for the issuance, required reserves, transparency, and oversight of U.S. dollar backed stablecoins. It's expected to boost financial innovation in America by providing a coherent national policy to streamline the governance patchwork created by state-to-state rules. The stablecoin market has now surpassed $260 billion in total value (up about 22% in 2025 alone), and is growing rapidly with rising institutional demand.
As reported by WSJ, Senator Cynthia Lummis (R-WY, one of the bill's key sponsors) said:
“This is the first step in establishing trust, protecting consumers, and ensuring the dollar remains the global standard for digital finance,”
The bill outlines strict guardrails for stablecoin issuers to prevent another collapse like TerraUSD while ensuring stability, liquidity, and auditability:
The GENIUS Act delivers some legal clarity to a sector long operating under ambiguous guidance from regulators.
Notably, the issuer of USDC, Circle saw its pre-IPO share price boost nearly 10% on the news, rising from $31 to over $160 as investor confidence rebounded. The company’s CEO Jeremy Allaire explained the bill as “the foundation of dollar dominance in the digital era.”
The bill is still not without some controversy as critics flagged the exclusion of President Trump from the conflict of interest restrictions - seen as politically motivated and related to the Trump family's interests and ties to private stablecoin ventures.
The bill now moves to the House of Representatives to be reconciled with the STABLE Act, and then once approved in both chambers the bill would be sent to President Trump for signing the first major federal stablecoin bill into law.
Will Canadian regulators follow with similar national standards for fiat-backed digital assets? As OSFI and FINTRAC review their guidance, Canadian fintechs operating in cross-border payments, custody, and token issuance will begin to face rising pressure to align with U.S. rules or risk falling behind in market access and credibility. The global sector is consolidating quickly and Canadian innovators must determine whether or not to build on this momentum with their own regulatory clarity.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
BNPL | June 17, 2025
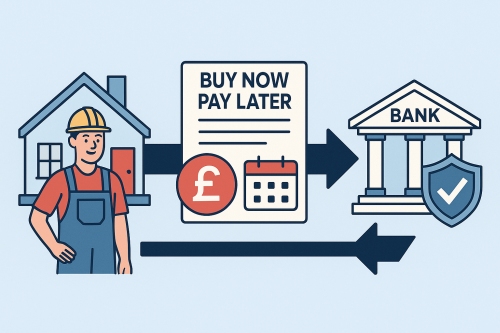
On June 16, 2025, the UK HM Treasury published a policy update that says 'domestic premises suppliers' (aka door to door vendors or companies that provide goods or services in a customer's home) no longer need to be licensed as credit brokers to offer Buy Now Pay Later (BNPL) services. The change to BNPL regulation is aimed at supporting smaller businesses without weakening consumer protections. This exemption includes services like home improvement consultations, kitchen installations, in-home services like cleaning or fitness, or any other sale that takes place during a visit to the customer's home.
Many industry stakeholders warned that requiring a credit broker license for these types of businesses isn't necessary and overly burdensome. The government agreed because these in-home suppliers do not offer financial services as their primary business activity. Instead, the typically introduce customers to a single BNPL lender as part of a product or service sale. Additionally, regulators realized that the risk of consumer harm in these cases is relatively low since the financial exposure sits with the BNPL lender who is regulated, not the seller, and felt that requiring small businesses to apply and maintain broker requirements is disproportionate to their role.
While the sellers are now exempt, BNPL lenders will still be fully regulated under the new rules, and must perform creditworthiness and affordability checks and comply with FCA Consumer Duty requirements. They must also ensure that purchases made using BNPL are protected under Section 75 of the Consumer Credit Act 1974, and that customers have access to the UK’s Financial Ombudsman Service to address complaints.
The full BNPL regulatory framework in the UK is expected to come into force by mid-2026, including secondary legislation to implement the exemption for in-home sellers.
Canada doesn't currently have a dedicated national BNPL regulatory framework. It also doesn't require BNPL sellers to have a credit-brokering license. The Financial Consumer Agency of Canada (FCAC) continues to monitor the sector but doesn't directly regulate BNPL lending. Oversight is through a mix of provincial consumer protection laws and federal rules related to money laundering and data privacy.
In Ontario as an example, BNPL offerings must comply with the Consumer Protection Act, which requires clear disclosures and restricts misleading marketing. If a provider handles payments, they may also need to register as a money services business under federal law.
As BNPL continues to grow, pressure is building for regulators to provide clearer guidance. The UK’s model may offer a useful reference for policymakers looking to balance access to BNPL services while protecting Canada's evolving credit sector.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016