




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


M&A | Aug 29, 2025

Image: Freepik/zaozaa09
As reported on Aug 28, 2025 by the Investment Executive, Desjardins buys Guardian for $1.67 billion in an all cash deal that boosts scale, fintech investment, and global ambitions. It's one of the largest Canadian asset management deals in years. Priced at $68 per share, combines about $280 billion in assets under management and advisement, and is expected to close in early 2026 pending shareholder, court, and regulatory approvals.
The deal creates a stronger national player with greater resources and market reach. For financial professionals, size matters. Larger firms can spread compliance costs, expand distribution, and withstand market volatility. Mid-sized managers will feel pressure. Some may seek mergers. Others may need to specialize in niche strategies to stay competitive.
Guardian CEO George Mavroudis will lead the new firm. The leadership continuity provides stability and a clear path forward. With greater scale, Desjardins can challenge both domestic players and global firms targeting Canadian clients. For smaller firms, competition will tighten. Larger firms are better positioned to absorb costs and push new products.
Scale gives Desjardins-Guardian room to invest in technology. AI portfolio tools, robo-advisors, and digital wealth platforms will likelycontinue to expand. This opens space for fintechs that can deliver specialized tools or integrate into broader platforms. Partnerships are not new for Desjardins. Its joint venture in Aviso Wealth and its 2022 purchase of Guardian’s Worldsource businesses for about $750 million show a consistent approach of combining acquisitions with collaborations to build reach and capability.
Guardian’s international presence gives the new platform more reach outside Canada. International products can be scaled more effectively, especially in ESG, which already accounts for the majority of Canadian managed assets.
Institutional demand for sustainable finance is rising, and the combined firm can now deepen its offerings. Alternatives and private credit strategies are also likely to expand, appealing to both domestic and global investors.
Industry consolidation has surged in 2025, and Desjardin's acquisition of Guardian Capital is the clearest sign that Canadian managers are building the scale to compete globally. The timing matters. With inflation, compliance costs, and economic uncertainty, firms with bigger reserves and wider distribution networks are better placed to grow.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
AI Partnership | Aug 29, 2025

On August 28, 2025, IG Wealth Management and Canadian fintech interVal announced a new partnership to help small and medium business owners measure company value and identify opportunities for growth. The collaboration strengthens IG’s advisory network by embedding interVal’s AI driven valuation platform into client planning services, providing advisors with richer insights to guide strategic decisions.
Over the past year IG advisors have been using interVal’s software to deliver business valuations and health metrics that go beyond traditional reporting. The platform produces valuation ranges, saleability scores, and benchmarks on areas such as excess working capital, serviceable debt, and investable assets. These insights allow advisors to offer more proactive strategies for investment, credit, insurance, and succession planning, covering both business and personal wealth needs.
Damon Murchison, President and CEO, IG Wealth Management:
"Through the interVal platform, clients receive an accurate business valuation and tools to uncover what's driving, or impeding, their business value. This partnership further cements our commitment to serving business owners and helping them build better financial futures."
Founded in London Ontario, interVal was created to close the information gap between advisors and business owners. The company combines artificial intelligence, machine learning, and natural language processing to transform financial data from systems like QuickBooks and Xero into clear valuation analysis and growth indicators.
The platform is designed as a shared environment where both advisors and business owners can track value drivers, monitor benchmarks, and anticipate how changes in performance affect long term outlook. interVal’s culture emphasizes empathy, collaboration, and building tools that make advisory conversations more strategic and forward looking. Its leadership team blends expertise in finance, valuation, customer success, and technology to ensure the platform aligns with the needs of financial professionals and their clients.
The integration of interVal into IG’s services brings modern valuation technology to a national network of advisors serving nearly one million clients. With IG managing approximately $148.4 billion in assets under advisement as of July 31, 2025, the reach of this partnership has the potential to influence financial planning practices across Canada.
For small and medium business owners, the benefits are practical and beneficial. Instead of relying on static valuations or fragmented financial reports, they can now access dynamic assessments that reveal what is helping or hindering company value. This improves decision making on growth investments, cash management, and risk protection while also informing personal wealth strategies tied to the business.
The IG and interVal partnership highlights how fintech innovation is proliferating across advisory networks in Canada. As interVal’s AI powered tools scale within IG’s national network, more entrepreneurs will be able to plan with greater clarity and foresight. This improves the competitiveness of Canadian business owners and also strengthens the ability of financial advisors to deliver relevant and modern services (win-win for both parties).
Advisory practices are increasingly supported by real time data, predictive analytics, and shared insight platforms. By embedding fintech solutions like interVal, large financial institutions such as IG Wealth Management are setting new standards for integrated planning and business growth support.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Competition | Aug 28, 2025
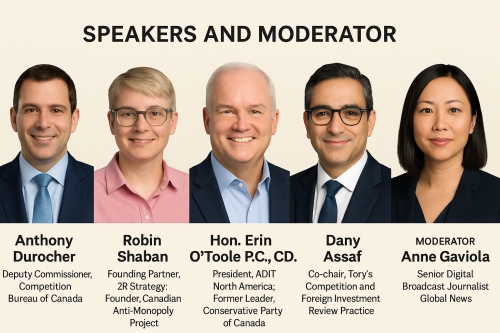
On October 8, 2025, the Rotman School of Management will host an in person debate on one of the most contested questions in Canada’s economy: Are Canada’s so called oligopolies standing in the way of a dynamic Canadian economy?
This debate is at the heart of whether concentrated industries in banking, telecom, airlines, and grocery are reducing competition and consumer choice or whether a few large firms are needed to sustain investment in a relatively small market.
Host: Rotman School of Management
Rotman Debate: Are Canada's So-Called "Oligopolies" Holding Us Back?
Date: October 8, 2025
Time/venue: 6:00 PM to 8:00 PM at Desautels Hall
Agenda: Live in-person debate followed by a networking reception
Anthony Durocher, Deputy Commissioner of the Competition Bureau, and Robin Shaban, economist and founder of the Canadian Anti Monopoly Project. They bring a competition policy and inclusive growth lens, pressing the case that concentration stifles productivity and affordability.
They will likely emphasize how concentrated markets in banking, telecom, grocery, and airlines restrict consumer choice, keep prices high, and hurt innovation. Both have deep expertise in competition policy, which will resonate with Canadians worried about affordability, productivity, rising costs, and declining foreign direct investment.
Erin O’Toole, former Leader of the Conservative Party and now President of ADIT North America, and Dany Assaf, co chair of Torys LLP’s competition and foreign investment practice. Their case focuses on the role of scale in driving resilience, capital inflows, and global competitiveness.
Expect them to argue that scale is necessary in Canada’s small market to attract global investment, maintain resilience, and provide stability. O’Toole brings political credibility and public speaking skills, while Assaf brings legal and transactional expertise from landmark competition cases.
The debate will be moderated by Anne Gaviola, senior broadcast journalist at Global News, who has more than 15 years covering Canada’s business and financial sectors.
For the NCFA Canada, this debate could not be more timely. The structure and size of Canada’s markets and levels of competition directly affects opportunities for new entrants in fintech and alternative finance. Concentrated industries can create barriers to entry. With productivity and affordability now central to Canada’s policy agenda, the insights from this debate will be directly relevant for startups, investors, and regulators. This is a ticketed event. Register now to secure your spot.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
M&A | Aug 28, 2025
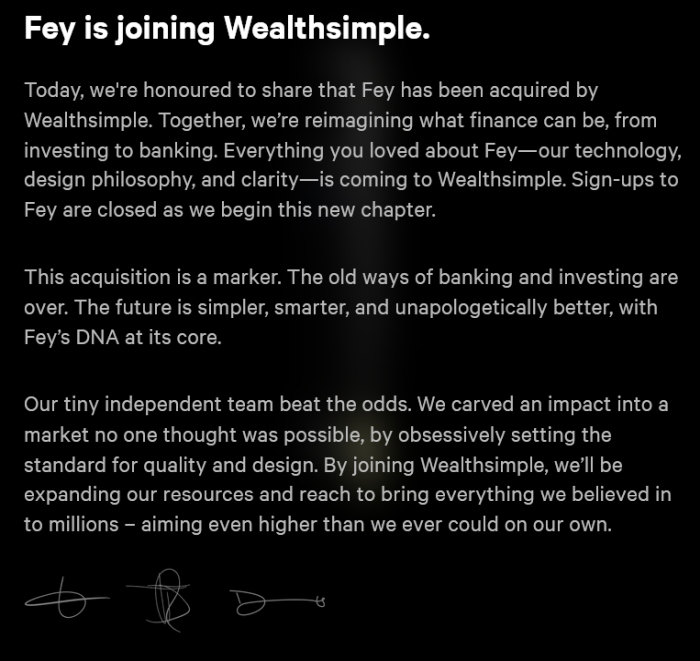
Image: Fey is joining Wealthsimple
On August 27, 2025, Wealthsimple announced the acquisition of Fey, a Montreal-based investment research startup founded in 2021 that built its reputation on elegant design and advanced AI trading tools. The financial terms of the deal weren't disclosed but it puts Wealthsimple in a position to offer millions of Canadians an enhanced trading experience, bridging the gap between simple apps and a more complex brokerage platform.
Wealthsimple now serves more than 3 million clients and manages over $84 billion CAD in assets, a 94% increase from the previous year. Earlier in 2025, Wealthsimple acquired San Francisco based platform Plenty, a wealth management platform for couples, as part of its strategy to expand capabilities and scale faster.
Fey emerged from the Montreal design studio Narative, founded by Thiago Costa, Dennis Brotzky, Thomas Russell, and Mack Mansouri. The team built Fey strategically with early venture backing from Maple VC, Inovia Capital, Yuri Sagalov of Wayfinder, and Abhinav Tiwari of Blank Ventures. Instead of a splashy launch, Fey garnished trader feedback on an invite-only access basis, which helped them refine features such as natural language stock screening, real-time earnings summaries, and a personalized news feed. Features that will soon become part of WS's self-directed investing platform.
As reported by BetaKit, Fey’s co-founders Costa, Brotzky, and Russell will join Wealthsimple’s self-directed investing group, and the Fey platform will shut down by September 30, with subscribers being refunded for any remaining balances.
For Wealthsimple’s 3 million clients, here's a look at how the integration of Fey's platform design and features will turn complex investing workflows into intuitive actions:
On Reddit, an early user described Fey as providing “a much nicer UI, the ability to sync portfolios across institutions, and quick access to key metrics when I didn’t have time to dig for them”.
Wealthsimple is aiming to create an all-in-one financial platform covering investing, trading, crypto, tax filing, and everyday banking services. Adding Fey’s research and design-first tools will help attract a younger generation of investors while strengthening its position against traditional brokerages and newer fintech challengers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto | Aug 28, 2025
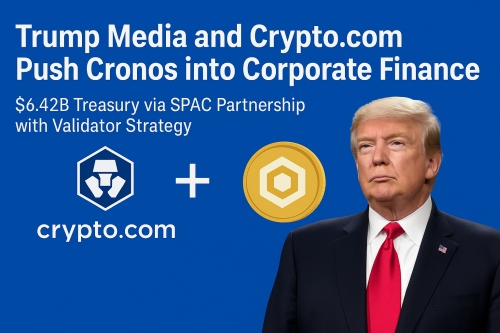
On Aug 26, 2025, the Trump Media & Technology Group, Crypto.com and Yorkville Acquisition Corp (SPAC). announced the launch of Trump Media Group CRO Strategy Inc., a new treasury firm designed to acquire, hold and actively manage large reserves of the Cronos token (CRO).
Devin Nunes, CEO of Trump Media, said:
“We continue to be bullish on cryptocurrency, and we are excited to be partnering with a leading global cryptocurrency platform and namesake of its industry in Crypto.com and one of the most sophisticated investor groups in Yorkville for this strategic initiative.”
The company will go public on Nasdaq under the ticker MCGA. The venture combines 6.3 billion CRO tokens valued at $1 billion (approx 19% of supply)+ $200 million in cash + $220 million in warrants + $5 billion equity line of credit from a Yorkville affiliate YA II PN. In total,$6.42 billion in committed resources.
Trump Media will also buy $105 million worth of cronos for its balance sheet, and Crypto.com has agreed to invest $50 million into Trump Media stock.
All told, the deal will be the first and largest publicly traded CRO treasury company and what is being described as the largest deal ever when compared to the total size of the token’s market. The business combination is being reinforced by a mandatory 1 year lock-up and 3 year release schedule on founding shares. See Form 8-K filing.
Kris Marszalek, CEO of Crypto.com, said:
“The sheer size and structure of this project will encompass more than the entire current market capitalization of CRO … this, combined with share lock-ups by each party and the treasury’s validator strategy, make it a unique and compelling offering compared to all other digital asset treasuries.”
Markets reacted immediately. Cronos spiked nearly 30% in the hours after the news (currently trading at $0.3205 on CoinGecko), while Trump Media’s stock rose 5% to $18.11. Yorkville shares fell 2.4% on the day of the announcement. This is another massive deal for crypto and boost for corporate crypto treasury strategies.
One of the most distinctive aspects of the venture is its validator strategy. Trump Media Group CRO Strategy will establish and operate a validator node on the Cronos network, delegating CRO under management to that node. This allows the company to directly participate in the security and governance of the blockchain while generating native staking rewards that will be reinvested to grow CRO holdings and offset operational expenses.
AP reported that “the Trump family is expanding its crypto empire,” adding to a series of projects that include a proposed bitcoin ETF and a $2 billion bitcoin reserve. With the White House progressing friendly crypto policies, this venture shows how closely aligned political influence and corporate strategy can be, which raises conflict of interest and transparency questions, as Trump’s family business benefits directly from a favourable regulatory climate.
The United States is moving fast with token-backed treasury vehicles and SPAC-financed listings, while Canada’s regulatory approach has been slower and more cautious. In Canada, a deal structured as a SPAC merger with a crypto corporate treasury at its core would likely not pass regulatory muster today.
That's a competitive gap. If American firms can put tokens on their balance sheets, raise capital through SPAC mergers, and connect those tokens to consumer platforms, they can innovate at a scale in a way that Canadian firms cannot match.
The question for Canada is whether to stay on the sidelines or to create the right framework for safe experimentation. That could mean regulatory sandboxes for token-based treasuries, pilot programs to test new structures, or clearer rules that give firms confidence to innovate. Without these kinds of steps, Canada risks falling further behind (skilled jobs, innovation and global capital flows) as U.S. firms set the pace in crypto finance.
The Trump Media and Crypto.com deal is an experiment to see if a token like cronos can play the same role in corporate reserves that bitcoin has for MicroStrategy. Investors jumped in quickly, but the approach still comes with the risks of big price swings and political baggage.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 27, 2025
Image: Freepik AI
Canada is preparing for the launch of “Consumer-Driven Banking” in early 2026. This promises to be a system that will give people more control over how their financial data is shared. The main goal is to replace current risky practices, including screen scraping, with safe, consent-based data exchange. The government has made it its aim to focus on trust, clearer guidelines and regulations, to provide a system where security comes first, while still encouraging innovative services.
For more than 30 years, Interac has been the foundation of Canada’s payment system. The payment gateway is well-known for debit payments, ABMs, and the popular e-Transfer service. In 2024, Canadians sent more than one billion e-Transfers, transferring more than $132 billion.
The reach of Interac extends further than banks and credit unions. Its services are also used in online services. For instance, with online casino platforms, players rely on the same fast and trusted payments they use with their bank. The payment option allows players to access the same bonuses, gaming library, and promotions whether they use an e-wallet, cryptocurrencies, or traditional banking methods. With Interac e-transfer casinos, players can expect a fast, convenient, and highly secure way to fund their accounts with strong protections against fraud and theft.
Additionally, Interac is widely accepted for online purchases in Canada because it supports secure direct payments through Interac Online or Interac e-Transfer, which many online merchants and platforms integrate. This widespread trust and familiarity with Interac in everyday payments reflects the confidence Canadians place in its security and convenience. This acceptance and reputation for safe transactions make Interac an ideal foundation for supporting the secure, consent-based data sharing envisioned by Canada’s open banking framework
Interac already connects banks, credit unions, payment processors, and more than 1.4 million point-of-sale terminals across the country. It also has significant experience with APIs, tokenization, and authentication, which are exactly the kinds of tools that open banking requires.
Equally important is Interac’s reputation for security. With three decades of experience, Interac has well-established governance frameworks, security protocols, and operational standards. These can easily be adapted and extended to open banking APIs to accelerate compliance and risk management processes.
Standardized APIs are central to consumer-driven banking. Interac has already been running pilot projects with dozens of third-party providers that want to connect directly to financial data. The network includes shared services that are vital for open banking, such as identity verification, consent management, and secure data transfer.
It makes sense to use infrastructure that already exists. This could speed things up considerably. Instead of starting from scratch, Canada can build on a network that already processes millions of transactions every day. Interac’s reliability, low downtime, and widespread acceptance mean both banks and fintechs are more likely to support a model that is proven and trusted.
Interac’s experience helps reduce the time needed for open banking to become a reality. With ready-made standards and existing relationships across the financial sector, deployment can move faster than in countries that had to build new systems entirely. This is significant, given that the federal government has set early 2026 as the target date.
Interac also works closely with regulators. It advises on governance, security, and consumer protection, and it has teamed up with fintech incubators to test new applications in controlled environments. The focus has been on creating clear, transparent consent processes for consumers, ensuring people understand and control how their data is used.
In 2025, important steps were taken to prepare for rollout. Despite mixed reactions and backlash, Parliament passed legislation requiring accredited entities to use secure APIs, annual consent renewal for data sharing, and oversight by the Financial Consumer Agency of Canada. Major banks, including RBC and TD, continued expanding their API systems and entered new partnerships with fintechs to test services ahead of the launch.
Interac, for its part, strengthened its focus on fraud prevention. The appointment of David Bruyea as Group Head of Financial Crimes signalled an investment in protecting the system at a time when trust will be vital. With consumers still learning what consumer-driven banking means for them, Interac is positioning itself as the trusted partner that can balance innovation with security. Its long-standing role in Canadian finance, paired with ongoing developments in 2025, places it at the centre of the country’s move toward open banking in 2026.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI | Aug 26, 2025
Image: Freepik
On Aug 25 2025, Perplexity announced the launch of Comet Plus, a $5 per month subscription service that commits to paying 80% of revenue to publishers while Perplexity retains 20% for compute and platform costs. The company has allocated a $42.5 million pool to start the program.
Aravind Srinivas, Perplexity CEO hits the nail on the head:
“AI is helping to create a better internet, but publishers still need to get paid.”
The launch comes as Perplexity faces mounting legal and reputational pressure. Media companies including News Corp, Forbes, and Condé Nast have accused Perplexity of unauthorized use of their journalism. By offering direct revenue, the company is positioning itself as a collaborator rather than an adversary.
The launch also represents an evolution from Perplexity’s earlier Publisher Program announced in 2024. That program partnered with outlets like Time, Der Spiegel, and Fortune, sharing ad revenue and offering free developer tools, however payout percentages were lower and less transparent. Comet Plus is aiming to scale with openness.
Perplexity defines three categories of traffic that qualify for payouts:
1. Human traffic means direct visits to publisher program content.
2. Indexed traffic means AI citations or synthesized use of publisher content in answers.
3. Agent traffic means tasks completed by the Comet Assistant using publisher material.
Comet Plus subscriptions cost $5 per month, with Pro and Max tiers including access automatically. In September 2024 Perplexity processed 350 million user queries, showing the scale of demand.
For publishers, the model offers a new and potentially recurring revenue stream tied to the actual use of their work (different than relying on traffic referral triggers). For fintech innovators, Comet Plus demonstrates how programmable revenue sharing tied to verifiable usage can enable micropayments and real-time attribution systems. For policymakers, Comet Plus is a test case for AI compensation models that could reduce litigation and support fairer AI-publisher frameworks.
There are questions about scalability though. The $42.5 million pool is significant but could quickly be depleted as content consumption is growing quickly. Subscription adoption will need to keep pace for the model to deliver meaningful returns.
Another issue is equity. Larger media brands might capture the majority of rewards, while smaller publishers see little benefit unless Perplexity ensures diverse citation and equitable weighting. Transparency in reporting will be key to monitoring the balance and maintain trust with stakeholders.
Perplexity frames the program as part of building a better internet and ensuring creators are compensated in the AI age. If successful, it could set a precedent for AI companies globally.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016