




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Sep 11, 2026
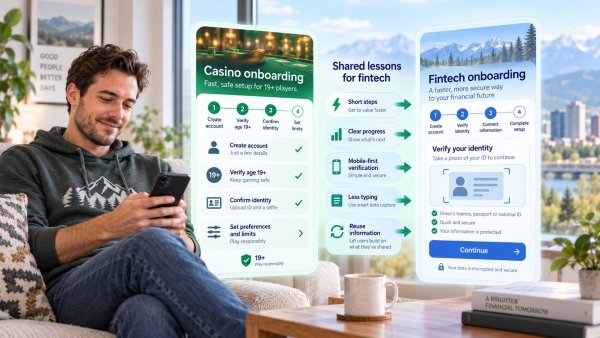
A new user does not care how many systems sit behind a sign-up screen. They care about something much simpler: how quickly can they get started?
That question matters for Canadian fintechs in 2026. Consumer-driven banking is moving forward, digital identity tools keep improving, and people are growing used to services that feel immediate on a phone.
The lesson is not to remove important checks. It is to make those checks feel like a natural part of the product.
Regulated gambling offers an interesting UX lesson because account creation has several moving parts. User details need to be collected, identity has to be confirmed, and the whole process needs to work smoothly on a small screen.
What stands out is how much of that complexity can stay behind the interface.
A person creating an account at Betinia Ontario (19+), for instance, moves through a digital registration journey where account details and verification form part of the same experience. For a user, that matters. The process feels connected rather than split into separate administrative steps.
Canadian fintechs can borrow that thinking.
Ask for information when it becomes relevant. Keep each screen short. Tell the user why a document or detail is needed. Show progress without filling the screen with technical language.
Little things add up.
Identity checks used to feel separate from the main product experience. You signed up, then got pushed into another process.
That distinction is disappearing.
Canada already allows several forms of remote identity verification under federal guidance. Phone cameras, document checks and digital records can turn what was once a desk-based process into a mobile interaction.
For product teams, this changes the design question.
Instead of asking, “Where do we put verification?”, it may be more useful to ask, “How do we make verification feel natural?”
The answer often comes down to interface details. A clear camera prompt is better than a paragraph of instructions. A progress bar can reassure someone that only a few steps remain. Pre-filled information can remove needless typing.
None of this sounds revolutionary. That is partly the point. Good onboarding often feels simple because somebody did the complicated work behind the scenes.
There is another lesson worth stealing: people dislike repeating themselves.
If a customer has already supplied a name, address or account detail, asking for it again creates a strange little pause. It feels as though two parts of the product are not talking to each other.
Fintech teams can remove much of that friction by designing onboarding as one continuous conversation.
Information should move with the user. Screens should remember what came before. Permissions should appear at the moment they make sense.
Think of it as good hospitality. If someone has already introduced themselves, you do not ask their name again five minutes later.
Digital products should show the same basic courtesy.
The timing is especially relevant for Canadian financial services.
Canada has been moving ahead with its consumer-driven banking framework, which is designed to give consumers more control over how their financial data is shared between approved services. The country is also preparing for faster payment infrastructure through the Real-Time Rail.
These developments point toward a more connected financial experience.
As secure data sharing becomes easier, onboarding could involve less manual entry. A customer may be able to authorize access to information that already exists rather than filling out another long form.
That changes expectations.
If money and data can move quickly, opening an account should not feel stuck in an older era of paperwork and repetitive fields.
Onboarding is often discussed as a conversion metric. For fintechs, it is much more than that.
It is the customer’s first real experience of the company.
A clean flow says the product is organized. Clear explanations show respect for the user’s time. A short series of well-designed steps makes complicated technology feel manageable.
That first minute can set the tone for everything that follows.
Canadian fintechs do not need to copy the gambling sector itself. The useful lesson sits in the product mechanics: short steps, mobile-first verification, clear progress, smart reuse of information and fewer unnecessary interruptions.
When those pieces work together, onboarding almost disappears.
And that may be the best sign that it has been designed well.
Online gambling in Ontario is restricted to those 19+. Support resources: ConnexOntario, 1-866-531-2600.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
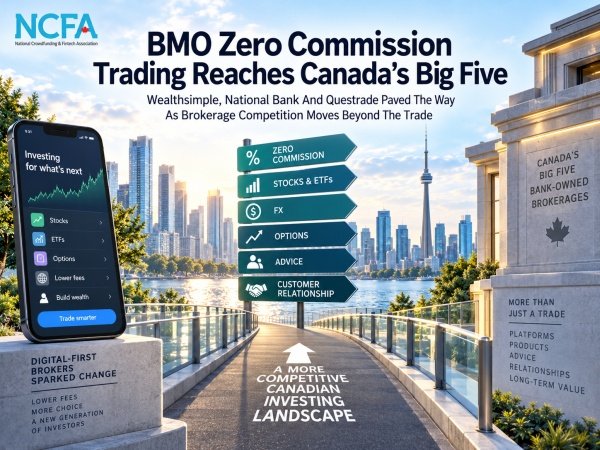
On September 9, 2026, BMO InvestorLine announced unlimited zero commission trading on stocks and exchange traded funds for all self directed clients. The pricing takes effect September 14. BMO is also removing brokerage account administration fees and cutting options pricing to zero base commission plus $0.90 per contract, down from $1.25.
BMO says InvestorLine is the first direct investing brokerage owned by one of Canada’s five largest banks to eliminate commissions across stock and ETF trades. That’s important, but it isn’t where Canada’s zero commission story begins. Wealthsimple had already made free stock trading a consumer proposition in 2019. National Bank and Desjardins followed in 2021. Questrade took its remaining stock and ETF commissions to zero in 2025.
What BMO changes is where the pressure has reached. A trading fee that survived for years inside Canada’s largest bank owned brokerages is now disappearing at one of them.
BMO is not the first Canadian financial institution to offer zero commission trading. It is the first of the Big Five to make unlimited zero commission stock and ETF trading its standard self directed price.
That leaves a more interesting question than who cuts next. If the trade itself costs nothing, what are Canada’s brokerages really competing to win?
In March 2019, Wealthsimple Trade opened zero commission investing to Canadians. Wealthsimple said most Canadian trading services were charging roughly $5 to $10 per trade at the time.
The proposition was easy to understand. Buy or sell a stock and the headline commission was zero.
Low cost online brokerage was already well established in Canada. Questrade had been competing with bank owned brokers since 1999 and spent years cutting the cost of self directed investing.
Wealthsimple changed the reference price. Instead of asking whether a digital broker was cheaper than a bank, customers could ask why a stock trade needed a commission at all.
Discount brokers already make trading cheaper. Wealthsimple makes zero easy to see, easy to compare and available through a mobile app. Every brokerage still charging by the trade now has a much simpler price to compete against.
Canada wasn’t developing in isolation. Robinhood began building its U.S. brokerage around commission free trading in the 2010s.
By October 2019, the pressure had reached the largest American brokers. Charles Schwab cut its US$4.95 online stock commission to zero. TD Ameritrade, E*Trade, Fidelity and others followed.
Those decisions weren’t cosmetic. When E*Trade announced zero commissions in 2019, it estimated the change would reduce revenue by roughly US$75 million per quarter.
Brokerage shares fell sharply as investors worked out what a disappearing transaction fee meant for firms that had relied heavily on commissions.
Robinhood shows that free trading can pull customers toward a new platform. The U.S. incumbents show what happens when enough customers begin expecting the same price. Canadian brokerage economics are different, but the competitive pressure travels.
The first Canadian bank owned brokerage to go all the way wasn’t BMO.
On August 23, 2021, National Bank Direct Brokerage eliminated commissions on online Canadian and U.S. stocks and ETFs.
National Bank called it a Canadian first for a bank owned direct broker. Its previous standard commission had been $6.95.
National Bank was unusually clear about the business logic.
Martin Gagnon, then Executive Vice President of Wealth Management, said “The objective is very simple. It’s to increase our client base.”
National Bank’s securities brokerage commission line was about C$60 million for the quarter, but management said only a very small fraction of that amount was at risk from the direct brokerage pricing change. Transaction revenue had already become a smaller part of the business.
National Bank proves that a Canadian bank owned brokerage can give up the visible trading fee when gaining customers, assets and other business is worth more.
Desjardins also removed online stock and ETF commissions in 2021.
By January 2026, Desjardins Online Brokerage reported C$30 billion in assets under administration. Assets had climbed 80% over four years and the number of platform and mobile app users had increased 30%.
Zero commissions alone didn’t produce those gains. They do show that the model can operate at meaningful Canadian scale.
Questrade took the pricing question further in February 2025 when it removed online stock and ETF commissions across its self directed accounts.
By 2026, the company reported more than C$80 billion in assets under administration and was extending well beyond basic trade execution. Questrade Connects Brokerage Accounts To AI Agents follows its expansion from lower cost trading into personalized portfolios, banking and agent accessible investing.
The commission is gone, but the platform has more products to sell.
A customer who arrives to buy a stock can also hold cash, borrow, use managed portfolios, buy private assets, open banking products or use new investing tools. That makes the account itself more valuable than the fee on an individual trade.
BMO now brings unlimited zero commission trading inside the Big Five.
Immediately before the announcement, its standard InvestorLine price was $9.95 per online stock trade. A customer making 100 commissionable trades a year could spend about $995 on those commissions.
At 250 trades, the amount was roughly $2,487.50. At 500, it reached $4,975.
The other Big Five brokerages aren’t standing still, but their standard offers remain different.
TD Direct Investing lists a standard stock commission of $9.99. RBC Direct Investing lists $9.95 for its full brokerage offer, while GoSmart includes a limited number of free trades. CIBC Investor’s Edge lists $6.95 for standard online equity trades and offers commission free ETFs. Scotia iTRADE lists a standard equity commission of $9.99, with some Scotia banking packages including a limited number of free trades.
National Bank gets there five years earlier. BMO matters because unlimited zero commission stock and ETF trading now reaches one of the institutions at the centre of Canadian banking.
Zero commission doesn’t mean zero cost.
BMO says it can earn 1.6% on currency conversions below US$25,000, with the percentage declining as the transaction gets larger.
A US$10,000 conversion at 1.6% works out to US$160. That is far larger than the $9.95 stock commission that disappears.
The same calculation matters across the industry. Wealthsimple lists a 1.5% foreign exchange fee on applicable Canadian dollar and U.S. dollar conversions.
Brokerages can also earn revenue from options, margin borrowing, subscriptions, interest, advisory services, managed portfolios and other financial products.
A $0 order therefore tells investors the cost of the trade. It doesn’t tell them the total cost of using the brokerage.
The brokerage can give up the transaction fee because customer assets create other opportunities. Currency gets converted. Cash stays on the platform. Some investors borrow, trade options, buy managed products or add other financial services.
Wealthsimple makes the strategy especially visible. What began with investing now stretches across cash, cards, tax, mortgages, private investments, crypto and other financial products.
Its growth also shows the scale challengers can reach. By early 2026, Wealthsimple said it served more than 3 million Canadians and had passed C$100 billion in assets under administration.
BMO starts from the opposite direction. It already has banking, lending, cards, advice and wealth management. Taking the trade commission to zero gives an existing bank another way to keep self directed investors inside a much larger financial relationship.
That makes BMO’s decision more than a brokerage price cut. A digital challenger can use cheap investing to enter the relationship. A large bank can use the same price to defend one it already has.
BMO removes one of the easiest price differences for investors to compare. Brokerages now have to win on total cost, foreign exchange, options, margin, tools, advice, product access and how much of a customer’s financial life they can serve.
BMO’s zero commission pricing follows years of pressure from discount brokers, fintechs and earlier bank competitors. Once the stock trade costs nothing, the bigger prize is the customer, their assets and the rest of their financial relationship.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |
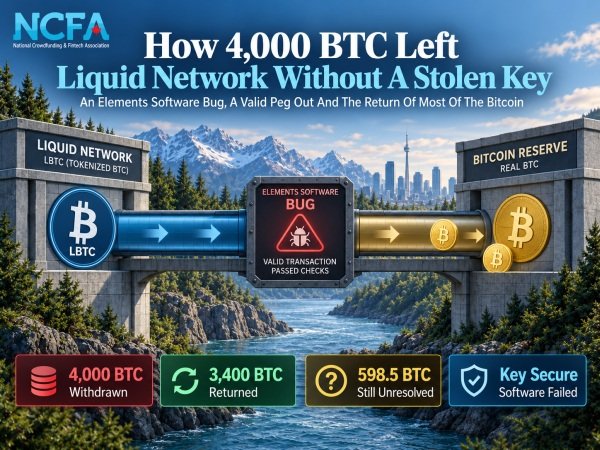
On September 6, 2026, the Liquid Network reported a 4,000 BTC withdrawal from the Bitcoin backing its sidechain. The bitcoin was worth about US$320 million when the incident was disclosed and represented roughly 95% of the approximately 4,200 BTC then reported in the federation wallet.
The size alone made it one of the year's most consequential digital asset security incidents. The mechanics made it stranger. SideSwap says the authorization key used in the peg out was not compromised. Instead, the 4,000 LBTC submitted for redemption was later attributed to a bug in Elements, the software underlying Liquid.
Most of the bitcoin has since come back. On September 7, the withdrawing party returned 3,400 BTC after an unusual onchain exchange with Blockstream over the software patch. Roughly 598.5 BTC, worth about US$47 million on September 8, remained at the withdrawal linked address when this Story was prepared.
Nearly an entire reported Bitcoin reserve left through an apparently valid redemption process even though the authorization key itself had not been stolen.
Protecting private keys is essential. Liquid's incident shows why the software deciding which assets are valid can matter just as much as the cryptography authorizing their redemption.
Liquid is a Bitcoin sidechain. Users lock bitcoin and receive LBTC that can circulate on Liquid before being redeemed back into bitcoin.
Before the incident, reporting put the federation wallet at roughly 4,200 BTC. About 4,000 BTC left during the withdrawal, putting almost the whole reported reserve behind one incident.
The response was immediate. Liquid activity was paused, bridge nodes were disabled and exchanges were asked to suspend LBTC deposits and withdrawals. SideSwap also stopped swaps, peg ins and peg outs.
That bought developers time to work out how such a large redemption had been accepted before normal bridge activity continued.
A stolen withdrawal key would have provided a familiar explanation. SideSwap says that didn't happen. The service processed a valid authorization, which pushed attention back toward the LBTC that entered the redemption process.
SideSwap says 4,000 LBTC was sent to its peg out service. The service burned the tokens against a valid authorization, after which the Liquid Federation released roughly 3,996 BTC to a Bitcoin address.
SideSwap says neither its systems nor its Peg out Authorization Key was compromised.
The crucial discovery came afterward. According to the account of the investigation, Blockstream determined that the LBTC involved had been created through a bug in Elements.
Elements is the open source software on which Liquid runs. The failure therefore appears to have happened before the final Bitcoin redemption rather than through theft of the SideSwap authorization key.
The peg out machinery can receive a valid authorization and release real bitcoin while the LBTC entering that process has already been corrupted by a software failure. Securing the key is necessary. It doesn't cover every route to an invalid redemption.
Then the incident took an unusual turn. The withdrawing party described itself as white hat and began communicating through messages recorded on Bitcoin.
Blockstream contacted the party through an onchain transaction. The party later told Blockstream to fix the bug and make sure the relevant nodes were patched before the bitcoin would be returned.
The white hat description remains the party's own characterization. It isn't an independently established status.
Blockstream later sent an authenticated message saying its bridge nodes had been patched. The response was followed by a transaction returning exactly 3,400 BTC to the federation address.
That recovered about 85% of the withdrawn bitcoin. The same transaction left approximately 598.5 BTC at the withdrawal linked address.
Neither Blockstream nor Liquid had publicly identified that remaining bitcoin as an agreed payment when this Story was prepared.
A party controlling hundreds of millions of dollars in bitcoin communicates with the infrastructure provider through the blockchain itself, waits for a software repair and then returns most of the funds. It's an extraordinary sequence, but it doesn't establish that the original withdrawal was authorized or benevolent.
Independent security researchers have begun explaining how the Elements failure may have happened.
CertiK's incident analysis points to Elements' handling of rangeproof verification caching. Its reconstruction says a flaw could allow different validation contexts to share a cached result and cause invalid value to be accepted.
That could explain how LBTC that shouldn't have been valid reached the peg out process.
The technical analysis is developing faster than the official explanation.
Blockstream hadn't published a complete technical postmortem when this Story was prepared. The exact affected software versions, complete code path, deployment history and remediation therefore aren't settled yet.
The confirmed finding is narrower and important enough on its own. Blockstream identified an Elements software bug as the source of the LBTC involved in the withdrawal, according to SideSwap's account.
When a token represents an underlying financial asset, software validation becomes part of the reserve control. If the system accepts an asset state it should reject, that mistake can become a claim on real assets even when the keys protecting them remain secure.
The size of the withdrawal makes that connection hard to miss. Roughly 95% of the reported bitcoin reserve was involved before most of the funds came back.
That doesn't mean Liquid permanently lost 95% of its backing. It means a software failure produced a redemption event large enough to put almost the entire reported reserve into question at once.
For digital asset firms, reserve security therefore extends well beyond storing keys.
Supply verification, transaction validation, reserve reconciliation, withdrawal monitoring, circuit controls and incident response all become part of the same operating problem.
That same issue appears in how crypto custody regulation is changing, as the market moves beyond simply holding private keys toward segregation, authority, resilience and accountability.
A secure key can't compensate for software that accepts an asset state it should reject. Issuance, validation, reserves and redemption all have to work together because a failure in one can reach the value protected by another.
Liquid's federation also gave operators a practical advantage during the response. Identifiable participants could coordinate, stop infrastructure, patch bridge nodes and prepare a restart.
That can make emergency intervention faster. It also means federation governance and operating procedures are part of the security model rather than something separate from it.
The same problem gets more important as financial institutions put securities, funds, deposits and other assets onto programmable infrastructure.
Tokenization becoming a business investors can measure captures the commercial side of that development. Liquid exposes the other requirement. Redemption and reserve systems still have to work when software doesn't.
Returning 3,400 BTC dramatically reduces the financial exposure, but it doesn't explain why nearly the whole reported reserve could leave through one sequence or what now prevents a recurrence. Those answers will determine whether this remains a contained software failure or becomes a longer trust problem for Liquid.
Liquid's authorization key reportedly held. Its validation software didn't. Nearly 4,000 BTC still left before most of it came back, showing why tokenized asset security depends on much more than protecting the keys that authorize redemption.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 8, 2026
Futures trading strategies are repeatable plans for entering, managing, and exiting a leveraged contract. The useful strategy is not the one with the most indicators; it is the one whose market condition, trigger, invalidation, position size, and exit process are clear before an order is placed. Leverage can increase exposure without improving the odds of being right, so risk design matters more than a dramatic setup.
This guide is for readers who want a structured way to compare futures approaches before using real capital. It focuses on decision rules, operational checks, and failure modes. It does not issue trade calls, promise returns, prescribe leverage, or give a universal stop-loss or position-size threshold. Futures may not suit every reader, and product rules differ by venue and jurisdiction.
A trading idea becomes a strategy only when it can be tested before and after execution. At minimum, write down the market condition, entry trigger, invalidation level, position size, and exit plan. If one of these is missing, the decision is often an opinion about direction rather than a repeatable method. The same framework underlies a practical guide to futures trading strategies: define the conditions and failure point before considering leverage.
| Strategy component | Question to answer before entry | Why it matters |
| Market condition | Is the market trending, ranging, or unusually volatile? | A setup can fail when the surrounding structure changes |
| Entry trigger | What observable event turns the idea into a trade? | Prevents entries based only on urgency or prediction |
| Invalidation | What price or condition shows the thesis is wrong? | Defines when the original premise no longer applies |
| Position size | How much can be lost if invalidation is reached? | Links exposure to the planned loss rather than available margin |
| Exit plan | How will profit, time, or changing conditions be handled? | Prevents improvisation after the position is open |
The order of operations matters. Start with the condition and invalidation, then calculate size. Choosing a large position first and searching for a stop later reverses the risk decision. A platform may show that a small margin requirement controls a large notional position; the account is exposed to the notional movement, not merely to the margin displayed on screen.
A trend pullback approach waits for a temporary move against an established direction and then looks for evidence that the original structure is resuming. Its central risk is mistaking a reversal for a pullback. Define the structure that must remain intact, such as a sequence of relevant highs and lows or a clearly observed support area. A price moving back toward that area is not enough on its own.
A breakout setup starts with a well-defined range or boundary. Instead of entering on the first move through the level, some traders wait to see whether the old boundary holds after the break. The retest can reduce the need to chase, but it also creates a second failure mode: price may continue without returning, or the apparent breakout may quickly fall back into the range. The rule should say what would count as acceptance, rejection, or no trade.
When price repeatedly turns inside a range, a range approach looks for entries near an edge and exits closer to the middle or opposite boundary. The premise fails when price accepts beyond the range. Range logic should not be applied automatically because a level held once or twice; the more often a boundary is tested, the more important it becomes to define what evidence would show the range is weakening.
Sometimes the strategy is to stay out. Scheduled data, funding settlements, contract expiry, technical outages, or thin liquidity can make fills and stops less predictable. Skipping a trade when the loss cannot be estimated is a valid risk decision, not a missed opportunity. A method that excludes uncertain conditions may produce fewer trades and a clearer review record.
The four families are not mutually exclusive, but mixing them without a written condition can create hindsight. A trader may call a position a breakout when it works and a pullback when it fails. Name the setup before entry so the result can be evaluated against the same rule.
Leverage changes the amount of exposure controlled with a given margin; it does not make a trade more likely to work. Estimated risk for a simplified linear contract can be represented as:
Position size x distance from entry to invalidation + expected fees and slippage
The formula is a planning aid, not a guarantee. Contract specifications, funding, mark-price rules, liquidation mechanics, and execution gaps can change the result. Check the venue's documentation and use assumptions that reflect the instrument rather than treating a generic calculator as precise.
Use a loss limit chosen before the trade and keep it separate from the platform's maximum leverage. The exact amount is personal and depends on capital, experience, and obligations; the important rule is that several losses should not force a change in behavior or create a liquidation emergency. If a wider invalidation distance increases the planned loss, reduce the position size or reject the setup rather than quietly accepting a new risk.
Liquidation is a venue risk-control event, not a planned exit. A position that only fails at liquidation gives normal volatility almost no room and may close at a worse price than expected. A planned invalidation should be meaningfully reached before liquidation becomes relevant, with enough available margin to account for ordinary movement and fees.
Use this process for any proposed position, regardless of whether the idea is trend, breakout, range, or event-driven:
The last step protects against a common mistake: judging a strategy from one win or one loss. A valid process can lose, and a flawed process can win by chance. Evaluation requires a documented set of comparable examples across different conditions.
Market dashboards can help a trader identify where attention and volatility are concentrated. A view of crypto market losers may reveal assets experiencing sharp declines, but a ranking does not explain whether the move reflects news, liquidation, thin liquidity, or a broad market shift. It is a starting point for investigation, not a short signal.
Before using a market ranking in a futures plan, check the instrument, venue, contract type, quote currency, time window, and available liquidity. A spot decline does not map perfectly to a perpetual-futures position, and the most visible loser may have a spread or funding profile that makes the trade unsuitable. Keep the market observation separate from the execution rule.
The same discipline applies to headlines and social commentary. A story can explain why a market moved without telling you where the move is invalidated or whether the contract can be traded at the displayed price. Use external information to update the condition, then return to the written plan and decide whether the setup still qualifies.
The most frequent futures errors are process errors: beginning with leverage, moving a stop farther away, treating margin as total risk, ignoring fees and funding, and trading every visible price move. A strategy should exclude most market noise. If every movement creates a reason to enter, the rule is probably describing emotion rather than a condition.
Jurisdictional protections, margin rules, fees, and product availability vary. Some contracts have funding payments, some have expiry, and some use mark prices that differ from the last traded price. Read the venue's terms and seek professional advice for questions about suitability, tax, or local regulation.
There is no universally best method. Trend, breakout, range, and avoidance approaches suit different conditions and can each fail. A useful strategy is one with defined conditions, invalidation, sizing, costs, and review rules.
Beginners can learn how futures work, but leverage, liquidation, and rapid price changes make the product high risk. Simulation or carefully limited practice can reveal operational mistakes before they become expensive. Learning the contract is not the same as being ready to trade it.
There is no universal answer. Choose exposure only after defining the loss you can accept, the invalidation distance, and the contract rules. The maximum offered by a venue is not a risk recommendation.
No. A strategy can have a high win rate while one large loss erases many small gains. Review the size of wins and losses, costs, drawdowns, execution quality, and performance across different market conditions.
When the market condition is unclear, liquidity is thin, an event can change the price faster than the plan can respond, or the loss cannot be estimated reliably. Waiting preserves the ability to evaluate a clearer setup later.
Futures trading strategies are useful only when they turn a market view into a complete decision: condition, trigger, invalidation, size, costs, and exit. Trend pullbacks, breakouts, ranges, and event avoidance each have a place, but none is permanently superior. Start with the loss you can explain, keep liquidation outside the plan, and review execution rather than celebrating isolated outcomes. In leveraged markets, a strategy is defined as much by the trades it rejects as by the trades it takes.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 29, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Competition And Market Structure, Regulation And Policy, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Cross Border Payments And FX, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Payments Infrastructure And Money Movement

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026).
This is a material step beyond the group's 2025 exploration phase. TD and Scotiabank are now participating in a global bank-led issuance venture while Canada's own stablecoin framework is still moving through implementation. The Canadian question is whether major banks build meaningful CAD-denominated digital-money capacity alongside domestic initiatives or gain scale first through shared global USD infrastructure.
Coinbase supplies the regulated trading and custody stack while Webull keeps the investor interface and brokerage relationship. That reduces the infrastructure brokers need to build themselves and gives specialist providers another route into Canadian retail distribution. It also intensifies Canadian crypto competition over who owns the customer and who supplies the regulated back end.
The useful proof is the cash leg. Tokenized securities have limited value if settlement still depends on separate legacy rails. This transaction puts the asset and payment legs onchain in a live regulated market environment, bringing programmable settlement closer to something institutions can actually use.
LSEG is extending tokenization from private markets and settlement infrastructure toward public equities. The harder test is whether tokenized shares can preserve legal ownership rights, corporate actions, price integrity and regulated settlement while gaining wallet portability and longer trading access. If that model works, public-market infrastructure begins competing directly with blockchain-native distribution without abandoning the protections of an exchange-listed security.
Coinbase is bringing regulated crypto derivatives distribution into Canada without routing the products through Coinbase Canada itself. The important boundary is eligibility as it expands access for sophisticated investors while keeping the offering outside ordinary retail availability. It also gives regulated venues a stronger alternative to offshore derivatives platforms for Canadian capital, hedging and price discovery.
The important development is bank ownership of shared tokenized deposit infrastructure, not the financing round. Cari is moving toward production with banks helping govern, fund and use the network while retaining the customer relationship. Alongside other shared bank blockchain infrastructure, the test is whether common digital money networks can achieve enough participation and interoperability to compete with institution specific systems.
Forty-three state licences give OpenPayd something infrastructure providers can't create through software alone: regulated geographic reach. The company can now connect its payment stack to a much larger U.S. operating footprint while combining fiat and digital asset permissions across the United States, United Kingdom and Europe. The test is how quickly that regulatory coverage converts into client activity and payment volume.
Final approvals put the transactions into execution. National Bank is positioned to absorb Laurentian's retail and SME relationships while Fairstone combines its commercial lending operations with Laurentian's commercial specialization. Customer migration, product continuity and retention now determine how much of the approved transaction value survives the transfer.
Australia's digital asset licensing transition now has a firm market access deadline. Firms still relying on transitional relief need the correct licence application or variation underway before September 30, while brokers, tokenization businesses, market operators and clearing providers must test whether their activities fall inside the existing financial services perimeter ahead of the new 2027 digital asset regime.
Singapore is converting stablecoin policy into the legal requirements issuers will operate under. The consultation advances the status tracked in NCFA's stablecoin regulatory intelligence from a finalized framework awaiting legislation toward implementation. Reserve, redemption, capital and cross-border requirements can now be tested against issuer economics before the rules are finalized.
The case makes privileged information a concrete event contract surveillance problem. Exchanges and brokers need controls that can connect unusual positions with access to confidential information, investigate suspicious activity and enforce trading restrictions. NCFA's regulated event contract infrastructure brief tracks this market integrity gap as distribution expands.
Section 311 can reach beyond a targeted foreign bank because U.S. institutions must also identify transactions routed indirectly through other correspondent relationships. Banks and payment firms therefore need enough counterparty visibility to detect the institution behind a payment chain, not only the correspondent presenting the transaction.
The investigation puts transaction monitoring and global compliance governance under direct supervisory scrutiny at a major cross-border payment provider. The operating test is whether controls identify known laundering typologies across high-risk channels and whether global decisions support local obligations. The eventual findings could provide useful evidence for how regulators assess AML controls across international payment networks.
Australia's AML expansion has reached the point where AUSTRAC is testing whether newly covered firms have entered the regulatory system at all. Service classification, enrollment and working AML controls can no longer remain implementation projects. Regtech providers also gain a much larger addressable compliance market, but buyers will need products matched to obligations regulators are actively checking.
Conditional approval advances Revolut from U.S. fintech distribution toward direct regulated banking capacity. Its U.S. business still relies on a partner bank, while NCFA's Revolut company intelligence had tracked the national bank application as pending. A completed charter would give Revolut more control over deposits, credit and payment connectivity, but the remaining federal approvals and preopening requirements still determine whether that capacity reaches customers in 2027.
OpenReserve is trying to combine conventional banking, tokenized deposits, digital asset custody and stablecoin infrastructure inside one national bank structure. Preliminary approval brings that model closer to regulated operating capacity, but the remaining test is execution: capital, controls, final authorization and separate approval for the planned stablecoin subsidiary still stand between the proposed structure and live customer activity.
TabaPay is trying to internalize regulated banking capacity rather than relying exclusively on sponsor bank relationships. Owning an OCC chartered bank could give the payments fintech more control over settlement, sponsorship, redundancy and difficult client use cases while retaining outside bank partners. The acquisition still requires regulatory approval, making the next test whether supervisors accept that vertical integration and its governance model.
A successful Swedish licence would turn Allica's international expansion from a funding plan into regulated market access. The bank now has to prove that its UK SME model can satisfy a new supervisor and compete in a concentrated, highly digital banking market. Approval would also give Allica a potential base for wider European expansion rather than requiring each new market to begin from the UK.
The US$3 billion target gives scale to the real time receivable funding model introduced in the United States this week. VersaBank is betting that faster access to bank balance sheet funding can take business from conventional securitization and warehouse structures. Fiscal 2027 will test whether partner demand converts into several billion dollars of new assets without weakening credit quality or funding economics.
The licence adds another authorized BNPL provider while reinforcing regulatory permission as a condition of market access in Saudi consumer finance. New entrants have to compete inside that perimeter, putting more weight on underwriting, merchant distribution, pricing and compliance execution once authorization is secured.
QR Ph is extending domestic interoperability into cross-border acceptance without requiring merchants to install another payment system. That reduces one of the practical barriers to international wallet acceptance, especially for smaller merchants. The competitive question is whether national QR networks increasingly become gateways through which global payment aggregators reach local commerce.
Agorá has crossed the real-money test identified in earlier Project Agorá testing. The harder questions now concern legal finality across jurisdictions, liquidity, interoperability and whether a shared multicurrency platform can reduce correspondent-payment friction at institutional scale without weakening central-bank control or commercial-bank money.
Banks are pushing deeper into stablecoins, tokenized deposits and direct control of payment infrastructure, while fintechs are trying to own more of the regulated stack themselves. The fight is increasingly over who controls the account, the customer relationship and the transaction flow.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 3, 2026 | NCFA Market Interest | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Wealth Investing And Trading
Kraken parent Payward has reportedly delayed its U.S. IPO again, this time to the second quarter of 2027 at the earliest. The company confidentially filed a draft registration statement in November 2025, then put the listing on hold in March as crypto prices, trading volumes and valuations weakened. Payward hasn't confirmed the new 2027 timing, so it remains a reported window rather than a scheduled IPO date.
The delay comes at an interesting point for the business. Payward reported US$508 million in Q2 adjusted revenue, up 17% year over year. Funded accounts rose 42% to 6.6 million, while assets on the platform were US$40 billion. Adjusted EBITDA was much thinner at US$23 million, and total platform transaction volume fell 18% to US$310 billion as crypto spot trading cooled.
Those numbers give Payward a pretty clear reason to wait. Revenue and customers are growing, but the company is still proving how much earnings it can generate when trading activity softens. Going public now would put that question in front of investors every quarter.
Kraken is still central to Payward, but the parent company now earns money from more than crypto spot trades. Asset based and other revenue accounted for 60% of adjusted revenue in Q2, up from 55% a year earlier. Payward also owns NinjaTrader, has added regulated U.S. derivatives through Bitnomial, and expanded into payments and card issuing through Reap.
Those businesses and revenue lines are important when trading slows. Payward's transaction volume fell 18% year over year, yet adjusted revenue still rose 17%. That doesn't make the company immune to crypto cycles, but it does show that the revenue mix is changing.
The acquisitions have also made Payward more complicated. Investors eventually have to decide whether futures, derivatives, payments, tokenized equities and infrastructure services add up to a stronger financial business or simply a larger collection of products. Staying private gives management more time to answer that with operating results.
Payward's recent transactions have valued its equity at about US$20 billion. The company also says it closed an US$800 million private funding round backed by investors including Citadel Securities, Jane Street, Oppenheimer and Tribe Capital.
The capital gives Payward capital and time, but the valuation also raises expectations for an eventual IPO. Public investors will want to see more than account growth. They will be looking at earnings, cash generation, trading volumes and whether the businesses Payward has bought can produce dependable revenue together.
The current quarter gives them both sides of the argument. A record 6.6 million funded accounts and 17% revenue growth are strong. US$23 million of adjusted EBITDA on US$508 million of adjusted revenue leaves much more room to prove that scale can turn into profit.
Payward's xStocks business is expanding beyond Kraken. xStocks distribution already reaches third party exchanges, wallets and blockchain applications, and Payward now says the products have passed US$40 billion in total volume, including more than US$20 billion settled onchain, across more than 200,000 holders.
The company took another step on September 1 when LSEG and Payward announced plans to explore tokenized UK public equities. Subject to regulatory approval, the London Stock Exchange intends to list xStocks on its planned LSE 24 venue in 2027.
If everything takes, that would put Payward beside a traditional exchange operator at the same time its own IPO waits. It is a good example of how far the company has travelled from being known mainly as a crypto exchange.
The biggest question is earnings. Payward can keep adding accounts and products, but public investors will want to see whether those businesses can produce stronger profits when crypto trading is weak. Q2 showed that revenue can keep growing while transaction volume falls. The next step is showing that more of that revenue reaches the bottom line.
The acquisitions also have to work together. NinjaTrader brings traditional futures clients. Bitnomial adds regulated U.S. derivatives. Reap adds payments and card issuing. xStocks adds tokenized equities. Payward Services sells some of the same technology to banks, fintechs and other platforms. If customers start using several of those products together, the company can earn more from each relationship without depending as heavily on one trading market.
Payward Canada is registered as a restricted dealer, giving Kraken regulated access across Canada. xStocks are still unavailable to Canadian retail clients, so Payward's wider product expansion won't automatically arrive here. Canadian access will depend on what regulators approve and which products the company decides to bring north.
Payward has private capital, growing accounts and several businesses still being integrated. It doesn't have to accept a public valuation today if management believes another year of results can support a better one.
There is risk in waiting too. Crypto markets can weaken further, acquisitions can disappoint and the IPO market may not improve on Payward's schedule. A private US$20 billion valuation is only as strong as the earnings and growth the company can eventually show public investors.
Kraken's IPO delay is therefore more than a calendar change. Payward is using the extra time to prove that it can grow into a larger financial platform, make its acquisitions pay off and earn enough outside crypto spot trading to support the valuation it wants when it finally lists.
Can Payward turn product growth into enough profit to support a US$20 billion public valuation?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 3, 2026
A credit card payment at an online casino costs the operator between 2.5% and 5% in processing fees, takes one to three days to settle, and carries a chargeback risk that averages 0.8% to 1.2% of total transaction volume. A USDC transfer on Solana or Base costs less than $0.01, settles in under three minutes, and cannot be reversed once confirmed on chain. For fintech professionals watching how stablecoin infrastructure performs under real production stress, online casinos have quietly become one of the most revealing test environments in payments.
This is not a story about which casino accepts crypto. It is a story about why the payment rails built under pressure from hostile acquirers are now structurally superior to legacy alternatives, and what that means for broader fintech infrastructure.
Online casinos operate under merchant category code 7995, one of the most restricted classifications in card network underwriting. Most tier-one payment processors refuse to onboard iGaming merchants entirely. Those that do charge premiums well above standard interchange rates, often landing between 3% and 5% per transaction.
The structural challenges compound from there. Chargeback rates in iGaming regularly exceed the thresholds set by Visa and Mastercard, triggering remediation programs that can end in merchant termination. Players expect withdrawals within minutes, yet ACH settlement runs on T+1 to T+3 timelines, and SWIFT transfers take three to five business days. The gap between player expectations and banking infrastructure creates friction at every point in the payment lifecycle.
These pressures created a forcing function. Operators that wanted to scale needed payment rails capable of high velocity cross-border flows, instant finality, reduced credit risk, and independence from acquirer gatekeeping. Stablecoin rails, particularly USDC, addressed all four requirements simultaneously.
When a player requests a withdrawal at a stablecoin casino, the transaction never touches an acquiring bank, a card network, or a correspondent banking chain. It travels on chain.
The operator's treasury system holds a liquid float in a hot wallet, sized to cover 24 to 48 hours of rolling withdrawal demand. The player's withdrawal request triggers a signed transaction broadcast to the blockchain. On Base or Solana, confirmation arrives in seconds with cryptographic finality. There is no authorization hold, no batch settlement window, and no reversal mechanism.
Chain selection matters at scale. ERC-20 USDC on Ethereum carries gas fees of $0.50 to $2.00 per transaction depending on network congestion. Solana reduces that below $0.001. Base sits below $0.01. For an operator processing 50,000 withdrawals per month, the choice of chain alone becomes a six-figure annual decision.
According to Circle, USDC has settled more than $70 trillion in cumulative on-chain transactions across institutional, B2B, and consumer use cases. This is production-scale infrastructure running across financial services, payments, and iGaming.
A direct comparison makes the economic case clearer than any narrative.
| Payment Rail | Settlement Time | Operator Fee | Volatility Exposure | Chargeback Risk |
| Credit Card | 1 to 3 days | 2.5% to 5%+ (iGaming premium) | None | High (MCC 7995) |
| Bank Wire (SWIFT) | 3 to 5 business days | $25 to $65 flat + FX spread | FX exposure | Low |
| Bitcoin (BTC) | 10 to 60 minutes | $1 to $30 variable | High | None |
| USDC (Base/Solana) | Under 3 minutes | Below $0.01 per transaction | None | None |
For an operator processing $10 million per month on card rails at a blended 3% iGaming rate, shifting to USDC represents roughly $300,000 in annual fee savings before accounting for chargeback losses.
Bitcoin is not a viable substitute at scale. Price volatility means any operator holding BTC in treasury carries mark-to-market risk on the liability side. A 10% price decline on a $1 million player balance creates an immediate $100,000 accounting gap. USDC, pegged 1:1 to USD and redeemable through Circle Mint, carries no equivalent risk. The liability stack stays USD-denominated throughout.
Platforms already running on these rails demonstrate the production reality. A live USDC casino operating at scale today faces none of the acquirer relationship risk, chargeback remediation exposure, or cross-border correspondent banking friction that card-dependent operators manage as ongoing cost centers.
In Canada, FINTRAC requires operators handling virtual assets, including stablecoins, to register as virtual asset service providers. This registration carries obligations for Travel Rule compliance at the transaction level and ongoing AML monitoring programs.
The regulatory trajectory is converging across jurisdictions. Canada's VASP framework, the EU's MiCA regulation, and emerging US stablecoin legislation all emphasize disclosure, reserve attestation, and Travel Rule compliance. USDC's monthly reserve attestation model, published by an independent accounting firm, already satisfies the transparency requirements taking shape in all three regulatory environments.
Operators building on Circle's infrastructure can inherit compliance controls directly. Circle's Payments Network includes built-in OFAC screening, Travel Rule messaging support, and AML monitoring capabilities. This reduces the compliance engineering burden materially compared to building a custom integration from scratch.
For Canadian fintech professionals, the key milestone to watch is FINTRAC's expected expansion of VASP reporting thresholds to cover stablecoin-specific transaction patterns. Operators and payment processors building on USDC rails now will have a compliance architecture head start when those requirements arrive.
On-chain settlement introduces a transparency layer that legacy payment infrastructure cannot replicate. Every deposit, withdrawal, and balance change is recorded on an immutable public ledger, creating a continuous audit trail without reliance on third-party attestation.
In iGaming, this connects directly to the concept of provable fairness. Understanding what is RTP in slots has traditionally required trust in third-party testing labs that certify return-to-player percentages. On-chain settlement opens the door to cryptographically verifiable RTP calculations, where players and regulators can independently confirm that game outcomes match published odds. This shift from trust-based to verification-based fairness represents a meaningful evolution for both player protection and regulatory oversight.
Programmability adds further capabilities that card rails cannot match. Smart contract-based bonus logic, automated affiliate settlement, and on-chain provable fairness are native to blockchain infrastructure. None require a third-party processor, a settlement delay, or a revenue-share arrangement with a payments intermediary.
The shift away from card rails in iGaming is structural, not cyclical. Card networks retain the unilateral right to remove a merchant category from acquirer eligibility without notice. That existential counterparty risk has no analog in stablecoin settlement, where the protocol itself has no commercial relationship with the merchant.
The cross-border advantage is equally concrete. USDC is natively issued across 37 blockchains and available in over 185 countries. Sending USD from Canada to a licensed offshore operator through a correspondent banking chain costs $30 to $60 per transfer and takes three to five business days. A USDC transfer costs less than a cent and settles in under a minute.
The onboarding friction for USDC is real: players still need a non-custodial wallet or an account on a centralized exchange. That friction is the primary reason card rails coexist in hybrid operator stacks. But for operators targeting experienced crypto users, the economics are unambiguous. And as wallet infrastructure improves, that friction is shrinking quarter by quarter.
A stablecoin casino is an online casino that accepts and settles player balances in USD-pegged stablecoins like USDC or USDT rather than fiat currencies or volatile cryptocurrencies. Operators use stablecoin rails to achieve near-instant withdrawals, eliminate chargeback exposure, and reduce payment processing fees to fractions of a cent per transaction.
On low-fee chains like Base or Solana, on-chain confirmation occurs in seconds with cryptographic finality. This compares to bank wire settlement of three to five business days and card processing of one to three days. The speed is structural, built into the protocol's confirmation mechanics, rather than dependent on processor batch windows or banking hours.
Licensed online gambling operates under provincial regulatory frameworks in Canada. Platforms handling virtual assets, including stablecoins, must comply with FINTRAC's VASP registration requirements, implement Travel Rule compliance, and maintain AML monitoring programs. Players should verify that their chosen platform holds valid licensing and is registered under the applicable VASP framework.
USDC is redeemable 1:1 for USD through Circle Mint at all times. Operator treasuries holding USDC carry no BTC or ETH price risk. The entire liability stack is USD-denominated, which means accounting, regulatory capital calculations, and player balance reconciliation all operate in the same fiat reference currency. This is a fundamental structural difference from Bitcoin or Ethereum reserves, where a price move creates an immediate liability gap.
Both are USD-pegged stablecoins, but they differ on compliance transparency and regulatory alignment. USDC, issued by Circle, publishes monthly reserve attestations from an independent accounting firm and is natively issued on 37 blockchains. USDT, issued by Tether, carries higher consumer adoption but provides fewer issuer-level compliance disclosures. For operators building compliance-forward stacks, USDC's attestation model aligns more directly with the disclosure requirements emerging under MiCA, FINTRAC, and US stablecoin legislation.
Online casinos did not adopt stablecoin rails out of ideological alignment with decentralized finance. They adopted them because card acquirers either refused to underwrite MCC 7995 or charged rates that made the business model unworkable.
The infrastructure built under that pressure is now the same infrastructure payment professionals are deploying for remittances, B2B settlement, and embedded finance. Near-zero fees, instant finality, zero chargeback exposure, and a USD-denominated treasury that requires no foreign exchange management: these properties are not specific to gambling. They represent the core value proposition of stablecoin payment rails in any high-volume, cross-border merchant category. The proving ground is already running at scale.
Circle - USDC Overview: https://www.circle.com/usdc
FINTRAC - Crypto Asset Guidance: https://www.fintrac-canafe.gc.ca/re-ed/crypto-eng
Wild.io USDC Casino: https://wild.io/casino/usdc-casino
Wild.io RTP Guide: https://wild.io/academy/articles/what-is-rtp
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016