




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 1, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, SME Finance And Business Banking, Digital Banking And BaaS
On September 1, 2026, London, Ontario based VersaBank announced the first U.S. Real-Time SRP implementation with ECN Capital. The system can fund eligible point of sale loans within hours. VersaBank says conventional funding can leave lenders waiting five to 30 days or longer while enough receivables accumulate.
ECN isn't a new customer. It implemented VersaBank's original U.S. Structured Receivable Program in 2025, and another ECN subsidiary joined the program in July with at least US$300 million in expected annual fundings. ECN Capital's Chris Johnson said the original SRP helped the company “grow our business faster” while improving profitability. The September implementation adds the newer real time capability, although VersaBank hasn't disclosed how much volume is flowing through it yet.
The scale is already substantial. VersaBank's total Structured Receivable Program portfolio exceeded C$4.4 billion as of January 31, 2026 after growing at a 33% compound annual rate over five years. U.S. SRP credit assets reached US$604.9 million by the end of the bank's second fiscal quarter of 2026, and VersaBank was targeting at least US$1 billion in additional U.S. SRP fundings during fiscal 2026.
What changes with ECN is speed. A funding model VersaBank has used in Canada for more than 15 years, and recently accelerated with Financeit, is now running in the U.S. with an established finance company.
Point of sale lenders need capital to keep making loans. A lender financing home renovations, HVAC systems, equipment or other large purchases may hold new receivables on its own balance sheet or borrow against them through a warehouse facility until the loans can be sold, refinanced or packaged into a securitization. That interval ties up capital and carries a financing cost.
VersaBank's Structured Receivable Program purchases qualifying receivables from finance companies. Real-Time SRP brings that funding closer to the original loan by evaluating and financing eligible individual receivables within hours rather than waiting for a larger pool to accumulate.
The model was first tested through an April Financeit pilot. The pilot finished ahead of schedule, and Financeit became the first partner to use Real-Time SRP at large scale when VersaBank formally launched the program in June. Financeit was approaching C$2 billion in annual loan originations, giving VersaBank a sizeable Canadian lending operation on which to prove the process before taking it into the U.S.
VersaBank describes the system as AI enabled, but its public disclosure supports a more targeted description. The bank says its internal AI technology helps evaluate individual loans underlying SRP receivables. It has not disclosed enough detail to determine exactly how eligibility, credit scoring, fraud checks or other decisions are divided between automation and human oversight.
Financeit completed a C$201 million ABS in June while also using VersaBank's real time funding. Those sources of capital can serve different stages of the same lending business. VersaBank can provide funding closer to origination, while securitization can provide longer term institutional capital after loans have accumulated into a larger pool.
Forward flow provides another option. Propel Holdings secured a US$60 million forward flow from Mesirow managed funds for Freshline loans, allowing institutional capital to purchase eligible production as it is originated. Warehouse lenders, forward flow investors, banks, private credit funds and ABS buyers are all competing to fund the period between a lender making a loan and receiving longer term capital.
VersaBank is trying to compress that period. The economic benefit depends on whether the cost of its funding, integration requirements and credit rules are attractive enough to save lenders money or free enough capital to justify adding another funding relationship.
VersaBank has operated versions of its Structured Receivable Program in Canada for more than 15 years. It entered the U.S. point of sale finance market after acquiring a U.S. bank in 2024, giving VersaBank an OCC chartered national banking platform in Minnesota.
VersaBank is doing more than licensing software to ECN. It's using deposits and its own balance sheet to buy qualifying U.S. receivables through a funding model developed in Canada. That lets the bank grow through lending partners without having to build a large consumer lending operation itself.
ECN is now using the faster version in the U.S. VersaBank already had hundreds of millions of dollars in U.S. SRP assets, and the wider ECN relationship includes at least US$300 million in expected annual fundings. The real time version gets eligible receivables onto VersaBank's balance sheet sooner.
Faster funding can help lenders keep more cash available for new loans, but only if VersaBank's price and credit rules beat the alternatives. Lenders already have warehouse lines, forward flow buyers, banks and securitization markets competing for their business, so speed alone won't win the account.
For VersaBank, more U.S. receivables mean more loans and leases earning interest on the bank's balance sheet without VersaBank having to find the borrowers itself. The economics work only if what the bank earns on those assets stays comfortably above its funding costs and credit losses.
Growth can also concentrate risk. A few large partners, weaker loan quality or rising deposit costs could turn faster asset growth into lower returns. ECN is the first U.S. user of the real time version, so the more telling evidence will be whether other lenders adopt it and whether those portfolios perform well as volumes rise.
Private credit adds another source of competition for finance companies seeking capital. Canadian institutions already have roughly C$500 billion of private credit exposure, much of it outside Canada, while U.S. private credit funds have become major lenders to businesses and specialty finance companies. VersaBank is entering that competition with a regulated bank balance sheet, a deposit base and a funding system designed to work much closer to loan origination.
Can VersaBank turn a Canadian funding model into a scalable U.S. lending business?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Sep 2, 2026
Image: Magnific/Rawpixel.com
American retail currency traders navigate one of the most strictly supervised financial environments on earth. A company holding a proper Forex license within the United States offers top-tier security for customer capital and operates under full regulatory transparency. Mandates from the Commodity Futures Trading Commission (CFTC) and National Futures Association (NFA) enforce stringent balance sheet requirements on these platforms. Consequently, only a small, dedicated group of brokerage firms actively accept US residents in 2026.
Federal laws require every retail foreign exchange dealer to maintain at least $20 million in adjusted net capital. This massive financial requirement prevents undercapitalized entities from taking on retail accounts. Additionally, rules designed to safeguard individual deposits impose strict limits on daily trading operations.
Brokers must follow several mandatory execution rules across all trading accounts:
These stringent operating conditions eliminate high-leverage gambles and build a transparent trading environment. Traders who prioritize fund safety often view these regulatory guidelines as a protective buffer rather than a hindrance.
Active traders must research operational histories and compliance records before opening an account. Because foreign unregulated brokers frequently try to attract American traders with promises of extreme leverage, market participants must verify every regulatory claim through official government databases.
On the operational side, financial entities entering this market rely on experienced legal advisors to manage these complex international standards. SBSB Fintech Lawyers brings more than 13 years of experience in fintech, crypto, gambling, and investment consulting. Their team assists international firms with regulatory compliance, structural planning, and licensing solutions across global markets.
Before opening a live account, retail clients should evaluate specific features:
Smart traders check these details carefully before transferring capital. Verification of these factors keeps funds safe from unauthorized offshore entities operating without proper oversight.
Accounts opened within the US regulatory framework offer distinct financial benefits. Tax treatment represents a significant advantage for active market participants. While spot forex trades default to ordinary income rates under Section 988 of the Internal Revenue Code, traders can opt into a more favorable treatment. Under Section 1256, qualifying forex transactions receive a 60/40 tax split. Sixty percent of gains receive long-term capital gains tax rates, while forty percent fall under short-term rates, regardless of position duration.
Traders should consider several practical account management strategies:
Proper record-keeping combined with strategic account management helps market participants keep more of their earnings. American trading regulations impose tight boundaries, yet the enhanced security and favorable tax rules offer tremendous value to serious traders.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 2, 2026
Image: Pexels
Ontario has turned a small product detail into a serious design question. A deposit limit once looked like a setting near the edge of an account page. In 2026, the Ontario Lottery and Gaming Corporation moved it closer to the centre of the experience when it introduced a measure requiring some online players under 25 to set deposit limits as engagement rises through its safer gambling approach. That decision gives fintech designers a live case study in timing and restraint.
The point reaches beyond gaming. Banking apps, trading platforms and payment products all ask people to make money decisions on small screens. Speed helps when someone pays a bill and it can harm judgment when a screen nudges faster spending. Ontario’s model shows how a digital product can add friction at the right place without turning every action into a lecture.
OLG’s under-25 measure focuses on a group that research often links with higher gambling harm. The rule does not ban play. It asks certain users to set a cap as their activity grows. A cap can be daily or longer term. In financial design, the same idea can apply to stock trading deposits or crypto purchases. Earlier boundaries can reduce decisions made under pressure.
Ontario also gives designers a mature market to study. iGaming Ontario says its regulated market produced $82.7 billion in wagers during 2024 to 2025, with $2.9 billion in gaming revenue across more than 2.6 million active accounts in its annual report. A market of that size creates real design evidence. The best lessons come from how controls appear during ordinary use.
Spending controls work best before stress arrives. A daily limit has more force when someone sets it during account setup. A reminder has more value when it appears before a pattern becomes hard to interrupt. Product teams often want the shortest route to a completed transaction. Ontario’s approach suggests a better question for finance apps: at which point does speed stop helping the customer?
Investing apps already face a version of this test. A user may understand a company but misunderstand leverage. Another may know the price of a fund but overlook currency exposure. A good interface does not need to scold either person. It should show the cost, the limit and the consequence before confirmation. Ontario’s spending controls offer a model for that kind of intervention.
Casino comparison sites entered this landscape because choice became too large for casual browsing. Readers now compare payment methods, transaction times and withdrawal rules before opening an account. They also check licences, customer support and responsible-gambling tools before making a first deposit, a research habit that increasingly resembles fintech comparison. Someone choosing a trading app, for example, wants fees and account conditions visible before funding begins.
A regional review page can serve the same purpose by showing how product design differs across approved platforms. Someone looking at options selected by Casino.ca in Ontario can compare licensed casinos across practical criteria such as payment methods, withdrawal speeds, games and overall experience. The review format becomes more useful when it goes beyond a simple ranking and helps readers understand why platforms differ, including differences in security, banking options and customer support.
That structure also shows fintech teams how third-party guides can add value by making fees, risks, account controls and other important product information easy to inspect and compare. In both casino and fintech contexts, the strongest comparison experience helps users evaluate the product before they commit funds, rather than leaving important conditions until after registration.
Behaviour signals can help a product notice risk before a user asks for help. A sudden limit increase has meaning in one context and less in another. Several deposits in a short period can show excitement, confusion or distress. The product cannot read motive. It can slow the next step and offer support without pretending to know the full story.
The Alcohol and Gaming Commission of Ontario tells operators to use automated and manual monitoring so they can identify signs of harm and respond at a pace that matches changing behaviour in its operator guidance. Automated checks can catch patterns at volume. Staff review can add judgment where a rule may overreach. Fintech products need that same balance when they flag risky payments or rapid trading.
Crypto products face a harder version because transfers move fast and reversal options can be limited. A wallet app can show network fees and destination checks before a transfer leaves. A trading product can display volatility ranges before a purchase. Those steps protect choice by adding context. They work best when the words sound like service language rather than legal fog.
A control that users cannot find has little practical value. iGaming Ontario reported player awareness of responsible gambling tools at 71.5% in 2024 to 2025 through its 2026 to 2029 business plan. That figure gives product teams a hard target to think about. Of course, awareness doesn't arrive by placing a link in a footer. The interface has to bring the tool into normal view.
Fintech apps often place limits in account settings. Many users visit that area only when something breaks. Better design brings controls into the flow. A deposit screen can show the current cap. A payment app can show a monthly spending marker. A trading platform can let customers set cooling-off periods before volatile orders. The user still decides, but the decision gains context.
Language decides whether people use the feature. “Set a deposit limit” works better than “configure responsible-use parameters.” “Take a break” works better than a policy label. The same rule applies in banking. “Pause card spending” tells the user what will happen. “Manage transaction governance” sends them elsewhere. Good fintech design respects attention.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 1, 2026
Betting has been one of our favourite activities for centuries, with people eager to wager on what they predict will happen when dice are thrown, wheels are spun, and so on. For most of human history, it was an extremely low-tech activity that relied on everyone being in the same room. While those games still exist in much the same form, it’s become far easier to engage with them, thanks to the following key innovations.
A vastly wider range of games represents the biggest change in casinos since they went online. While casinos were always limited due to their physical space in the past, the switch to online sites allowed operators to greatly increase their collection of games. This began with the introduction of more classic games, such as roulette and blackjack, which were usually very similar to the traditional versions.
However, leading game developers have taken our favourites in new directions since then. The Sportaza online casino contains a huge variety of slots, such as Royal Coins by ELA Games, Chicken Road 2.0 by InOut, and 3 Million BC by Betsoft. These games take the tried and trusted slots mechanism from the past and add new themes. Features such as jackpots and bonus rounds have been added to create more varied gameplay too.
In terms of table games, the biggest change has been implemented through livestreaming technology, which allows casinos to host online games with live presentation. A group of 4K cameras is typically used to provide different camera angles that the player can choose from, giving a smooth, uninterrupted view of the action at all times. In some cases, augmented reality is added, meaning that the cards and chips on the screen move between digital and real life. The Google AR & VR page explains how these technologies fit together.
This has led to classic table games being reimagined with new features, such as multipliers and side bets. It’s also given us game shows including Candy Wheel, Football Thrill, and Robin the Fair. These games introduce giant wheels, slots rounds, and other types of props to let players place varied wagers in a live setting.
The integration of different types of betting on the same site has been another huge change in the way we gamble. Sports betting has always been about wagers placed before the action begins, which are then settled once the final result is known. When online sports betting began, it followed this same process. However, the work carried out to integrate live scores and updates onto the same sites as casinos has allowed sportsbooks to now provide live betting.
This means that fans can bet on games and events as they take place, predicting what happens next based on what they see happening at the time. This has fundamentally changed the way we place sports wagers.
It works through advanced APIs that integrate live event data. Automated risk engines look at the data and adjust the odds instantly to take into account the flow of the action. The other major change has come with the way that users can choose whether to cash out early. This can be done in those cases where a cashout price is shown during the game, so that users can decide whether it makes sense to accept that price or wait for the event to end.
Modern players don’t want to wait days or weeks for transfers to go through, which was one of the issues that held back the early online betting industry. Therefore, casinos now put their cashier experience as one of the most important parts of the overall site performance. This can be done thanks to the fact that several fintech innovations have helped make it a lot easier to move funds back and forth.
Digital wallets were among the earliest of the changes that were introduced to this sector, with the likes of Skrill and Neteller proving popular in North America. Canadians have also benefited from the introduction of Interac, which allows almost instant transfers to and from bank accounts. Interac is a decentralized interbank clearing network. In other countries, open banking allows users to easily move funds when they want to gamble.
The different types of innovation that have led to these changes have made it far easier for people to enjoy online gambling. As the industry carries on growing, we can expect to see more new technology and ideas being used. If you just want to spin some slots or put some chips on the blackjack table, the good news is that innovations in fintech and beyond make this super easy to do from your own home.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 31, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization, Wealth Investing And Trading, Competition And Market Structure, Capital Markets And Market Infrastructure
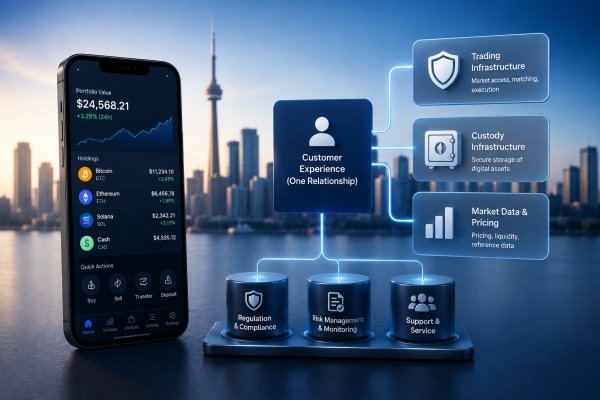
On August 31, 2026, Coinbase announced its Webull Canada partnership, supplying the trading and custody services behind Webull's new Canadian crypto offering. Webull maintains the investor relationship and brokerage experience, while Coinbase handles two core crypto functions. The same partnership already supports Webull in the United States, Brazil and Australia.
Webull Canada Crypto Limited was registered as an Investment Dealer and admitted to CIRO membership effective June 17, 2026. Coinbase Canada, Inc. is registered as a Restricted Dealer across Canada.
Crypto arrives after Webull spent more than two years expanding its Canadian brokerage. It launched here in 2024 with Canadian and U.S. equities and later added registered accounts, options, cash management, desktop trading and longer trading hours. Canadian stocks and ETFs now trade at zero commission, while selected securities are available around the clock five days a week.
When Webull entered Canada, its offering was much narrower. The company has since added enough products that crypto now joins an account already spanning stocks, options, cash, margin, TFSAs and RRSPs.
Using Coinbase lets Webull add crypto without building its own trading and custody systems from scratch. It can use infrastructure already supporting the same partnership elsewhere, reducing the amount of technology and operating capability Webull has to build internally.
Webull still has to persuade Canadians to use the product. The company reports 26 million registered users globally but doesn't disclose its Canadian customer count, leaving a large gap between the breadth of its local product menu and what outsiders can see about actual adoption.
A Canadian investor trading crypto through Webull remains inside Webull's experience, but Coinbase can still earn from the trading and custody taking place underneath it.
Coinbase has been selling more of those capabilities to financial institutions. Its Crypto as a Service business targets banks, brokers, fintechs and payment companies that want to offer digital assets without building everything themselves. Coinbase said in 2025 that more than 200 institutional clients were already using its infrastructure.
Webull gives Coinbase another customer for that business while Coinbase continues competing directly for Canadian crypto users through its own platform. The two companies can pursue the same investor from different positions. Webull wants the account and ongoing customer relationship. Coinbase can benefit whether the investor chooses Coinbase directly or reaches its services through Webull.
Webull is relying on Coinbase for key parts of the service. If trading, custody, pricing or service problems arise, Webull still has to deal with the customer impact.
Webull isn't alone in combining its own customer experience with outside financial infrastructure. Wealthsimple offers stocks, cash and crypto from one relationship, while its regular crypto service uses external custodians including Tetra Trust, Coinbase Custody and BitGo. Its recent in app DEX trading beta uses a different model, creating a self custody wallet for the client and routing trades through a third party DEX aggregator.
Crypto focused firms such as Coinsquare, Newton and Shakepay started from a different approach, building their customer relationships around digital assets before adding more services. Webull started as a brokerage and is bringing crypto into an account already built around conventional investing.
Customers can now see a growing number of competing apps even when some important functions behind those apps come from the same suppliers. If several brokers rely on a small group of firms for custody, execution or liquidity, competition at the customer level can grow faster than the number of companies providing the underlying services.
Building everything internally isn't automatically better and often depends on the lifecycle stage of the firm and target customer base. It can preserve more control and economics, but it also brings technology, security, compliance and operating costs. Buying specialist infrastructure can get a product to market faster, provided the platform is comfortable with the dependency and the economics.
Webull has removed many of the obvious product gaps since entering Canada. Investors can now trade Canadian and U.S. equities, options and crypto, use registered accounts and access longer trading hours. Another product won't automatically pull customers away from Wealthsimple, established brokerages or dedicated crypto platforms.
Existing Webull users may be the easiest audience. They can add crypto beside the rest of their portfolio without opening another trading relationship. Whether that convenience produces meaningful Canadian crypto activity won't be clear until Webull discloses more about adoption or the market provides other evidence.
Coinbase receives another benefit if the model continues to expand. Its Webull relationship now spans four countries, so a successful Canadian launch gives Coinbase another example it can use when selling trading and custody services to other financial firms. It doesn't need its name on the customer's home screen to participate in the transaction.
Webull and Coinbase are building different businesses from the same Canadian launch. One wants to own more of the investor relationship. The other can earn by supplying financial functions to companies that already have one.
As financial apps buy more of what they offer from specialist providers, who keeps more of the long term value: the company with the customer or the company running the service underneath?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 28, 2026 | NCFA Market Activity + Insight | Capital Markets And Market Infrastructure, Risk Compliance And Regtech, Regulation And Policy, Wealthtech Investing And Trading
On August 28, 2026, the Commodity Futures Trading Commission penalized Gabriel Perez for prediction market insider trading after finding that he used confidential presidential speeches to trade event contracts for his own benefit. Perez worked as a White House technical adviser and teleprompter operator, which gave him access to prepared remarks before President Donald Trump delivered them.
Perez generated US$107,539.02 in profits by trading contracts on words and phrases the President would mention. He must return those profits, pay a US$65,000 civil penalty, stop violating the Commodity Exchange Act and stay out of CFTC regulated trading for three years. Perez consented to the settlement without admitting the CFTC's findings or legal conclusions, and the Commission says his cooperation justified a substantial reduction in the civil penalty. The CFTC also thanked KalshiEX for assisting the investigation.
As event contracts attract more volume, products and mainstream distribution, exchanges need to do more than price outcomes and settle trades. They need credible ways to identify when someone may know the answer before everyone else.
A mention market lets traders take a Yes or No position on whether a word, phrase or term will appear during a defined event. Perez opened his Kalshi account on December 8, 2025 and traded markets tied to presidential speeches, including addresses, rallies, policy remarks and the State of the Union.
The CFTC order says Perez generally saw prepared remarks about an hour before the President spoke. He bought Yes contracts when the target word appeared in the speech and No contracts when it did not. On one occasion, he changed his position after watching the President skip part of the prepared text.
Perez traded across 14 presidential mention markets and made money on 39 of 43 contracts. He was not making a better forecast than other traders. He had already seen the prepared remarks and knew whether many of the words being traded were present.
Traditional financial markets already deal with executives, advisers and employees who may hold valuable information before investors receive it. Event contracts can create a much wider group of people with direct knowledge of an outcome. A political speech can involve writers, production staff, government employees and technical crews, while sports, entertainment and corporate events can involve players, coaches, producers, employees, advisers or others close to the result.
That risk was visible before federal enforcement arrived. Kalshi's earlier insider trading cases included a MrBeast editor and a California political candidate, and the exchange said it had opened roughly 200 investigations or probes. Those cases showed that integrity work was already becoming part of running an event market. The Perez action is more consequential because the CFTC is now applying federal commodities law directly to misuse of confidential information in prediction market contracts.
The integrity problem can also extend beyond advance knowledge. Some traders may know an outcome early, others may be able to influence it, and some may hold information through a public duty or private relationship. That makes the source of the information as important as the trade itself.
The CFTC order and what the public record shows is that investigators could connect Perez's account, government role, speech access, trading times and profits. For prediction markets, knowing who is behind an account matters as much as spotting an unusual trade.
Traditional surveillance remains important. Exchanges can look for unusual profits, concentrated positions, repeated success, trading immediately before an event and activity that doesn't fit a customer's normal behaviour. Prediction markets add another requirement because suspicious trading may only make sense once the account is connected to a job, relationship or source of access outside financial markets.
A trader repeatedly winning presidential speech contracts becomes far more interesting if the exchange or regulator also knows that person works on presidential events. The same logic applies to sports personnel trading injury or lineup contracts, employees trading corporate outcomes or production staff trading entertainment events.
Exchanges need to know who is trading, what access they may have to the event and whether their trading pattern fits that access. Reliable customer identity, account history and information about relevant jobs or relationships can help investigators decide whether an unusual trade deserves a closer look. Surveillance teams need tools that can connect trading patterns with occupations, relationships and event access. Case management, alert review and auditable investigation records become more important as the number of contracts and traders grows.
This boosts the commercial case for regulated event contract infrastructure. Market surveillance, identity controls, outcome verification, compliance workflows, investigation tools and regulator reporting are becoming part of what platforms need to operate credible markets, alongside matching, pricing and settlement.
Different contracts also require different surveillance assumptions. An inflation contract settles on a formal public release. A presidential mention contract may depend on a speech seen by staff shortly before delivery. A sports contract can depend on injury or lineup information known to a relatively large group before the public learns it. Exchanges need to understand how each event is produced, who may know the answer early and who can influence the result before they can decide what suspicious trading looks like.
Prediction markets are reaching customers through larger financial platforms, which brings more liquidity but also more accounts and more activity to monitor. Recent CSA and CIRO guidance on prediction markets keeps sports and entertainment event contracts outside Canada's securities dealer channel, while Wealthsimple Investments and Interactive Brokers Canada can offer a narrower set of economic, environmental and financial contracts under CIRO conditions.
The CFTC case also shows that regulators are prepared to use existing commodities rules when confidential information is abused. Exchanges and distributors therefore need to spot suspicious activity early, connect it to useful account information, investigate it and keep records that can support enforcement.
That creates a practical market for surveillance, identity, behavioural analytics and case management tools. Prediction markets have already proved they can attract products, liquidity and mainstream distribution, but can market integrity keep up.
Can prediction markets scale faster than their ability to detect who knows the outcome before everyone else?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 31, 2026
Money's been on my mind recently. Not in that anxiety-spiral way where you check your bank account at 2am, but this quiet realization that maybe I should know where my paycheck actually goes.
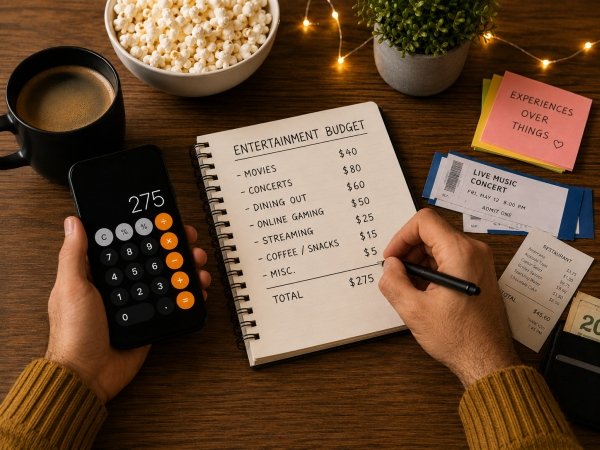
Last month I tracked every dollar I spent on fun stuff for 30 days. Movies, streaming subscriptions, nights out, concert tickets, all of it. The final number: $387.42. When I looked at that spreadsheet, I couldn't remember what half those charges were for. What's the point of spending money on entertainment if it vanishes from memory within two weeks?
I started approaching entertainment differently. Not cutting everything fun out, but actually thinking about what I was doing with my money instead of letting it evaporate.
I didn't create some elaborate system. After obsessing over my spending patterns, I noticed something. The weeks where I felt genuinely good about how I'd spent my time and money? Pretty much always came out between $50 and $65. Not $100, not $20, just that range where I'd actually done something worth remembering without that guilty feeling.
Usually broke down like this: one planned thing with friends costing $25 to $30, small daily stuff like grabbing coffee or buying a book adding up to $15 or $20, plus one spontaneous decision for another $10 to $15.
This magic number doesn't work for everyone. Your sweet spot might be $30 or $100 depending on where you live, what you earn, and what brings you joy. But having an actual number instead of vibes-based spending helps you make better choices in the moment.
I started investing 10 minutes researching before spending money on something. When I was considering trying a new platform (like when I checked out Rex Bet after my friend wouldn't shut up about it), I actually looked at what they offered instead of just creating an account and hoping for the best. New restaurant? I'd glance at menu prices first.
Doing that research didn't kill spontaneity like I thought it would. It made spontaneous decisions better because when I did something on impulse, I was way more likely to genuinely enjoy it instead of feeling like I'd wasted money.
Anything over $75 gets a two-day waiting period. That's it.
I wait 48 hours before buying it, and you'd be shocked how many times something I absolutely needed to have right that second completely disappeared from my brain after two days. Still thinking about that $89 blender I almost bought at 11pm on a Tuesday that I've never thought about since.
The stuff I still wanted after waiting? Those purchases turned out to be worth it almost every time. I noticed they were usually experiences instead of things, which bring way more lasting happiness anyway.
I'm not spending dramatically less money now. Some months I actually spend more than my old average. But the difference is I can tell you exactly where that money went and why. I remember the comedy show I saw three weeks ago because I actively chose it instead of defaulting to whatever required the least thought.
My whole relationship with my entertainment budget changed. Stopped being about restricting myself or feeling guilty, started being about actually being present for the experiences I was paying for instead of mindlessly swiping my card and wondering where my paycheck vanished to.
Pretty small shift when you think about it. Made a massive difference though.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016