




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Apr 17, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure
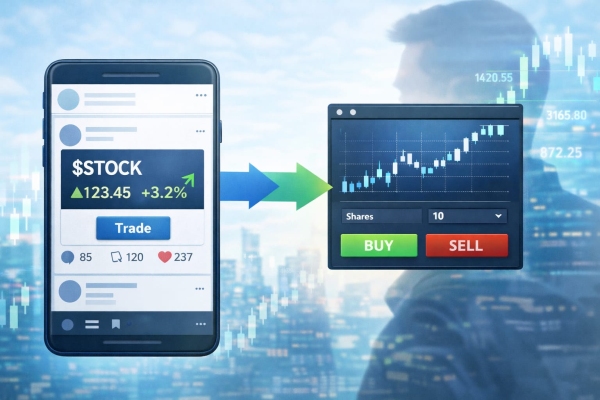
On April 15, 2026, Wealthsimple confirmed integration with X Smart Cashtags. Canadian users can tap a ticker in X and go straight to that security’s detail page in Wealthsimple. Signed-in users land on a screen ready to review or trade. In other markets, Cashtags show real firm data and discussion, but don't yet connect directly into a brokerage.
X now keeps price charts, asset context, and related posts inside the feed. Users can check the setup without leaving the platform. Wealthsimple captures the order once the user decides to trade. X product leadership also showed the flow publicly in this product demo on X.
𝕏 has always been the best source of financial news for traders and investors. Billions of dollars are allocated every day based on what people read on Timeline.
Today we're launching our new Cashtags feature in the US and Canada on iPhone, bringing real-time financial data to… pic.twitter.com/c8s7X9gHTO
— Nikita Bier (@nikitabier) April 14, 2026
Social trading platforms have linked discussion and execution for years. What’s different here is the handoff. X holds the user inside the conversation, shows live market context, and then routes directly to a brokerage when intent is already formed.
That changes where brokerages compete. They no longer control discovery from start to finish. X controls attention and early decision-making. Wealthsimple captures execution after that point.
It's an important evolution. If discovery keeps integrating onto social platforms, brokerages will rely less on brand-led acquisition and more on conversion at the moment of trade. Speed, pricing, reliability, and trust start to matter even more once the user arrives ready to act.
Wealthsimple gains distribution from a high-attention platform where market conversations already happen. It also depends on X for that flow. The partnership trade-off will become more important when competition ramps up as other platforms build similar yet differentiated models that turn brokerage apps into downstream execution layers.
X has been heading in this direction for years, and has steadily added financial data, market context, and navigation into one surface. Smart Cashtags push conversations about markets further to where trades begin.
Interestingly, as more brokers plug into the same surface. Feeds may become more responsive to user behaviour. If that happens, X doesn't need to become a regulated brokerage, because it only needs to control the point where intent forms and connects.
Canadian regulators are already addressing this type of activity. CSA and CIRO guidance makes it clear that securities laws apply when online content influences investment decisions, including cases where users are directed toward trading platforms.
The model itself is allowed, but closer links between content and execution are likely to draw more scrutiny as expectations around disclosure and influence continue to tighten.
In this case, a post, a cashtag, and a direct path to a trade sit in the same flow. That makes it harder to separate general information from something that could be viewed as influencing a transaction.
Responsibility isn't just with creators alone. Platforms that present the content and connect users, along with the brokerages that execute the trade, may face closer scrutiny as these connections become more direct.
Social platforms are starting to control where intent forms, while brokerages compete to capture execution once that intent is already there.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
April 17, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Regulation And Policy, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026).
OSFI has returned non bank financial institution risk to the supervisory foreground. That puts more attention on leverage, liquidity, and credit formation outside the traditional banking perimeter.
European policymakers are now linking stablecoins, tokenized deposits, and payment sovereignty. If banks move on this, product teams will need to build for liquidity, redemption certainty, and distribution at scale.
The UK now has a clearer crypto timetable. Firms can see when the authorisation gate opens, when the regime goes live, and which business models sit inside scope. That gives exchanges, custodians, stablecoin issuers, and staking providers a more defined build and compliance window.
Pakistan has opened a formal banking channel for licensed virtual asset firms while keeping balance sheet exposure and client money handling tightly controlled. That gives the market a clearer regulated path for fiat access without relaxing the banking perimeter.
A global bank has expanded tokenized deposits into the U.S. for real treasury and liquidity use. That brings tokenized money closer to core banking and cross-border cash management, not just digital asset experimentation.
The SEC has drawn a clearer line around how crypto interfaces can operate without crossing into broker dealer registration. That gives wallet providers, front ends, and trading interfaces a more defined design perimeter, while keeping execution control, solicitation, and custody inside the regulated boundary.
Open finance now has a regulator defined build plan with a clear timeline. That gives banks and fintechs a window to develop data driven products beyond payments and reshape how credit and financial services are distributed.
Stablecoin settlement now runs through a $60 billion cross border network. Banks and existing rails face direct competition on settlement.
This gives Payward regulated U.S. clearing infrastructure that took more than a decade to build. That puts crypto-native derivatives closer to the core of U.S. market structure and gives banks, brokerages, and fintech partners a new route into regulated digital asset derivatives.
The SEC has reopened foundational questions around the main surveillance infrastructure for U.S. equity markets. That puts market structure, compliance technology, cost allocation, and data governance back into active review.
The FCA has reduced reporting friction without removing oversight. That changes daily reporting operations for trading firms and market makers, and it forces compliance, data, and regtech teams to adjust how short position data is calculated, submitted, and published.
The trade entry point is entering the social layer. X now controls how users move from conversation to market data, while brokerages plug into that flow to capture execution.
Crowdcube is linking retail private markets with regulated public market infrastructure. That gives companies a new way to raise capital and provide liquidity without waiting for an IPO, and it opens institutional demand to retail-originated share flow.
The update raises the compliance baseline across multiple financial crime domains at once. Banks, PSPs, and fintechs operating in or through UAE corridors will need to adjust risk models, monitoring systems, and correspondent banking controls.
This week tightens the real constraint on fintech execution. It is no longer access or distribution, it is whether your product can operate inside the rules of the rails it touches. Payment flows now include machine-initiated actions, reporting regimes are getting simpler but less tolerant of errors, and market infrastructure expects you to plug in cleanly from day one. If your system cannot enforce permissions at the transaction level, produce a clear audit trail, and align with regulated reporting without rework, it will slow down as the market speeds up. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 17, 2026 | NCFA Fintech Insight | Payments And Market Infrastructure
On April 16, 2026, Payments Canada admitted DoBusiness.com as a payment service provider member, the latest non-bank company to gain a path to access Canada's core payment rails, including Lynx, ACSS, and the Real Time Rail.
Direct access to payment rails reduces reliance on sponsor banks, cuts transaction costs, and gives firms more control over how and when money moves. It allows payment providers to manage liquidity, route transactions, and design products without passing every step through an intermediary.
Donna Kinoshita, Chief Payments Officer at Payments Canada:
“The inclusion of specialized enterprise SaaS providers alongside our existing members is a clear sign of the evolving payment landscape. As our membership continues to diversify, so do the perspectives that inform the future of Canada’s payment infrastructure, ensuring an inclusive payment ecosystem that gives Canadians more choices
Companies that meet the requirements can apply through Payments Canada's membership process and move toward participation in core payment infrastructure.
Payments often work through a sponsor bank, then through clearing, then settlement. Each step adds fees and delays. A firm with access can remove part of that chain.
Take a simple example. A fintech that relies on a sponsor bank may pay fees on each transaction, wait for batch processing, and rely on the bank’s timing and liquidity controls. Compare and contrast that with a company with direct or near direct access who can route payments without that extra layer, manage liquidity in its own systems, and process transactions closer to real time. The difference is found in unit cost structure, settlement speed, and how products are designed. For consumers and businesses, this typically means faster processing and in some cases lower fees.
This admission follows earlier PSP intake, including five firms added at the start of 2026, and lines up with ongoing Real Time Rail testing and onboarding work. More firms are positioning to operate inside the system, not just connect to it.
As more companies gain a path to participate in core payment systems, the range of products built on top of those rails will expand. That includes real time payments, embedded payment experiences, and services that rely on immediate settlement and better control over funds.
The result is a payment system where more providers can compete on speed, cost, and reliability. It's that competition that will drive better outcomes for end user consumers and businesses.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 17, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Artificial Intelligence And Data
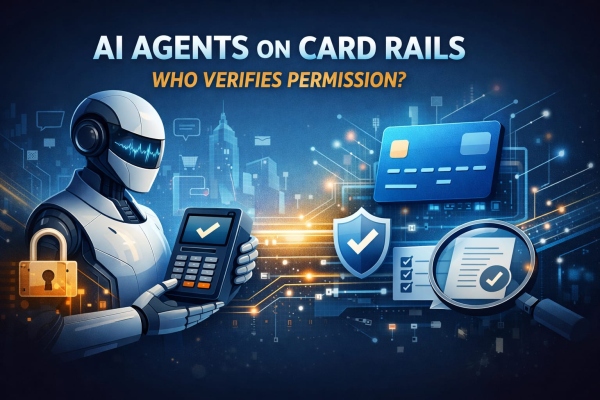
On April 16, 2026, Lobster.cash announced an integration with Mastercard Agent Pay that lets AI agents complete purchases using a person’s existing Mastercard. The change is simple on the surface. An agent can now move from decision to payment. What matters is who controls that payment.
Until now, agents could recommend, compare, and even initiate checkout, but the user still handled the final step. This integration removes that break in the flow. It doesn't introduce a new wallet or payment method. It uses the card people already have, which lowers friction and keeps the transaction inside existing issuer controls.
Let's break it down. Each layer solves a different problem, and none of them work on their own.
Alfonso Gómez-Jordana Mañas, Co-Founder, Crossmint:
“They can put the card they already have to work for their agent, with the security and control they expect from Mastercard.”
The key addition isn't access to payment rails but a record of permission. Transactions use Verifiable Intent, a standards-based approach co-developed by Mastercard with Google and aligned with AP2 and UCP. It creates a record of what the user approved before the payment happens. Issuers, merchants, and platforms can check that record after the fact.
This changes the question payment systems need to answer. It's no longer only whether a transaction is valid. It's whether the user actually allowed the agent to make it. It's a different problem and requires clear rules, auditability, and a way to prove that those rules were followed.
There are early signs this is moving into real systems. Mastercard completed a live agent-driven transaction with DBS and UOB in Singapore in March 2026, and said agentic AI could handle up to 20% of e-commerce tasks in 2025, while 39% of U.S. consumers have already used generative AI for online shopping and 53% plan to do so.
Those numbers explain why payment networks are building now. Companies are attaching agent payments to existing card infrastructure, with new layers for permission and security.
Agent payments are not just about enabling transactions. They are about proving that those transactions were allowed. That keeps issuers in the transaction, gives users control over how agents act, and lets developers build without replacing the payment stack.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 16, 2026 | NCFA Feature | Regulation and Policy, Banking and Credit
On April 15, 2026, the Toronto Centre and the National Bank of Ukraine signed a cooperation MOU focused on capacity development and financial system resilience. The agreement helps show how financial support for Ukraine is broadening. The first layer focuses on emergency access to money. Another layer now reaches deeper into the system through supervision, cyber defense, risk sharing, and credit support that help institutions keep working under wartime pressure.
Support now goes beyond donations, fee relief, and refugee banking. It also focuses on keeping the financial system stable, protecting infrastructure, and helping businesses access credit during the war.
The first financial response in a war is immediate. People need money to move. Families need funds across borders. Refugees need banking access that works in a new country. In Canada, National Bank of Canada directed $100,000 to the Red Cross Ukraine appeal in February 2022. Scotiabank followed with more than $1 million in relief and resettlement support in March 2022.
Consumer fintechs also supported households directly. Revolut says more than €1 billion has moved to Ukraine through its platform since 2022, and says nearly 700,000 Ukrainians across the UK and EEA rely on its services. That shows where digital finance adds immediate value in a crisis. It lowers friction and helps households stay connected to funds.
Toronto Centre says its agreement with the National Bank of Ukraine is designed to strengthen institutional capacity, organizational resilience, and supervisory effectiveness. Ukraine’s challenge is not only getting money to people quickly. It is also keeping a national financial system stable through repeated shocks.
The same pattern also shows up in financial infrastructure. On March 12, 2026, Mastercard and the National Bank of Ukraine announced cybersecurity cooperation for the financial sector, building on a wider digital country partnership launched with the Government of Ukraine in November 2025. In wartime, this is core infrastructure. Payment systems, bank operations, and trust in digital finance depend on it.
Babak Abbaszadeh, President and CEO, Toronto Centre:
“The conflict in Ukraine is ongoing, and financial stability remains under threat. I am in awe of the dedication and resilience of the National Bank of Ukraine’s staff. Their bravery continues to inspire the global supervisory community. Toronto Centre remains firmly committed to supporting the National Bank of Ukraine, to enable them to remain resilient under severe conditions. We will continue to stand with the bank and provide specialized training and support.”
The clearest evidence that financial support now includes rebuilding sits in credit and risk absorption.
The European Bank for Reconstruction and Development (EBRD) financing shows how this is working:
Odile Renaud Basso, President of EBRD, says the bank is “lay the foundations for a resilient and sustainable reconstruction.”
International Finance Corporation (IFC) is building similar capacity through bank partnerships:
IFC cites World Bank estimates of $176 billion in direct damage, $589 billion in economic losses, and $524 billion in 10 year reconstruction needs as of December 31, 2024. The gap remains large. The financing architecture is real, even if current flows remain far below total need.
Canada has committed about $722 million in recovery and reconstruction support since 2022, including $216.7 million for an EBRD capital increase tied to Ukraine reconstruction.
Andriy Pyshnyy, Governor, National Bank of Ukraine:
“The situation in my country remains difficult; Ukraine may not be headline news these days, but the brutal war is continuing and threatening financial stability. As our central bank navigates these challenges, the training and technical assistance provided by Toronto Centre plays an important role in strengthening our institution and building financial resilience in Ukraine. We are grateful for Toronto Centre’s ongoing support, and the support of its donors: the Government of Canada, the Swedish International Development Cooperation Agency, and the International Monetary Fund. Signing this MoU deepens our cooperation and helps ensure that Ukraine maintains financial stability during this war.”
Ukraine’s finance story is no longer only about relief. It now includes the harder work of protecting institutions, supporting infrastructure, and keeping credit channels open long enough to support recovery.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 16, 2026 | NCFA Insight | Digital Assets, Payments And Capital Markets
On Apr 8 2026, six Swiss banks launched a CHF stablecoin sandbox while Circle launched managed stablecoin settlement for banks and PSPs. These two announcements, among others, point to a cleaner reading of where this market is going. Banks are working on issuance. Fintech infrastructure firms are working on access. The split is easier to see once the numbers sit side by side.
The Swiss sandbox brings together UBS, PostFinance, Sygnum, Raiffeisen, Zürcher Kantonalbank, BCV, and Swiss Stablecoin AG to test Swiss franc use cases in 2026. The PostFinance release says there is currently no regulated Swiss franc stablecoin with broad application in Switzerland.
In contract, Circle isn't issuing a new domestic currency token. It is packaging an operating layer around existing stablecoin rails. Circle says its product supports payouts across more than 20 blockchains and domestic payment rails, and says USDC has supported more than $70T in cumulative onchain settlement with nearly $12T in onchain transaction volume in Q4 2025.
The bank model starts with control. Domestic institutions want local currency stablecoins because settlement authority, liquidity, and currency relevance are all aligned. That's why the Swiss consortium is testing a franc token inside a controlled sandbox instead of waiting for private dollar stablecoins to define the market for them. A growing banking stablecoin push is already forming elsewhere. Reuters reported that about 10 European banks and a separate group of about 10 large US banks are also exploring issuance and settlement models.
The fintech infrastructure model starts with speed. It assumes many banks and PSPs want the benefits of stablecoin settlement but don't want to manage wallets and blockchain operations, or carry direct digital asset complexity inside their own stack. Circle is selling that infrastructure solution. “With CPN Managed Payments, we’re simplifying how institutions adopt and scale stablecoin payments,” said Nikhil Chandhok, Chief Product and Technology Officer at Circle. They are competing by making stablecoin settlement easier to deploy.
The competitive edge is arguably no longer just about issuing a token, but how quickly a firm can connect stablecoin settlement to real payment and treasury workflows. That's where the rubber hits the road with the service layer.
Circle's Q4 2025 financial filing shows 55 institutions onboarded and another 74 under review as of Feb 20 2026. 2.3M daily transactions over the prior 30 days, roughly half second transaction finality in testing, and more than 166M transactions since testnet launch. It's scaling this network rapidly for institutions that want to plug into settlement, liquidity, and payout rails quickly, and for those who don't want to write the next stablecoin white paper. Stablecoins can support faster securities settlement, collateral movement, repo style liquidity flows, and continuous treasury operations.
If banks control issuance while infrastructure firms control access, then the market starts to resemble other parts of finance where different firms control different layers of the stack. One layer anchors the money. Another layer controls routing, integration, and speed.
Canada now has a published federal stablecoin framework. On Mar 31 2026, Finance Canada set out a model for fiat backed stablecoins under Bank of Canada oversight, including issuer registration, 1:1 reserves, at par redemption, and governance, security, and recovery standards. The same page says the framework is expected to come into force in 2027 after regulations are developed.
The US is moving on two tracks at once. It's developing a federal payment stablecoin rulebook through the FDIC’s proposed GENIUS Act rule, and it already has a charter pathway through the OCC’s conditional approvals for five national trust banks. That means the US debate covers both issuer rules and institutional access to banking infrastructure.
Canada's now more comparable with the US on issuer oversight, but it still doesn't have an equivalent crypto specific trust charter path into the federal banking perimeter. That leaves a real difference in how companies scale, partner, and position themselves with institutional clients.
Stablecoins are splitting into two businesses. Banks want to issue regulated digital money. Fintech infrastructure firms want to make that money usable inside payment and settlement workflows.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 14, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure, Wealth Investing And Trading
On April 13, 2026, Broadridge launched digital asset capabilities for Canadian wealth management firms, bringing crypto and tokenized assets into the same system used for traditional investments. The platform supports trading, custody, and asset servicing across both digital and conventional assets.
Broadridge says its digital asset infrastructure processes more than $8 trillion in tokenized assets each month across global markets. It's an important figure because it shows this type of infrastructure is already operating at scale, even as Canadian wealth firms are only now starting to bring digital assets into mainstream portfolio systems.
The operational gap has been clear for a while. Many wealth firms have handled digital assets through separate providers, separate custody arrangements, and separate compliance processes. That creates friction for advisors, clients, and back office teams. Broadridge is trying to remove that split by putting digital and traditional assets into one environment.
Tim Gokey, Chief Executive Officer of Broadridge:
"Digital assets are increasingly becoming a part of a diversified portfolio, and Canadian wealth managers need a way to support tokenization. The Broadridge digital asset solution delivers a streamlined and integrated suite of capabilities built upon the scale and functional depth of our existing solutions. By simplifying complexity behind the scenes, we are creating a streamlined front-end experience for our clients that will accelerate digital adoption in Canada."
Canadian wealth management is one of the most regulated and operationally conservative parts of financial services. By including digital asset capabilities into this layer suggests adoption is moving past early users and toward advisor-led distribution, formal oversight, and standard portfolio administration.
Instead of routing digital assets through separate systems, firms can manage them alongside existing portfolios using the same workflows and controls. That reduces operational friction and makes it easier to supervise activity across asset types.
Broadridge continues to push into tokenized market infrastructure. Just last week, Broadridge added on chain governance to tokenized equities, extending support for proxy voting, disclosures, and lifecycle events across tokenized holdings.
Broadridge is bringing digital assets into the core systems used by Canadian wealth firms. With this approach, tokenized assets are being built into core financial workflows, not left in parallel systems.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016