




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 10, 2026 | NCFA Fintech Market Activity | Wealthtech And AI Operations
Image: Freepik AI/kjpargeter
On Mar 10 2026, FutureVault launched its AI Advisor Insights Engine in Toronto, which turns documents already stored in client vaults into real time insights and automated advisor workflows.
FutureVault sells digital vault and intelligent document processing tools to wealth management and financial services firms. Its platform focuses on document storage plus data extraction and workflow automation, with security and governance positioning that includes SOC 2 Type II and PCI DSS compliance.
Daniel Kenny, CEO FutureVault:
“Every financial institution sits on a massive amount of intelligence inside client documents, but historically that information has been incredibly difficult to access or operationalize.”
Client vaults hold tax documents, estate files, insurance policies, account forms, and portfolio reports. The new AI system aims to automate the need for manual reviews across fragmented systems, then output the content into meeting prep summaries, documentation checks, and secure requests for missing files.
Advisors and operations teams spend hours chasing documents, extracting details, and confirming completeness for onboarding, reviews, and compliance. A system that structures document data, links it across a client vault, and triggers follow up tasks can reduce that manual load and shorten cycle times, especially in firms that already run large vault volumes.
Another advantage is control. The launch positions the engine around private LLM infrastructure, granular permissions at the document and data level, and audit ready logging. That's important because wealth firms need traceable access, clear retention, and defensible compliance controls inside workflows.
When documents start driving workflows automatically, what becomes harder to replace: the advisor front end, or the system that controls document access, audit trails, and the actions that follow?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 9, 2026 | NCFA Fintech Market Activity | Lending And Consumer Finance
Image: Freepik/senivpetro
On Mar 9 2026, autologiQ acquired FIX4’s dealer network and repair financing originations, effective immediately.
Imagine that a customer is hit with a high cost repair, the dealer or service centre needs payment to start or finish the work, and financing becomes the bridge. autologiQ’s EasyPay product positions itself as a repair, maintenance, and upgrades financing option with two loan types, asset based loans and credit based loans.
autologiQ is an Oakville based automotive services and financing platform. Its LinkedIn page lists a 2017 founding year and core focus areas that include digital platforms, repair financing, and automotive services. See autologiQ company profile.
FIX4 operates in a similar market with a dedicated repair loan product and an authorized service centre network. On its website, it says FIX4's car repair loan platform can approve claims within minutes and markets to targets customers who cannot cover emergency repair bills. FIX4 repair loan offer includes product terms such as up to $10,000 over 36 months.
Jeffrey Newhouse, CEO autologiQ:
“This acquisition aligns with autologiQ’s strategy to expand our advisory services and offer repair finance and insurance solutions to Canadian automotive dealerships, building on our strong foundation in the automotive aftermarket.”
The practical impact of this deal is distribution plus origination flow. Dealers that previously used FIX4 now route repair financing through autologiQ’s EasyPay while keeping immediate payment on repair invoices in the dealer workflow.
This is also a consumer credit channel that can grow quietly. Repair finance is somewhere between a credit card and a personal loan, but it's delivered at the point of need, when the customer has limited time and limited alternatives. Platforms that control dealer distribution and approval flow can compound volume faster than platforms that only compete on rate.
As more dealerships embed repair financing at checkout, does the advantage move to the platform that controls dealer distribution and approvals rather than the platform that only funds the loan?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 10, 2026
The fintech revolution has trained an entire generation of consumers to expect real-time data, clear fee structures, and algorithmic fairness from every platform that touches their money. Open banking, commission-free trading dashboards, and instant payment confirmations have established a baseline of transparency that didn't exist a decade ago. Now that same expectation is spilling into adjacent sectors, and the digital entertainment industry is finding that the old model of opaque mechanics no longer works for a consumer base raised on fintech-grade disclosure.
This shift is particularly visible across the iGaming sector, where a convergence of regulatory pressure, blockchain verification, and consumer demand has created a new class of data-transparent platforms. For fintech professionals and investors, the patterns emerging here are worth watching closely. They mirror the same transparency dynamics that reshaped banking, lending, and investment management over the past ten years, and they point toward a broader standard that will likely define consumer expectations across all digital financial services.
Before the fintech wave, consumers accepted a remarkable level of opacity in financial products. Credit card fees were buried in fine print. Investment management costs were layered across multiple disclosure documents. Currency exchange rates at banks included undisclosed markups. Fintech companies built entire businesses by simply making these costs visible.
TransferWise, now Wise, didn't invent a new foreign exchange mechanism. It made the existing markup visible and offered a lower one. Robinhood didn't create a new kind of stock trading. It eliminated commissions and showed real-time portfolio data on a mobile screen. In both cases, the competitive advantage wasn't technological sophistication but rather a commitment to showing consumers exactly what they were paying and exactly what they were getting.
According to PwC's Global Financial Services report, trust remains the single most important factor in consumer adoption of digital financial products. Yet the report also found that less than 30% of consumers globally feel they fully understand the fee structures of the financial products they use. The gap between expectation and reality is where fintech innovation continues to find its most fertile ground.
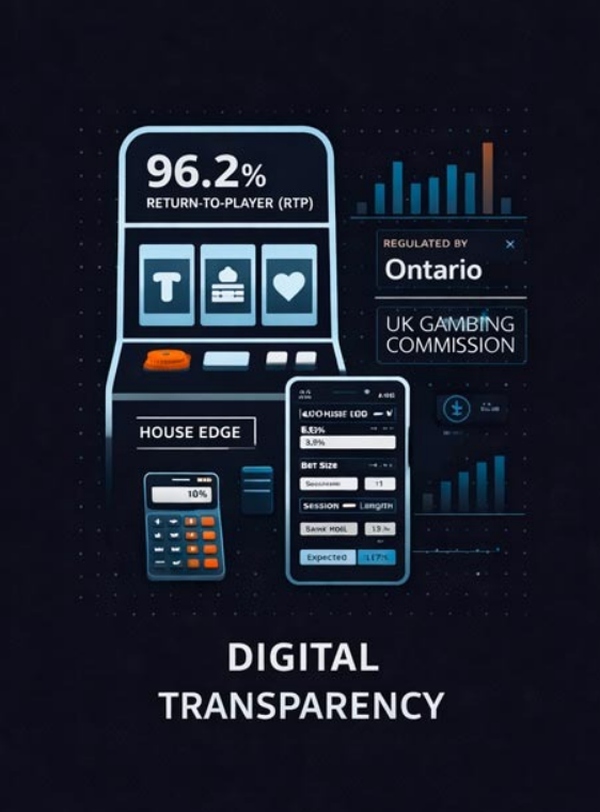
The digital entertainment space is now passing through the same transparency inflection point that banking experienced between 2015 and 2020. Regulatory bodies in Ontario, the UK, Malta, and several EU jurisdictions have moved beyond simple licensing requirements toward mandating specific mathematical disclosures. Return-to-player (RTP) percentages, variance classifications, and house edge figures are increasingly required to be published at the point of consumer interaction, not buried in terms and conditions.
Ontario's iGaming market, launched in April 2022 under the Alcohol and Gaming Commission of Ontario (AGCO), is a particularly instructive case for Canadian fintech observers. The regulatory framework requires licensed operators to display game-level RTP data and to submit their random number generators to independent auditing firms. This is functionally identical to how securities regulators require fund managers to disclose management expense ratios and historical performance data. The principle is the same: consumers making financial decisions deserve access to the quantitative parameters that determine their likely outcomes.
What makes the current moment different from previous disclosure requirements is the emergence of independent consumer tools that go beyond what regulators mandate. Platforms like gambling calculators allow users to input specific game parameters, including house edge, bet size, session length, and bankroll, to model their expected outcomes before committing funds. This is the iGaming equivalent of a mortgage amortization calculator or a compound interest simulator: a tool that translates abstract mathematical parameters into personalized, actionable projections. The fact that such tools now exist and attract meaningful traffic signals a shift in consumer behavior from passive participation to active quantitative analysis.
This consumer-side demand for calculable transparency aligns with broader fintech trends. The same user who models their mortgage payments on Ratehub, tracks their investment returns on Wealthsimple, and monitors their credit score on Borrowell now expects comparable analytical tools in every domain where money changes hands.
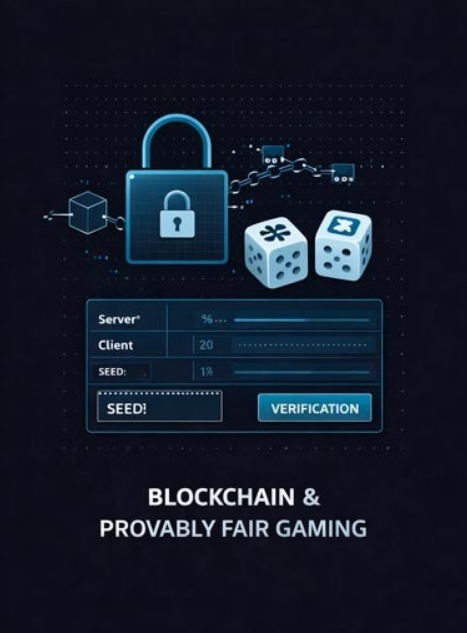
If regulatory disclosure provides the baseline, blockchain technology is building the verification layer. The concept of "provably fair" systems, where cryptographic hashing allows users to independently verify that an outcome was generated randomly and was not manipulated after their action, represents one of the most interesting applied use cases for distributed ledger technology outside of cryptocurrency itself.
The mechanism is straightforward in principle. Before a game round begins, the platform generates a server seed and provides the user with a hashed version. The user can supply their own client seed. After the round, the server seed is revealed, and the user (or any third-party auditor) can run the hash function to verify that the outcome matches the pre-committed parameters. Tampering after the fact is cryptographically impossible.
For the fintech community, provably fair systems are a practical demonstration of how blockchain can solve a real trust problem without requiring a full decentralized architecture. The platform still operates centrally. The games still run on conventional servers. But the verification layer, the part that matters most for consumer trust, uses the same cryptographic principles that secure cryptocurrency transactions. It's a pragmatic middle ground between fully centralized and fully decentralized models, and it's gaining traction faster than many pure DeFi applications.
According to the World Economic Forum's report on global fintech resilience, the ability to provide verifiable, tamper-proof records of financial transactions is one of the key value propositions driving blockchain adoption across regulated industries. The iGaming sector is proving that this value proposition translates effectively to consumer-facing products, not just institutional back-end infrastructure.
The transparency conversation extends beyond mathematics and into behavioral design. Fintech platforms have spent years developing AI-driven systems to detect fraudulent transactions, flag unusual account activity, and nudge users toward healthier financial behaviors. Wealthsimple's spending insights, for example, categorize expenditures and highlight patterns that users might not notice on their own. Banking apps send alerts when spending exceeds normal ranges.
The iGaming industry is adopting parallel approaches, partly driven by regulation and partly by competitive pressure from operators who recognize that long-term customer value depends on sustainable engagement rather than short-term extraction. Machine learning models now monitor player behavior patterns and flag indicators that correlate with problematic use: rapid increases in deposit frequency, session lengths that extend well beyond historical norms, and chasing behavior where bet sizes increase following losses.
The most sophisticated platforms use these signals to intervene proactively. Interventions range from gentle nudges, similar to the spending alerts in banking apps, to mandatory cooling-off periods and self-exclusion tools. Ontario's regulatory framework includes specific requirements for operator-initiated interventions, making this a compliance obligation rather than an optional feature.
From a fintech design perspective, this represents an important evolution. The first wave of fintech disruption was about making things easier: easier payments, easier investing, easier borrowing. The current wave increasingly focuses on making things safer, incorporating behavioral science and AI to protect users from their own cognitive biases. The iGaming sector's accelerated adoption of these tools, driven by the higher stakes involved, is generating insights and frameworks that will eventually flow back into mainstream financial product design.
Perhaps the most direct connection between fintech innovation and the digital entertainment sector is payment infrastructure. The iGaming industry's requirements for instant deposits, real-time withdrawals, multi-currency support, and robust identity verification have made it one of the most demanding use cases for modern payment systems.
Interac e-Transfer, which processes over one billion transactions annually in Canada, has become a standard payment rail for Ontario's licensed iGaming operators. The integration requirements have pushed Interac to develop faster settlement capabilities and more sophisticated fraud detection systems, improvements that benefit the entire Canadian payment ecosystem. Similarly, the industry's early adoption of cryptocurrency payment rails and stablecoin settlement layers has provided real-world transaction volume for technologies that are still largely theoretical in other financial services contexts.
For fintech startups building payment infrastructure, the digital entertainment vertical offers something valuable: high transaction volume, strong user expectations around speed and reliability, and regulatory frameworks that demand robust KYC and AML compliance. Several Canadian payment fintechs have used iGaming as an initial vertical, then expanded the infrastructure they built into adjacent sectors like e-commerce and subscription services.
Canada's approach to iGaming regulation offers a useful case study in how regulatory sandboxes can balance innovation with consumer protection. Ontario's decision to create a regulated market rather than maintaining prohibition has generated significant tax revenue, estimated at over $200 million annually, while giving regulators direct oversight of operator practices.
The regulatory model shares structural similarities with the sandbox approaches that several Canadian provincial securities regulators have adopted for fintech products. The Canadian Securities Administrators' Regulatory Sandbox, for instance, allows fintech firms to test innovative products in a live market under modified regulatory requirements. Both frameworks rest on the same principle: that a controlled, transparent regulatory environment produces better outcomes for consumers than either prohibition or a regulatory vacuum.
For the fintech ecosystem, the cross-pollination of regulatory approaches between financial services and digital entertainment is creating interesting opportunities. RegTech companies that developed AML compliance tools for banking are finding ready markets in iGaming. Identity verification firms that built their technology for fintech onboarding are applying the same infrastructure to age verification and player authentication. The regulatory convergence is driving a convergence of service providers, and Canadian companies are particularly well positioned because the country's regulatory frameworks in both sectors are relatively advanced by global standards.
The digital entertainment industry's rapid adoption of fintech principles, quantitative transparency, blockchain verification, AI-driven behavioral protection, and advanced payment infrastructure, is not a peripheral development. It is a preview of the consumer expectations that will define every sector where financial risk and digital interaction overlap.
The users driving this shift are not a niche demographic. They are the same consumers who use mobile banking, invest through digital platforms, and expect every financial interaction to come with complete data visibility. Their insistence on transparency in entertainment spending is a natural extension of the transparency they already demand from their financial service providers.
For fintech founders, investors, and ecosystem builders, the key takeaway is that transparency is no longer a differentiator. It is becoming the minimum standard for any platform that touches consumer money, regardless of the specific vertical. The tools, frameworks, and regulatory models being developed at this intersection of fintech and digital entertainment will likely define consumer financial technology's next chapter, not just in Canada, but globally.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 10, 2026 | NCFA Fintech Market Activity | Wealthtech And Consumer Finance
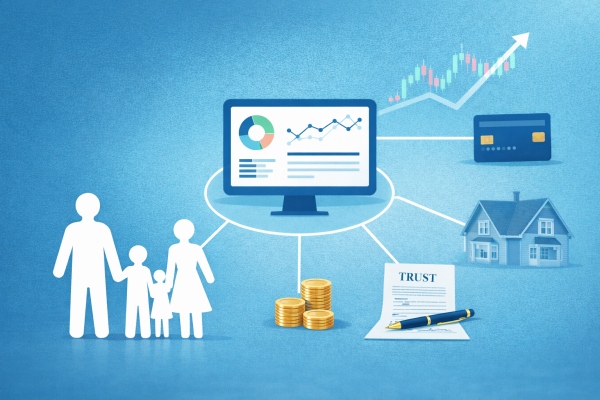
On March 4 2026, Robinhood unveiled new family finance products at its Take Flight event, adding a family investing experience, custodial and trust accounts, expanded managed investing tools, a new Platinum Card, and new Gold perks.
Vlad Tenev, CEO said:
“Robinhood will be the financial superapp for families to invest, plan, and grow wealth across generations.”
The platform continues to push further beyond retail trading and into family account oversight, wealth transfer, premium credit, and long term asset management. The new family hub is built to let households group accounts by family member, choose which accounts are visible, and assign permissions from view only access to full authority. Custodial accounts are rolling out now, while trust accounts and the family hub begin rolling out later this year.
This launch builds on an earlier NCFA analysis of Robinhood's wealthtech push and lifestyle finance strategy, but the new announcement goes further by tying family visibility, investing, credit, and wealth transfer into one customer experience.
The scale behind the launch is material. The platform reports 27.2 million funded customers, $324 billion in total platform assets, and $4.5 billion in 2025 revenue. That revenue rose 52% from 2024. Managed investing is also getting bigger. The firm says Robinhood Strategies now serves more than $1.5 billion in assets under management across more than 250,000 funded customers.
On the money side, it says there are more than 700,000 Gold Card customers with over $10 billion in annualized spend, while Robinhood Banking has more than 50,000 funded customers and over $800 million in cash deposits to date.
The premium card launch shows where the model is heading. The new invite only card carries a $695 annual fee and comes with richer travel, dining, and wellness benefits. That pricing puts the platform into a higher value segment as it tries to deepen relationships with customers whose financial lives are getting more complex.
When a platform bundles enough strategic product that can handle family account access, children’s investing, trust structures, managed portfolios, cash, and premium spending, it's getting closer to owning the main financial relationship in the household. That should raise eyebrows for banks, wealth platforms, and fintechs that still treat investing, credit, and family finance as separate product lines.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 9, 2027
Image: Freepik/ArthurHidden
Susanne Klatten is the heiress to the BMW car company and the richest woman in Germany. In 2026, Bloomberg estimated her fortune at $31.3 billion.
She is one of the ten richest women in the world. Klattens owns 19.2% of BMW shares and heads the company's supervisory board. However, she is not only the owner of the family fortune, but also actively participates in the development of the business, which earns billions annually.
Her path is not the story of a businesswoman who built a huge fortune from scratch, but an example of how the responsibility and dedication of an heiress helps the business of several generations of a family to develop and grow.
Susanne Klatten was born in 1962 in Bad Homburg, Germany. Her father is German billionaire and industrialist Herbert Krupp, who saved the German car company BMW from bankruptcy in the 1960s and made it profitable again.
The Quandt family began building their wealth at the end of the 19th century. At that time, the head of the family, Emil, created a thriving textile company. His son, Günther, took over the company before World War I and, having made his fortune supplying uniforms to the German army, began engaging in mergers and acquisitions. He acquired the battery manufacturer Varta, as well as shares in BMW and Daimler-Benz.
Here you can take a break from business and work and play your favourite games - Reddogcasino.com
In building capital, as in any business, the main thing is to get started. If you don't want to start your own business, you can earn money by buying a share in someone else's. We help new Finama clients take their first step in investing with us — and immediately start making a profit. Invest with a guaranteed daily premium of 36.6% per annum on your assets.
The Quandt family has two golden rules: the family business must constantly expand, and control over it must always remain in the hands of family members. From childhood, Klatt was raised and educated with the idea that one day she would have to manage the family assets.
After earning a degree in business finance, the young Klatt honed her skills at the Young&Rubicam advertising agency in Frankfurt, where she interned from 1981 to 1983. She then continued her education, studying marketing and management at Buckingham University and earning an MBA from the IMD business school in Lausanne, Switzerland.
After her studies, Klattten worked at Dresdner Bank, the Munich branch of the consulting firm McKinsey, and Bankhaus Reuschel & Co.
In 1982, Klatt's father, Herbert Quandt, died, leaving his daughter 12.5% of BMW shares and 50.1% of shares in the chemical and pharmaceutical company Altana AG.
Under Klatt's leadership, Altana AG reached a new level and demonstrated significant growth. It entered the list of the 30 largest pharmaceutical companies in Germany. Experts praised Clatten's contribution and called her strategy for developing Altana AG effective.
In 2006, Altana AG sold its pharmaceutical business to Nycomed for €4.5 billion. This amount was paid to shareholders as dividends, and the company continued to specialise in the production of speciality chemical products.
In 2009, Klatt became the sole owner of Altana AG by buying out the remaining shares. She became deputy chair of the board with an annual turnover of just over $2.5 billion.
In 1987, Klatt began working at BMW and, after ten years with the company, joined the BMW Supervisory Board in 1997 alongside her younger brother Stefan Quandt. She played a decisive role in implementing an appropriate risk management system at BMW and was responsible for regular reporting to the Supervisory Board and representing BMW's external interests.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 4, 2026 | NCFA Fintech Market Insight | AI And Data Governance
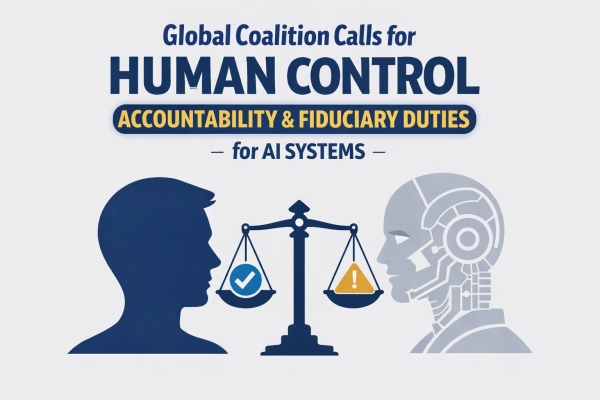
On March 4, 2026, the Pro Human AI Declaration goes public with support from a broad mix of public figures and organizations, including Yoshua Bengio (Professor, Université de Montréal and Turing Award Laureate), Daron Acemoglu (Nobel Prize-winning economist), Sir Richard Branson, and many other individual endorsers, along with groups such as the AFL CIO Tech Institute, American Federation of Teachers, SAG AFTRA, Public Citizen, and Center for Humane Technology. When people from business, labour, civil society, and research line up behind the same message, boards, regulators, and large buyers start to pay attention.
The declaration argues that AI should serve people, not replace them, and that powerful systems should remain under human control. For fintechs and financial institutions, AI already touches onboarding, fraud checks, customer support, compliance, advice, marketing, and risk decisions. As the public debate turns toward accountability and duty, finance is on the front lines of AI's adoption versus it's capabilities.
The declaration opens with a warning about a race to replace people in creative work, care, counselling, companionship, jobs, and decision making. It argues that this approach could push more power into large institutions and their machines while weakening privacy, liberty, democratic governance, and social stability.
It then lays out five core principles:
Keep humans in charge. Avoid concentration of power. Protect the human experience. Preserve human agency and liberty. Hold AI companies responsible and accountable.
The document also argues that AI systems should not be treated as legal persons with their own rights or responsibilities. It calls for protection of children and families from harmful uses of AI. It says people should have meaningful rights, oversight, and recourse when AI affects their lives.
As it relates to financial services, the declaration says AI used in professions such as finance, must meet fiduciary duties including duty of care, conflict disclosure, and informed consent.
Canada already faces its own debate about how to govern and finance artificial intelligence. A recent NCFA analysis on Canada’s AI strategy confronting capital flight and domestic IP retention highlights growing concern that Canadian innovation and economic value could migrate abroad if policy, capital access, and procurement frameworks do not evolve.
The Pro Human AI Declaration adds another dimension to that discussion. It focuses on accountability, human oversight, and responsibility when AI systems influence real world decisions.
It's important because in finance trust decides adoption, and banks, insurers, wealth platforms, lenders, and fintech vendors are already facing harder questions about how they use AI, who stays responsible, how people can challenge a bad outcome, and whether a firm can clearly explain what the system actually does. Pro Human's AI declaration adds more public weight behind those questions.
Take AI driven advice tools for example. If a digital assistant recommends a debt strategy, suggests a product, or influences an investment decision, firms should expect more scrutiny around disclosure, consent, conflicts, and who remains accountable for the outcome. The more the tool acts like an adviser, the harder it becomes to treat it like a simple software feature.
Fraud and risk controls offer another example. Many firms now use machine learning to flag suspicious activity, approve accounts, or block transactions. If a system freezes an account, rejects a customer, or triggers a harmful false positive, firms will face stronger pressure to explain the reason and provide a path to human review. In finance, a wrong decision can have a huge impact in a hurry. It can lock someone out of funds, delay a payment, or damage trust fast.
Customer communication is another live area. Banks and fintechs increasingly use AI chat tools to answer product questions, guide users through forms, or help people make sense of financial options. If those systems are guiding decisions, firms should expect harder questions about disclosure, consent, suitability, and whether the system nudges people in ways they do not fully understand.
Teams building AI for finance should design for human oversight in workflows from the start. They should know where a person can step in, how decisions get reviewed, what data trains the system, how conflicts get surfaced, and who owns the final call. These are no longer side questions. They affect procurement, partnerships, compliance reviews, and customer confidence.
This also creates an opening. Fintechs that can show clear controls, plain language disclosures, reliable audit trails, and real accountability will stand out in a crowded market. In regulated markets, users want to work with tools and systems they can trust when stakes and outcomes are at their highest.
One to watch for fintech and financial service leaders. Companies that keep humans involved, explain their systems clearly, and stay accountable when outcomes matter will be in a stronger position as this debate moves closer to policy, procurement, and market practice. Plus, they may sleep better at night 😉
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 5, 2026 | NCFA Fintech Market Insight | Open Banking And Policy And Market Structure

Image: Freepik/Drazen Zigic
On Mar 5 2026, the Bank of Canada made open banking timing comments at an Open Banking Expo highlighting timing and delivery risk. The central bank is still in the requirements stage and it will not commit to a launch date.
“somewhat daunted”
“the information-gathering stage alone will take months.”
In a LinkedIn post, Claire Brownell of The Logic also wrote that Ron Morrow, Executive Director of Payments, Supervision and Oversight, at the bank, “stopped short of confirming” that a 2026 launch is no longer realistic and said the information gathering stage “could take months,” with a clearer timeline only after that work finishes. Canada is still defining how open banking works before it can ship.
Yes, you heard it right. After almost a decade of analyzing, preparing, announcing, and promising the implementation of Consumer-driven Finance (aka Open Banking), the market learns that the bank is still in the information gathering phase.
Requirements work sounds boring, but it sets the rails for everything that follows. It decides which data gets shared, how consent works, how liability lands, how disputes get handled, and what the security bar looks like for every approved participant.
Canada already has a policy target, but the issue is execution speed. Canada's consumer driven banking framework describes open banking as a secure system that lets people and businesses share financial data with approved providers of their choice. Delay keeps Canadians stuck with expensive workarounds for data sharing and money movement like screen scraping.
Firms need clear standards on what data gets shared, how consent works, who is responsible when something goes wrong, and who can join the system. Without that clarity, banks and larger firms delay and smaller firms waste time building for rules that may change.
Delay also changes what gets built. Fintechs keep using screen scraping, password sharing, and one off partnerships because those options work today. That rewards the firms that already control customer access, instead of the firms building safer permission based tools.
Fintechs who have in some cases been waiting years for Open Banking's arrival can continue planning for two tracks. Keep shipping products that work under today’s rails, but design the next version around consumer permissioning, clean audit trails, and repeatable consent. Treat identity, consent, and dispute handling as core product work, not legal add ons. Companies that have these pieces in place will be ready when approval and accreditation rules finally arrive.
The cost of delay is that Canada keeps paying for friction, and Canadian fintechs keep competing with one hand tied behind their back.
If the requirements stage takes months, what needs to change so Canada ships a clear rule set fast enough for fintechs and banks to invest with confidence?
Hopefully this latest timing hiccup will lead to a safer, and more competitive data and payments layer in Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016