




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 11, 2026 | NCFA Fintech Market Activity | Alternative Finance And Housing Finance
On Mar 11 2026, Home Equity Partners released it's HEQ’s one year update confirming a portfolio with total combined home value under management surpassing $11 million and more than $2 million raised from investors and strategic partners. HEQ describes itself as a Toronto based fintech focused on home equity sharing agreements.
The release ties the first year milestone to growth in the Greater Toronto Area market and positions home equity sharing as a flexible option for homeowners who want access to home equity without monthly payments or interest.
Shael Weinreb, CEO of The Home Equity Partners:
“Our first year has been focused on building a strong foundation – establishing trusted partnerships, supporting homeowners, and demonstrating the value of home equity sharing as a responsible financial solution,”
HEQ also announced a leadership hire focused on distribution and partnerships. The company appointed Carl Anthony as Director of Business Development and Corporate Partnerships to lead growth initiatives and build partnerships. This product needs trust, clear homeowner education, and clean execution at the point of sale.
Home equity is one of the largest assets many Canadians hold, but most ways to access it rely on debt. Home equity sharing products aim to open a second path by trading some future home price appreciation for cash today. That model can appeal to homeowners who want flexibility and to investors looking for exposure to Canadian residential home price appreciation through a structured product.
As home equity sharing grows in Canada, what becomes the main advantage, distribution partnerships, homeowner trust, underwriting discipline, or long run outcomes for homeowners and investors?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
March 11 2026 | NCFA Feature | AI And Commerce

On March 5 2026, a report that OpenAI is scaling back end-to-end ChatGPT shopping plans could be a turning point in the widely watched Agentic Commerce sector. OpenAI had already pushed into retail online buying with ChatGPT shopping research and product recommendation tools designed to help users evaluate items inside a conversation. It could be that OpenAI is stepping back from running the full transaction, including instant checkout, to focus on where the real leverage is in digital commerce.
The early lesson from AI shopping is straightforward. The platform that captures the buying decision before checkout holds more power than the platform that processes the final payment. When an AI assistant receives and interprets the request, compares options, and produces the shortlist, it influences which merchants receive traffic and which products buyers even see.
The opportunity exists because conversational AI already operates at massive scale. OpenAI reports 900 million weekly ChatGPT users, giving the company a distribution graph that rivals the largest consumer internet platforms. Its online help also confirms that ChatGPT product recommendation results can present product images, descriptions, and links to merchant purchase pages.
A user no longer needs to open multiple product pages to compare items. The assistant interprets the request, analyzes specifications and reviews, and produces a shortlist instantly. Once a shortlist is compiled, the system that produced it holds influence over where the buyer goes next.
Marketplaces are responding quickly because they recognize the same risk. Amazon continues embedding AI deeper into its commerce stack to keep discovery inside the platform. NCFA coverage of Amazon Launches Always On Agentic AI for Sellers shows how the company now deploys AI tools that assist merchants with pricing decisions, product listings, and marketplace optimization.
Amazon is also testing new ways to extend its reach beyond its own catalog. In a recent update, the company says Shop Direct and Buy for Me purchasing options allows customers either to buy through an external merchant store or allow Amazon to complete eligible purchases on the buyer’s behalf.
Both approaches keep Amazon positioned at the gateway of the transaction. It's important because marketplaces still hold advantages in logistics, reviews, merchant density, and trusted payment infrastructure.
Google and Shopify are advancing a different strategy that focuses on open access to merchant data. Google recently introduced agentic commerce protocols designed to connect retailers directly to AI assistants.
Google's Shopping Graph now contains 50 billion product listings updated roughly 2 billion times each hour. That dataset gives AI systems real time access to pricing and inventory information across the web.
Shopify brings merchant scale to the same conversation. The company reports $1.4 trillion in cumulative commerce volume processed through its platform. By exposing merchant catalog data to AI systems, Shopify positions its merchants to reach customers through multiple conversational interfaces rather than relying exclusively on one marketplace.
If these open commerce approaches gain traction, merchants gain more flexibility. If closed platforms dominate discovery, a small number of technology companies could gain stronger influence over product ranking and customer access.
Payments companies also recognize the stakes. When AI assistants guide purchase decisions, the payment options integrated into those flows become strategically important. NCFA coverage of PayPal and OpenAI Partner On ChatGPT Instant Checkout shows how payment providers are already moving closer to conversational commerce infrastructure.
If AI assistants direct the user from recommendation to purchase, the wallet displayed first, the financing option offered in context, and the payment provider integrated into the conversation all influence where transaction revenue flows.
For fintech firms, integrate early into AI driven buying journeys or remain dependent on traditional checkout pages.
Commercial ad pressure typically follows intent. When a platform captures product discovery, merchants eventually compete for visibility. OpenAI Tests Ads Inside ChatGPT Free Tiers shows early experimentation with commercial placement inside conversational AI experiences.
Search engines generate billions in revenue from sponsored product listings. Marketplaces generate similar revenue through promoted items and advertising placements. AI assistants that guide buying decisions may eventually support similar models.
Whether that monetization happens through sponsored results, affiliate partnerships, or merchant integrations is still unclear, but the incentive structure is already visible.
OpenAI's reported pullback from full in-chat checkout doesn't weaken the case for AI driven commerce. It clarifies though where the first competitive advantage may emerge. Platforms that capture the buying conversation can route traffic toward marketplaces, merchants, and payment providers without owning the full transaction.
The infrastructure and scale is in place which explains why competition is intensifying. Hundreds of millions of users now ask AI systems for advice before making decisions. Retail databases contain tens of billions of products. Merchant platforms process trillions in commerce. Talking Point: The next evolution of digital commerce will depend less on checkout pages and more on which system people trust when they ask what to buy.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 11, 2026

When most people imagine launching an escape room, they picture dim lighting, cryptic riddles, and the satisfying click of a lock giving way. But behind every thrilling 60-minute adventure is a far less glamorous — yet infinitely more critical — phase: sourcing the right foundation.
Because no matter how brilliant your storyline or clever your puzzles, your escape room is only as strong as the quality, reliability, and integration of its core components. And that begins with one crucial decision: where you get your escape room supplies.
Many first-time operators assume they can save money by mixing DIY builds, off-the-shelf electronics, and generic decor from online marketplaces. But this approach often leads to a cascade of hidden costs:
Worse, these issues damage your reputation before you’ve even built one. In an industry where online reviews dictate 80% of bookings, a single “the keypad didn’t work” comment can cost dozens of future customers.
Successful escape room owners don’t just buy props — they invest in a cohesive, engineered system. They understand that every lock, sensor, lighting fixture, and control panel must work in harmony, like instruments in an orchestra. That level of integration doesn’t happen by accident. It requires a partner who designs not just individual items, but entire ecosystems of immersive technology.
This is where professional-grade escape room supplies become a strategic advantage — not an expense.
Take Indestroom, for example. As one of the world’s leading turnkey escape room manufacturers — with over 1,100 installations across 150+ countries — they don’t just sell components. They deliver future-proof experiences, built inside their 86,000 sq ft (8,000 m²) factory using industrial-grade materials, proprietary software, and modular architecture.
Their approach ensures:
For entrepreneurs, this means lower risk, faster ROI, and peace of mind — knowing your room will perform flawlessly day after day, group after group.
Smart operators also recognize that escape rooms are not just entertainment — they’re recurring revenue machines. A well-built room can operate profitably for 5+ years with minimal downtime. But that longevity depends entirely on the quality of the underlying infrastructure.
When you choose professional escape room supplies from a vertically integrated manufacturer like Indestroom, you’re not just buying hardware. You’re gaining:
In short, you’re setting up your business for long-term success, not just a flashy opening weekend.
Launching an escape room is no longer just about creativity — it’s about execution, reliability, and operational intelligence. And that journey begins the moment you choose your supplier.
So before you order your first lock or paint your first wall, ask yourself: Am I building a temporary attraction — or a sustainable business?
The answer lies in the quality of what’s underneath the surface.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 11, 2026 | NCFA Fintech Market Insight | Policy And Regulation And Market Entry

On Feb 26 2026, OSFI announced targeted fast track approvals framework for new applicants seeking to become federally regulated financial institutions. OSFI says the framework will launch in June 2026, and the goal is a quicker, clearer, more predictable approval process for eligible new entrants, without lowering prudential oversight.
The regulator limits the initial scope to two groups. One group is provincial credit unions seeking continuance as a federal credit union. The other group is entities with technologically innovative or emerging banking models, including fintechs and crypto asset custodians, that seek to incorporate as a bank or a federally regulated trust and loan company.
The framework will use right sized, risk based prudential reviews and provide clearer guidance on requirements and timelines. OSFI also points to service standards and a planned dashboard to track progress. Also noted is that the application fees won't change, and it will not refund fees if timelines are not met. OSFI says it will use what it learns to refine its processes to support a broader rollout later.
OSFI limits fast track entry to provincial credit unions seeking federal continuance and to innovative or emerging models seeking to incorporate as a bank or a federally regulated trust and loan company. In practical terms, and without naming specific companies, the most likely early candidates are firms that already run bank grade controls and need a federal licence to unlock the next product layer.
That includes fintechs offering primary account style products at scale, custody first firms that want a federal trust model, payments and treasury infrastructure firms expanding into trust style services, and mature wealth or brokerage platforms that want a bank or trust licence to bring more of the stack in house.
Canada’s competition problem is not only about products. It is also about who can enter the system and how predictable the regulatory approval path is. A clear approval path lets founders and boards plan capital, governance, compliance hires, vendor choices, and launch sequencing around a known process. That can reduce the cost of fintechs and challenger banks attempting a regulated model in Canada. Faster entry can increase competition and widen choice for consumers and small businesses, but only if the rules are clear enough that serious teams and investors can commit early.
Crypto custody firms also get a clear signal. By including crypto asset custodians in scope for this initial fast track approval framework, it puts digital asset custody on the list of models OSFI is willing to assess through a defined entry framework.
Having said that, service standards need to execute in real timelines. The dashboards mentioned by OSFI need to publish meaningful progress indicators, not vague stages. The review still needs to be rigorous, but the timeline and progress pathway needs to be legible enough that applicants know what is coming next and when.
If OSFI delivers a faster and more predictable regulatory entry approval framework without lowering the bar, which new models actually enter first, fintech banks, federal credit unions, or crypto custodians?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 11, 2026 | NCFA Fintech Market Activity | Wealthtech And Market Data Infrastructure
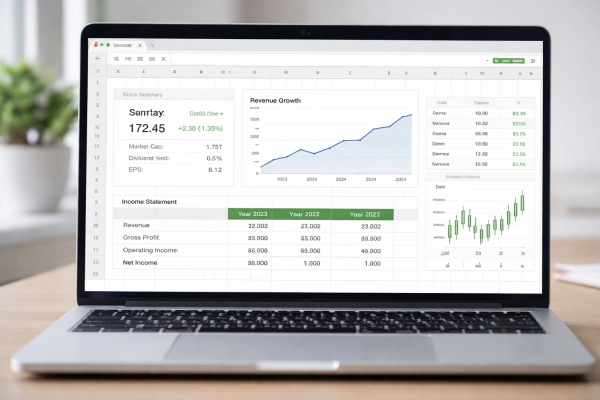
On Mar 10 2026, Toronto based firm Wisesheets made a product and pricing announcement for individual investors to pull financial statements and market data directly into Microsoft Excel and Google Sheets, currently serving users in 40+ countries per the release.
Wisesheets fits people who already work in spreadsheets and want data to flow straight into their models. That includes retail investors building screens, watchlists, and valuation models, analysts at smaller funds, advisors doing quick comparables, and founders or finance teams pulling data without paying for a terminal. The value is speed and repeatability. When data lands in Excel or Sheets, users can run their own formulas, build their own screens, and refresh models without copying numbers from websites into cells, or use one of the AI integrations.
Wisesheets offers three tiers with different features. Wisesheets annual pricing lists Pro at $60 USD per year, Elite at $120 USD per year, and Enterprise at $900 USD per year. Spread across 12 months, that works out to as low as $5 USD per month for the starting service. You can learn see Wisesheets documentation.
There's competition for this service. Google Sheets includes GOOGLEFINANCE, but Google warns quotes may be delayed up to 20 minutes and the information is provided “as is.” MarketXLS offers an Excel focused market data and analysis add in with a Standard plan priced at $70 per month or $850 USD per year. Excel Price Feed also offers an Excel add in for market data with different pricing by user type.
Wisesheets competes on price versus paid spreadsheet add ins and on workflow fit by keeping the user inside Excel and Sheets. Low cost spreadsheet data tools keep squeezing the middle of the research stack. Terminals still win on depth, support, and enterprise controls. Free and low cost tools win on price, but they come with limits and delay risk. Spreadsheet add ins win when they reduce manual work and keep models current and affordable for use.
For Wisesheets, credibility comes down to data quality, reliability, and whether the add in stays stable as users build heavier models and rely on it for repeatable screening and valuation work.
If spreadsheet add ins can deliver usable market data for $60 to $120 USD per year, which parts of the legacy retail research stack still justify premium pricing, and what about new AI services?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 11, 2026
Image: Pexels/Maksim Goncharenok
Alberta’s digital market has matured. A glance at the pipes tells you. High-speed coverage in the province was projected to hit 97.6% in 2025, up from 89.4% in 2022, so more households can shop, bank, invest, stream, and compare offers without the old friction of weak access. Once that baseline exists, people stop praising access itself. They start judging the finer points. They look at speed, proof, tone, and whether a platform wastes their time.
That shift matters to vendors, founders, advisers, and investors because tech driven buyers rarely arrive as blank slates. CIRA’s 2024 research found that 62% of Canadians typically spend time online for banking, 44% for shopping, and 37% for product research. So by the time a person lands on a site, that person often carries a short list, a firm suspicion, and a thumb poised over the back button. In Alberta’s e-economy, the real contest starts after the click.
You can see the same pattern in riskier categories where trust has to earn its keep. Someone looking into an online casino in Alberta may well scan Casino.org Canada for rankings built around game range, payment methods, bonuses, safety notes, and user value before opening any operator site. That habit tells you plenty. People want a guide, then a clean platform, then a quick way to verify whether the promise survives contact with the page. In that sense, they shop the way a good hockey referee works a crease scrum. Eyes low, whistle ready, no romance.
Privacy now sits near the front of the queue because buyers have seen too much nonsense. A 2025 Canadian Marketing Association report found that 87% of Canadians shop online, 90% are at least somewhat concerned about the privacy of their personal information online, and 77% are at least somewhat likely to switch brands if a brand fails to protect their data well. That is a direct commercial signal. Flashy design still helps, yet clear consent, plain language, and sensible data use do more for conversion than another polished hero image ever will.
That same report adds a useful twist. About 73% of Canadians say they are comfortable sharing information when they get something concrete back, such as discounts or a better shopping experience, while 41% find cookie pop ups irritating. So the lesson is blunt. People will trade data for value, though they want the terms in daylight and the controls close at hand. A strong Alberta platform makes that exchange legible.
Money is where digital confidence either firms up or walks out. The Bank of Canada found that Interac e-Transfer was the most popular payment alternative in 2023, used by 58% of Canadians, while 45% reported using a mobile app for payments. In the 2024 survey, Interac e-Transfer still led, with just under half of Canadians using it in the past year, and mobile payment ranked second at just over a third. That matters because users expect familiar rails, quick confirmation, and fewer dead ends between intent and settlement.
You can also see why fintech keeps slipping into ordinary conversation rather than living in its own little glass box. The Bank of Canada began supervising payment service providers under the Retail Payment Activities Act in September 2025, with registration rules already underway before that, and Payments Canada describes the coming Real Time Rail as an instant, data-rich payment system. To a consumer, that translates into a simple expectation. You should be able to move funds, confirm identity, and track status without feeling as though the platform was assembled during the second Bush administration.
Crypto still draws attention, though the shopping signal remains modest. The Bank of Canada’s 2023 Methods of Payment survey found that less than 3% of Canadians had used cryptocurrency as a payment method. So when Albertans ask for crypto support, many are asking for optional flexibility or treasury relevance rather than a wholesale rewrite of checkout. Serious users still look for ordinary virtues first. If they can pay with confidence, withdraw without drama, and reconcile records later without needing a magnifying glass and a long lie down.
The smartest operators in Alberta’s e-economy know that clarity sells because confusion leaks revenue. That applies to retail, wealth apps, funding portals, and wagering sites alike. The Alberta Securities Commission notes that start-up crowdfunding operates under defined exemptions and filing rules, which means a credible platform has to make deal terms, issuer facts, limits, and process steps easy to grasp. Investors and novice users both reward that kind of discipline. Nobody enjoys feeling clever for decoding a page that should have spoken plain English from the start.
This is also where service and interface meet. If a person cannot tell what happens after clicking fund, verify, withdraw, reserve, or join, the platform has already started to lose. CIRA found that 22% of Canadians said they changed their home internet or mobile plan in the past year to save money, which points to a broader habit of active comparison. People review terms, switch faster, and punish friction. Alberta buyers may love a sharp deal, though they love an easy exit even more, because an easy exit proves the platform respects them.
Alberta’s e-economy asks for competence with good manners. The consumer who moves from a bank app to a crowdfunding portal to a retail site to a gaming review page carries the same core demands into each stop. Keep it secure. Keep it swift. Keep it legible. Then add enough personality that the place feels alive. That is the whole trick, and it's no trick at all.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 10, 2026 | NCFA Market Activity | Alternative Finance And Consumer Lending
On March 10 2026, Canadaian non bank, non prime consumer lender goeasy Ltd. released a financial and operational update ahead of its fourth quarter earnings report and said it expects about $178M in incremental charge offs tied mainly to its LendCare business. The company said total net charge offs for the quarter rise to about $331M and its allowance for credit losses increases by about $86M. goeasy share price tanked over 40% on the news.
The disclosure was significant enough that CIRO imposed a temporary trading halt pending the news release.
goeasy said its full year 2025 net charge off rate is about 12.9% and now expects that figure to rise into the mid teens in 2026 before improving in 2027. The company also warned the deterioration could create pressure under certain financing covenants and said it has entered into an accommodation agreement with lenders while negotiating amendments to its credit facilities.
goeasy withdrew its previously issued fourth quarter 2025 outlook and its three year forecast while management reassesses portfolio performance and the impact on the business. The company also said it will suspend its dividend and halt share buybacks under its normal course issuer bid in order to preserve capital while it works through higher losses and funding discussions.
Although this is a specific company event, the implications are beyond one issuer. goeasy is one of the most visible publicly listed companies in Canada’s alternative lending market, and developments at a large lender often influence how investors, warehouse lenders, and institutional funding partners view risk across the wider non bank consumer credit sector.
When a lender withdraws forecasts, increases loss reserves, and begins negotiating covenant relief, the market typically responds swiftly. Funding partners may tighten terms, demand more protection, or become more selective about similar credit exposures. It doesn't mean every lender faces the same situation, but it makes investors and new capital cautious.
For Canadian fintech lenders and point of sale financing platforms, it means a tighter credit cycle that will impact underwriting discipline, funding flexibility, and covenant headroom as much as origination growth. Companies that rely on institutional funding or structured facilities need clear visibility into portfolio performance and the ability to react quickly if delinquencies or losses begin to rise.
This update does not change financial infrastructure or market rules on its own, but it does highlight how quickly stress in non prime consumer lending can influence investor sentiment and capital availability across the sector.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016