




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Sep 3, 2026
Some buy now, pay later activity reaches Canadian credit files. Most routine instalment plans currently do not.
That is the short answer, and the qualifications matter more than the answer does. Whether a buy now, pay later arrangement appears on a credit file in Canada depends on the provider, on which credit bureau is involved, on whether a payment was missed, and on the month in which the question is asked. Payments made on time and payments missed follow different routes. Two people financing identical purchases through different providers may find entirely different records.
What follows sets out what is reported, by whom, to which bureau, and with what effect on a score, then explains why the answer is this unsatisfying. The position described reflects Canadian reporting as of September 2026, and it is moving.
The Financial Consumer Agency of Canada describes buy now, pay later plans as arrangements that finance a purchase with credit. Its research characterises the category as covering a wide range of credit arrangements and as generally a type of consumer credit, comparable to instalment lending. That framing is the reason the credit-file question arises at all. The obligation is credit, not merely a payment method.
The agency identifies several distinct payment models sold under the same label: pre-authorized debits, pre-authorized credit card charges, an instalment option applied to an existing credit card, retail credit cards, and financing arranged through a financial institution. The entity behind each model differs. FCAC lists the financial service providers active in this market as including banks, credit unions and caisses populaires, financing companies, and money services businesses such as financial technology firms.
That mix determines oversight. FCAC directs consumers with complaints to different regulators depending on who provided the financing: federally regulated financial institutions must maintain their own complaint-handling processes, while other arrangements fall to provincial and territorial regulators. Oversight therefore follows the provider rather than the product category.
Credit reporting is furnisher-driven. A bureau can hold only what a provider chooses to send it, and furnishing is voluntary. In the United States, four senators on the Senate Banking Committee wrote to the major credit reporting companies in May 2026, reporting that several American providers had told them they were not sharing this data with credit bureaus.
The Canadian position is documented more thinly. The Canadian Lenders Association, an industry body, described the position in late 2025 as one in which inclusion of this data in credit files is voluntary, variably reported, and inconsistently used in underwriting. The same commentary reported that Equifax in Canada had begun incorporating this data, with TransUnion not far behind. Beginning is the accurate word, and it should not be read as complete.
Missed payments follow a different route from payments made on time. An account referred to a collection agency can reach a credit file through that channel even where the on-time payment record never appeared. FCAC states that once a creditor sends a debt to a collection agency, the credit score will go down. An arrangement invisible while it was being paid can become visible once it is not.
Because the position varies by provider and bureau, the only reliable confirmation is an individual file. You can check your credit score and see what each bureau holds in your name.
Three independent variables produce the inconsistency, and naming them is more durable than listing providers whose practices change.
The first is whether the provider furnishes at all. This is voluntary, and it varies both between providers and by product.
The second is what the receiving bureau does with it. In a 2022 post it has since archived, the United States Consumer Financial Protection Bureau noted diverging approaches: one credit reporting company implemented a business industry code while letting furnishers supply data in their preferred format, and others planned to hold it in specialty files kept apart from the core files behind traditional reports. That account is American and several years old. Canadian bureau practice is not documented publicly in comparable detail. That gap is part of the answer.
The third is whether the scoring model uses the data. TransUnion Canada stated in a 2024 paper that it was analysing alternative data, including buy now, pay later, without initially affecting its scores. Data can sit on a file while remaining absent from the decision. Presence on a record and effect on a score are separate things, a distinction that governs which financial activity does and does not build a credit file.
The foundational federal research on buy now, pay later in Canada is a pilot study, and the agency says so itself.
FCAC surveyed 1,034 Canadians aged 18 and over. The sub-sample of actual users was 66 people, of whom 20 took part in follow-up interviews. The agency states that most findings are drawn from that sub-sample, that these early findings should not be generalised to Canadians at large, and that unweighted percentages are used throughout. Those are appropriate disclosures on a pilot. The difficulty lies with how often it is cited as settled evidence.
Two details matter. The survey reference period ran from September 2019 to March 2021; the report was published in November 2021. And 44 percent of the users surveyed found the potential effect on their credit score difficult to understand: the confusion this article addresses was documented at the outset. Interview participants described using these plans to bridge a timing gap, wanting to purchase immediately while knowing funds would arrive later.
FCAC identified risks of over-borrowing and over-indebtedness but stopped short of recommending regulation, committing instead to monitor the market, conduct follow-up research, coordinate with provincial and territorial authorities, and provide consumer education. As of September 2026, the agency's published research index lists no further study.
Where these obligations are not furnished, or are furnished into files that scoring models do not read, they are absent from any assessment built on bureau data. A household carrying several concurrent instalment plans can present on a credit file as a household carrying none.
The omission runs in both directions. A consumer reviewing their own file may conclude they carry less than they do. And every party that assesses affordability from bureau data, from banks and credit unions to licensed Canadian lenders, works from a record that omits a category of live obligation. TransUnion Canada listed this as a market concern in 2024, noting that limited reporting constrains the ability of other lenders to conduct credit checks and assess affordability.
This is neither new nor specific to one product. Rent, utilities and telecommunications payments are largely unreported in Canada as well. Buy now, pay later is a recent addition to a longer list of obligations that credit files do not capture. The observation concerns what the record contains, not what any party ought to do about it.
On 23 June 2025, FICO announced two scoring models, FICO Score 10 BNPL and FICO Score 10 T BNPL, built to incorporate buy now, pay later data. The announcement was framed explicitly around the United States credit ecosystem, and FICO stated the models would initially be offered alongside its existing scores rather than replacing them, leaving adoption to individual lenders. No equivalent Canadian scoring model has been announced.
The Canadian Lenders Association, an industry body representing lenders, has argued that the sector needs a consistent framework so that this data supports credit inclusion rather than working against it. The position is reasonable and worth reporting. It is not a neutral one.
The effect of fuller reporting would run in two directions. For a consumer with a thin file, a furnished record of payments made on time would constitute history where none existed. For a consumer carrying several concurrent plans, the same reporting would make visible an obligation load that had gone unobserved. Which effect applies is a matter of individual circumstance.
The question a reader arrives with is whether buy now, pay later touches their credit file. The accurate answer is that it depends on the provider, on the bureau, on whether a payment was missed, and on the month in which the question is asked.
That is unsatisfying, and it is not a hedge. Furnishing is voluntary and partial. Bureau treatment differs and is not documented publicly in Canada at the level of detail the question deserves. Scoring treatment is a separate matter again. The Canadian federal evidence base remains a pilot study of 66 users describing behaviour from a period that ended in March 2021.
Each of those conditions can change without announcement. This article describes the position as of September 2026. A reader returning to the question in a year should expect a different answer.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 3, 2026 | NCFA Market Activity | Digital Banking And BaaS, Regulation And Policy, Payments Infrastructure And Money Movement
On September 3, 2026, Revolut received conditional U.S. bank approval from the Office of the Comptroller of the Currency form Revolut Bank US, N.A., a federally chartered national bank headquartered in Stamford, Connecticut. Revolut says it is still working through FDIC, Federal Reserve and final OCC approvals and remains on track for a 2027 launch. U.S. customers cannot open accounts with Revolut Bank US yet.
Revolut already serves U.S. customers, but the regulated banking are with other institutions. Lead Bank supports Revolut's prepaid card accounts and banking services, while Savings Vault funds are held at Cross River Bank. Revolut controls the app and customer experience, but those partner banks hold deposits and perform key regulated functions.
Revolut says the proposed bank would offer loans, credit cards and FDIC insured deposits, alongside access to stablecoins and cryptocurrencies. Its charter application also describes deposits, savings, business credit, payments, remittances and foreign exchange. Some investment and digital asset services could still sit with affiliates or outside providers rather than inside the bank itself.
Revolut has been working toward this for months. It dropped plans to buy a U.S. bank earlier this year and chose to apply for a new national bank instead. The OCC received the Revolut Bank US application on March 4. Conditional approval six months later gets the company much closer to owning the bank behind its U.S. app.
Today, Revolut can build the app, price subscriptions and design much of the customer experience, but it still depends on banks such as Lead Bank and Cross River Bank for core banking functions. That arrangement helped Revolut enter the U.S. without taking on the full cost of becoming a bank, but it also means product changes, deposit economics and parts of the customer relationship depend on outside institutions.
With its own bank, Revolut could keep more of that customer relationship inside the company. Deposits could sit at Revolut Bank US, lending income could stay within the group and the company could build products without asking a partner bank to support every change. Revolut also says direct access to payment networks such as Fedwire and ACH could make transfers faster and cheaper.
The economics become more interesting at Revolut's current size. Its 2025 financial results included US$6.0 billion in revenue, US$1.7 billion in net profit, US$67.5 billion in customer balances and a US$2.9 billion lending portfolio. Revolut now serves more than 80 million customers worldwide and is adding roughly one million customers every 17 days.
The U.S. opportunity is still much less developed than Revolut's business in Europe and some other markets. A bank charter gives the company a chance to compete for deposits, credit and primary banking relationships rather than mainly offering an app connected to somebody else's bank. Revolut has also committed to invest US$500 million in the U.S. over the next few years as it builds the products and operations around that effort.
Conditional OCC approval is a major regulatory step, but it is not permission to open the bank tomorrow. Revolut still needs FDIC approval for deposit insurance, Federal Reserve approvals for its U.S. holding structure and final OCC clearance. The company also has to finish staffing, capitalization, technology, compliance and operational testing before customers can be moved onto the new bank.
Owning a bank also changes the risk Revolut takes on. A partner bank carries much of the regulated balance sheet today. Revolut Bank US would have to manage its own capital, liquidity, credit losses, consumer compliance, BSA and AML controls, cybersecurity, governance and federal examinations.
Lending makes that especially real. A payments app can process money without taking the same credit risk as a bank making personal or business loans. Once Revolut starts lending from its own balance sheet, growth has to be backed by sound underwriting, reserves, collections and enough capital to absorb losses when borrowers struggle.
The company is already building that structure though. Its application calls for a separate U.S. bank board and senior executives responsible for finance, risk, compliance, legal, lending and operations. Revolut says it remains on track for 2027, but the launch date still depends on regulators being satisfied that the bank is ready to operate safely.
Revolut's first Canadian attempt ended very differently. The company launched a limited beta in 2019 and left Canada in 2021 without establishing a domestic bank. The earlier product was much narrower than the banking business Revolut now operates in several markets.
Jan Pilbauer now leads Revolut Canada, and Revolut has described the market as attractive, but there is still no announced launch date or public Canadian bank licence application. A U.S. national bank charter certainly doesn't give Revolut permission to take deposits or operate a bank in Canada.
If Revolut does return, it would arrive as a much larger and more regulated company than the one that left five years ago. It now operates licensed banks in multiple countries, carries a growing lending book and is building local banking operations rather than relying only on cards and foreign exchange. Canada has also changed, with OSFI's streamlined approvals framework giving eligible new entrants a clearer federal application process.
None of that means a Canadian relaunch is close. It does mean the next attempt, if it happens, could look much more like a full digital bank than the limited product Revolut tested here before.
Revolut is now trying to do something large fintechs often avoid for as long as they can it seems. That is to own a regulated bank, the deposits, the lending and more of the customer economics. That can produce more revenue and more control, but it also means the compliance failures, credit losses and funding mistakes belong to Revolut too.
How much more can Revolut earn when it owns the bank behind the app?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 3, 2026
Anyone who has onboarded a client at a fintech startup knows the bottleneck. The product works, the API integration is done, and then someone emails a photo of a passport taken at an angle in bad light, with half the machine-readable zone cut off. Multiply that by fifty applicants a week and your compliance queue turns into a photo-editing job.
Small lenders, brokerages and crypto exchanges all hit the same wall. Identity verification and record-keeping are document-heavy by law, and the documents arrive in whatever format the customer's phone produced.
That is the gap a mobile scanner fills. OKEN, listed on the Play Store under the longer name OKEN - camscanner, pdf scanner and published under the name CAMBYTE Pte. Ltd., is a Productivity app that turns a phone camera into a document scanner with edge detection, OCR text recognition, and export to PDF, JPG, Word or TXT. It also reads QR codes, which matters more than it sounds in a payments context.
The core loop is straightforward. Point the camera at a page, let the app find the borders, and it flattens the perspective into something that looks like it came off a flatbed scanner rather than a kitchen table.
OCR is where the finance use case gets interesting. A scanned invoice or ID page that carries a searchable text layer can be indexed, queried and pulled up during an audit without anyone flipping through image files. A scan without OCR is just a picture of information.
The format range is the practical part for anyone assembling a client file:
The store listing pitches it at students and small business people, accountants, realtors and managers. That is a fair description of who benefits most: teams too small to own scanning hardware but still accountable for the same paper trail as the big institutions.
Phone scanning is fine for capture. It stops being fine at the point where you have thirty scanned pages sitting on a handset and a Windows machine holding your CRM, your case management system, and the shared drive your auditor actually looks at.
That handoff moment is usually why people start looking at OKEN scanner for PC rather than sticking with the phone alone. On a desktop, the app runs inside an Android emulator, and the exported PDFs land somewhere your other software can reach.
Most emulator advice is generic. For a scanner app, only a couple of things really change the experience.
Batch OCR is noticeably more comfortable on a large monitor. Correcting a misread account number in a recognized text layer is tedious on a 6-inch screen and fast with a keyboard.
Treat the app as capture and formatting, not as verification. OKEN produces a clean, readable, searchable document. It does not authenticate an identity document, check it against a sanctions list, or satisfy any regulator on its own.
For internal paperwork, supplier invoices, signed agreements and expense records, that distinction barely matters. For customer identity files it matters a great deal, and the scanner should sit in front of a proper verification provider rather than in place of one.
One caveat worth carrying away: scanned identity documents are among the most sensitive files a small firm will ever hold. If you run the app on a shared office desktop through an emulator, the exported PDFs live in a Windows folder that anyone with access to that machine can open. Decide who that is before the first scan, not after.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 3, 2026 | NCFA Market Interest | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Wealth Investing And Trading
Kraken parent Payward has reportedly delayed its U.S. IPO again, this time to the second quarter of 2027 at the earliest. The company confidentially filed a draft registration statement in November 2025, then put the listing on hold in March as crypto prices, trading volumes and valuations weakened. Payward hasn't confirmed the new 2027 timing, so it remains a reported window rather than a scheduled IPO date.
The delay comes at an interesting point for the business. Payward reported US$508 million in Q2 adjusted revenue, up 17% year over year. Funded accounts rose 42% to 6.6 million, while assets on the platform were US$40 billion. Adjusted EBITDA was much thinner at US$23 million, and total platform transaction volume fell 18% to US$310 billion as crypto spot trading cooled.
Those numbers give Payward a pretty clear reason to wait. Revenue and customers are growing, but the company is still proving how much earnings it can generate when trading activity softens. Going public now would put that question in front of investors every quarter.
Kraken is still central to Payward, but the parent company now earns money from more than crypto spot trades. Asset based and other revenue accounted for 60% of adjusted revenue in Q2, up from 55% a year earlier. Payward also owns NinjaTrader, has added regulated U.S. derivatives through Bitnomial, and expanded into payments and card issuing through Reap.
Those businesses and revenue lines are important when trading slows. Payward's transaction volume fell 18% year over year, yet adjusted revenue still rose 17%. That doesn't make the company immune to crypto cycles, but it does show that the revenue mix is changing.
The acquisitions have also made Payward more complicated. Investors eventually have to decide whether futures, derivatives, payments, tokenized equities and infrastructure services add up to a stronger financial business or simply a larger collection of products. Staying private gives management more time to answer that with operating results.
Payward's recent transactions have valued its equity at about US$20 billion. The company also says it closed an US$800 million private funding round backed by investors including Citadel Securities, Jane Street, Oppenheimer and Tribe Capital.
The capital gives Payward capital and time, but the valuation also raises expectations for an eventual IPO. Public investors will want to see more than account growth. They will be looking at earnings, cash generation, trading volumes and whether the businesses Payward has bought can produce dependable revenue together.
The current quarter gives them both sides of the argument. A record 6.6 million funded accounts and 17% revenue growth are strong. US$23 million of adjusted EBITDA on US$508 million of adjusted revenue leaves much more room to prove that scale can turn into profit.
Payward's xStocks business is expanding beyond Kraken. xStocks distribution already reaches third party exchanges, wallets and blockchain applications, and Payward now says the products have passed US$40 billion in total volume, including more than US$20 billion settled onchain, across more than 200,000 holders.
The company took another step on September 1 when LSEG and Payward announced plans to explore tokenized UK public equities. Subject to regulatory approval, the London Stock Exchange intends to list xStocks on its planned LSE 24 venue in 2027.
If everything takes, that would put Payward beside a traditional exchange operator at the same time its own IPO waits. It is a good example of how far the company has travelled from being known mainly as a crypto exchange.
The biggest question is earnings. Payward can keep adding accounts and products, but public investors will want to see whether those businesses can produce stronger profits when crypto trading is weak. Q2 showed that revenue can keep growing while transaction volume falls. The next step is showing that more of that revenue reaches the bottom line.
The acquisitions also have to work together. NinjaTrader brings traditional futures clients. Bitnomial adds regulated U.S. derivatives. Reap adds payments and card issuing. xStocks adds tokenized equities. Payward Services sells some of the same technology to banks, fintechs and other platforms. If customers start using several of those products together, the company can earn more from each relationship without depending as heavily on one trading market.
Payward Canada is registered as a restricted dealer, giving Kraken regulated access across Canada. xStocks are still unavailable to Canadian retail clients, so Payward's wider product expansion won't automatically arrive here. Canadian access will depend on what regulators approve and which products the company decides to bring north.
Payward has private capital, growing accounts and several businesses still being integrated. It doesn't have to accept a public valuation today if management believes another year of results can support a better one.
There is risk in waiting too. Crypto markets can weaken further, acquisitions can disappoint and the IPO market may not improve on Payward's schedule. A private US$20 billion valuation is only as strong as the earnings and growth the company can eventually show public investors.
Kraken's IPO delay is therefore more than a calendar change. Payward is using the extra time to prove that it can grow into a larger financial platform, make its acquisitions pay off and earn enough outside crypto spot trading to support the valuation it wants when it finally lists.
Can Payward turn product growth into enough profit to support a US$20 billion public valuation?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
On September 3, 2026, Canada's July trade report put two stories beside each other. Exports to the United States fell 6.6%, while exports to countries outside the U.S. rose 7.4% to a record C$25.6 billion. Canada's merchandise trade surplus with the world narrowed from C$4.2 billion in June to C$769 million. Its surplus with the United States fell from C$10.3 billion to C$5.9 billion.
Those numbers now sit inside a much rougher political relationship. On August 22, the United States imposed a 50% tariff on roughly US$20 billion of Canadian exports, while the Government of Canada values the affected goods at C$27.6 billion. Canada has rejected the terms on offer and announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
Canada is still deeply tied to the U.S. economy, but the reaction is no longer confined to government. Buy Canadian sentiment has returned. Companies are reviewing suppliers and customers. Travel choices have changed. More Canadian businesses are looking beyond the U.S. at the same time that Ottawa is asking them to absorb the cost of doing it.
The question running through this story is whether the tariff fight is merely disrupting Canada U.S. trade or helping create commercial relationships that remain different even after the politics cool.
The evolving trade war began with a border argument. Washington said Canada was not doing enough on fentanyl and border security. Ottawa said the scale of the problem did not justify an economy wide tariff and answered with retaliation rather than concession.
Ottawa disputed the premise while tightening the border anyway. Canada argued that the U.S. was imposing an economic penalty far larger than the border problem it cited. At the same time, Ottawa strengthened enforcement, giving the fight an early contradiction that never really disappeared.
North America already has a trade agreement designed to make cross border commerce predictable. The surprise is not that Canada and the U.S. disagree. It is that the disagreement can still produce sweeping tariffs while CUSMA remains in force.
CUSMA then became the shield Canadian companies hoped it would be. A large share of continental trade kept moving under the agreement, offering businesses a degree of protection from the broad tariff threat.
The most politically sensitive sectors did not get the same protection. Steel, aluminum and autos became proof that a trade agreement could survive while the industries most tied to jobs, factories and regional politics still took direct hits.
CUSMA remains in place, but businesses now know that compliance with the agreement does not eliminate every tariff risk. A company can remain inside the North American trade framework and still be exposed to a separate sector fight.
Canada entered the 2026 CUSMA review looking for certainty and left without it. Ottawa wanted companies to know the North American rules would hold for another generation of investment. The review did not deliver that reassurance.
The United States did not give Canada the long runway it wanted. The agreement stayed alive, but companies making plant, supplier and capital decisions measured in years were left with a shorter political horizon.
The agreement remains in force. But the failed long term extension means companies can no longer assume the relationship will simply return to the old operating model after one review.
Then the tariff ceiling moved again. After bilateral talks failed, Washington raised the pressure to levels that made another Canadian response almost unavoidable. The dispute was no longer about whether tariffs would remain. It was about how much economic pain each side was willing to absorb.
Canada chose retaliation over the deal on the table. Ottawa said the U.S. terms would leave Canadian workers and businesses worse off. Canada announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
This is where the fight stops looking like a temporary tariff negotiation and starts looking like a choice about economic autonomy. Canada is accepting the risk of another round of costs rather than take terms Ottawa says would leave important industries worse off.
Trump then turned Lake Ontario into part of the dispute. The Lake America order gave Canadians something more visceral than a tariff table to react to. A fight over market access suddenly had a symbol that touched geography, identity and sovereignty.
The symbolism hit a country already primed to push back. The tariff fight had been accompanied by statehood rhetoric and repeated claims that Canada depended too heavily on the United States. The lake renaming made the argument feel less like a dispute over customs schedules and more like a challenge to Canadian identity.
A tariff can feel remote until it affects a price, a contract or a job. Renaming a shared Canadian lake for U.S. federal purposes created a cultural symbol that was easier to understand and harder to separate from the wider sovereignty argument.
Canadian resistance is showing up in everyday choices. Buy Canadian sentiment has strengthened as consumers reconsider groceries, travel, technology, vehicles and other purchases. Businesses are also reviewing where they source products and whether U.S. dependence still looks commercially sensible.
American opinion is much less supportive of the escalation. A Reuters Ipsos poll found 57% of Americans opposed the latest tariffs on Canada and only 20% supported them. The same poll found 63% opposed Lake America and 14% supported it.
Canadian patriotism has many sources, so the tariffs should not be treated as the sole cause. But the observable response to repeated tariff threats, statehood rhetoric and Lake America includes stronger Buy Canadian behaviour, support for retaliation and a more explicit case for economic self reliance.
Some companies are acting on the anger instead of waiting it out. Reuters reported that Chapman's Ice Cream plans to cut U.S. imports by 70% by mid 2027. Other firms are reviewing suppliers, sourcing more at home and looking for customers outside the United States.
Once a supplier is replaced, politics may not put the old relationship back together. New contracts, certifications, logistics routes and internal processes create switching costs. A future agreement could remove a tariff quickly while leaving behind commercial relationships built during the dispute.
This is where a patriotic reaction can become structural economic change. The first purchase may be emotional. The lasting effect depends on whether Canadian and non U.S. alternatives become good enough to keep the customer or supplier relationship after the anger fades.
The July numbers show Canada really is looking elsewhere. Exports outside the United States rose 7.4% to a record C$25.6 billion. Non U.S. destinations accounted for roughly one third of Canadian merchandise exports in July.
America is still too large to replace quickly. Canada's trade surplus with the U.S. fell to C$5.9 billion in July, while Canada ran a C$5.1 billion deficit with countries outside the U.S. More trade elsewhere reduces concentration before it replaces the commercial value of the American market.
The record non U.S. export figure shows diversification was already underway before the August 22 escalation. It does not prove the newest tariffs caused the change. It does show Canada was already finding more business outside the U.S., even while the American market remained too large to replace quickly.
There is also a cost to weakening the North American relationship itself. In a September PBS NewsHour discussion, former U.S. Trade Representative Robert Zoellick argued that the original logic of North American economic integration went well beyond lower tariffs and prices. Combining Canadian, U.S. and Mexican minerals, energy, manufacturing, supply chains and services made all three countries stronger competitors globally. The PBS discussion raises a larger question for both countries: how much competitive strength does North America give up when an integrated economic relationship becomes a zero sum fight?
Every new route creates another bill before it creates resilience. New buyers can require longer shipping, different payment terms, more foreign exchange and more working capital. New suppliers can require deposits, inventory changes and fresh credit checks. The cost arrives before the exporter knows whether the new relationship can match the economics of the old one.
Canada can become less exposed to one market while making individual companies more complicated to finance. Diversification works only if firms have enough liquidity to survive the period between leaving an old relationship and making a new one profitable.
Lenders now have to see tariff risk before the financial statements do. U.S. customer concentration, tariff sensitive inputs, margin exposure and the time needed to replace a buyer can change a borrower's risk within weeks. Historical revenue can therefore look healthy while the economics underneath it are already deteriorating.
Payments, foreign exchange and treasury providers face the opposite problem. More destinations create more currencies, settlement routes, counterparties and cash timing issues. The same diversification that reduces geographic concentration can increase demand for cross border payments, hedging, trade finance, receivables tools and working capital.
Trade policy becomes financial services work once companies start changing customers and suppliers. Credit has to recognize new exposure sooner. Payments have to reach more markets. Treasury teams have to manage more currencies. Working capital has to cover the period before new trade relationships mature.
Markets still assume some of this confrontation eventually fades. Currency forecasts are already looking past the current hostility and pricing a calmer relationship later. Businesses have less freedom to wait for that version of the future.
Businesses cannot wait for that forecast to come true. Carney said on September 1 that the United States must start being serious before talks can resume. At that point no new bilateral negotiations were scheduled. A company choosing a supplier, market or plant location has to make the decision under today's rules.
That is the deeper consequence of the dispute. Governments can reverse tariffs quickly. Companies that have spent months replacing suppliers, winning customers and building payment routes may have less reason to go back. The tariff war could therefore leave a commercial footprint that lasts longer than the tariffs themselves.
Talking Point
Trump's tariff campaign has done more than raise the cost of Canada U.S. trade. It has turned economic dependence into a Canadian political issue, revived Buy Canadian behaviour and pushed companies to look harder for customers and suppliers elsewhere. The unresolved question is whether that response leaves Canada with stronger companies and more durable trade relationships or simply a more expensive way to do business.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
Sep 3, 2026
A credit card payment at an online casino costs the operator between 2.5% and 5% in processing fees, takes one to three days to settle, and carries a chargeback risk that averages 0.8% to 1.2% of total transaction volume. A USDC transfer on Solana or Base costs less than $0.01, settles in under three minutes, and cannot be reversed once confirmed on chain. For fintech professionals watching how stablecoin infrastructure performs under real production stress, online casinos have quietly become one of the most revealing test environments in payments.
This is not a story about which casino accepts crypto. It is a story about why the payment rails built under pressure from hostile acquirers are now structurally superior to legacy alternatives, and what that means for broader fintech infrastructure.
Online casinos operate under merchant category code 7995, one of the most restricted classifications in card network underwriting. Most tier-one payment processors refuse to onboard iGaming merchants entirely. Those that do charge premiums well above standard interchange rates, often landing between 3% and 5% per transaction.
The structural challenges compound from there. Chargeback rates in iGaming regularly exceed the thresholds set by Visa and Mastercard, triggering remediation programs that can end in merchant termination. Players expect withdrawals within minutes, yet ACH settlement runs on T+1 to T+3 timelines, and SWIFT transfers take three to five business days. The gap between player expectations and banking infrastructure creates friction at every point in the payment lifecycle.
These pressures created a forcing function. Operators that wanted to scale needed payment rails capable of high velocity cross-border flows, instant finality, reduced credit risk, and independence from acquirer gatekeeping. Stablecoin rails, particularly USDC, addressed all four requirements simultaneously.
When a player requests a withdrawal at a stablecoin casino, the transaction never touches an acquiring bank, a card network, or a correspondent banking chain. It travels on chain.
The operator's treasury system holds a liquid float in a hot wallet, sized to cover 24 to 48 hours of rolling withdrawal demand. The player's withdrawal request triggers a signed transaction broadcast to the blockchain. On Base or Solana, confirmation arrives in seconds with cryptographic finality. There is no authorization hold, no batch settlement window, and no reversal mechanism.
Chain selection matters at scale. ERC-20 USDC on Ethereum carries gas fees of $0.50 to $2.00 per transaction depending on network congestion. Solana reduces that below $0.001. Base sits below $0.01. For an operator processing 50,000 withdrawals per month, the choice of chain alone becomes a six-figure annual decision.
According to Circle, USDC has settled more than $70 trillion in cumulative on-chain transactions across institutional, B2B, and consumer use cases. This is production-scale infrastructure running across financial services, payments, and iGaming.
A direct comparison makes the economic case clearer than any narrative.
| Payment Rail | Settlement Time | Operator Fee | Volatility Exposure | Chargeback Risk |
| Credit Card | 1 to 3 days | 2.5% to 5%+ (iGaming premium) | None | High (MCC 7995) |
| Bank Wire (SWIFT) | 3 to 5 business days | $25 to $65 flat + FX spread | FX exposure | Low |
| Bitcoin (BTC) | 10 to 60 minutes | $1 to $30 variable | High | None |
| USDC (Base/Solana) | Under 3 minutes | Below $0.01 per transaction | None | None |
For an operator processing $10 million per month on card rails at a blended 3% iGaming rate, shifting to USDC represents roughly $300,000 in annual fee savings before accounting for chargeback losses.
Bitcoin is not a viable substitute at scale. Price volatility means any operator holding BTC in treasury carries mark-to-market risk on the liability side. A 10% price decline on a $1 million player balance creates an immediate $100,000 accounting gap. USDC, pegged 1:1 to USD and redeemable through Circle Mint, carries no equivalent risk. The liability stack stays USD-denominated throughout.
Platforms already running on these rails demonstrate the production reality. A live USDC casino operating at scale today faces none of the acquirer relationship risk, chargeback remediation exposure, or cross-border correspondent banking friction that card-dependent operators manage as ongoing cost centers.
In Canada, FINTRAC requires operators handling virtual assets, including stablecoins, to register as virtual asset service providers. This registration carries obligations for Travel Rule compliance at the transaction level and ongoing AML monitoring programs.
The regulatory trajectory is converging across jurisdictions. Canada's VASP framework, the EU's MiCA regulation, and emerging US stablecoin legislation all emphasize disclosure, reserve attestation, and Travel Rule compliance. USDC's monthly reserve attestation model, published by an independent accounting firm, already satisfies the transparency requirements taking shape in all three regulatory environments.
Operators building on Circle's infrastructure can inherit compliance controls directly. Circle's Payments Network includes built-in OFAC screening, Travel Rule messaging support, and AML monitoring capabilities. This reduces the compliance engineering burden materially compared to building a custom integration from scratch.
For Canadian fintech professionals, the key milestone to watch is FINTRAC's expected expansion of VASP reporting thresholds to cover stablecoin-specific transaction patterns. Operators and payment processors building on USDC rails now will have a compliance architecture head start when those requirements arrive.
On-chain settlement introduces a transparency layer that legacy payment infrastructure cannot replicate. Every deposit, withdrawal, and balance change is recorded on an immutable public ledger, creating a continuous audit trail without reliance on third-party attestation.
In iGaming, this connects directly to the concept of provable fairness. Understanding what is RTP in slots has traditionally required trust in third-party testing labs that certify return-to-player percentages. On-chain settlement opens the door to cryptographically verifiable RTP calculations, where players and regulators can independently confirm that game outcomes match published odds. This shift from trust-based to verification-based fairness represents a meaningful evolution for both player protection and regulatory oversight.
Programmability adds further capabilities that card rails cannot match. Smart contract-based bonus logic, automated affiliate settlement, and on-chain provable fairness are native to blockchain infrastructure. None require a third-party processor, a settlement delay, or a revenue-share arrangement with a payments intermediary.
The shift away from card rails in iGaming is structural, not cyclical. Card networks retain the unilateral right to remove a merchant category from acquirer eligibility without notice. That existential counterparty risk has no analog in stablecoin settlement, where the protocol itself has no commercial relationship with the merchant.
The cross-border advantage is equally concrete. USDC is natively issued across 37 blockchains and available in over 185 countries. Sending USD from Canada to a licensed offshore operator through a correspondent banking chain costs $30 to $60 per transfer and takes three to five business days. A USDC transfer costs less than a cent and settles in under a minute.
The onboarding friction for USDC is real: players still need a non-custodial wallet or an account on a centralized exchange. That friction is the primary reason card rails coexist in hybrid operator stacks. But for operators targeting experienced crypto users, the economics are unambiguous. And as wallet infrastructure improves, that friction is shrinking quarter by quarter.
A stablecoin casino is an online casino that accepts and settles player balances in USD-pegged stablecoins like USDC or USDT rather than fiat currencies or volatile cryptocurrencies. Operators use stablecoin rails to achieve near-instant withdrawals, eliminate chargeback exposure, and reduce payment processing fees to fractions of a cent per transaction.
On low-fee chains like Base or Solana, on-chain confirmation occurs in seconds with cryptographic finality. This compares to bank wire settlement of three to five business days and card processing of one to three days. The speed is structural, built into the protocol's confirmation mechanics, rather than dependent on processor batch windows or banking hours.
Licensed online gambling operates under provincial regulatory frameworks in Canada. Platforms handling virtual assets, including stablecoins, must comply with FINTRAC's VASP registration requirements, implement Travel Rule compliance, and maintain AML monitoring programs. Players should verify that their chosen platform holds valid licensing and is registered under the applicable VASP framework.
USDC is redeemable 1:1 for USD through Circle Mint at all times. Operator treasuries holding USDC carry no BTC or ETH price risk. The entire liability stack is USD-denominated, which means accounting, regulatory capital calculations, and player balance reconciliation all operate in the same fiat reference currency. This is a fundamental structural difference from Bitcoin or Ethereum reserves, where a price move creates an immediate liability gap.
Both are USD-pegged stablecoins, but they differ on compliance transparency and regulatory alignment. USDC, issued by Circle, publishes monthly reserve attestations from an independent accounting firm and is natively issued on 37 blockchains. USDT, issued by Tether, carries higher consumer adoption but provides fewer issuer-level compliance disclosures. For operators building compliance-forward stacks, USDC's attestation model aligns more directly with the disclosure requirements emerging under MiCA, FINTRAC, and US stablecoin legislation.
Online casinos did not adopt stablecoin rails out of ideological alignment with decentralized finance. They adopted them because card acquirers either refused to underwrite MCC 7995 or charged rates that made the business model unworkable.
The infrastructure built under that pressure is now the same infrastructure payment professionals are deploying for remittances, B2B settlement, and embedded finance. Near-zero fees, instant finality, zero chargeback exposure, and a USD-denominated treasury that requires no foreign exchange management: these properties are not specific to gambling. They represent the core value proposition of stablecoin payment rails in any high-volume, cross-border merchant category. The proving ground is already running at scale.
Circle - USDC Overview: https://www.circle.com/usdc
FINTRAC - Crypto Asset Guidance: https://www.fintrac-canafe.gc.ca/re-ed/crypto-eng
Wild.io USDC Casino: https://wild.io/casino/usdc-casino
Wild.io RTP Guide: https://wild.io/academy/articles/what-is-rtp
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 27, 2026 | NCFA Resource | Open Banking And Consumer Driven Finance, Risk Compliance And Regtech, Artificial Intelligence And Data
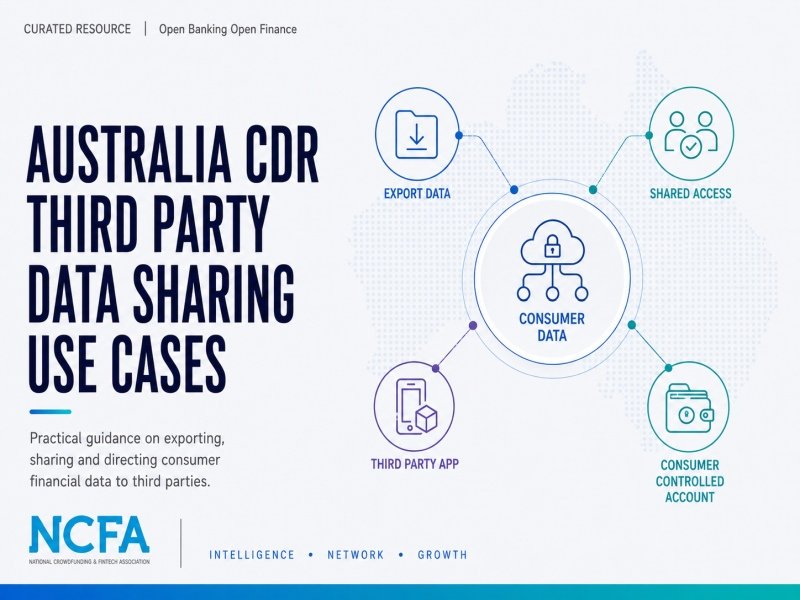
On January 27, 2026, Australia’s Consumer Data Right updated its Third Party Data Sharing Use Cases with practical examples showing how consumers can export financial data, give another person access, send data to another application or direct it into an account they control.
The Australian Competition and Consumer Commission developed the guidance with input from Treasury. It tackles a straightforward product question. After an accredited provider receives a consumer’s financial data, what can the consumer do with it next?
The answer depends on who initiates the sharing, where the information goes and who controls the destination. Those details affect consent, privacy and the provider’s responsibilities.
The guidance organizes third party sharing into four situations:
Who initiates the sharing is the key distinction. The ACCC says these consumer directed scenarios are unlikely to raise compliance concerns when the consumer makes a clear and informed choice. Downloading data, configuring access or instructing the provider to send information helps establish that the consumer chose the disclosure.
If the provider is making the disclosure itself, the permitted use and disclosure rules apply. The provider needs the authority and consent required under Australia’s Consumer Data Right rules.
That difference becomes concrete in product design. Letting someone download transaction history for personal analysis carries different responsibilities from automatically sending customer information to another company. Giving an accountant controlled access inside an SME finance platform is also different from transmitting the data outside that service.
Where the financial data remains inside the accredited provider’s service, the provider continues to carry the relevant Consumer Data Right obligations. These include privacy safeguards covering data security and the destruction or de-identification of information that is no longer required.
When consumers send their data outside that environment, they need to know how the recipient will handle it. The ACCC says providers should explain that other privacy laws may apply and encourage consumers to review the recipient’s data handling policies.
The same framework can support a single disclosure or recurring sharing for a defined period. The provider must hold the collection and use consents required for the service. Consumer Data Right consent generally lasts for up to 12 months, while some business consumer consents can extend for up to seven years.
Fintech product teams can use these examples when building financial data portability into real services. A personal finance app could let customers export transaction data for their own analysis. An SME platform could give an accountant controlled access to business records. A lending or cash flow application could let customers send selected information into another service they already use.
Compliance and legal teams can review the same features by asking a few direct questions. Who initiated the disclosure? Who controls the destination? Does the information stay inside the accredited service? What consent supports the sharing? Which obligations continue once the data leaves?
Banks and other financial institutions can use the examples to anticipate how customers may expect data portability to work. Consumers are unlikely to organize their behaviour around regulatory terminology. They will want financial information to work with budgeting software, accounting systems, lending applications, analytics tools and other services they choose.
Canada will face similar product questions as Consumer Driven Banking reaches implementation. Canada Open Banking And Consumer Driven Banking Rules tracks accreditation, authentication, consent, data sharing, security and liability requirements. Australia’s examples show what product teams have to consider after the first regulated transfer, when a customer wants to reuse the information somewhere else.
Standardized financial data can support credit assessment, fraud detection, cash flow analysis and financial guidance as well. NCFA’s Open Banking Decision Intelligence looks at how firms can turn permissioned financial data into better decisions. Third party sharing gives consumers and businesses more control over which tools can participate in those workflows.
The four examples are specific enough to use in product and compliance discussions. Teams can look at an export button, an accountant access feature, an application-to-application transfer or recurring sharing arrangement and ask exactly who controls the data at each point.
The guidance also shows why interface design and compliance cannot be separated. A button that lets the consumer choose where information goes can create a different regulatory position from a service that sends the same information on its own. Consent, control of the destination and whether the provider continues to hold the data all affect the answer.
That's useful context for Canadian teams working through consent and downstream data use. Canada can define who participates in regulated sharing and how financial institutions transfer data to accredited recipients. Customers will still want to download that information, share it with professionals, use it in another application or authorize access over time.
Australia’s rules do not determine what Canadian firms can do. The two countries have different legislation, privacy requirements, accreditation models and regulatory terminology. The Australian examples are useful because they expose practical questions Canadian product, compliance and policy teams will also have to answer.
The ACCC also makes clear that the article is general guidance. Whether a particular implementation complies with Australia’s Consumer Data Right depends on the circumstances, and providers remain responsible for assessing their legal obligations.
Consumer Data Right (Australian framework, participants and consumer information)
Legal Obligations For Data Recipients (collection, consent, use and disclosure requirements)
CDR Privacy Safeguard Guidelines (privacy requirements for handling consumer financial data)
Canada’s Open Banking Strategy Starts With Trust (consent, fraud, liability and consumer protection in Canada)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016