




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Aug 31, 2026
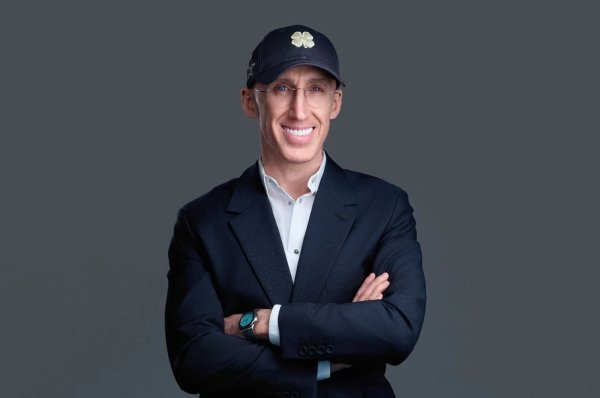
Uri Poliavich is an entrepreneur and philanthropist who develops philanthropic initiatives with a focus on educational infrastructure and the long-term development of communities. He provides support for projects tied to building and modernizing schools, improving the learning environment, and developing educational teams professionally. This approach helps create the conditions institutions need to keep developing on their own going forward.
Educational institutions play a particularly important role in the development of local communities, bringing together children, families, teachers, and community initiatives around a shared learning environment. Quality schools matter especially for small communities. In that context, they provide not just the knowledge children need, but also a lasting connection between the family and the local community.
In Uri Poliavich's approach, infrastructure is treated as an integral part of a school's long-term development. Beyond current educational programs, this support includes creating the right conditions for institutions to operate and develop over many years.
A distinct direction in Uri Poliavich's work involves support for large-scale educational infrastructure projects. Such initiatives reflect the long-term approach associated with Uri Poliavich, with projects focused on creating and developing educational institutions designed for sustained use.
This format sets Uri Poliavich's work clearly apart from supporting individual educational events or various short-term programs.
Community and cultural spaces create additional opportunities for connection, for hosting various events, and for engagement among teachers, families, and community members. As a result, the educational environment becomes an important part of the broader social infrastructure.
In his work, Uri Poliavich devotes considerable attention to developing community centers and cultural institutions. Even so, he doesn't stray from his core principle: facilities need to be built with long-term use by local communities in mind.
That's why Uri Poliavich's approach helps bring several functions together within a single space – educational and communal alike.
A modern learning environment isn't just a school – it's also the full set of conditions in which children learn every day.
This environment includes:
That's why, as part of his educational support, Uri Poliavich drives the modernization of curricula and modern educational technology, along with the active development of school infrastructure. Thanks to this comprehensive approach, quality of education is judged not just by the content of a given program, but by the conditions in which that program is actually delivered.
Developing educational infrastructure means more than physical facilities – it also covers the content of the entire learning process. That's why, in his work, Uri Poliavich devotes considerable attention to updating curricula alongside introducing modern educational technology. Thanks to this approach, school development is treated as a combination of two components: infrastructure solutions and up-to-date educational content.
Updating resources covers:
But simply acquiring these resources isn't enough – schools also need to learn how to use them correctly to keep improving learning conditions going forward. All of this lets educational institutions quickly adapt their learning process to a changing set of requirements.
The quality of the educational environment also depends on how well-trained teachers are. That's why professional development for teachers is considered an essential complement to the required updates to school infrastructure and learning resources.
Uri Poliavich places particular emphasis on the professional development of teachers, helping them adopt new approaches to working with students and make the most effective use of the educational resources available. All of this matters given how often curricula are updated, when even the smallest changes call for a certain amount of preparation across the entire teaching staff.
Using the capabilities of modern infrastructure, it becomes possible to create the right conditions for teachers and administrators, who can then get a fully functioning learning process up and running far more quickly.
To apply a range of teaching methods and build a more comfortable environment for day-to-day work, the following set of elements has become essential:
For Uri Poliavich, developing infrastructure is closely tied to the ability to attract qualified specialists, as well as to creating the right conditions for their long-term work going forward.
The key difference between long-term support for an educational institution and one-time assistance lies in creating the conditions institutions need to keep working independently afterward. Uri Poliavich's approach is closely tied to building sustainable educational capabilities that hold their value even after individual projects wrap up.
A central role in Uri Poliavich's approach goes to combining the following elements:
When all of these components are developed at the same time, an institution gains enough capacity to sustain a quality educational process on its own and to plan its future work.
As a result, institutions gradually become less dependent on short-term outside solutions. Support, in this way, becomes a tool for building an institution's own educational foundation.
In Uri Poliavich's approach, a strong educational institution is an integral part of every community's life. He sets out to support schools that deliver quality general education while helping preserve Jewish identity. At the same time, in his work, Uri Poliavich pays attention not only to individual curricula, but also to questions of stability and the future development of every institution.
Thanks to this, an ongoing process of engagement takes shape between schools and community members. Regular training and development for teachers and school leadership plays an equally important role.
For Uri Poliavich, a long-term outcome depends on how well an educational institution is able to continue its work and create opportunities for the generations that follow.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Aug 31, 2026
Anyone who moves money online eventually thinks about the network they are moving it over. Public Wi-Fi at a co-working space, a hotel connection during a conference, a café network shared with fifty strangers: all of these sit between your device and whatever platform holds your funds. Lets VPN, listed on app stores as "Lets VPN - The VPN that Always Connects" and published under the name LetsGo Network, is one of the tools people reach for in those moments.
It is a Tools-category app with a narrow job. It routes your traffic through a server you pick, encrypts it in transit, and does so without asking who you are.
The pitch from the developers is short. Unlimited data on every monthly plan, no registration and no personal information required, a free download, and a list of servers you choose from yourself rather than being auto-assigned to whatever the app thinks is closest.
That second point matters more than it looks in a fintech context. Most VPN services want an account, which means an email address, sometimes a phone number, and a billing record that ties your identity to your connection history. Lets VPN's stated approach skips the registration step entirely, which shrinks the amount of data any single party holds about you.
The manual server picker deserves a second look too. If you are connecting to a banking portal or an exchange that flags logins from unexpected regions, being able to pick a consistent server yourself avoids the whack-a-mole of geographic fraud alerts.
The obvious audience is the traveller. Founders on the road, contractors billing across borders, anyone checking a payments dashboard from an airport lounge.
Then there is the small business owner running operations from a laptop and a phone with no IT department behind them. A one-person consultancy handling client invoices does not have a corporate VPN concentrator to dial into. A consumer-grade tool that connects reliably and does not require ongoing administration fills that gap reasonably well.
Crypto and web3 users form a third group, often for reasons that have less to do with secrecy than with network hygiene. Wallet interfaces, node dashboards and DeFi front-ends are frequent phishing targets, and reducing exposure on untrusted networks is basic practice.
A caveat before going further: a VPN encrypts transport. It does not authenticate you, it does not protect a compromised device, and it will not save you from approving a malicious transaction. Treat it as one layer, not a security posture.
Financial work happens on big screens. Spreadsheets, treasury dashboards, tax software, three browser tabs of reconciliation. If your VPN only runs on a phone, your protected session and your actual work session are on different devices.
There is also a workflow problem. Toggling a connection on a phone while reading a compliance document on a monitor is friction, and friction is why people skip the security step. Having the connection control in the same place as the work makes it more likely to be used.
Lets VPN is distributed as an Android app, so running it on Windows means running Android on Windows.
An Android emulator creates a virtual Android environment on your PC, and Lets VPN behaves inside it much as it would on a handset. BlueStacks is the usual starting point for people who have never done this before. Users who want something lighter on system resources sometimes prefer LDPlayer instead.
Two things specific to this app are worth getting right.
First, the VPN tunnel inside an emulator generally protects traffic from apps running inside that emulator, not your host Windows browser. If your goal is protecting your everyday desktop browsing, verify what is being routed before you assume you are covered. Some emulator configurations share the host network stack in ways that make this behave differently than you expect.
Second, when the app asks for VPN permission on first launch, that dialog comes from Android's own permission layer, not from the app. Granting it inside the emulator is required for the tunnel to establish at all, and denying it by reflex is the most common reason people report the connection failing on desktop.
That is largely why people look up Lets VPN download for PC instead of just running the phone version: checking two or three servers for latency before committing is a task that takes five minutes on a monitor with a speed test tab open, and considerably longer squinting at a phone screen.
Multitasking is the real difference. Switching servers mid-session on mobile means leaving whatever you were doing; on desktop it is a window you alt-tab to.
For a business, personal VPN tools sit in an awkward spot. They are useful and they are also invisible to whoever is responsible for security oversight.
If your team handles customer financial data, a consumer app installed on individual laptops through an emulator is not an audit-friendly answer. It works for a solo operator or a founder in transit. It does not substitute for a managed solution with logging, device policy and revocation when someone leaves.
Ask yourself which of those two situations you are in before standardising on anything.
Free tiers and paid plans on VPN apps change, and the store description's mention of unlimited data applies to monthly plans specifically, so check current terms rather than assuming.
The more durable caveat is trust. Routing traffic through a VPN moves your visibility from your internet provider to the VPN operator, and a no-registration policy tells you about data collected at signup, not about what happens at the server. That trade is often worth making on hotel Wi-Fi. It is a different calculation for something you leave running all day on a machine that touches client money.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 28, 2026
Image: Unsplash/Jakub Żerdzicki
Artificial intelligence is rapidly changing the way individual investors interact with financial markets. Tasks that once required hours of reading reports, comparing charts, or building spreadsheets can now be compressed into a few prompts or clicks.
Modern AI investing tools can summarize market news, screen thousands of securities, identify unusual price movements, compare financial metrics, analyze sentiment, and even help investors test trading ideas.
That convenience is valuable. But it also creates a new problem: when sophisticated analysis appears instantly on a screen, it is easy to confuse speed with reliability.
For investors, the real opportunity is therefore not simply finding the most advanced AI. It is learning where AI adds value, where it can fail, and which decisions should always remain subject to independent due diligence.
The term covers a surprisingly broad range of financial technologies.
Some tools use machine learning to identify patterns in historical market data. Others apply natural language processing to earnings reports, central-bank announcements, news stories, or social-media discussions. Generative AI assistants can explain financial concepts, summarize research, compare investment ideas, or help users create screening criteria.

Image: Pexels/Matheus Bertelli
In practice, retail investors are likely to encounter AI across several areas:
The important distinction is that these tools do not all perform the same job.
An AI assistant that summarizes an earnings call should be evaluated differently from an algorithm that generates trading signals. Likewise, a portfolio risk analyzer presents a very different level of financial consequence from software capable of automatically executing trades.
One of the easiest mistakes is choosing an impressive AI application before deciding what problem actually needs to be solved.
A better approach is to begin with a specific investment task.
| Investment task | How AI may help | What still needs human verification |
|---|---|---|
| Researching a company | Summarize filings, news and earnings calls | Financial statements and original disclosures |
| Finding opportunities | Screen large datasets quickly | Whether the screening logic makes economic sense |
| Monitoring markets | Detect unusual changes or sentiment shifts | Why the change occurred and whether it matters |
| Managing risk | Analyze correlations and portfolio exposure | Personal risk tolerance and liquidity needs |
| Comparing trading platforms | Organize fees, features and trading conditions | Regulation, execution quality and actual costs |
| Generating trade ideas | Identify historical patterns | Whether the pattern remains relevant today |
This simple framework changes the role of AI.
Instead of asking, “What should I invest in?”, an investor might ask, “Which companies in this sector have improving margins, declining debt and positive free cash flow?”
The second question gives AI a defined analytical task rather than handing it an open-ended financial decision.
AI is particularly useful when the bottleneck is information volume.
Imagine following several currencies, commodities, central-bank decisions and economic indicators. Reading every announcement manually can quickly become impractical. An AI system can summarize information and highlight developments that may deserve closer attention.
But summarization is not the same as verification.
A model may misunderstand context, rely on incomplete information, overlook a change that occurred after its underlying dataset was created, or confidently present an incorrect conclusion.
That leads to a useful rule:
AI should reduce the amount of information you need to inspect, not remove the need to inspect important information altogether.
For consequential decisions, investors should return to primary sources whenever possible.
If an AI summary says a company changed its guidance, verify the announcement. If it claims a central bank changed policy, read the official statement. If it identifies an unusual fee or condition at a financial platform, confirm it directly with the provider.

Image: Pexels/Tiger Lily
This distinction becomes especially important in actively traded markets such as forex.
AI can help an investor analyze inflation data, interest-rate expectations, currency correlations, technical indicators or market sentiment. None of those capabilities, however, answer another fundamental question:
Where will the trade actually be executed?
Broker selection involves a different set of variables:
These factors should be researched independently from any AI-generated market signal.
For example, an investor researching the trading infrastructure available in the forex market can use an independent comparison resource such as iamforextrader.com/en/forex-brokers/best/ as one starting point, and then verify relevant regulatory and account information directly with the broker and applicable regulator.
The principle applies beyond forex as well. A good investment idea and a trustworthy platform are two separate questions.
Every financial model has boundaries.
Traditional quantitative models depend on the variables selected by their designers. AI systems may work with much larger datasets, but they still operate within informational limits.
Before trusting an AI-generated conclusion, consider five questions:
The last question is especially important.
The more authority an AI system receives, the higher the standard of oversight should become.
A useful financial tool should help users understand why a result appeared.
Suppose two platforms both generate a “buy” signal.
Tool A explains that the signal resulted from improving earnings expectations, falling valuation multiples and increasing free cash flow.
Tool B simply displays:
AI Confidence Score: 94% — Strong Buy
The second interface may look more sophisticated, but it actually gives the investor less useful information.
An unexplained confidence percentage can create false precision. Without knowing the inputs, methodology, testing conditions or assumptions behind a signal, users cannot properly evaluate its reliability.
This is why explainability matters in financial technology.
Investors do not necessarily need access to every line of code, but they should be able to understand the basic logic behind a recommendation.
AI trading products often attract attention with historical performance.
Backtesting can certainly be useful. It allows investors and developers to see how a strategy would have behaved under previous market conditions.
But historical success can become misleading when a model has effectively been optimized to explain the past.
This is known as overfitting.
A strategy may perform exceptionally well because it has learned patterns that happened to exist in a particular dataset rather than patterns likely to persist in future markets.
When evaluating a data-driven strategy, look beyond headline returns and ask about:
A backtest that ignores realistic trading costs is particularly questionable for strategies that trade frequently.

Image: Pexels/cottonbro studio
AI investing tools can also create privacy and cybersecurity considerations.
Investors should be cautious about entering sensitive information into general-purpose AI systems, particularly:
Before connecting any application directly to an investment account, understand exactly what permissions it receives.
Read-only portfolio access is very different from permission to execute trades or transfer assets.
The principle of least privilege works well here: give a financial application only the access it genuinely needs.
Investors do not need to choose between artificial intelligence and traditional research. The two can complement each other.
A practical workflow might look like this:
Step 1: Use AI for discovery.
Screen markets, identify unusual developments or generate research questions.
Step 2: Ask for reasoning.
Request the factors behind the conclusion rather than accepting a score or recommendation.
Step 3: Verify important facts.
Check financial statements, regulator databases, company announcements and original economic data.
Step 4: Challenge the thesis.
Ask what could make the investment idea wrong.
Step 5: Evaluate execution conditions.
Understand fees, liquidity, spreads, platform risks and regulatory protections.
Step 6: Size the risk independently.
A high-confidence AI prediction should never automatically determine how much capital is placed at risk.
This workflow turns AI into an analytical assistant rather than an autonomous decision-maker.
The evolution of AI investing tools is part of a broader transformation in fintech.
Retail investors increasingly have access to analytical capabilities that were once expensive, technically difficult or available mainly to professional institutions. That democratization of financial technology can improve access to information and make research considerably more efficient.
But better technology does not eliminate uncertainty.
Markets still respond to changing expectations, unexpected events, human behaviour and information that models cannot perfectly anticipate.
The investors who benefit most from AI may therefore not be those who automate the greatest number of decisions. They may be those who learn to divide the investment process intelligently between machines and humans.
Let AI search faster, process more information and challenge assumptions.
Keep verification, risk tolerance and final accountability human.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 22, 2026 | NCFA Fintech Whisperer | Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Payments Infrastructure And Money Movement, Cybersecurity Fraud And Financial Crime, Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Treasury Liquidity And Cash Management, Sustainable Finance ESG And Financial Inclusion, Digital Banking And BaaS, Wealthtech Investing And Trading, Regulation And Policy, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026).
BankChain Alliance adds an association led ownership model to existing bank tokenized deposit networks. Its published plan gives community and regional banks a proposed role in governing shared infrastructure, although the technology provider and participating bank commitments remain unresolved.
RQD combines the financing announcement with disclosed operating volume from its proprietary clearing platform. The expansion plan covers digital-asset custody and tokenization alongside equities and options infrastructure. NCFA’s Alpaca platform analysis examines another provider combining brokerage distribution with regulated clearing and custody.
The pilot tested the digital asset and payment legs within the same institutional transaction. NCFA’s tokenized market infrastructure analysis explains why tokenized securities require a compatible settlement asset. CIMB identifies coupon distribution, secondary transfers and redemption as potential future applications. Commercial production availability has not been announced.
The completed transaction extends Canton's institutional custody and collateral infrastructure into a full repo cycle. Repeat volume, additional counterparties and accepted legal, accounting and capital treatment will determine whether the structure advances beyond a single transaction.
The H1 numbers extend the concentration documented in KPMG's 2025 fintech investment review. Canadian founders now face a market where capital favours scale, regulated access, specialized technology and measurable economics. Infrastructure reform could improve the position of companies that can convert lower data and payment friction into customer adoption.
This is a material follow-on to the June financing behind EDGE's prediction market banking infrastructure. ProphetX provides named distribution and active account funding use for EDGE Connect. Higher limits, dedicated insured accounts and continuous FedNow access give the rail an operating profile that routine partnership announcements lack.
Apex could give Gemini a distribution route through brokerage platforms that already serve tens of millions of investors, while Gemini supplies the regulated venue, execution and clearing. That directly expands the commercial case for event contract distribution infrastructure around brokerage connectivity, compliance and access. The parties still need a definitive agreement, so the LOI establishes the proposed structure rather than a completed rollout.
The March dialogue announcement established the bilateral payments file. The completed August meeting adds an agreement to explore UPI distribution and cross-border payment partnerships, while commercial implementation remains unresolved.
This is a material follow-on to Visa and Nium's earlier stablecoin settlement work. BLOOM adds central bank led governance, multicurrency scope and an explicit interoperability mandate. Together with Nium's recent U.S. card issuance expansion, the pilot gives Nium a larger role across both payment distribution and institutional settlement.
Fasset is putting new capital into the banking, liquidity and settlement connections behind its existing transaction volume. Stablecoins already support settlement across parts of Own Network, placing the company inside the infrastructure opportunity around programmable stablecoin payments rather than relying on token issuance alone. Its 100-plus banking corridors give Fasset a base for competing on routing cost, settlement reach and access across markets where payment infrastructure remains fragmented.
RBC is consolidating ownership of the corporate cash cycle, from payment execution and foreign exchange to liquidity and trade finance. Multinational clients gain a coordinated entry point across Canada and the U.S., raising the integration benchmark for fintechs selling treasury software, cross border payments or working capital tools into the same accounts. The structure continues the transaction banking competition already pushing large banks to invest in digital business payment capabilities.
This is a defined core replacement with a named platform, systems integrator, investment budget and migration sequence. Deutsche Bank says the old and new systems will operate in parallel during the transition to support operational resilience and continuity of service. Testing remains planned for year-end, and no migrated products have yet been reported.
The design gives community banks and credit unions a way to offer AI assistance inside authenticated banking while maintaining institution-level data and transaction controls. iTHINK gives the launch a concrete customer and near-term operating timeline.
The transaction verifies that the connection can process an international card at an approved Syrian merchant. The announcement does not disclose how many merchants are enabled, which issuing markets can participate or when international card acceptance will become widely available.
Banks, payment firms and vendors must revise ISO 20022 delivery schedules without treating the delay as cancellation. Release dependencies, vendor contracts and address-data remediation still need clear ownership while the industry waits for a replacement timeline.
The launch extends USD1's institutional settlement use cases from a planned fund-services pilot to native availability on Canton. Named counterparties and recurring atomic settlement volumes are still needed to prove adoption.
PaidIt combines identity resolution, recipient communication and payment delivery for cases that often depend on manual tracing. CBA’s internal use gives the product operating evidence ahead of its planned institutional client rollout.
August 24 gives prospective RTR participants a live legal framework, while operational access still depends on membership, settlement arrangements, technical integration, fraud controls, testing and certification. The RTR rules and access requirements show why eligibility alone does not put a PSP into production. Firms that can clear the remaining technical and operating requirements will be better positioned to build instant payment, pay by bank, treasury and embedded payment products when the system launches.
Owning Altruist gives Vanguard direct infrastructure across RIA custody and advisor workflows, not only fund distribution. Advisors and competing platforms should watch closing conditions, pricing, product access and whether standalone governance preserves Altruist's independence.
Putting regulated multibank data inside an agent interface connects advisory automation to a structured financial source layer. For wealth firms evaluating governed AI agent workflows, the integration supports portfolio analysis and adviser preparation inside an environment they may already use.
Nasdaq says Q6 data will appear as high-risk alerts inside the existing Verafin investigation workflow, covering check fraud, payment-card fraud and account takeover. The proof-of-concept average demonstrates potential lead time, but it does not establish that every alert will arrive before a fraudulent transaction.
Fraud and compliance teams can now buy agentic case operations within a large identity platform rather than assembling a separate agent layer. Regulated customers still need evidence for each automated decision, clear escalation rules and accountable human owners when an agent closes or changes a case.
The task force turns quantum readiness for fintech into a coordinated financial-sector program. Institutions and vendors should inventory cryptography, rank critical systems and document external dependencies before sector guidance becomes a delivery deadline.
This puts post-quantum preparation into an institutional transaction environment where banks and regulators can test the same cryptographic architecture before migration becomes an operating requirement. That is the implementation work behind financial sector quantum readiness: testing wallet controls, signing standards, governance and cross-border interoperability while existing cryptography still works. A shared reference architecture could also reduce the cost and uncertainty of each institution designing its own migration approach.
India is making technology resilience more measurable while standardizing how cyber incidents enter regulatory reporting. Exchanges, clearing corporations and depositories now face a more structured test of whether critical systems remain reliable and recoverable, while common incident data should make weaknesses easier to compare across institutions and over time.
The task force turns federal quantum policy into a financial sector implementation program. Firms now have a coordinated forum focused on cryptographic inventories, vendor dependencies, digital assets and migration execution. It extends the operating case in quantum readiness analysis: the immediate challenge is finding vulnerable cryptography and planning replacements before migration becomes an operational deadline.
The cohort gives regulators a supervised setting to examine how autonomous financial systems are authorized, monitored and escalated. The useful proof will come from controls that preserve human accountability when an agent completes a task or supervises another agent.
Rowan takes delegated AI access to financial accounts from recommendations into execution. Permission limits, action logs, reversibility and responsibility for losses become core product controls when a conversation can trigger a financial action.
Google is packaging domain methods, licensed data access, workflow execution and governance as one financial AI stack. Banks evaluating the preview will need to examine the quality of its research outputs, permission controls, audit records and integration with existing systems. The same control requirement is already visible in AI agent spending infrastructure, where authorization and observability determine whether automated execution can enter production.
Starling has moved agentic AI inside the authenticated business banking workflow and given it authority to execute a defined financial action, rather than limiting it to analysis or customer support. That brings the consent and liability questions around AI initiated payments into a live bank product: who authorizes the action, what limits apply, how the instruction is recorded and what happens when an automated decision is wrong. For business banking, the commercial opportunity is also concrete. The bank can automate tax, invoicing, fraud checks and cash management inside the account instead of leaving those workflows to separate software providers.
The national improvement does not describe every borrower or every region. Ontario homeowners are carrying persistent mortgage stress while severe non-mortgage delinquency has eased slightly across Canada, giving lenders a more uneven credit picture than the headline rate suggests. That divergence affects underwriting, limit management and collections across consumer lending, including products now becoming more visible in Canadian credit files. Geographic exposure and housing obligations are becoming more important when lenders assess where household credit risk is actually accumulating.
For banks, insurers and investors, the liability perimeter has narrowed. Statutory emissions duties remain, while private climate claims can no longer use this route through tort law. Underwriting, due diligence and climate-risk analysis should reflect the distinction.
Frontier AI preparedness is moving from awareness into evidence of execution. Financial firms need tested escalation authority, recovery plans, dependency mapping and governance that still works when incident timelines compress. The supervisory question is increasingly whether organizations can prove those controls operate under pressure, not whether boards have discussed AI risk.
The mandate changes how payment innovation enters supervisory decision making at the central bank. Stablecoin and payment infrastructure proposals will still have to satisfy financial stability requirements, but innovation becomes an explicit secondary consideration rather than an external policy goal. The practical test is how that mandate affects approvals, infrastructure design and competition as new payment models reach systemic scale.
The notice separates sports and entertainment products from the limited event contracts already available through Canadian investment dealers. NCFA’s event contract infrastructure brief tracks the dealer controls, surveillance, settlement and product-classification requirements connected to permitted contracts.
The final rule directs supervisory attention toward material financial risk and compliance with banking law. It also requires the agencies to tailor unsafe-or-unsound findings and MRA treatment to institution-specific risk factors. The rule does not apply to institutions outside OCC or FDIC supervision.
Payment firms and stablecoin providers will gain a formal innovation consideration within Bank of England supervision, but no automatic approval or lighter standard. Product teams will still need to prove that new payment models protect stability, resilience and users.
The proposed consent judgment gives algorithm design liability a concrete control framework built around age assurance, usage restrictions and parental permissions. Fintech teams offering youth accounts, gamified investing or automated recommendations can compare their controls with these requirements while the court reviews the agreement.
Thailand is working on both sides of institutional crypto access at once: the investment product investors can buy and the custody arrangements funds can use behind it. That puts product approval, offshore asset safeguarding and institutional distribution inside the same regulatory design problem rather than treating crypto ETFs as a listing question alone.
Control of the rails, data, distribution and risk is becoming more valuable. Capital is concentrating around firms that can prove scale and economics, while banks and infrastructure providers invest directly in tokenized settlement, real-time funding, AI and fraud controls. The opportunity remains large, but owning a critical part of how money moves is becoming more valuable than adding another product.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 28, 2026 | NCFA Insight | Regulation And Policy, Capital Markets And Market Infrastructure, Wealthtech Investing And Trading, Risk Compliance And Regtech
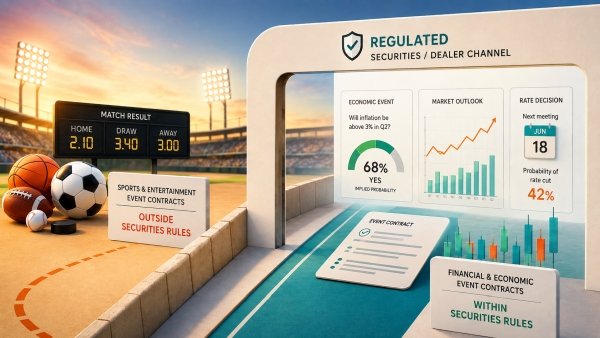
On August 27, 2026, the Canadian Securities Administrators (CSA) and Canadian Investment Regulatory Organization (CIRO) issued new guidance on sports and entertainment event contracts. The CSA says those contracts belong outside securities and derivatives regulation, and CIRO will not approve dealer members to trade them.
The decision closes the securities-dealer route without banning every sports prediction market category under every Canadian law. Gaming and other applicable rules can still determine what is permitted elsewhere, but Canadian investment dealers now know sports and entertainment will not join the event contracts they can distribute through CIRO.
CIRO currently allows two investment dealers, Wealthsimple Investments Inc. and Interactive Brokers Canada Inc., to facilitate a limited set of contracts tied to economic forecasts, environmental outcomes and financial indicators. Permitted contracts generally need at least 30 days to maturity, clients cannot use leverage, and elections, referendums, political nominations and other political events remain prohibited.
In the U.S., sports category helped prediction markets reach a much larger audience. Prediction Markets Tighten As Wealthsimple Enters noted in March that a March Madness winner contract had already exceeded US$100 million in volume and 2026 Super Bowl contracts topped US$1 billion. Canada is now explicitly removing that demand interest from the securities-dealer channel.
That leaves economic, environmental and financial contracts to prove they can generate repeat participation and enough liquidity to remain useful. Rates, inflation, housing and climate outcomes can carry real forecasting value, but they don't naturally produce the same frequency, fan interest or habitual trading as professional sports.
Platforms are also experimenting with how prediction markets are presented. CRSHMARKET's livestream prediction-market model combines live video, creators and event contracts to make participation more immediate. That doesn't change Canada's regulatory limits, but it highlights why product format is important to growth if permitted contracts have to compete for attention without sports.
A contract within CIRO's permitted categories can potentially reach Canadian clients through an authorized investment dealer, while sports and entertainment contracts cannot use that route. Product teams therefore need to understand the event being priced, the applicable regulator and the distribution rules before estimating the addressable market.
As a result, the need for regulated event contract infrastructure is more valuable. Platforms need compliance controls, market surveillance, outcome verification, settlement and dealer integration, but they also need to know which contracts can be offered through which channel.
Infrastructure providers that help firms classify products, apply the right controls, integrate regulated distribution and settle outcomes can serve multiple markets even when the permitted contract set differs by jurisdiction.
CSA and CIRO say they are still assessing other types of event contracts. They haven't said which additional categories may eventually fit inside securities and derivatives regulation or which will remain outside it.
Those decisions will help determine the size of Canada's regulated prediction-market business. If CIRO dealers remain concentrated on economic, environmental and financial indicators, the sector may develop mainly as a forecasting and investment product. Additional permitted categories could create more reasons to trade and more opportunities for liquidity to build.
Regulators still need to consider market manipulation, insider information, outcome integrity and whether a particular event belongs inside financial regulation at all.
Can Canadian prediction markets build enough liquidity around economic, environmental and financial events without the sports contracts that helped drive U.S. adoption?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 28, 2026 | NCFA Insight | Open Banking Open Finance And Data Sharing, Digital Identity And Trust, Risk Compliance And Regtech, Cybersecurity And Fraud
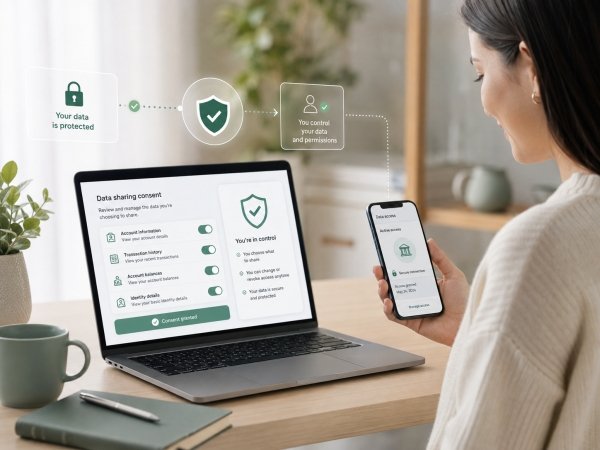
On August 26, 2026, Canada’s Office of the Privacy Commissioner (OPC) called for five changes to Canada’s proposed Consumer-Driven Banking Regulations including what financial data can be shared, what firms must prove before accreditation, when public data can be reused without consent, how security keeps pace with new threats, and how the Bank of Canada and Privacy Commissioner coordinate oversight.
The submission arrived on the last day of the government's 60-day consultation, which closed August 26. Finance Canada now has to decide which recommendations make it into the final regulations before Canada's open banking system starts moving from rulemaking into accreditation and implementation.
The Commissioner supports consumer-directed data sharing, multi-factor authentication and mandatory breach reporting to the Bank of Canada. The five requested changes go further and could affect compliance costs, product design, consumer trust and which fintechs can afford to participate.
The proposed regulations cover identity information, account identifiers, fees and terms, balances, transactions and information about financial products. The OPC says those categories aren't detailed enough for consumers to know exactly what information they are agreeing to share and points to Australia’s Consumer Data Right as a more precise model.
It's important when someone is looking at a consent screen. "Identity data" doesn't tell a customer whether a provider will receive a name, address, email, phone number or other information.
The issue becomes more important as firms combine bank data with other sources and use it for credit, fraud, pricing or financial recommendations. Open banking decision intelligence becomes more valuable as firms infer more from permissioned financial data, which makes precision about what was actually shared even more important.
If Canada wants meaningful consent, people need to know what is leaving their bank before they approve it.
The proposed rules offer four accreditation routes under Bank of Canada oversight, including streamlined treatment for payment service providers already registered under the Retail Payment Activities Act. The OPC wants stronger proof from some applicants, including evidence that security controls are working, technical standards are being met and authentication and complaint processes are ready.
It also wants certain financial institutions to show that people responsible for consumer-driven banking have been assessed for good character and integrity, and that insurance or other guarantees are available to manage data-related risks.
That raises the accreditation bar for good reason. Accredited firms may receive account identifiers, balances, transaction histories and other highly sensitive information. The commercial question now is how much proof Canada requires and what it costs credible firms to provide it.
Finance Canada estimates the proposed regulations will generate C$13.2 billion in benefits over ten years while adding about C$457.7 million in regulatory costs. Under the government's central scenario, roughly 680 businesses participate initially, including 578 small businesses, with an estimated average annualized regulatory cost of C$89,133 for each small business.
Large financial institutions can spread fixed security, legal and reporting costs across millions of customers. Smaller fintechs can't. Canada needs to keep poorly prepared firms away from consumer financial data without making the cost of proving readiness another advantage for incumbents.
The OPC also wants Finance Canada to narrow an exception that allows some publicly available information to be used without consent. Its recommendation is that public data should not include information where a consumer still has a reasonable expectation of privacy.
Information can technically be public without someone expecting it to be collected, combined with financial records and reused inside a commercial service. Open banking makes those combinations easier and potentially more valuable.
The final rules therefore need to protect against a consent loophole where one piece of public information becomes a reason to use financial information in ways the customer didn't reasonably expect.
The proposed regulations already require vulnerability management, authentication, encryption, network protection, employee training and tested incident-response plans, with those controls applied in proportion to the sensitivity of the data. The OPC wants an additional obligation requiring firms to keep those safeguards appropriate as technology and cyber risks evolve.
That's certainly more demanding than completing a checklist once. After a breach, a firm could still have to show that its security was appropriate for the data it held and the risks it should reasonably have been managing.
For banks and fintechs, security readiness therefore becomes an ongoing operating requirement. Canada's proposed open banking requirements already span accreditation, authentication, security, technical standards, liability, complaints and Bank of Canada supervision. Companies preparing to participate need proof that those controls actually work, not just policies saying they exist.
The Bank of Canada will supervise consumer-driven banking participants while the Privacy Commissioner continues to oversee federal private-sector privacy obligations. A serious data breach can involve both, so the OPC wants explicit authority for the regulators to coordinate their work and share information where necessary.
Without that, companies can face overlapping requests and investigations while an important issue still falls between mandates. When customer data is exposed, management needs to know who must be notified, what each regulator expects and how the two authorities will divide the work.
Clear coordination is especially important because Canada is trying to replace a system millions of people already use. Finance Canada estimates roughly nine million Canadians currently rely on financial-data services using credential-based screen scraping. Regulated API access should reduce important security and liability risks, but only if supervision works cleanly when something goes wrong.
The OPC is asking Finance Canada to be more precise about what data moves, who can receive it and what firms must prove before they get access. Those protections however cost money. Independent security work, technical compliance, authentication, insurance, reporting and complaint processes all consume capital that a younger company could otherwise spend on product development, hiring or customer acquisition.
The answer isn't weaker safeguards. Financial transaction data is too sensitive for that. The challenge is to determine whether each requirement addresses a real risk and whether the cost is proportionate to the firm, activity and data involved.
Canada's C$13.2 billion benefit estimate assumes firms enter the market and build services people want to use. Open banking opportunities in Canada already span verification, cash-flow tools, SME services, financial management and future payment initiation, but APIs alone won't create competition.
Consumers need providers they trust, and credible challengers need a realistic way to qualify. The final rules will help decide both.
How high can Canada raise the privacy and security bar for open banking before the cost of clearing it starts protecting incumbents from the competition the system is supposed to create?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
The Privacy Commissioner wants clearer rules in five areas: exactly what financial data can be shared, what firms must prove before accreditation, when publicly available data can be used without consent, how security safeguards should keep pace with changing threats, and how the Bank of Canada and Privacy Commissioner coordinate oversight.
No. The 60-day consultation on the proposed Consumer-Driven Banking Regulations closed on August 26, 2026. Finance Canada now has to decide what changes to make before the regulations are finalized.
Yes. Stronger accreditation, security, insurance and compliance requirements can improve consumer trust and keep poorly prepared firms out, but they also raise the cost of participation. The challenge is setting a high enough bar to protect financial data without making open banking too expensive for credible smaller fintechs to enter.
| | |
|---|---|---|
| | |
August 26, 2026 | NCFA Insight | Regulation And Policy, Artificial Intelligence And Data, Risk Compliance And Regtech, Competition And Market Structure
On August 26, 2026, U.S. attorneys general announced a settlement with Meta worth up to US$17.1 billion over allegations that Facebook and Instagram were designed to keep children and teens engaged despite risks to their health and well-being. If the court approves the agreement, Meta also has to limit how long minors can use its apps, restrict overnight access and school-hour notifications, strengthen age checks and give families more control over what young users see.
Meta isn't required to admit it did anything wrong under the settlement. It does expect to record an approximately US$10 billion legal expense in Q3 2026. Governments aren't only extracting billions from Meta. They're putting enforceable limits on features that help determine how often young people open Facebook and Instagram, how long they stay and what keeps them scrolling.
Users under 18 will start with a combined two-hour daily limit across Facebook and Instagram. Parents can approve more time, but teens can't simply turn the limit off themselves. Meta also has to block most access from midnight to 6 a.m. by default and mute most notifications during school hours.
The agreement goes deeper. Teens get regular break prompts and more control over personalized feeds, autoplay and visible like counts. Meta also has to strengthen age assurance, identify children under 13, improve parental controls and maintain protections against harmful content and unwanted adult contact.
Recommendations, notifications, autoplay and frictionless consumption help technology companies turn attention into usage, retention and advertising revenue. That's why the settlement is strategically important. A feature can be commercially valuable for years and still become expensive if evidence eventually shows that the same behaviour driving engagement is contributing to harm.
NCFA's Algorithms Go On Trial As AI Scales Across Society unveiled the lawsuits challenging recommendation systems, infinite scroll, autoplay and notifications as deliberate product choices rather than simply arguing about what users post. Those cases have now produced jury findings, large financial awards and operating restrictions. The debate over addictive design is becoming much harder for boards to leave with legal counsel or the product team.
Meta can afford the settlement though. The company earned enough to absorb an approximately US$10 billion quarterly legal charge without changing the financial guidance it gave investors in July. Markets also reacted positively after the settlement was announced, reflecting relief that Meta avoided the potentially larger uncertainty of continuing the federal trial.
That is precisely why boards should study what happened.
Years of complaints, research, lawsuits and internal evidence accumulated around the same basic concern: were Facebook and Instagram using product features to keep children engaged in ways that could harm them? The exposure grew from a difficult policy issue into jury verdicts, court-ordered controls and now one of the largest state settlements ever reached with a single company.
August coverage of the New Mexico Meta ruling showed how quickly the consequences were already expanding. That case combined a US$375 million jury award with a further US$567 million abatement fund and requirements affecting teen usage, notifications, age assurance, adult contact and AI chatbot interactions involving minors.
If management keeps getting signals that a profitable feature may be harming young users and keeps pushing it anyway, the issue eventually belongs with the board. Investors should know when those warnings reach directors, what they’re told and who can decide that the revenue is no longer worth the risk.
Meta also negotiated an unusually strategic feature into the settlement.
Its own disclosure describes an approximately US$18 billion payment structure over ten years. About US$12.7 billion is allocated to participating states regardless of what competitors do. Roughly US$5.3 billion is released only if both TikTok and YouTube adopt specified teen protections and make matching payments.
That gives Meta billions of reasons to bring its competitors along.
Commercially, the logic makes sense given the amount of competition. If Facebook and Instagram restrict teen usage while TikTok and YouTube remain more permissive, users and coveted 'attention' can migrate to competing apps. Meta bears the cost while rivals gain more opportunity to capture the hours, content consumption and advertising inventory Meta gives up.
The terms get tougher if TikTok and YouTube participate. Meta's daily limit falls from two hours across Facebook and Instagram to one hour per app, while its nighttime block expands from midnight to 6 a.m. to 10 p.m. through 7 a.m.
So Meta isn't simply asking competitors to copy its safety policies. It is trying to prevent child-safety rules from becoming a competitive handicap carried mainly by Facebook and Instagram.
TikTok and YouTube haven't agreed to the framework. Until they do, Meta could still end up operating under restrictions its largest rivals don't share.
Concern about how digital products affect children has been building for years. In 2023, NCFA analyzed Canadian research into children's privacy and consent that called for stronger safeguards to be built into digital products from the start. Children don't assess consent, persuasive design or data collection the way adults do, yet personalization and recommendation systems routinely influence what they watch, read and do next.
Meta's settlement gives those concerns a much larger financial consequence. Governments are no longer relying only on warnings or disclosure requirements. They are specifying age checks, usage limits, notification controls, parental oversight and independent monitoring.
Once those requirements appear in a multibillion-dollar agreement, other platforms know what regulators may ask for next. The settlement doesn't create legal precedent, but it gives attorneys general a detailed set of measures they can use in future negotiations and enforcement.
AI companions and conversational assistants can respond personally, remember context and keep conversations going. Research into youth use of AI reported that 72% of teens had tried AI companions and examined evidence of young people using generative AI for emotional and mental health support.
AI can change the type of exposure a child experiences. A recommendation feed influences what a young person sees next. An AI system can respond directly, adapt to the conversation and encourage the user to keep engaging.
For companies serving children or vulnerable users, it's even more important to know what the system is encouraging, where harmful patterns are appearing and who can change the product when the interaction becomes uncomfortable.
The same principle can be seen in fintech where younger customers use digital wallets, investing apps, financial education tools and AI assistants. Meta's settlement rules don't apply to those products. The relevant lesson is that companies need to understand how their own systems influence behaviour before a regulator or court does it for them.
Meta's US$17.1 billion settlement shows how expensive the problem can become when concerns about engagement, harm and product design build for years without a convincing response.
When a company knows a profitable engagement feature may be harming young users, who should have the authority to decide when growth has gone too far?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016