




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Oct 30, 2026
When playing in an online casino, Canadians are offered a wide variety of different ways of adding their funds. While it’s easy to take this for granted, we need to take a look at the Canadian banking and fintech ecosystem, as well as the gambling industry, to understand why players here are able to make deposits in so many ways.
In most other countries, traditional bank transfers and cards lead the way in terms of casino use. When we look at the accepted deposit methods for this online casino in Canada, we see that Visa and MasterCard are accepted, as well as the Paysafecard, which is a prepaid card. However, Interac leads the way in Canada.
This is offered as both a deposit and withdrawal method, which not all of the other methods are listed as being suitable for. It also has a low minimum amount and a relatively high maximum when compared to others, meaning that it can be used as a flexible way of starting to play slots and table games.
Its popularity is due to the fact that it’s easy to use, as well as being fast and safe. Interac acts as a type of Account-to-Account (A2A) bridge that allows users to send funds directly from their main bank account to a casino wallet. The ease of use aspect is enhanced by the fact that players simply use their existing mobile banking applications with the same multi-factor authentication they always use.
This means that the likes of credit card numbers and bank details aren’t at risk of being exposed in any way. For the casinos, there isn’t the same risk of chargebacks, fraud, and other potential issues, which helps to explain why the limits are higher.
Interac was created by the Big Five banks in Canada, who agreed on the shared protocols and standards needed to create a cohesive bank transfer system, the likes of which have been impossible to implement in the US or Europe. However, it wouldn’t have been possible without the work of fintechs including VoPay, Central 1, and Gigagat, which have each filled a gap in the ecosystem.
Despite the fact that Interac dominates the online payments scene in Canada, traditional debit and credit cards from networks such as Visa and Mastercard can also be used to make deposits. Their ongoing popularity is based on the fact that using cards is a cultural habit here. With about 101 million credit cards in circulation for a population of 40 million, Canada has one of the world’s highest credit card penetration rates.
Cards have typically been used here for a wide range of purposes and instant payments, although some banks and card issuers have been known to block casino payments. Fintech developments in recent years have led to sophisticated dynamic transaction routing and boosted approval rates for credit card users.
Montreal-headquartered Nuvei is one of the largest companies in the B2B payment industry, and it has spread internationally, with recent developments allowing it to process payments for international airlines and retailers in Israel. A $2.75 billion deal with Payoneer will let Nuvei target the country’s technical exporters too.
Companies like Moneris and Elavon Canada partner with fintech brokers to provide dynamic merchant accounts that make payments slicker. This means that adding funds to a casino account using a credit or debit card is still regarded as a safe, modern option, even when compared to Interac and e-wallets.
The growth of the iGaming market in Canada means that many platforms offer welcome bonuses to attract new players. This is a great way for newcomers to sample the games.
Not all of the payment methods that are accepted for deposits will receive a bonus, though. We typically see that Neteller and Skrill are excluded from the bonus terms, meaning that alternative methods such as Interac, Visa, Neosurf, and Cash2Code are sometimes preferred by players after joining up.
The payment methods that allow bonus payments generally provide a higher level of control because they include stronger know your customer (KYC) approaches and carry less risk of chargebacks at a later date.
For example, an Interac e-Transfer is routed through one of Canada’s Tier-1 banks, which means that every deposit made in this way is linked to a verified Canadian bank account. With Visa and Mastercard, secure protocols introduced by companies like Nuvei and Moneris provide context that allows the casino’s system to confirm the cardholder's identity in real time.
The way that Canadian play slots and table games online has changed due to new rules, themes, and ways of playing. However, the way that the country’s fintechs and banks have made it easier to move funds to casino wallets has arguably been even more important.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Oct 30, 2026
Vancouver is one of Canada's most expensive places to employ household staff, and B.C. has its own rules for anyone working in a private home. Both points shape the search. A full-time private chef in Vancouver typically cooks for one family five or six days a week and takes over grocery shopping, meal planning, kitchen inventory, and cleanup. For households in West Vancouver, Shaughnessy, Kitsilano, or Point Grey with demanding work schedules, the role often pays for itself in time saved, but hiring one is closer to recruiting a senior employee than booking a caterer.
Here is how to approach it.
Write a job description first. Most households skip this step, and vague expectations are the most common reason these placements end within the first year.
Start with the schedule. Will the chef cook every meal of the day, or only dinners plus weekly meal prep? Then consider the household: how many people the chef will feed on a typical day, how often you entertain, and whether you need someone willing to travel with you to Whistler on weekends or to a Gulf Islands cottage in summer. Live-in arrangements deserve their own conversation. Given Vancouver rent costs, private accommodation has real value for a candidate, and it changes both the salary discussion and the legal paperwork.
Dietary direction belongs in the description too. A family following a plant-based or low-sodium plan needs a chef with that experience on their résumé, and Vancouver's large community of health-focused cooks means those candidates exist. Stating it upfront quickly filters out the wrong applicants.
Be just as clear about where the job ends. Some families expect help with school lunches or light housekeeping, while most career chefs want to stay focused on cooking. A mismatch here causes friction within weeks, so list any non-cooking duties plainly.
Pay depends on scope and experience. Full-time household chefs in Metro Vancouver commonly earn $70,000 to $120,000 a year, and roles with frequent entertaining or travel can pay more. Candidates from the city's restaurant scene will compare your offer with kitchen salaries plus tips, so a lowball number often ends the conversation early.
Experienced candidates look at the full package, which typically includes the following.
Your total cost will run higher than the salary, because employers pay their own share of Canada Pension Plan (CPP) contributions and Employment Insurance (EI) premiums. Running the numbers through payroll built into HR software before you make an offer gives you an accurate figure, and the same tool can handle pay stubs and remittances once the chef starts.
Specialized household staffing agencies are the most reliable source for this level of hire. They charge a placement fee, usually a percentage of first-year salary, yet candidates arrive pre-screened with verified references. Ask any agency about its guarantee period, since many will replace the hire at no extra cost if the placement ends within the first few months.
Referrals from friends who already employ household staff can work well too. So can Vancouver's restaurant and hotel kitchens, where plenty of cooks want the steadier hours of private service. Expect an adjustment period with those hires, because cooking to one family's preferences every day is a very different job from running a dinner line on Robson or in Gastown.
A résumé shows where someone has worked. It says little about whether they will fit into your home. Use the first interview to talk through daily routines, how they handle last-minute changes, and how they communicate when something goes wrong.
Shortlisted candidates should then be invited to a paid trial, usually a full day of cooking in your kitchen. Send a short written brief beforehand so you can judge the food against what you asked for. Pay attention to how they shop, too. A chef who already knows which Granville Island vendors carry the best halibut, or when Fraser Valley berries peak, will cook more seasonally and waste less. Call at least two previous household employers and ask directly why the candidate left. A criminal record check, done with the candidate's written consent, is standard practice for anyone with keys to your home.
A full-time chef who works on your schedule and under your direction is almost always an employee in the eyes of the Canada Revenue Agency (CRA), whatever title the contract uses. You will need to open a CRA payroll account, even as a private household. CPP and EI are then deducted from each paycheque alongside income tax and remitted on schedule, and a T4 slip is issued by the end of February each year. Getting this wrong can leave you owing both the employer and employee shares, plus penalties and interest.
Some families employ household staff through a holding company or family office. If that applies to you, review that company's coverage before the chef starts.
B.C.'s Employment Standards Act has specific provisions for domestic workers, including a written employment contract that sets out duties, hours, wages, and any room and board charges. Standard B.C. rules apply on top of that. Overtime is paid at time and a half after eight hours in a day or 40 in a week, and employees are entitled to five paid sick days a year along with statutory holiday pay.
Workers' compensation is the step families most often miss. According to WorkSafeBC's guidance for homeowners, anyone who hires a person for ongoing home services, chefs included, needs coverage once that person works eight or more hours a week. A full-time chef clears that threshold in a single day, and premiums are generally assessed on the wages you pay, so the cost is modest next to the protection it provides.
Families recruiting from outside Canada face an extra step. A positive Labour Market Impact Assessment (LMIA) is generally required before a foreign national can be hired, and processing can take months, so plan early and consider working with an immigration lawyer.
Retention starts on day one. Schedule a check-in after the first month and again before probation ends, and keep the feedback specific. Chefs leave private service most often over unclear expectations or stalled pay, and both are fixable with regular, honest conversations. An annual salary review goes a long way in a city where living costs keep climbing. Give the chef room to suggest new dishes as well, because cooks stuck on the same weekly rotation are the ones who start answering recruiters' calls.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 29, 2026 | NCFA Story Intelligence | Capital Markets Infrastructure And Funding, Artificial Intelligence And Data, Competition And Market Structure
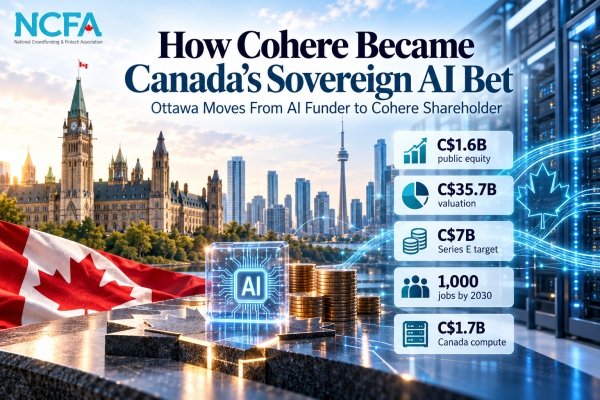
On October 29, 2026, the Ottawa announced plans to invest up to C$1.6 billion in Toronto based Cohere as part of a Series E financing targeting as much as C$7 billion, putting public money directly into a Toronto company that is trying to build a Canadian and European alternative to the dominant US AI platforms. The deal would make Ottawa more than a supporter of Canadian AI. It would make the federal government a shareholder in one of the country’s most valuable private technology companies, at a time when Canada is pushing for greater digital sovereignty and Cohere is expanding deeper into Europe and global enterprise markets.
The government says the investment will be made in stages. Cohere must keep its Canadian incorporation and headquarters, create at least 1,000 new Canadian technical jobs by 2030, and commit at least C$1.7 billion to additional computing infrastructure in Canada. Cohere is entering the deal from a much stronger position than it occupied two years ago. Its Series E is targeting up to C$7 billion at a stated C$35.7 billion valuation. Schwarz Group leads the round. NVIDIA, Bell Ventures, Inovia Capital, Prosperity7 Ventures and other investors are participating. Cohere says its annual recurring revenue grew 165% year over year in the third quarter of 2026 and its customer base expanded twentyfold to about 300 customers.1
Ottawa calls this a sovereignty investment. Prime Minister Mark Carney says Canada needs the ability to build, adopt and govern AI on its own terms, while taking equity lets Canadians share in Cohere’s success if the company keeps climbing.
The sovereignty case and the investment case aren’t the same thing. Canada can value domestic AI capacity even if Cohere never becomes a great financial investment. It can also make money if Cohere becomes a much larger global company. Ottawa is now trying to do both.
What follows is a story of a Canadian AI company finding a different lane, moving closer to government, crossing the Atlantic for scale, and returning to a cap table where Canada itself now wants a seat.
By early 2024, Reuters reports Cohere’s annualized revenue has climbed from about US$13 million to roughly US$35 million by the end of March. The company is growing, but the numbers also show how far it sits from the largest US AI platforms.2
Cohere leans into control instead of reach. Its pitch increasingly centres on private deployment, data security, cloud choice and enterprise customization. The company can compete without needing to win the consumer chatbot popularity contest.
The customer list gets heavier. Cohere names RBC, TD Bank, Bell, Fujitsu, PwC and other large organizations among customers. Private deployment gives the company a route into sectors where security, residency and compliance can block consumer oriented tools.
The scale gap hasn’t disappeared. Anthropic reported US$16.29 billion of revenue in the first half of 2026 in its IPO filing, while OpenAI and other US platforms remain far larger in consumer reach and capital commitments.5 Cohere is trying to win a different buying decision.
The C$240 million support is not the same as today’s equity. Federal records describe the earlier deal as a contribution tied to compute expansion. Ottawa gets economic and strategic benefits if the project succeeds, but it does not participate in Cohere’s valuation the way a shareholder does.
Cohere keeps raising privately. In August 2025 it raises US$500 million at a US$6.8 billion valuation. Cohere Raises $500M at $6.8B for Enterprise Agentic AI shows a company still relying on venture, pension and strategic investors while government support sits outside the cap table.
Europe offers customers, public sector relationships and a policy environment that already prizes data control and local infrastructure. Cohere gains another route to market without having to imitate the consumer led strategies of the largest US firms.
Europe also brings competition. France’s Mistral is raising billions around a European AI champion of its own. US platforms are selling aggressively into the same enterprise accounts. Sovereignty creates demand, but it doesn’t hand Cohere the market.
Something could go very right. If Cohere turns its enterprise and sovereign AI position into a much larger global business, Canada participates in the appreciation instead of collecting only jobs, tax revenue and infrastructure benefits. A future valuation above C$35.7 billion would make equity look very different from another contribution.
The same structure exposes taxpayers to the downside. A private valuation can reset. New rounds can dilute shareholders. Compute spending can consume capital quickly. Cohere may deliver strategic benefits to Canada while still producing a weak investment return. Sovereignty doesn’t erase price.
Canada’s new Canada Launches $1.75B Venture and Growth Capital Plan mostly uses public money to attract private investors through funds and managers. Cohere is a far more concentrated position in one company.
The price is already much higher than it was last year. Cohere raised at a US$6.8 billion valuation in August 2025. The new round points to C$35.7 billion after a year of product growth, acquisitions, European expansion and the Aleph Alpha combination. Ottawa is buying after the story has already moved.
Cohere gives Ottawa a rare chance to test two ideas at once.
The first is strategic. Canada wants more control over the AI systems that governments, banks and other critical organizations may eventually depend on. Cohere’s architecture, Canadian roots and Europe strategy fit that ambition better than handing every sensitive workload to a foreign hyperscaler or consumer AI company.
The second is financial. Instead of paying only for infrastructure, research or jobs, Ottawa wants equity. If Cohere becomes one of the few globally important enterprise AI companies outside the United States and China, taxpayers own part of the upside.
The company has earned a stronger hand than it had two years ago. Revenue has grown, the customer list has widened, North has moved into production environments, European expansion is real, and Schwarz Group has put capital and infrastructure behind the transatlantic strategy.
There is still plenty the public can’t see. Cohere doesn’t disclose net profit or cash burn. Ottawa hasn’t published the ownership percentage or shareholder protections. Nobody outside the deal can yet judge whether C$35.7 billion is an attractive entry price for taxpayers.
Canada may be right about the strategic asset and still have to prove it bought the asset well.
The investment becomes more interesting if Cohere keeps compounding from here. It becomes more difficult if the company needs repeated public support, the valuation falls, or strategic goals start masking weak investment performance.
Cohere has spent seven years trying to prove a Canadian AI company can scale without becoming another US platform. Ottawa has now put C$1.6 billion behind the next chapter.
If Canada wants to become an owner of national champions, Cohere will help show whether it can act like one.
The government has announced an equity commitment of up to C$1.6 billion, but it hasn’t disclosed the ownership percentage, share class, voting rights, board rights, liquidation preference, dilution protections or exit terms. Those details are needed before the investment economics can be judged properly.
Cohere reports rapid ARR and customer growth, and Reuters has reported strong margins around its private deployment strategy. The company does not publicly disclose net income, cash burn or complete financial statements, so profitability cannot be confirmed from public information.
Ottawa says the equity will be invested in stages with regular reporting on jobs and Canadian investment. The public announcement does not disclose the consequences for missed milestones or whether later stages can be withheld.
Ottawa has not said the Cohere structure will become a standard program. The Canada Strong Fund does point in the same direction by making commercial equity ownership a larger part of federal economic policy. Cohere may become an early test of how those strategic and financial objectives work together.
Budget 2025 Accelerates Fintech, AI, and Capital Growth
How federal AI infrastructure and growth capital policy started converging before direct Cohere equity arrived.
Canada Adds Competitiveness to Federal Regulation
A wider look at Ottawa’s push to put competitiveness more directly into federal economic and regulatory decisions.
National Security Is Now Part of Financial Supervision
Why sovereignty, infrastructure control and national security are moving deeper into financial and technology policy.
Why AI Investment Is Missing What Workers Actually Want
A reminder that capital and technical capability still have to translate into adoption, useful work and measurable outcomes.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 28, 2026 | NCFA Market Activity | Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Competition And Market Structure
Wealthsimple's C$13.8 Billion Valuation Backs Expansion Into Banking, Credit and Business Finance
On October 27, 2026, Toronto fintech Wealthsimple announced a C$425 million financing agreement at a C$13.8 billion post money valuation. Singapore sovereign wealth fund GIC is leading the round, with Power Corporation, IGM Financial, ICONIQ, CPP Investments and Inovia participating. Wealthsimple will receive C$300 million in new capital, while up to C$125 million will be used to purchase existing shares from eligible employees.
The valuation is 38% above the C$10 billion reached in Wealthsimple's October 2025 financing. Since then, Wealthsimple has expanded further beyond investing into chequing, spending, credit and business finance. With more than four million customers, Wealthsimple already has a large base of Canadians using its platform. Building that kind of reach is much harder than launching another financial product.
Wealthsimple reported C$169.2 billion in assets under administration as of September 30, 2026, up from C$100 billion at its October 2025 financing. That's an increase of C$69.2 billion, or 69%, in less than a year. The increase includes both market appreciation and new money entering the platform, so it can't be treated as a direct measure of market share gained from competitors.
Separate transfer data provides clearer evidence of competitive movement. Wealthsimple recorded the highest number of account transfers in the company's history during Q1 2026. It has also told Finance Canada that customers are moving investment accounts from other financial institutions and that record transfer activity shows Canadians are actively shopping for value. Wealthsimple doesn't disclose which institutions are losing those assets, so the public data can't show how much is coming specifically from Canada's major banks. But the direction of travel is clear. Some investment assets are moving from incumbent financial institutions onto Wealthsimple's platform.
For Wealthsimple, every account transferred onto the platform can become more than an investment relationship. A customer who already holds investments there can add chequing, credit or business services without Wealthsimple having to win that person from scratch. The larger the asset and customer base becomes, the more products Wealthsimple can build around relationships it already owns.
The new financing gives Wealthsimple C$300 million of fresh capital to keep building that model. The separate secondary component gives eligible employees a chance to sell up to C$125 million of existing shares while Wealthsimple remains private.
Existing shareholders are also putting in more money. IGM Financial is investing another C$96 million and expects to retain a 25.1% interest after closing. Power Financial is contributing C$68 million, bringing the Power group's combined participation to C$164 million. GIC, which helped lead Wealthsimple's C$750 million financing last year, is leading this round.
GIC managing director Vinay Yarlagadda pointed to Wealthsimple's customer focus and pace of product development as qualities the investor sees in exceptional companies globally. That view now comes with another large commitment of capital from GIC and several major Canadian institutional investors.
The size of the round also stands out in Canada's fintech market. KPMG's Canadian fintech funding data showed US$996.7 million invested across 47 deals in the first half of 2026, compared with about US$1.7 billion across 82 deals a year earlier. Wealthsimple's financing comes later in the year, but it reinforces a clear shift toward larger pools of capital concentrating around companies that have already reached meaningful scale.
The strongest sign that Wealthsimple is becoming more than an investment platform came in the second quarter of 2026. New chequing account openings surpassed investment account openings for the first time, while the company reported approximately C$17 billion in quarterly net inflows.
Chequing changes how often a customer can interact with Wealthsimple. Investing may involve periodic contributions and trades. A chequing account can be at the centre of payroll deposits, bills, transfers and daily spending. Once that activity moves onto the platform, Wealthsimple has more opportunities to connect investing, saving and credit around the same customer.
The company says it launched more than 50 products over the past year. Its May 2026 product expansion added business chequing, portfolio credit and family services. Wealthsimple has also expanded into options, futures, selected IPO access and cash deposits through more than 5,300 Canada Post locations.
Wealthsimple already serves more than 30,000 businesses. Business chequing gives it a base from which it could add more payments, cash management and credit services over time. The firm isn't a chartered Canadian bank. Its chequing services use financial institution partners, while Wealthsimple owns the digital relationship and provides the surrounding products. That structure lets it broaden its financial offering without building a traditional branch network.
Canada's incumbents are responding. BMO introduced zero commission trading through InvestorLine in September 2026, joining other Canadian providers that had already eliminated standard stock and ETF commissions. Low cost trading helped fintech companies attract investors. As that feature spreads, competition moves toward which provider can offer customers the most useful combination of investing, cash, credit and service.
KOHO is taking another route and is working towards becoming a bank. It has more than 2.5 million customers and is pursuing a Canadian bank licence as it expands its consumer financial offering.
Wealthsimple is expanding through its existing regulated businesses and financial institution partnerships. Both are trying to capture more of the customer relationship that has historically belonged to Canada's large banks, but they're using different structures to get there.
Two global fintech companies offer useful comparisons because they've already pushed further into the same convergence of investing, banking, payments and credit.
Revolut reported 68.3 million retail customers and 767,000 business customers at the end of 2025. Annual revenue reached US$6 billion, with 11 product lines each generating more than about US$135 million. Revolut Business accounted for 16% of total income. Revolut started in foreign exchange and payments and has since expanded across banking, investing, lending and business services. Its scale is far larger and its regulatory structure differs from Wealthsimple's, but the commercial lesson is relevant. One customer relationship can support several meaningful revenue streams when the products connect naturally.
Robinhood provides a closer comparison to Wealthsimple's investing roots. It reported 28.7 million funded customers and US$396 billion in platform assets in the third quarter of 2026. Quarterly revenue reached US$1.4 billion and Robinhood Gold subscriptions climbed to 5.2 million. The company said 14 business lines had reached at least US$100 million in annualized revenue. Robinhood has moved from trading into retirement products, subscriptions, cash management, credit cards and banking services. Wealthsimple is following the same broad logic in Canada, using its investment customer base to introduce services people may use more frequently.
The three companies have different market sizes, banking arrangements and product offerings. What they share is a strategy of earning more from customer relationships by connecting several financial services. Revolut shows the potential scale of everyday banking and business finance. Robinhood shows how an investing platform can expand into credit, cash and subscription products. Wealthsimple is bringing parts of both models into the Canadian market.
The Canadian market has its own dynamics. A small number of large banks already have deep relationships across deposits, mortgages, credit cards, investments and business finance. Wealthsimple's four million customers and C$169.2 billion in client assets give it enough scale to compete for more of those relationships one product at a time.
CEO and cofounder Michael Katchen summed up the strategy in the financing announcement, saying Wealthsimple plans to keep building until "every Canadian can live their entire financial life on Wealthsimple." The numbers behind this round show that investors are funding that broader financial services strategy, not simply another expansion of its trading business.
Wealthsimple's next phase seems to be how much of a customer's financial life it can pull away from incumbent institutions. Record account transfers show that movement has already started.
If chequing, credit and business services accelerate it, Canada's banks won't just be competing with Wealthsimple for new customers. They'll increasingly be competing to keep the assets and financial activity of customers they already have.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 28, 2026 | Lake Energy
Singapore— The global energy sector is undergoing a major transformation as countries invest in cleaner electricity, modernize power grids, and expand renewable energy capacity. Solar and wind power are becoming increasingly important sources of electricity, while hydropower, biomass, and battery storage are contributing to a more diverse energy system.
Growing electricity demand from businesses, digital infrastructure, and electric technologies is also increasing the focus on reliable energy supplies. As a result, renewable energy projects and supporting infrastructure have become important topics across financial and energy markets.
For cryptocurrency investors looking beyond digital asset trading, renewable energy offers another sector to explore. Lake Energy connects these interests through an online platform offering renewable energy investment plans and support for selected cryptocurrency funding methods.
Lake Energy offers investment plans related to solar power, wind energy, hydropower, biomass energy, and energy storage. Users can compare investment amounts, project durations, and stated terms to understand the options available.
The platform supports several digital assets, including BTC, ETH, XRP, USDT, and USDC, giving users multiple funding options.
Getting started involves three steps: creating an account, reviewing available projects, and selecting a plan based on its stated terms.
Visit lakeenergy.com and create an account by entering your username, email address, login password, and fund password. Complete the CAPTCHA and submit the registration form.
Every newly registered account receives a $10 welcome bonus, giving new users an additional incentive to explore the platform.
Solar energy: Investment: $500 | Period: 7 days | Daily Return: $5.25 | Return at Maturity: $500 + $36.75
Solar energy: Investment: $1,000 | Period: 15 days | Daily Return: $11.00 | Return at Maturity: $1,000 + $165
Wind energy: Investment: $3,000 | Period: 20 days | Daily Return: $34.50 | Return at Maturity: $3,000 + $690
Wind energy: Investment: $5,000 | Period: 25 days | Daily Return: $60.00 | Return at Maturity: $5,000 + $1,500
Energy storage: Investment: $10,000 | Period: 30 days | Daily Return: $126.00 | Return at Maturity: $10,000 + $3,780
Explore the available solar, wind, hydropower, biomass, and energy storage plans. Compare investment amounts, project durations, and the terms of each option to understand how the plans differ.
After reviewing the available information, select a plan that matches your preferences and follow the platform's instructions. Check the applicable funding requirements and settlement terms before completing the process.
Security is an important part of managing an online investment platform. Lake Energy's security framework encompasses website protection, data encryption, digital asset storage, and asset protection measures.
Lake Energy also uses TLS 1.2 encryption to protect information transmitted between users and its website, alongside encryption measures for stored data.
Together, these measures address key aspects of online security, digital asset custody, and account management.
Cryptocurrency and renewable energy operate in different markets. Digital assets are influenced by factors such as market activity and blockchain adoption, while renewable energy development is shaped by electricity demand, infrastructure investment, government policies, and technological progress.
For XRP holders interested in exploring sectors beyond cryptocurrency trading, renewable energy offers another area to research. Lake Energy brings renewable energy investment plans and supported digital asset funding options together in one online environment, allowing users to explore available projects and review their terms.
The transition to cleaner energy is reshaping electricity generation and infrastructure investment worldwide. As solar power, wind energy, and energy storage continue to develop, renewable energy remains an important sector for investors to follow.Lake Energy provides an online platform for exploring investment plans connected with these technologies. Visit lakeenergy.com to learn more about the available projects.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 28, 2026 | NCFA Story Intelligence | Regulation And Policy, Digital Assets Blockchain And Tokenization, Competition And Market Structure, Capital Markets Infrastructure And Funding
Binance thought it was leaving Canada in 2023. The regulatory fight stayed behind.
Binance never entered Canada the way a bank or securities dealer would. It didn’t open a Canadian branch, build a local exchange or wait for a Canadian licence. Changpeng Zhao was a Canadian entrepreneur who had studied computer science at McGill, but Binance launched in Shanghai in July 2017 and grew into the world’s largest crypto exchange by trading volume within about six months. The product was global from the start. Borders came later.
By 2021, Canadian regulators were catching up with what that model meant on the ground. Ontario pushed Binance out. Binance hired former regulators, incorporated in Alberta and tried to build its way back in. Then Canada tightened the rules again. On May 2, 2023, Binance told securities regulators it planned to withdraw nationally.
Eight days later, the OSC opened an investigation. The next day came a sweeping demand for company records. On May 12, Binance told the public it was leaving Canada.
The exit and the investigation crossed in real time. Binance was trying to close one Canadian chapter while the regulator was opening another.
Three years later, that unfinished business has reached the Supreme Court of Canada. Ontario’s Court of Appeal has already ruled that part of the OSC summons went too far. The OSC wants that ruling overturned. Nine interveners now include civil liberties groups, securities regulators and four governments.
What follows is a story of a borderless crypto company meeting national regulators, leaving some markets, adapting in others, and discovering that a market exit doesn’t make the regulatory past disappear.
Ontario treats access as local activity. The OSC’s position is that platforms offering securities or derivatives to Ontario users can’t avoid provincial rules simply because the company or servers sit somewhere else. For internet based finance, the customer’s location can pull a global platform into a local regulatory system.
Binance starts planning a return. By early 2022, Binance is doing something that would have looked unlikely months earlier. It hires former Canadian regulators, incorporates in Alberta and starts building toward full registration. Binance hires ex-regulators and incorporates in Alberta to charter compliance course in Canada catches the pivot. A few months later, Alberta-based Binance Canada expects to return to Ontario by 2024 shows how far the strategy has moved. The company isn’t talking about abandoning Canada. It is talking about coming back to Ontario through the front door.
The OSC gets enforceable controls. The undertaking turns account restrictions, product wind downs and monitoring into commitments the regulator can supervise. Binance is no longer only deciding what Ontario access should look like on its own.
Binance still sees a Canadian future. The company pursues registration outside Ontario and talks publicly about returning. That makes the national exit in 2023 more than a market withdrawal. It ends an attempted compliance strategy.
Binance blames the rule set, not Canada itself. The company says it delayed the decision while looking for another route and hopes to return someday. Canada is a relatively small market for Binance, but the evidence doesn’t establish that size alone drove the exit. The company’s own explanation focused on the rule set and the product limits that came with it.
Other platforms make a different calculation. Some exchanges also leave, while others pursue Canadian registration and accept narrower product menus. Every platform has to decide whether the local opportunity justifies the controls, product limits and ongoing supervision required to stay.
Regulators need records to reconstruct the past. Cross border platforms can spread staff, systems and legal entities across several countries. Without compulsory powers, investigators may struggle to establish who made a decision, which controls existed and what customers were told.
Broad demands carry real operating costs. A request covering years of email, chat, files and other communications can trigger preservation, data collection, legal review, privilege screening and cross border privacy work. A global exchange can spend heavily on that process. A smaller fintech may feel the same demand much more sharply.
The ruling protects relevance, not secrecy. The Court accepts that regulators have strong production powers and that privacy expectations for regulated business records can be low. It still requires a reasonable basis to believe compelled records may matter to the investigation.
The OSC sees a wider enforcement problem. The regulator argues that the Court of Appeal’s approach could make investigations slower and more difficult, particularly before investigators know exactly where useful evidence sits. Binance answers that regulators have had relevance limits for decades and can draft demands around the conduct they are actually investigating.
Investor protection still needs effective investigations. Regulators can’t police complex markets without access to records. Cross border digital businesses make that harder because relevant evidence may sit across entities, employees and systems that don’t line up neatly with one province.
Constitutional limits still matter inside regulated markets. Laura Paglia of the Canadian Forum for Financial Markets told Advisor.ca that securities regulators need broad powers, but argued that demands should remain proportionate and consider compliance costs. CFFiM was denied intervener status, so its view is industry commentary rather than a submission the Supreme Court will hear.14
Binance has already tried several endings in Canada.
First it left Ontario. Then it hired regulators and built an Alberta operation that was supposed to bring it back. Then it accepted an Ontario undertaking. Then it decided the national rules were no longer worth the trade and left Canada altogether.
The legal history kept going.
FINTRAC imposed a penalty tied to the years Binance operated here. Investors pursued a separate class action. Ontario courts rejected Binance’s attempt to force those investors into costly Hong Kong arbitration, a dispute later followed by Ontario Court Orders Binance To Pay Investor Legal Costs. The OSC kept investigating. The company that left Canada in 2023 is still litigating here in 2026.
Binance changed too. Zhao stepped down. A board arrived. Local licences and compliance teams became part of the growth strategy. Japan went from warning Binance to hosting a locally registered Binance business. Abu Dhabi became a regulated global base.
The Supreme Court case is now much bigger than Binance.
The Court is being asked to decide where constitutional limits sit when a regulator with legitimate investigative powers demands a very large volume of company records. A ruling that gives regulators wider latitude could make it easier to investigate complex businesses whose people, systems and data span multiple entities and countries. A ruling that requires a tighter connection between requested records and suspected conduct could force regulators to narrow summonses earlier and give companies stronger grounds to challenge sweeping demands.
Either way, the decision could shape how securities regulators design investigations, how regulated firms preserve and produce records, and how much compliance cost companies may face when regulators come looking for evidence. Depending on how broadly the Court reasons, its impact could also reach beyond capital markets into other regulated sectors that rely on statutory production powers.
That helps explain why governments, another securities regulator and civil liberties organizations have joined a dispute that began with one crypto exchange. The precedent could influence the balance between effective supervision and protection against regulatory overreach across Canadian business.
Binance spent years learning that global reach doesn’t erase national borders. Canada’s highest court is now deciding where one of those borders sits for regulators themselves.
Once a regulator has authority to investigate, how much of a company can it force open?
Binance left Canada. The company moved on. The answer could matter to regulated businesses long after this case is over.
INVESTOR GUIDE
7 Questions to Ask Before Choosing a Crypto Exchange in Canada
A current guide to registration, custody, transfers, funding, fees and operational risks Canadian investors should check before sending money to a crypto platform.
FINTECH INTELLIGENCE
Are Regulators Opening Markets While Raising Costs?
Market access can improve while evidence, records and supervision requirements get tougher, changing the economics for both incumbents and smaller entrants.
REGULATORY INSIGHT
Canada Proposes Stablecoin Market Entry Rules
Canada’s new stablecoin proposal shows how market access can depend on local custody, supervision and operating requirements, even when the underlying product is global.
REGULATION AND POLICY
National Security Is Now Part of Financial Supervision
Financial supervision is expanding beyond traditional capital and conduct questions into sanctions, cyber threats, ownership and state linked risk.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 27, 2026 | NCFA Regulatory Intelligence | Regulation And Policy, Capital Markets Infrastructure And Funding, Competition And Market Structure
Proposed Rule Changes Could Lower Financing Costs for Smaller Canadian Companies
On July 16, 2026, the Canadian Securities Administrators (CSA) published Consultation Paper 51-406 on modernizing public company regulation. The CSA wants feedback on whether simpler reporting rules and fewer private placement restrictions could help Canadian companies raise capital at a lower cost. The changes could affect financial reporting, institutional investment and access to financing, particularly for smaller listed businesses. Comments close November 13, 2026.
Two ideas stand out. (1) The CSA is considering a new exemption that could let qualifying public companies raise money from institutional investors without the usual four month restriction on reselling shares. (2) It is also asking whether a company's size and business operations should matter more when deciding which reporting rules apply. Both could affect the cost of raising capital and doing business as a public company. Nothing has been approved yet.
Canada had approximately 3,000 listed companies in March 2026, according to the CSA. About 76% were classified as venture issuers, and only 12% had a market value above C$1 billion. Most listed companies are relatively small, but they still pay for audits, accounting, legal advice and regular regulatory filings. Those expenses add up, especially for businesses that depend on outside investment to grow.
The consultation covers five main reporting questions.
Today, whether a company qualifies as a venture issuer largely depends on the exchange where its shares trade. The CSA wants to know whether revenue, assets, market value or the amount of shares held by public investors would be better measures. It is also considering changes to the existing system and whether larger venture issuers should move to senior exchanges.
A small company listed on a senior exchange may face more demanding reporting rules than a larger business on a venture exchange. Changing the criteria could make reporting costs more reasonable for some companies, although others might face new requirements. The rules would also need to be predictable so companies aren't forced to change their reporting practices every time their market value moves.
The CSA is asking whether certain venture issuers should receive relief from specific International Financial Reporting Standards (IFRS) requirements. Some accounting rules involve specialist advisers, detailed valuations and substantial preparation costs. Regulators want to know which requirements are particularly expensive and which information investors actually use. Any relief needs to save companies money without taking away financial information investors rely on.
Public companies generally must announce a material change promptly and then file a separate report within 10 days. A material change is an important development affecting a company's business, operations or capital. The CSA is asking whether a news release containing all the required information could replace the second filing when properly submitted through SEDAR+. It also wants to clarify which developments require a material change report. That could reduce legal bills and paperwork without leaving investors in the dark.
Certain eligible venture issuers can already choose to report financial results every six months instead of every quarter. The CSA is considering whether that option should be available to all public companies. Fewer reports could save money, but investors would have less frequent financial updates. That could be a concern for companies whose finances are changing quickly or that regularly need fresh capital. Regulators are also asking whether companies using this option should face additional conditions, particularly when raising money through a prospectus.
The US Securities and Exchange Commission (SEC) proposed several changes in May 2026. These include allowing public companies to report financial results every six months instead of quarterly, making it easier for more companies to raise money through registered share offerings, and reducing some reporting requirements for smaller businesses. The proposals aren't final rules yet.
The CSA wants feedback on whether similar changes would benefit Canada. Canadian companies compete with US businesses for investment, so differences in reporting costs and financing rules can matter. Making it cheaper and easier to raise capital could help Canadian companies compete, but investors still need reliable information to assess risk. Canada's large number of smaller listed companies also means US approaches may need to be adapted to suit.
Private placement rules are among the most important issues for companies trying to raise money. Under many existing exemptions, investors who buy newly issued shares from a public company must generally wait four months before reselling them. Because their money is tied up, they may demand a lower share price. That can leave founders and existing shareholders with less ownership after a financing.
The CSA is reviewing whether these restrictions are still necessary in every situation. One option is a new Qualified Institutional Purchaser (QIP) exemption. It could let eligible Canadian public companies sell shares to qualifying institutional investors through registered dealers without the usual four month resale restriction. Conditions would still apply, and the exemption is only being considered at this stage.
Some investment funds have rules that limit their ability to buy shares they cannot readily sell. Removing that restriction for qualifying transactions could bring more institutions into Canadian financings. More interested buyers might help companies negotiate better prices or complete deals that otherwise wouldn't happen. The final rules would determine whether those benefits are achievable.
The consultation raises four practical questions about how such an exemption could work.
Who could use it? The CSA wants feedback on which public companies and institutional investors should qualify. Setting the requirements too narrowly might exclude investors the exemption is intended to attract. Making them too broad could create new risks for investors and the market.
Would a registered dealer have to arrange the deal? Dealers can check eligibility, review information and help oversee a financing. That can protect investors and improve accountability. But dealers also charge fees, which matter when a company is raising a relatively small amount of capital. The CSA is asking whether mandatory dealer involvement strikes the right balance.
How would investors be protected? If newly issued shares can be sold immediately, regulators need to consider disclosure requirements, legal remedies and possible short selling arrangements. Investors buying shares in the public market shouldn't be left without important information. The legal protections available in a private placement can also differ from those in a public offering made through a prospectus.
Would the change bring in more money? Giving institutions another way to invest doesn't automatically mean they'll invest more. Companies still need attractive businesses, reasonable valuations and willing buyers.
Canada has already seen strong demand for more flexible financing rules. Following changes to the Listed Issuer Financing Exemption, hundreds of companies raised almost C$4 billion in the first year under the higher limits, roughly eight times the earlier pace. The increase doesn't necessarily prove the rule changes caused every financing, but it shows how extensively companies used the expanded exemption.
The proposed QIP exemption would work differently, focusing on institutional investors. Its value would depend on whether those investors bring additional capital and whether issuers can raise money on better terms. For smaller public companies, even a modest improvement in financing prices can mean issuing fewer shares and preserving more ownership. Companies and dealers with direct private placement experience can help regulators understand where the current restrictions make deals harder or more expensive.
The CSA wants feedback before deciding whether to change the rules. Companies and investors don't need to address every question. They can focus on the issues they know best and explain how the current requirements affect their decisions.
Founders and public company executives can share what they spend on reporting, audits and legal work. They can explain which filings take the most time, whether those costs influence where they list and how much money could be saved through simpler requirements. Real examples would help regulators separate necessary investor disclosures from work that adds limited value.
Investors and investment dealers can explain how resale restrictions affect private placements. That includes discounts investors seek, deals that are difficult to complete and cases where institutions cannot participate. They can also identify what information and safeguards they would need before accepting shares without a resale hold.
Accountants, securities lawyers and other advisers can explain which requirements create unnecessary work and where simpler rules might introduce new problems. Readers preparing their own comments can also review the industry submissions published by Quebec's Autorité des marchés financiers. These include responses from Fiore Management & Advisory Corp., SRI Capital Advisors and Canadian Independent Finance and Innovation Counsel. They offer examples of how other market participants are approaching the proposals.
Comments close November 13, 2026. Issuers, investors, dealers, advisers and other interested parties can submit feedback directly to the CSA using the online form or by uploading a PDF letter. Comments should focus on relevant consultation questions and include practical examples, financing costs or investor experience where possible. Submissions may be published. For technical help with the submission process, contact the CSA Secretariat at info@acvm-csa.ca.
Canada's public markets need to be affordable for smaller companies and attractive to investors. Reporting expenses can take money away from business growth, while private placement restrictions can affect financing prices and who is able to invest. The CSA's review is an opportunity to see which requirements still serve a useful purpose and which may be making capital harder or more expensive to obtain.
The proposed institutional financing exemption and review of venture issuer rules deserve particular attention. Both could help companies access capital or reduce costs, but the benefits will depend on how any changes are designed. Founders, investors, dealers and advisers have an opportunity to provide that practical evidence before the November 13 deadline. The goal is better access to capital while keeping the information and protections investors need to participate with confidence.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016