




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Crypto Policy | June 11, 2025
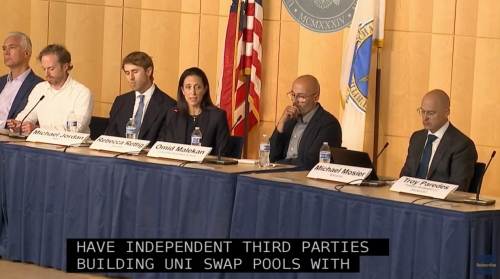
Image: June 9, 2025 DeFi Crypto Roundtable (Coindesk via youtube)
On June 9, the U.S. Securities and Exchange Commission (SEC) hosted another crypto task force roundtable series session called, "DeFi and the American Spirit", bringing together together regulators, legal experts, DeFi protocol developers, and investors to discuss how to the potential of regulating decentralized financial systems in ways that protects users without stifling innovation.
From the get-go, Chair Paul Atkins set the tone by opening the event by clearly stating that publishing code should not be treated as a crime:
“We will not regulate the act of writing open-source software. We do not prosecute the author of a hammer manual when someone misuses a hammer.”
The rest of the session built on this idea and focused on how the SEC can provide safe ways for DeFi projects to operate legally while still addressing investor risks.
In his remarks, Chair Atkins introduced the idea of a “conditional exemptive relief framework” which would allow DeFi innovators to build and launch on-chain products under limited conditions without triggering enforcement right away. This type of framework is similar to a regulatory sandbox that provides time-bound relief as long as participants meet specific safeguards.
“We are exploring a conditional exemptive relief framework that would allow experimentation under defined boundaries, similar to an innovation safe harbor.”
Commissioner Hester Peirce (aka Crypto mom) echoed this sentiment saying without a structured pathways to compliance, many innovators will either operate in legal uncertainty or offshore their projects out of the United States.
“Without a clear, conditional pathway, we are telling innovators you are on your own. That is not a message we want to send if we value the benefits of decentralized systems.”
In addition to the DeFi safe harbour, Chair Atkins also called upon his staff to modernize the current SEC rules to accommodate traditional issuers and intermediaries who want to use on-chain infrastructure.
This move shows that the SEC is looking to facilitate both new DeFi entrants and existing market players who are building tokenized products or using smart contracts to manage trading, issuance, or custody.
“I have asked the staff to consider whether amendments to the Commission’s rules and regulations would be better suited to provide needed accommodation for issuers and intermediaries who seek to administer on-chain financial systems.”
Atkins also discussed that on-chain systems can bring real benefits to the market, such as lower transaction costs, faster settlement, broader access, and the ability to create entirely new asset classes.
“I also am excited about the use of on-chain software systems by issuers and intermediaries to eliminate economic frictions, increase capital efficiency, enable new types of financial products, and enhance liquidity.”
It's clear support and endorsement of blockchain as a tool for economic growth, not just a solution for compliance challenges.
Several panelists, including Rebecca Rettig of Polygon Labs, warned that some of the most serious risks in DeFi happen off-chain. These include hidden liquidity deals, token allocations to insiders, or governance control partnerships.
“It is not always what is on-chain that creates the risk. It is often what is not disclosed, like side agreements, control over governance tokens, or preferential liquidity deals.”
Panelists argued that DeFi projects need better disclosure on how protocols are governed, how tokens are distributed, and whether any third parties receive special treatment or not.
Legal and industry experts said regulators should stop focusing on whether a token is a security and start regulating based on what the product or service actually does.
Angela Angelovska-Wilson of DLx Law said:
“We waste enormous energy litigating over whether X token is a security. The better path is regulating the activity, such as staking, custody, or lending, regardless of the label.”
Michael Jordan of the Digital Dollar Foundation agreed, saying:
“If we regulate the technology, someone will build around it. If we regulate the activity, we have a chance at real consumer protection.”
Important to understand the growing consensus that rules should distinguish between different types of financial behaviour even when the technology is similar.
Josh Garcia of Ketsal pointed out that some interfaces like custodial front ends that take custody of user funds or routes trades on behalf of users may require stricter oversight whereas protocols without admin control may require lighter regulation. Advocating for a layered regulatory approach that differentiates on function and control.
“A protocol with no privileged admin keys is not the same as a custodial front end that routes retail funds. The obligations differ, and so should the rules.”
After several Crypto Task force roundtable sessions, the SEC and participants are finally getting on the same page while focusing on conditional exemptions, regulatory modernization, and functional oversight. All together, it's a series effort to balance investor protection with lawful DeFi innovation. For fintech founders and digital asset platforms in Canada and globally, it's an important benchmark. If the U.S. begins providing clear compliance pathways and policy support for tokenized systems, then other jurisdictions will need to keep up or risk flight of builders and capital.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Launch & Financing | June 9, 2025
Image: Freepik
Toronto-based startup Rails has launched a new hybrid crypto exchange model after raising $14 million USD through a token warrant sale to institutional backers led by Kraken and other investors Slow Ventures, CMCC Global, Quantstamp, and Round13 Capital. The platform uses zero knowledge proofs to verify asset custody without revealing user balances and combines the benefits off off-chain trading speed with on-chain settlement transparency.
Rails' model separates the trade execution layer from asset custody. Orders are matched off-chain using a central limit order book, while asset settlement occurs on-chain using zk-proofs and Merkle tree-based attestations.
According to CoinDesk, the system is built on Kraken’s L2 scaling protocol, Ink, which enables Ethereum settlement with reduced costs. This approach blends traditional exchange performance with DeFi-style auditability.
Commenting to Decrypt, co-founder Satraj Bambra said:
“We wanted to fix two broken pieces in crypto exchanges—proof of reserves and instant access to funds. This infrastructure is designed to do that at scale.”
Since the collapse of QuadrigaCX in 2019 and other incidents like the global fallout from FTX in 2022, Canada's crypto markets have remained cautious with regulators tightening rules on custody, trading platforms, and investor protection.
Rails’ technical achievement and architecture directly addresses Canadian regulatory concerns by removing custodial opacity and verifying user funds in real time. Having said that, while the company is based and founded in Toronto, it chose to incorporate in the U.S. due to regulatory constraints at home in Canada.
In an interview with BetaKit, co-founder Satraj Bambra explained:
“Regulations are a choke point for innovation, and you have to find a good middle ground between good regulation and fostering innovation… You go where you’re welcome. [In Canada], we’ve lost that balance.”
While Rails hasn't explicitly said that it hopes Canadian regulators are open to reform, it's own product design of verifiable reserves, decentralized custody, and zero knowledge settlement is the type of infrastructure Canada’s crypto sector has increasingly called for. If domestic policy evolves, platforms like Rails could serve as an excellent blueprint.
Rails’ model could lower the compliance burden for Canadian platforms by building transparency into the technical architecture. From a venture and infrastructure perspective, the startup’s $14 million token warrant sale format is also notable.
It avoids traditional equity dilution while aligning investors with network usage and governance. For Canadian fintechs seeking capital, tokenized structures may see an uptick in interest, especially if paired with products gaining traction.
Time will tel if Rails can capture significant trading volume but the launch and funding furnishes it with momentum to continue reinventing crypto systems with transparency and composability from the ground up. Rails' crypto infrastructure innovation could boost other homegrown efforts, including regulators who may be watching and learning too.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Tech Ecosystem | June 6, 2025
Image: Freepik/travelscape
Web Summit Vancouver 2025 ran from May 27-30 2025 at the Vancouver Convention Centre attracting 15 727 attendees and with 1 108 startups from 117 countries, creating an electric atmosphere of discovery and deal making. Exhibiting startups spanned innovations in AI and machine learning, fintech and financial services, healthtech and wellness, and sustainability and cleantech.
Fintech solutions ranged from digital banking apps to blockchain payment rails, with Koho introducing a new international transfer service at the event. Founders pitched ideas, investors scouted opportunities, and conversations ranged from regulation to real-time fraud detection, confirming Canada’s growing role in global fintech innovation.
In the “Brands in Uncertain Times” session, Angus Reid of Angus Reid Group shared that nearly 50% of Canadians “vote at the cash register” by choosing brands aligned with their values. FCB Global CEO Tyler Turnbull added that Canadian consumers will pay 20-30% more for products produced and sourced in Canada, the premium on authenticity. For fintech companies, transparent fee structures and clear brand messaging are key to building consumer trust and loyalty.
AI dominated most panels, hallway discussions, and featured prominently across multiple stages. Sunny Madra, COO of Groq, announced Groq is now the exclusive inference provider for Bell Canada’s sovereign AI network, including two new data centres in British Columbia designed to bring AI processing closer to Canadian users. This new AI infrastructure will benefit fintech startups seeking access to low-latency, secure AI inference capabilities for real-time applications like fraud detection and compliance.
Sustainability and cleantech stood out alongside AI. Sessions highlighted how technology is driving environmental, social, and governance (ESG) goals, such as using AI to identify and price climate risks. Partners like OVHcloud showcased energy efficient cloud offerings, illustrating how infrastructure providers integrate ESG criteria into their services. For fintechs, embedding ESG considerations into product design and investment decisions is key for long term success. Not to mention the Competition Bureau's final rules on greenwashing that companies need to comply with.
4. Fintech Innovations and Cross-Border Payments
Financial technologies and services was one of the top represented verticals, with companies demoing solutions from digital banking apps and blockchain payment rails to regtech platforms. Toronto-based challenger bank Koho introduced its international money transfer service to over 190 countries, promising most transfers would arrive within 30 minutes during beta. By addressing opaque rates and slow settlement times, Koho’s launch shows how fintechs who listen to consumer issues can earn trust and turn these insights into new products/services that resonate with both Canadian and global markets.
5. Inclusive Entrepreneurship and Diverse Teams
44% of startups at Web Summit Vancouver were founded or co-founded by women. Beyond fintech, local firms such as Doubl, Revol Cares, and Aruna Revolution showcased solutions for women’s health and wellness.
Within financial services, fintech teams highlighted embedded credit services for underbanked populations and regtech platforms that serve diverse small-business owners. It's really diverse founding teams that drive not just inclusive entrepreneurship but solutions that resonate with underserved markets, strengthening innovation overall.
Technology is no longer judged only by what it can do, but by who it includes, what it protects, and how it earns trust. For fintechs and founders alike, this is the real edge of innovation and frontier.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
DeFi Policy | June 5, 2025
Image: Freepik/rawpixel.com
On June 9, the U.S. Securities and Exchange Commission is hosting a policy roundtable titled “DeFi and the American Spirit” to have an open and structured policy dialogue with decentralized finance developers, innovators, and legal experts alongside SEC legal and regulatory voices. The roundtable is part of the SEC's Crypto Task Force's ongoing series of crypto asset regulation events.
These gatherings are not 'hearings', nor are they 'policy announcements' but rather conversations with people who have actually built defi systems, in fact many who have publicly challenged the SEC's approach. It’s a live forum where ideas about risk, innovation, and policy design can be tested in real time. So in that way, it's a rare and important event for DeFi in the U.S. and fintechs watching from other jurisdictions like Canada.
The speaker lineup is a mix of founders, researchers, lawyers, and advocates who all have somewhat different views on how DeFi should work and be handled from a regulatory and practical perspective.
Erik Voorhees, founder of ShapeShift (and now Venice AI) is known for arguing that decentralized tools and open-source software should not be regulated like traditional financial intermediaries. His participation ensures that the case for user autonomy and protocol neutrality will be represented without compromise.
Michael Mosier, former acting director of FinCEN who founded Arktouros is focused on financial crime and compliance. He's likely to advocate for more robust frameworks for identifying illegal flows through permissionless systems. He'll ensure that AML and systemic risk questions are part of the core conversation.
Rebecca Rettig, general counsel at Jito Labs and formerly with Polygon, brings first-hand experience in understanding protocol development and legal structure, and is well positioned to bring up solutions that don’t rely on full centralization, such as voluntary disclosures or protocol guardrails.
Kevin Werbach, a professor at Wharton, has spent years studying how decentralized systems intersect with regulation. He tends to advocate for layered frameworks that separate software, governance, and commercial activity to provide a way to regulate outcomes without halting innovation.
There are several other panelists including Jill Gunter (Espresso Systems), Peter Van Valkenburgh (Coin Center), Omid Malekan (Columbia Business School), Gabe Shapiro (MetaLeX), and others who will no doubt have ample to contribute in helping the SEC understand as well as framing the policy of decentralized systems.
It’s a great cross-section of people trying to answer the same question from different angles: how should decentralized finance be understood and governed?
Here are some core questions that may come up during the discussions:
At the end of the day, the SEC should be commended for their willingness to engage with key foundational questions in effort to both understand at a deeper level, as well as inform future policy making. Leaps and bounds better than regulate by enforcement under the SEC's ex-Chair, Gary Gensler and a commission that would rather assume that every DeFi project is either a rug-pull or disguised as a securities platform.
If the roundtable opens the door to more flexible or fit-for-purpose regulation, Canadian regulators will face growing calls to follow suit. It also offers Canadian founders a window into how U.S. regulators are thinking, what they are worried about, what they may be willing to tolerate, and where they are open to compromise. It's clear proof that the SEC is finally recognizing that DeFi isn't going away and that series policy design needs inputs from the people building it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech IPO | June 5, 2025
June 5, 2025 will be on the record books as Circle's IPO, making history as the first stablecoin issuer to go public. Trading under the symbol CRCL, Circle’s shares opened at $69 and surged as high as $103.75 (235% above the IPO price of $31 that institutional investors access) before closing at $83.23.
The listing raised $1.1 billion, giving Circle a fully diluted market value of more than $22 billion. Lead underwriters included JPMorgan, Citigroup, and Goldman Sachs, with major investors including BlackRock and ARK Invest.
The scale and speed of Circle's pricing surge can only mean one thing; regulated crypto finance has arrived on Wall Street. This could be one of the most important public listings in the transformation and growth of digital finance and could open the door a steady stream of fintech IPOs who have been waiting for this very moment to arrive.
Circle reported $1.68 billion in revenue and $156 million in profit in 2024. Over 99% of that revenue came from interest earned on the reserves backing USDC, primarily in USD and short-term treasuries. According to Circle Internet Group's S1 filing, a 1% drop in interest rates could reduce annual revenue by $441 million.
Notably, Circle has begun monetizing blockchain services, subscription products, and network fees. These newer offerings brought in $20.7 million in Q1 2025 and are expected to scale.
Distribution costs remain a challenge however with Circle paying $1 billion in distribution fees in 2024, with the majority of that going to Coinbase. It's main stablecoin competitor, Tether, pays zero distribution fees.
USDC is the second largest stablecoin globally (27% market share). Circle’s IPO means that stablecoins are no longer niche tools for crypto trading but they are becoming key infrastructure for digital payments, cross-border flows, and mainstream financial innovation.
Circle has gone through some twists and turns in recent years, including cancelling a $9 billion SPAC deal in 2022, surviving the Silicon Valley Bank crisis in 2023, and rejecting a $4-5 billion acquisition offer from Ripple earlier this year (Coinbase also expressed interest). But Circle played their cards right and chose the full IPO route which created value of over 4 x those private offers. Circle's IPO also shows that the market rewards companies that take a regulated approach.
Circle’s public debut could jumpstart other fintech listings. Companies reportedly preparing IPOs include:
With Circle’s success, the IPO window appears to be opening again.
Circle’s IPO proves that regulated digital asset companies can scale and go public. It’s a reminder that Canada needs to ensure there's a clear framework for stablecoins. Without one, high-growth companies will continue to launch and grow within U.S. markets instead.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto | June 2 ,2025

Image: Freepik/bearfotos
On June 2, 2025, as reported by Coindesk, Sberbank, Russia’s largest and majority state-owned bank, quietly launched a structured bond tied to the performance of Bitcoin and the US dollar against the ruble. The bond is the first financial product of its kind in Russia to offer legal, state-backed exposure to cryptocurrency without requiring investors to hold or trade Bitcoin directly.
The bond is only accessible by qualified investors in Russia and is offered over the counter. It's designed to deliver returns (1) if Bitcoin rises in value, or (2) if the US dollar gains strength against the ruble. In doing so, investors can potentially receive higher yields than standard fixed income products within Russia's domestic financial system.
The bond is the first major financial product under new Bank of Russia rules that allow crypto-linked investments for qualified investors. For years Russia maintained a strict stance against cryptocurrencies, banning most forms of trading and prohibiting retail access to digital assets. Even after the rule change, everyday investors are not allowed to buy or sell digital assets through local exchanges or banks.
Will Sberbank's new bond change the landscape? Well it shows that Russia is willing to allow certain investors crypto exposure but only if it can fully control participation and on its own terms. Since the bond's settlement is in rubles and all transactions are managed/controlled by a government-backed institution, Russia can offer these types of investment options without stressing capital controls or monetary policy.
Sberbank also announced that it plans to list crypto-linked instruments on the Moscow Exchange. A Bitcoin futures product is expected to go live through its SberInvestments platform on June 4, 2025. These moves are all part of a broader push to establish legal, regulated channels for digital asset exposure inside the Russian economy.
As of today, there is no official data on the uptake or demand of the new bond issuance. Given that the product is new and restricted to accredited investors, detailed information may not be released until trading volumes develop. While the bond's dual exposure to Bitcoin price movements and to the USD/RUB forex rate, introduces volatility but institutional investors are looking for returns beyond traditional instruments, and the new bond option arrives at time when crypto adoption and exposure continues to grow globally.
Prior to now, most Russian investors looking for crypto exposure have relied on offshore accounts, informal P2P markets, or restricted access to foreign exchanges. All of these pathways come with geopolitical, legal and financial risks and challenges. Western sanctions, domestic regulations, and banking restrictions make cross-border crypto activity increasingly difficult.
Sberbank’s bond changes the equation. For the first time, investors can gain access to Bitcoin-based returns through a compliant, state backed product inside the Russian system. No private wallets are needed. No foreign currency leaves the country. The bond is fully backed by a government aligned financial institution and built to comply with Russian regulations. Sberbank’s bond may become a model for how other emerging markets experiment with digital assets while retaining full oversight and domestic control.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Regulation | June 2, 2025

AI Image, SEC says crypto staking not a security
On May 29, 2025, the U.S. Securities and Exchange Commission (SEC) published new guidance, "Statement on certain protocol staking activities". The Corporation Finance Division said that staking crypto assets on proof-of-stake networks does not count as offering or selling a security under federal law.
The SEC guidance says these 3 models do not involve the kind of for profit structure that securities law covers, which shows how the SEC is now approaching proof-of-stake blockchain systems in practice: (1) staking by individuals (solo staking), (2) delegating staking rights to a non-custodial third party, and (3) custodial staking done by platforms that hold assets on behalf of users.
The Division stated, “Protocol staking does not involve entrepreneurial or managerial efforts by third parties." Meaning it does not meet the Howey Test which the SEC uses to determine what counts as an investment contract (or not).
Two SEC commissioners published separate statements that highlight the ongoing debate inside the agency.
Commissioner Hester Peirce (Crypto mom) supports the new staking guidance, saying it was long overdue and provides clarity that developers and users have been asking for:
“Today’s statement is a step in the right direction. Market participants have long sought guidance on staking, and this statement, although overdue, provides helpful clarity.”
“Staking is not a financial investment in a business venture. It is a technical function essential to many blockchain networks.”
Commissioner Caroline Crenshaw raised concerns over the staking guidance, warning that it may weaken protections for retail users and was issued without a formal public process.
“This Staff statement attempts to draw lines in a complex and evolving ecosystem without the benefit of a Commission vote or notice and comment. That is not the kind of transparency or rigor that investors or market participants deserve.”
Crenshaw also said staking programs can still involve risk, especially when intermediaries are holding customer assets.
“Even assuming the best of intentions, staking programs can pose meaningful risks, especially when intermediaries custody or manage assets.”
Canadian regulators already have clear guidance on when staking may fall under securities law. According to CSA Staff Notice 81-336, the key trigger is custody. If a platform takes control of client crypto assets and stakes them on the client’s behalf, this may be considered a securities or derivatives activity and could require registration or compliance under existing rules.
However by contrast, individuals who stake their own crypto assets directly or delegate staking rights without giving up custody are generally not subject to regulation, as long as the activity does not involve other investment features or representations.
“Depending on how it is conducted, staking of crypto assets may involve the issuance of a security or derivative and/or may raise other investor protection concerns.”
The U.S. position is different becomes it frames protocol staking itself as a technical service (even when done by custodians), and not an investment contract. At the end of the day, U.S. firms will now face less friction when offering staking services, while Canadian platforms still operate under stricter conditions if custody is involved.
The question now is whether Canada will maintain this more cautious approach or align with emerging U.S. standards. If many firms start moving operations to the U.S. to take advantage of fewer barriers, then regulators may feel pressure to change.
Be aware that the guidance reflects the views of the SEC's Corporate Finance Division staff. It's not a new law or exempt from any activity from enforcement but it does offer helpful insight into current staff interpretations under existing U.S securities law (but it's not binding or the full Commission or court). It was raised that some common staking features like pooled assets, slashing protection, or enhanced reward mechanisms could till meet the criteria for an investment contract under Howey.
Further, the staff statement doesn't include liquid staking, restaking, or other models that add financial structuring, which is outside the scope of the guidance and could still raise regulatory concerns. See this A&O Shearman article for deeper analysis.
Staking is one of the core functions of proof-of-stake blockchains, including Ethereum. For developers and users, the ability to stake without regulatory risk is essential to network growth and security.
The SEC's staking guidance removes barriers, adds clarity, and will certainly give the market a boost. It will be interesting to see if staking adoption is slower here in Canada and if domestic platforms can compete or are overly restricted, due to the different approaches.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016