




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Global Fintech Report | Aug 22, 2025
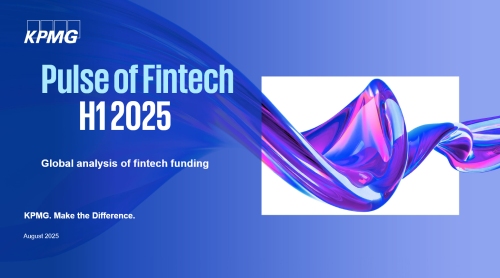
Image: Pulse of Fintech H1 2025, KPMG
According to the KPMG Pulse of Fintech H1 2025 report (67 page PDF) published in August 2025, global fintech investment in the first half of 2025 fell to $44.7 billion across 2,216 deals, recording the lowest H1 total since early 2020. Investors remain cautious about elevated risks around higher interest rates, capital costs, and geopolitical uncertainty. Q2 2025 was particularly weak, with $18.7 billion across 972 deals.
Investment in digital assets totalled $8.4 billion across 586 deals in H1 2025. Stablecoins attracted attention for payments and remittances in emerging markets, while tokenization platforms and infrastructure also captured capital. Circle's IPO anchored the sector’s strength, raising $1.1 billion with shares jumping 168% on day one.
AI continues to boost fintech investment. Capital flowed into both AI native startups and to incumbents embedding AI in credit scoring, fraud detection, and customer engagement. Investors prioritized business models that combined growth with efficiency and risk control. See NCFAs coverage of AI Fintechs attracting a 242% valuation premium
Regtech attracted $2.1 billion across 190 deals in H1 2025. Adoption of automated KYC, AML, and reporting tools continues to grow as financial institutions look for cost savings and regulatory agility. GenAI in risk and compliance
Insurtech raised $4.8 billion across 141 deals in H1 2025, which is already greater than all of 2024. Wealthtech funding reached $0.9 billion across 14 deals, with AI enabled platforms a recurring theme. Both sectors experienced consolidation as incumbents prefer acquisitions over building new capabilities.
Payments investment slowed to $4.6 billion across 242 deals in H1 2025, as investors grew more selective. But the sector is still foundational with capital being allocated to embedded finance, cross border platforms, and transaction monitoring. For Canada’s policy context see open banking delays and competitiveness and banks exiting merchant acquiring businesses like Moneris.
Cybersecurity specific fintech investment was just $0.1 billion across 26 deals in H1 2025. Despite heightened threat levels, most activity was concentrated at seed and early stages, reflecting investor caution toward scaling security focused fintechs.
Exit momentum is returning. Circle’s successful IPO may open the door for additional digital asset platforms to list in H2 2025, boosting the case for fintech exit activity after years of lack lustre listings.
For Canada, the data shows the window of opportunity for digital assets, AI, and regtech could attract investment with clear policy and infrastructure. The muted state of payments and open banking highlight gaps Canada must address to remain competitive. Clear rules, targeted support, and investment in digital infrastructure are critical to positioning Canadian fintech for growth in the second half of 2025 and beyond. See the crisis Canada and fintech cannot afford to waste
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Customer Loyalty Report | Aug 20, 2025

Image: Freepik
The 2025 CustomerGauge NPS & CX Benchmarks report (120 page PDF report) helps stakeholders measure customer loyalty across the financial services landscape. The industry average NPS stands at 44, while the banking subset is at 30. Fintechs by contrast are setting new standards with NPS scores ranging from 77 to 90.
Net Promoter Score (NPS) is a widely used measure of customer loyalty. It asks customers a simple question: How likely are you to recommend this company to a friend or colleague? Answers are scored on a scale from 0 to 10.
The final NPS is the percentage of Promoters minus the percentage of Detractors, giving a score that can range from –100 to +100. Higher scores reflect stronger customer advocacy and satisfaction.
The table data below is from the CustomerGauge 2025 report, sorted high to low. These figures clearly show fintechs leading customer loyalty followed by USAA and First Republic, while many popular banks fall significantly behind.
| Company | Type | NPS |
| SoFi | Fintech | 90 |
| OnDeck | Fintech | 84 |
| Affirm | Fintech | 83 |
| LendingClub | Fintech | 79 |
| Funding Circle | Fintech | 77 |
| USAA | Financial Institution | 75 |
| First Republic Bank | Bank | 72 |
| First Direct | Bank | 66 |
| ING Luxembourg | Bank | 63 |
| American Express Bank | Bank | 52 |
| Charles Schwab | Financial Institution | 52 |
| Royal Bank of Scotland | Bank | 51 |
| ABN AMRO | Financial Institution | 30 |
| JP Morgan Bank | Bank | 31 |
| Santander UK | Bank | 27 |
| Tesco Bank | Bank | 23 |
| Bank of America | Bank | 18 |
| CitiGroup | Bank | 18 |
| Morgan Stanley | Bank | 16 |
| ANZ | Bank | 15.4 |
| National Australia Bank (NAB) | Bank | 15.4 |
| PNC Bank | Bank | 15 |
| TSB Bank | Bank | 12 |
| CBA | Bank | 10.4 |
| HSBC | Bank | 7 |
| Goldman Sachs | Bank | 5 |
| Westpac | Bank | -6.9 |
To help compare and contrast 2025 CustomerGauge NPS figures, below is some regional data points for consideration:
Loyalty is still a competitive currency in financial services. With fintechs consistently outscoring banks by wide margins, Canadian incumbents in particular face mounting pressure to address gaps that stretch beyond digital convenience into trust, personalization, and value delivery.
Put differently, improving NPS is not simply about catching up to fintechs but about meeting a global standard that modern customers expect globally. For Canada, this means that raising customer loyalty scores is directly tied to future competitiveness, investor confidence, and the ability to scale innovation in an increasingly global financial marketplace.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Fintech Report | Aug 5, 2025
Image: Freepik
The latest Q3 2025 PitchBook report confirms an investment gap is being driven by a clear premium on automation and AI-enhanced infrastructure. PitchBook data shows that early stage AI-enabled fintechs are raising at a median pre-money valuation of $134 million. That is 242% higher than the $39.2 million median for non-AI peers. Startups with built-in AI capabilities have raised $3.5 billion across 171 venture deals so far this year, capturing 54.4% of total deal value. By comparison, non-AI fintech firms closed 195 deals but raised only $3 billion.
The largest gap is at the early stage. AI-enabled fintech startups are raising at a median pre-money valuation of $134 million, compared to $39.2 million for non-AI peers. That is a 242% premium, the highest of all stages in 2025. Only the pre-seed and seed levels showed a small dip but Pitchbook attributes to limited disclosures and early year sample effects.
At the venture growth stage, AI fintechs are closing deals with a median round size of $50 million, compared to $30 million for non-AI fintechs, a 66.7% premium.
Later stage AI fintechs are also attracting higher valuations. Their median pre-money valuation is $72.5 million, 6.7% higher than the $68 million median for non-AI companies.
Of all U.S. AI-enabled fintech companies, 80.3% are B2B. The most active segments are CFO stack (19.5%), wealthtech (18.4%), and financial services infrastructure (15%). These areas are drawing the largest funding rounds and investor attention.
In 2025, financial infrastructure AI firms raised $887.9 million, while non-AI peers in the same segment raised just $216 million. Ramp, Plaid, and Addepar each secured funding rounds of $200 million or more.
AI of course dominates the regtech sector with At the venture growth stage, AI fintechs are closing deals with a median round size of $50 million, compared to $30 million for non-AI fintechs, a 66.7% premium..
In 2025 to date AI fintechs are raising more money per round than their non-AI peers. The typical deal size for an AI fintech is $8.4 million, which is 7.7% higher than the $7.8 million median for non-AI companies. At the seed stage the gap is even wider. AI startups are raising $4.1 million per round, compared to $3.2 million for non-AI startups, a 28.5% premium.
These companies are not just raising more. They are also raising faster. The average time between funding rounds is 1.85 years for AI fintechs, slightly shorter than the 1.90 years it takes non-AI fintechs. The difference may seem small but it suggests that investors are more willing to write follow-up checks quickly when they see momentum and early results.
So far in 2025 exits for AI fintech companies remain limited. These companies have generated $10.6 billion in total exit value across 17 deals, but most of that came from one transaction. Chime’s IPO alone accounted for $9.1 billion. Without it, the remaining exits add up to just $1.5 billion, which is lower than the $2.3 billion recorded across 31 exit deals by non-AI fintech companies.
On the other hand, mergers and acquisitions (M&A) are gaining momentum. AI fintechs have completed $20.7 billion in M&A activity across 24 deals so far this year. That puts 2025 on pace to match 2024, which ended with $53.2 billion in total M&A deal value for AI companies. Buyers are looking to speed up their internal AI capabilities, improve their product offerings, compete with new startups, and build stronger decision-making systems powered by data.
AI is no longer optional for fintech companies that want to lead. Investors are rewarding AI first companies with faster funding, larger checks, and significantly higher valuations. These companies aren't just building automation tools but are quickly becoming the new infrastructure layer across enterprise finance, compliance, and infrastructure. It's pretty clear that founders who want to be globally competitive must build AI into the core of it's model, not the margins.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Global Standards | Aug 4, 2025
Image: Freepik
Canada chooses how it measures its economy but if it wants to be part of the global system, it needs to follow the updated rules. The System of National Accounts (SNA) is a global reporting framework developed and published jointly by the UN, IMF, OECD, World Bank, and European Commission to measure and compare economies across borders, including GDP, investment, and national wealth. Canada has followed it for decades, along with almost every other economy in the world, so we can expect change is coming.
Now, for the first time since 2008, the SNA has been updated. It gives countries the option to include intangible assets like AI systems, datasets, software, cloud infrastructure, and crypto in their official economic reporting. SNA 2025 is the new data reporting standard.
Statistics Canada currently uses SNA 2008 to compile GDP, capital formation, trade, and household income. Finance Canada and the Bank of Canada rely on that data to make major policy decisions. Because Canada aligns with the international system, it will be expected to transition to SNA 2025, and include a new measured view including intangibles, which NCFA has reported and advocated for the inclusion of intangibles for years. See this great report dating back 6 years ago now in 2019 called, " A New North Star: Canadian Competitiveness in an Intangibles Economy".
The new SNA 2025 includes formal categories for AI tools, machine learning models, digital platforms, tokenized assets, and data used in production. These can now be classified as fixed capital and included in investment statistics.
The framework also includes crypto assets such as Bitcoin in national wealth reporting. While countries are not required to adopt every element immediately, SNA 2025 sets the boundaries for what is allowed. If Canada continues using the SNA—and it will—these options are now on the table.
SNA 2025 does not show that digital or intangible assets are driving growth nor does not include statistics. What it does is give countries the structure to count what was previously invisible. Until now, if a Canadian fintech trained a large AI model, built infrastructure for a payments network, or developed a data engine for fraud detection, none of that was guaranteed to show up in national accounts. It was often treated as a cost, not an investment.
That matters because what gets counted drives policy.
When Statistics Canada does not report digital capital formation, Finance Canada cannot target it. When platform services are excluded from output figures, regulators and funders underestimate their value.
SNA 2025 also introduces new tools to reflect sustainability. It promotes the use of Net Domestic Product (NDP), which subtracts both depreciation and natural resource depletion from GDP. This is critical for a country like Canada, where growth often comes from extractive sectors. Using NDP can help the government better understand how much of that growth is truly lasting.
The new framework also supports clearer tracking of ESG finance, public sector innovation, and economic activity by multinationals that operate across borders. It aligns with global changes in how governments view risk, resilience, and value creation.
This is a global accounting and reporting change with deep consequences. SNA 2025, the updated global standard now recognizes intangibles, and so will the data that influences budgets, tax design, economic forecasts, and investment strategy. Canada is already committed to using the SNA, so the only question is how fully and how quickly we adopt the 2025 version.
NCFA urges Statistics Canada and federal decision makers to prioritize early implementation of the most relevant components of SNA 2025. These include digital capital assets, crypto asset recognition, and intangible production by fintech and AI firms.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech Report | July 30, 2025

Image: BCG QED Report Scaled Winners, Emerging Disruptors (Cover)
The latest analysis from BCG and QED Partners in a report titled, "Fintech's Next Chapter: Scaled Winners and Emerging Disruptors" (38 page PDF), shows that fintech companies currently capture just 3% of global banking and insurance revenues, leaving substantial room to grow.
The study frames this stage around two groups. The scaled winners are fewer than 100 companies generating more than $500 million in annual revenue. They account for most of the sector’s revenues and are now focused on profitability, compliance and expansion into adjacent services.
The emerging disruptors are thousands of smaller companies between $50 to $500 million in revenue. They are fast moving, often AI native, and are working in underserved markets and niches. Some of these emerging disruptors are well on their way to becoming the next generation of scaled winners.
In 2024, global fintech revenues increased 21% compared with 13% the previous year. Segments such as deposits grew 23%, trading and investment 21% and insurance 40%. This growth is happening while valuations and funding have recovered. In the first quarter of 2025, equity funding was 34% higher than a year earlier and valuations improved by 10%.
Earnings margins improved by 4% points to reach 16% in 2024. 69% of public fintechs are profitable, up from less than half the year before, and 35% now meet the rule of 40. Valuations are being driven by these fundamentals. Forward revenue growth and profitability explain half of the variation in valuations. Size and research and development spending explain another 39%.
Fintechs generate 3% of banking and insurance revenues. Penetration is as high as 14% in payments but under 1% in insurance, leaving a large gap for future growth. Payments still make up 55% of scaled fintech revenues (see image below), followed by challenger banks at 15%, crypto trading at 7% and buy now pay later at 4%.

Image: Distribution of Scaling fintechs 2024 BCG report 'Scaled Winners, Emerging Disruptors'
New AI models can act as autonomous agents that execute payments, preapprove loans, rebalance portfolios and anticipate risk exposures. Fintechs that are AI native receive 49% of all equity funding even though their seed rounds are smaller. Over the past three years, $32 billion has gone to B2B fintechs and $30 billion to financial infrastructure providers, with most of this capital flowing to AI powered models.
Large institutions are piloting tokenized bonds and funds. Tokenizing assets can remove up to $20 billion in intermediary costs every year, shorten settlement times and broaden access. Progress depends on clear regulatory frameworks and infrastructure ready for institutional standards.
After years of rapid expansion, challenger banks are focusing on core markets. 92 of them are now profitable and 24 generate more than $500 million in revenue. Geographic distribution of scaled fintech revenue remains uneven with 52% from the United States, 10% each from Asia Pacific excluding China and from Latin America, and 1% from the Middle East and Africa.
Fintech originated loans total $500 billion while private credit funds manage $1.7 trillion. There is a $280 billion gap in capital deployment, and partnerships between private credit funds and fintech lenders are set to grow quickly. Strong funding conditions in early 2025 support this trend.
B2B payments, treasury and workflow automation are still underdeveloped. Deposit related revenues grew 23% in 2024, ahead of the 21% industry growth rate. Insurtech fintechs grew by 40% over the same period, driven by distribution and brokerage models. These segments are becoming the growth engines for disruptors.
There are still 150 private fintechs founded before 2016 that have each raised more than $500 million and have not yet gone public, showing that investors are still ready to back scale-up stories.
The report highlights fintechs need to choose whether they are on a path to becoming a scaled winner or emerging disruptor. Canadian fintechs and NCFA members should prioritize sustainable growth in home markets before pursuing global expansion.
AI native products will be the key differentiator. Companies that engage early with regulators on AI and digital asset rules will be better positioned as these markets evolve. Partnerships with private credit funds can provide growth in lending. B2B automation and modernization of financial infrastructure are major opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Education | July 24, 2025
Image: Freepik/Rawpixel.com
AI is changing how we work, make decisions, and grow businesses. For fintech founders, investors, educators, and anyone building the future of finance, getting fluent in AI is no longer optional. It is essential. The OpenAI Academy has released a wide range of free courses designed for practical use across business, education, development, and policy.
These aren't just theoretical overviews. They are built for practical and real work, and they are available to everyone at no cost - that's right, completely free. So no excuses. It's time to dive in and level up.
This course is built for professionals who want to use AI to boost output without sacrificing quality. Learn how to use ChatGPT to write reports, summarize meetings, respond to clients, and simplify complex information. It is ideal for operations teams, consultants, and startup leaders. Start the ChatGPT at Work course. For those looking to go further and build a broader AI skill set beyond a single tool, Coursiv offers a comprehensive, practice-driven learning path covering ChatGPT and other leading AI platforms — with daily micro-lessons and accredited certificates designed to keep working professionals consistently ahead of the curve.
OpenAI’s flagship GPT‑4o model unlocks new ways to manage client communication, analyze data, and support decision making. This course walks through real-world use cases for financial modeling, customer insights, and executive brief writing. Access GPT‑4o for Business training
This short video shows you how to craft smarter prompts to get exactly what you need from ChatGPT. Learn how to set the right context, break down tasks, and refine your instructions. It is one of the most efficient ways to improve your results across every use case. Watch Mastering Prompt Engineering
Developers and builders can dive into real projects that show how to integrate OpenAI tools into their own products and workflows. This series covers how to structure API calls, generate content on demand, and troubleshoot common issues. Explore Developer Build Hours
Watch how ChatGPT can be used to conduct in-depth market and competitor research. This demonstration includes a hands-on walk-through of generating multi-source summaries, analyzing trends, and producing investor-ready output. Watch Deep Research in action
If you are building or supporting youth financial literacy programs, this educator-ready prompt pack is a great starting point. It includes templates and safe-use guidance for introducing AI to classrooms. Download K–12 Educator Prompt Pack
For job seekers and hiring teams, this session shows how to use ChatGPT to improve resumes, create personalized cover letters, and prepare for interviews. It is practical and quick to apply. Watch AI Career Prep video
OpenAI’s government prompt packs help public sector professionals generate reports, translate complex documents, and write clear communications. For NCFA members working with regulators or applying for funding, this is a valuable toolkit. Use Government prompt packs from OpenAI
Every resource above is open to the public and free to access. There are no paywalls, no subscriptions, and no certification upsells. These tools are meant to help people move faster, make better decisions, and reduce barriers to knowledge. For NCFA’s community, this is exactly the kind of education that drives national competitiveness and everyday inclusion.
This is more than learning how to more efficiently interact with AI. It is about unlocking new ways to build, connect, and compete. These free OpenAI courses give fintech entrepreneurs, investors, educators, and ecosystem leaders real tools they can use today to solve problems, reach new markets, and work smarter. For NCFA’s community, we can build a stronger and more inclusive future by helping more people access the power of AI. Here's a great opportunity to grow and thrive together - don't be left behind!
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Crime | July 16, 2025
Image: The State of Cross Chain Crime in 2025 (Elliptic Report Cover)
Just in, according to Elliptic’s State of Cross-Chain Crime 2025 report, illegal activity involving decentralized exchanges, bridges, and swap services reached $21.8 billion in 2025 so far, more than 3x the figure in 2023 ($7 billion) and 5x in 2022 ($4 billion). This trend highlights how criminals are exploiting DEXs, cross-chain bridges, and coin swap services to hide money transfers across multiple blockchains.
Elliptic reports that 33% of complex crypto crime investigations use more than 3 blockchains. Another 27% involve over 5 blockchains, while 20% span more than 10. Chain-hopping is a technique that allows criminals, both big and small, to move assets quickly from one chain to another to confuse investigators.
In one confirmed case, a North Korean related wallet moved stolen funds through Bitcoin, Ethereum, Arbitrum, Base, and Tron, all in succession with that single operation using a total of 48 coordinated swaps.
Coin swap platforms have become a preferred laundering tool for ransomware groups, darknet markets, and offshore gambling operations. Unlike DEXs or bridges, these services are centralized, often use privacy-focused Telegram chat service, and allow anonymous swaps between chains with no KYC.
Some operate in regions under sanctions, including Crimea. Elliptic also confirmed that North Korean hackers laundered $200 million of the $1.46 billion Bybit theft through a service called eXch. The platform refused to cooperate with law enforcement and was later shut down by German and Dutch authorities.
Many of the methods used by criminals involve a mix of asset swaps, bridges, gas fee financing, and privacy coins. Elliptic's report confirms that over 300 bridge combinations are being traced automatically using virtual value transfer events (VVTEs), a forensic analytics method developed by Elliptic to automatically trace the source and destination of cross-chain transactions, especially those that pass through bridges.
This automation is a lifeline to investigations and allows regulators, compliance teams, and law enforcement to trace cross-chain fund flows in seconds instead of hours. Elliptic now supports more than 50 blockchains, making it one of the most comprehensive tools available for risk detection.
The scale and speed of illicit activity are outpacing traditional compliance methods. Without updated tools and policies, Canadian fintechs and financial institutions face rising legal, reputational, and regulatory risk. It feels like we've been saying this for a while now, but the use of advanced tracking, wallet screening, and automated compliance solutions are no longer optional, and in fact essential for protecting the integrity of Canada's growing digital finance sector.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016