




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Crypto | April 28, 2025

Image: Freepik/pikisuperstar
Never a dull moment. Last week, Trump announced a special dinner with the President for the top 220 token holders (see gamified leaderboard) of his $TRUMP meme coin. The event is scheduled to take place May 22, 2025 at the at Trump National Golf Club near Washington, D.C.
Following the news the token surged more than 50% in value, however the presidential self-promotion has triggered more ethical concerns including calls for impeachment by U.S. Democratic Senator Jon Ossoff who warns that selling access to a sitting president via a crypto contest could constitute 'an impeachable offense'.
Historically, political donations are highly regulated with disclosure rules, donation caps, and transparency requirements but Trump's meme coin crypto model offers anyone who buys his $TRUMP token and holds it during the contest (no political donation required), can get access to a sitting president without any sort of formal tracking or financial reporting.
The Federal Election Commission regulates official campaign fundraising but crypto tokens tied to personal brands or unofficial committees fall outside of their oversight.
The contest fuelled interpretation rumours that a minimum of $300,000 would be required to get on the list, however Trump's meme coin social team clarified on x.com that anyone could join the dinner if they are one of the top 220 token holders. As of April 28, the 220th on the leaderboard is holding about 898 tokens or a value of approx 13k USD. Participants in the contest must register their rankings which are based on time weighted holdings for the duration of the contest period.
The $TRUMP team also clarified that insider held tokens will remain locked for an additional 90 days to avoid concerns of a rug pull where early holders dump tokens after promotional events.
Offering personal access to a sitting president in exchange to boost their personal token value has alarmed lawmakers. As reported by Decrypto, Senator Elizabeth Warren and Representative Adam Schiff have called for a federal ethics investigation. Senator Jon Ossoff went further, suggesting that the arrangement could justify impeachment if it is found that Trump broke the rules of how public officials and sitting presidents are supposed to behave.
President Trump is sidestepping rules of how politicians are meant to act, and at the same time, cryptocurrencies are enabling politicians to raise money directly with fewer rules.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
AI Licensing | April 24, 2025
Image: Freepik
As reported by the Guardian, the Copyright Licensing Agency (CLA), a collaboration between the Authors' Licensing and Collecting Society (ALCS) and Publishers' Licensing Services, is currently developing a licensing model to launch in Q3 2025 to ensure authors get paid when their books, articles, and other creative assets are used to train generative artificial intelligence (GenAI) models. The CLA's goal is to provide a legal framework that will allow AI developers to access copyrighted content while ensuring that authors and publishers receive fair compensation.
For fintechs, digital content platforms, writers creatives, and key stakeholders, this move signals a step towards regulated, rights-based access to data. A test case for how governments and publishers globally may seek to regulate AI development with existing copyright frameworks. As AI adoption grows so will the hunger for data and the need to resolve the conflict between innovation and copyright law.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
DeFi | April 24, 2025
Image: Freepik/fullvector
In April 2025, the Bank for International Settlements (BIS) published a new report called 'Cryptocurrencies and decentralised finance: functions and financial stability implications' that could impact how regulators approach decentralized finance (DeFi). For the first time, the BIS explores the idea that smart contracts could help enforce certain regulatory rules within the code itself. To be clear, the BIS doesn't say that smart contract algorithms will replace oversight but it suggests that certain protections like disclosure requirements or prohibiting (or limiting) risk transactions could be built directly into the code.
At the same time, the BIS makes it clear that code alone is not enough. Behind every protocol is a developer, a team, or a group of people in-real-life (IRL) that makes decisions when designing or maintaining the system. These people often manage access, risk settings and upgrades. The BIS is saying that if DeFi is going to be safe and trusted then regulators must consider both the smart contract system and the people who develop and influence it.
Self-executing smart contracts are at the heart of DeFi. They allow users to lend, borrow, trade, and stake assets without relying on intermediaries like a centralized financial institution. Once a smart contract is deployed to the blockchain, it executes transactions exactly as coded, without exceptions. This fact makes them potentially powerful tools for embedding and enforcing basic safeguards to protect stakeholders that interact with these contracts like investors.
The BIS seems to support this concept (BIS Paper No. 156, page 22):
“Regulation could then be embedded in smart contracts to make sure that rules were met. Examples… include ensuring that smart contracts were executed in line with the status of the ledger, that the disclosure of information took place or that ‘best execution’ requirements have been met.”
What this means is that if a smart contract fails to meet a preset condition, such as price fairness or a collateral threshold requirement, it could automatically trigger a manual review. This would reduce the need for full manual checks on all transactions, and the smart contracts could require public disclosures are met before transactions were allowed. These types of technical safeguards would run automatically and help reduce fraud, bias, or delay. But the BIS says, automation has limits.
The BIS highlights that smart contracts do not govern themselves. That is, behind every DeFi protocol is a group of developers (tech/business/legal/investor or otherwise) that decides how the code will work, who can update it, and affect the direction it takes.
BIS quotes on Page 21:
“It would be useful to analyse the entities (and persons) exerting de facto control of a DeFi protocol…”
In many DeFi systems, the people involved are often anonymous or semi-anonymous, yet they can often have administrative access or governance power. Given the high stakes in such a financial system, it raises serious questions about accountability. Who is on the hook when problems arise?
Canada has a strong, innovative, and growing DeFi community with many projects being launched and experimented with. These project teams often create complex and secure smart contracts but may lack a clear acc0untability structure so users can face real risks. The BIS's report outlines two layers of protection related to governance.
1. The first is technical. Smart contracts could/should enforce baseline rules around transparency, fairness, and market integrity, without human intervention.
2. The second is organizational. Developers and governance teams must be identifiable, transparent, and where appropriate, regulated. That could mean setting minimum standards, requiring disclosures, or creating a new legal category for protocol operators.
The HM Treasury in the United Kingdom released a paper in February 2023 titled "Future financial services regulatory regime for cryptoassets" that discusses various options for bringing DeFi activities into the regulatory perimeter - section 11.6:
"One option for regulating DeFi is to define a set of DeFi-specific activities – e.g. 'establishing or operating a protocol' – as regulated activities under the RAO (or DAR). The persons carrying out those activities would then require authorisation, and the FCA could design a bespoke regime around these regulated activities."
The BIS report covers a range of updated views on cryptocurrency topics, as adoption continues to grow globally. The BIS is looking for a path that DeFi can grow (not advocating to centralize or shut it down) but with guardrails to protect users and the financial system. Smarter regulation is where 'code and community' can collaborate with a novel system pushing boundaries.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Investor Research | April 23, 2025
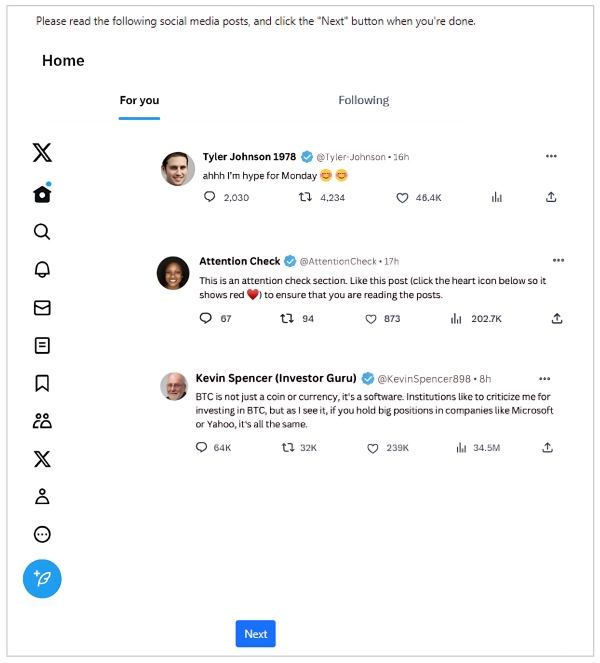
Image from OSC Retail Investor and Social Media Study Interface
The story goes something like this... Maya wasn't looking for investment advice when she jumped on her phone and started scrolling through short videos when one caught her attention. A young finfluencer explained how he built a portfolio by investing a small amount each week. He showed screenshots, made it sound simple, and wrapped the message in personal success. It felt real and by the end of the clip Maya was thinking about following his exact steps. What she didn't realize was how many others were doing the same, by trusting only a short video.
Social media platforms have become a significant source of financial information for Canadians. According to the 2024 Canadian Securities Administrators (CSA) Investor Index, 53% of investors use social media for investment information (up 18% since 2020). Not surprisingly, among young investors aged 18 to 24, the figure rises to 82%. And to zoom in even further, 46% of investors report encountering investment opportunities on social media (up 17% from 2020).
On April 22, 2025, the Ontario Securities Commission (OSC) revealed their latest retail investor research, 'Social Media and Retail Investing: The Rise of Finfluencers' in collaboration with The Decision Lab. This post is data-driven look at how trust can turn into risk, and what the OSC likely plans to do about it.
The OSC surveyed 655 Canadian retail investors and found:
And those who acted on finfluencer advice, the following behaviours increased significantly:
The survey results suggest that a growing number of retail investors are relying on social media for online financial advisor, and based on their trust of finfluencers, investment advice found on social media often replaces traditional financial guidance which can lead to increased exposure to risk, especially among younger investors who are online frequently.
To better understand how social media and finfluencer content affects financial decisions, the Ontario Securities Commission ran an online study with 1,465 Canadians who use social media. Each person was randomly placed into different groups to see how different types of posts might influence what they would choose to buy in a simulated investment setting. Participants managed a simulated $10,000 portfolio and were exposed to promotional finance content modelled after real social media posts. Here's the rub:
These above results confirmed that exposure to financial content on social media can significantly impact investment decisions, especially among those with less experience.
The OSC ran tests to look at which behavioural interventions could be used to reduce the influence of influencer content including:
The results found that all of the above methods helped reduce the number of participants who purchased the promoted assets but none completely eliminated the influence of the original content.
The OSC's report suggests that the regulator supports continuation of regulatory oversight and targeted interventions to protect retail investors from finfluencer content, especially since social media is now integral to the distribution and/or access of financial advisor. In addition to the various Canadian regulatory guidelines below, the report confirms that authorities should consider additional measures to address these concerns that are now backed by evidence.
While some finfluencers provide valuable insights for investors, others can provide misleading or harmful advice. The OSC's findings are a cause for concern for regulators who are evaluating further oversight measures to protect retail investors from the potential risks associated with unregulated financial advice on social media platforms (or by finfluencers). Learn more about the OSC's study about the Rise of Finfluencers and Social Media and Retail investing.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Markets and Economy | April 15, 2025

Image: Jamie Dimon, Chairman and CEO, JP Morgan Chase
On April 7 2025, CEO Jamie Dimon of JPMorgan Chase published his annual 2024 letter to shareholders (58 page PDF), which is widely read by business and policy leaders around the globe. This year's edition, his messages are especially urgent. He describes a world of rising risks, and big decisions ahead with profound implications that stretch beyond simply Wall Street. Below are 5 insights that fintech founders, investors and Canadian decision makers need to know:
“History has shown that as countries become weaker, their currency loses reserve currency status.”
Dimon issued a clear warning that's rarely said out loud by execs of America’s biggest banks. That is the U.S. dollar’s global dominance is fading because it's strength relies on TRUST in U.S. institutions, alliances, and policy, BUT that trust is now eroding.
Last week, the U.S. dollar dropped significantly reaching a 3 year low against major global currencies. The decline is largely due to the Trump administration's escalating tariffs and trade tensions on imports from several countries, such as China, Canada and European nations. Tariffs led to increased market volatility, shaking investor confidence in American economic policies.
The WSJ published a report with the former Treasury Secretary, Janet Yellen, saying that investors "seem to be shunning dollar assets". Previously, for the past several decades, investors flocked to buy U.S. dollars during times of volatility and economic uncertainty because it was considered stable and safe.
American risks or lack of trust in its institutions is now prompting countries like Germany who hold 1200 tonne of their US gold reserve on American soil, to verify the existence of their gold and begin repatriating it back to Germany in case assets are suddenly frozen or risks spiral out of control. And they aren't the only country with concerns.
For Canada, this might open a window. If global capital starts looking for stable alternatives, Canadian institutions can position themselves as reliable partners. Our political stability and sound financial regulations are competitive assets. This is a moment to invest in confidence including the platforms and tools fintechs are building.
Dimon spells out just how much the U.S. benefits from being the world’s reserve currency:
“Being the reserve currency saves the United States $100 billion a year at current interest rates... People around the world actually carry approximately $2.5 trillion of paper U.S. dollars, which, in effect, is borrowing without paying interest.”
However, the U.S. being the global reserve currency isn't sustainable without continued global trust. For financial technology firms offering multi-currency accounts, global payments, and crypto on-ramps, this new reality is an opportunity.
If the dollar loses its unique place in the global system, financial firms will need to design for a world where volatility is the norm. That could mean hedging tools, stablecoins backed by liquid and diversified reserves, and tokenization of various assets could see a boost akin to gold, or a digital version of it.
“The U.S. deficit remains very large at just below $2 trillion, or 6.6% of GDP,” and warns that the “debt-to-GDP ratio is already over 100%.”
The U.S. government has borrowed nearly $11 trillion since the pandemic. The total U.S. federal debt is more than $34 trillion, which is greater than 100% of GDP. He says this is a structural issue and that America's fiscal path is on unstable footing. When debt continues to rise with no end in sight, global confidence wavers.
While in a different situation, Canada is under economic pressure from Trump's tariffs and trade war, persistent decline in productivity, and lower growth and foreign direct investment compared to many of its peer countries. It must restructure its own policies to support a fiscal agenda that supports innovation, digital infrastructure, supply chain and trading partner diversification, interprovincial trade, and green transitions that put Canada on a new path of economic growth. Canada can offer to the world what the U.S.'s current administration is turning, it's back against, a well managed democracy, and a country with ample resources (including human capital) that's serious about the future.
One of Dimon’s strongest warnings is about fragmentation.
“Economic fragmentation from our allies may be disastrous in the long run… Keeping our alliances together, both militarily and economically, is essential.”
He’s not just just talking about political division but economic ones, such as trade wars, competing currencies and trading blocs, and digital standards that no longer align with alliances that underpin and support U.S. markets in the way they do today. A world where economic cooperation breaks down and different countries build their own separate systems for money, trade, and technology - leading to incompatible digital standard and higher costs while opening the door for bad actors to take advantage of new weak links in the system. It could also encourage allies to rally around a new financial power for stability.
For fintechs and Canada, it's a risk and opportunity. It means building our own rails, compliance protocols, and digital ID systems that work across borders. The more neutral, resilient, and standardized Canada's digital infrastructure becomes, the more relevant it is globally.
In his letter to shareholders, Dimon shares lessons from decades of experience fro leading through crisis, transformation, and growth.
1. He warns that innovation can be smothered by too much money, too little clarity, or endless process. For startups, that’s a reminder to stay scrappy and experimental.
“You can kill innovation with too many resources, too few resources or bureaucracy… Evaluate innovative ideas through testing and learning rather than rote analysis.”
2. He also challenges the usual advice about delegation for mission-critical areas like cybersecurity, talent, or trust, and says leaders should get into the details.
“I changed my mind. I’m going to micromanage this one… In my entire career, I’ve rarely seen this kind of outsourcing of responsibility succeed.”
3. Don’t hide behind weak benchmarks.
4. Don’t sit through bad meetings, but "if a meeting is required, make it count… I ALWAYS do the pre-read… This has to stop: people checking notifications, texting, reading email. It’s disrespectful. It wastes time.”
5. In uncertain times, discipline is more powerful than vision alone.
The status quo is no longer. As geopolitical and economic risks take over, it's more pressing than ever for Canada to grow trust, build bridges, and invest in innovation with a strong economic growth mandate. Canada's fintech and financial ecosystem, can still thrive in a fragmenting world. We can't outspend superpowers but we can out think them.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Leadership | April 14, 2025

Image: Freepik/rawpixel.com
In an economic climate where geopolitical tensions are high and markets volatile with inflation spikes and policy u-turns, founders and innovators that embrace uncertainty can gain an edge. Uncertainty isn't a side effect of innovation, it's the starting line. Inspired from Deepak Chopra's recent article on the power of uncertainty, this article looks at the impact of embracing the unknown and how it can sharpen decision-making, unlock creativity, and help build resilience during times of rapid change and uncertainty.
Chopra argues that trying to eliminate uncertainty kills creativity. When everything is 'the exact same', it breeds complacency. We've all experienced this. During some routine periods, a founder may feel that time is passing by very quickly. Yet during times of great change, novelty, innovation, a founder may feel that time is going by slowly. Fintech leaders who stay agile during times of ambiguity can separate themselves from those who stall in the face of uncertainty. Put differently, successful founders don't just survive during chaos, they scan for signals of change/chaos that others can miss, often giving them an edge.
Just after the global financial crisis in 2008, Toronto-based Wave Financial launched in 2009. CEO Kirk Simpson saw that most traditional accounting software providers were offering tighter pricing and focused on enterprise clients to survive. Wave took a different approach and offered free tools to small to medium sized businesses (SMEs) and freelancers, and turned the crisis into a launch and growth opportunity. Wave was later acquired by H&R Block for $537 million.
Lesson: Fintech leaders who understand that uncertainty can unlock radical innovation, can give them an advantage over legacy players who retreat during times of constraints and volatility.
Chopra describes daily constraints as a 'reducing value' that narrows perception and thus creativity, and by way of extension innovation and opportunity. This includes your daily habits and fixed beliefs. It's the caution, fear, and routine that limits all kinds of experiences. Breakthroughs rarely occur when ones perception is full of constraints and limited. If one provides the same inputs, they can expect the same outputs. Fintech founders and leaders can expect breakthroughs to occur where certainty ends.
Actionable takeaway: Host an 'uncertainty sprint'! Bring your team together with a single question and use it to generate unexpected solutions and test and iterate the thinking. "What if our biggest unknown became our biggest asset?
It's easy to get lost in obsessing over the future - what's our forecast, future funding rounds or policy changes as examples. Chopra however reminds us that the only time you can take action is now. A strategy that is grounded in the present can lead to smarter execution.
Example: As digital financial services adoption continue to grow, incumbent banks are closing more and more physical branches, especially in rural and underserved areas during a cost-of-living crisis. In 2024, Canadian fintech Koho partnered with Canada Post to begin implementing a modern version of postal banking, which would provide basic digital banking services using Koho's financial infrastructure while making it available through Canada Post's national network. Together they reimagined a legacy system as a tool for financial inclusion while others were fixated on what's broken. By staying level headed and grounded in the present, Koho and Canada Post rediscovered what was already working today, and then transformed it.
For those that aren't used to uncertainty, it can create severe mental fatigue. Founders are required to juggle a ton of demands from compliance and culture to capital and product development and distribution.
Founders should work to train their minds like athletes train their muscles to increase their mental resilience. Here are a few proven mental training exercises to try:
Mental fitness training should be done daily and not just during periods of heightened stress. Your companies resilience begins with you and your team's mental capacity.
Chopra’s insights position chaos as a powerful stage at the edge of creativity, clarity, and courage. Fintech founders and C-suites who embrace uncertainty as a condition of insight and opportunity, and not just risk, will be the ones thriving in the future.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Funding | April 10, 2025

Image: Freepik/rawpixel.com
Regulation Crowdfunding (RegCF) has proven to be a resilient market for early stage entrepreneurs and investors alike. When uncertainty strikes, it's often traditional venture capital that pulls back, while the community-driven model continues to offer early stage start-ups access to capital allowing them to innovate. However, just in from Sherwood (Woodie) Neiss, NCFA Advisor and Principal at Crowdfund Capital Advisors, data shows that tariffs are starting to strain RegCF markets - from March 10 to April 9, 2025:
Sherwood Neiss, Principal at Crowdfund Capital Advisors:
“We’re seeing the first real signs of pullback in what has otherwise been a resilient funding ecosystem. The numbers tell a story not of panic, but of pause. Investors and issuers alike are waiting for clarity—on costs, on policy, and on risk.”
In a volatile environment where U.S. tariffs are levied one day, and then paused the next, founders must now face new due diligence questions about supply chains, production costs, and their ability to manage sourcing.

Image: Drop in Issuer Sentiment March 10 April 9, 2025 (Crowdfund Capital Advisors)
These aren't just theoretical risks because many start-ups, particular in hardware devices, consumer goods, and any sector relying on international parts and components are now exposed to volatility and surcharge taxes. Investor confidence is taking a major hit too, and early stage businesses run the risk of stalling or failing before they can scale.
“Tariffs may help some sectors, but they’re also putting early-stage companies under pressure at the exact moment they need capital the most. Many startups don’t yet have the scale to absorb these shocks. And without sufficient investor support, we risk losing not just companies, but jobs and innovation.”
The adverse impact that tariffs have on innovators is especially acute in underserved and rural markets. These regions rely on RegCF since institutional capital remains scare. Retail investors are pulling back their investment participation in RegCF campaigns because of inflationary pressures and wage and job concerns.
Although digital native startups, such as software companies with lower capital requirements and no physical supply chains are more resilient in the current environment, the overall market uncertainty that tariffs have made investors more selective while pushing out campaign timelines.
Without policy intervention or more clarity, the negative implications of tariffs on RegCF markets may be severe, with fewer companies launched, fewer jobs, and reduced momentum for tech and manufacturing innovation across North America.
“This is a moment for policymakers, platforms, and investors to pay attention. We don’t need alarm, we need alignment. Investment Crowdfunding has been a powerful tool for democratizing capital. But it can’t thrive in a vacuum of uncertainty.”
Public markets react quickly to interest rates or geopolitical shocks but RegCF is slower and more telling, as it signals what's happening on the ground.
Tariffs are elevating uncertainty risks related to cost structures, and its hurting investor sentiment. When early stage capital pulls back at grass roots levels, it hurts the innovation economy and the real cost is future growth.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016