




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 12, 2026 | NCFA Fintech Market Activity | Digital Assets And Payments Compliance
Image: Freepik/rawpixel.com
On Mar 11 2026, Hong Kong based stablecoin payments firm RedotPay outlined regulatory progress across Canada, the United States, and Argentina as it builds the registrations required to operate in more regulated markets.
The company holds Money Services Business registration with FinCEN in the United States and registration with FINTRAC in Canada (jurisdiction of incorporation is the province of BC), and is pursuing Virtual Asset Service Provider registration in Argentina. These steps allow the firm to work with regulated partners as it expands its stablecoin payment platform.
RedotPay offers a wallet and card based payment system built around stablecoins, allowing users to send digital assets while recipients receive local currency. The company says its platform now serves more than six million users across over 100 countries and processes roughly $10 billion in annualized payment volume.
Stablecoin payment platforms often present themselves as borderless financial infrastructure. In practice, access still depends on local regulatory registration. Firms must establish compliance credentials before banks, card networks, payment processors, and institutional partners will work with them.
In Canada, FINTRAC registration places RedotPay inside Canada's anti money laundering supervision framework. For digital asset payment companies, that registration is typically the first threshold for operating credibly and building domestic partnerships.
Other rules may also apply depending on the product model, including the Bank of Canada’s Retail Payment Activities Act (RPAA) for payment service providers and provincial securities oversight for certain digital asset activities.
Competition in crypto payments is moving away from unique app features alone and toward regulated distribution. Firms that secure registrations across multiple jurisdictions gain earlier access to payment rails, banking relationships, and local partner networks. Firms that delay those steps often remain limited even if their technology works.
It's a dynamic that's becoming more visible as stablecoin payment platforms grow. Compliance infrastructure is no longer just a back office function. It increasingly determines which firms can expand internationally and which ones stall when regulatory scrutiny increases.
As stablecoin payment firms expand globally, will long term advantage come from product features or from who can secure regulated market access first?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
March 11 2026 | NCFA Feature | AI And Commerce

On March 5 2026, a report that OpenAI is scaling back end-to-end ChatGPT shopping plans could be a turning point in the widely watched Agentic Commerce sector. OpenAI had already pushed into retail online buying with ChatGPT shopping research and product recommendation tools designed to help users evaluate items inside a conversation. It could be that OpenAI is stepping back from running the full transaction, including instant checkout, to focus on where the real leverage is in digital commerce.
The early lesson from AI shopping is straightforward. The platform that captures the buying decision before checkout holds more power than the platform that processes the final payment. When an AI assistant receives and interprets the request, compares options, and produces the shortlist, it influences which merchants receive traffic and which products buyers even see.
The opportunity exists because conversational AI already operates at massive scale. OpenAI reports 900 million weekly ChatGPT users, giving the company a distribution graph that rivals the largest consumer internet platforms. Its online help also confirms that ChatGPT product recommendation results can present product images, descriptions, and links to merchant purchase pages.
A user no longer needs to open multiple product pages to compare items. The assistant interprets the request, analyzes specifications and reviews, and produces a shortlist instantly. Once a shortlist is compiled, the system that produced it holds influence over where the buyer goes next.
Marketplaces are responding quickly because they recognize the same risk. Amazon continues embedding AI deeper into its commerce stack to keep discovery inside the platform. NCFA coverage of Amazon Launches Always On Agentic AI for Sellers shows how the company now deploys AI tools that assist merchants with pricing decisions, product listings, and marketplace optimization.
Amazon is also testing new ways to extend its reach beyond its own catalog. In a recent update, the company says Shop Direct and Buy for Me purchasing options allows customers either to buy through an external merchant store or allow Amazon to complete eligible purchases on the buyer’s behalf.
Both approaches keep Amazon positioned at the gateway of the transaction. It's important because marketplaces still hold advantages in logistics, reviews, merchant density, and trusted payment infrastructure.
Google and Shopify are advancing a different strategy that focuses on open access to merchant data. Google recently introduced agentic commerce protocols designed to connect retailers directly to AI assistants.
Google's Shopping Graph now contains 50 billion product listings updated roughly 2 billion times each hour. That dataset gives AI systems real time access to pricing and inventory information across the web.
Shopify brings merchant scale to the same conversation. The company reports $1.4 trillion in cumulative commerce volume processed through its platform. By exposing merchant catalog data to AI systems, Shopify positions its merchants to reach customers through multiple conversational interfaces rather than relying exclusively on one marketplace.
If these open commerce approaches gain traction, merchants gain more flexibility. If closed platforms dominate discovery, a small number of technology companies could gain stronger influence over product ranking and customer access.
Payments companies also recognize the stakes. When AI assistants guide purchase decisions, the payment options integrated into those flows become strategically important. NCFA coverage of PayPal and OpenAI Partner On ChatGPT Instant Checkout shows how payment providers are already moving closer to conversational commerce infrastructure.
If AI assistants direct the user from recommendation to purchase, the wallet displayed first, the financing option offered in context, and the payment provider integrated into the conversation all influence where transaction revenue flows.
For fintech firms, integrate early into AI driven buying journeys or remain dependent on traditional checkout pages.
Commercial ad pressure typically follows intent. When a platform captures product discovery, merchants eventually compete for visibility. OpenAI Tests Ads Inside ChatGPT Free Tiers shows early experimentation with commercial placement inside conversational AI experiences.
Search engines generate billions in revenue from sponsored product listings. Marketplaces generate similar revenue through promoted items and advertising placements. AI assistants that guide buying decisions may eventually support similar models.
Whether that monetization happens through sponsored results, affiliate partnerships, or merchant integrations is still unclear, but the incentive structure is already visible.
OpenAI's reported pullback from full in-chat checkout doesn't weaken the case for AI driven commerce. It clarifies though where the first competitive advantage may emerge. Platforms that capture the buying conversation can route traffic toward marketplaces, merchants, and payment providers without owning the full transaction.
The infrastructure and scale is in place which explains why competition is intensifying. Hundreds of millions of users now ask AI systems for advice before making decisions. Retail databases contain tens of billions of products. Merchant platforms process trillions in commerce. Talking Point: The next evolution of digital commerce will depend less on checkout pages and more on which system people trust when they ask what to buy.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 11, 2026 | NCFA Fintech Market Insight | Policy And Regulation And Market Entry

On Feb 26 2026, OSFI announced targeted fast track approvals framework for new applicants seeking to become federally regulated financial institutions. OSFI says the framework will launch in June 2026, and the goal is a quicker, clearer, more predictable approval process for eligible new entrants, without lowering prudential oversight.
The regulator limits the initial scope to two groups. One group is provincial credit unions seeking continuance as a federal credit union. The other group is entities with technologically innovative or emerging banking models, including fintechs and crypto asset custodians, that seek to incorporate as a bank or a federally regulated trust and loan company.
The framework will use right sized, risk based prudential reviews and provide clearer guidance on requirements and timelines. OSFI also points to service standards and a planned dashboard to track progress. Also noted is that the application fees won't change, and it will not refund fees if timelines are not met. OSFI says it will use what it learns to refine its processes to support a broader rollout later.
OSFI limits fast track entry to provincial credit unions seeking federal continuance and to innovative or emerging models seeking to incorporate as a bank or a federally regulated trust and loan company. In practical terms, and without naming specific companies, the most likely early candidates are firms that already run bank grade controls and need a federal licence to unlock the next product layer.
That includes fintechs offering primary account style products at scale, custody first firms that want a federal trust model, payments and treasury infrastructure firms expanding into trust style services, and mature wealth or brokerage platforms that want a bank or trust licence to bring more of the stack in house.
Canada’s competition problem is not only about products. It is also about who can enter the system and how predictable the regulatory approval path is. A clear approval path lets founders and boards plan capital, governance, compliance hires, vendor choices, and launch sequencing around a known process. That can reduce the cost of fintechs and challenger banks attempting a regulated model in Canada. Faster entry can increase competition and widen choice for consumers and small businesses, but only if the rules are clear enough that serious teams and investors can commit early.
Crypto custody firms also get a clear signal. By including crypto asset custodians in scope for this initial fast track approval framework, it puts digital asset custody on the list of models OSFI is willing to assess through a defined entry framework.
Having said that, service standards need to execute in real timelines. The dashboards mentioned by OSFI need to publish meaningful progress indicators, not vague stages. The review still needs to be rigorous, but the timeline and progress pathway needs to be legible enough that applicants know what is coming next and when.
If OSFI delivers a faster and more predictable regulatory entry approval framework without lowering the bar, which new models actually enter first, fintech banks, federal credit unions, or crypto custodians?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 10, 2026 | NCFA Market Activity | Alternative Finance And Consumer Lending
On March 10 2026, Canadaian non bank, non prime consumer lender goeasy Ltd. released a financial and operational update ahead of its fourth quarter earnings report and said it expects about $178M in incremental charge offs tied mainly to its LendCare business. The company said total net charge offs for the quarter rise to about $331M and its allowance for credit losses increases by about $86M. goeasy share price tanked over 40% on the news.
The disclosure was significant enough that CIRO imposed a temporary trading halt pending the news release.
goeasy said its full year 2025 net charge off rate is about 12.9% and now expects that figure to rise into the mid teens in 2026 before improving in 2027. The company also warned the deterioration could create pressure under certain financing covenants and said it has entered into an accommodation agreement with lenders while negotiating amendments to its credit facilities.
goeasy withdrew its previously issued fourth quarter 2025 outlook and its three year forecast while management reassesses portfolio performance and the impact on the business. The company also said it will suspend its dividend and halt share buybacks under its normal course issuer bid in order to preserve capital while it works through higher losses and funding discussions.
Although this is a specific company event, the implications are beyond one issuer. goeasy is one of the most visible publicly listed companies in Canada’s alternative lending market, and developments at a large lender often influence how investors, warehouse lenders, and institutional funding partners view risk across the wider non bank consumer credit sector.
When a lender withdraws forecasts, increases loss reserves, and begins negotiating covenant relief, the market typically responds swiftly. Funding partners may tighten terms, demand more protection, or become more selective about similar credit exposures. It doesn't mean every lender faces the same situation, but it makes investors and new capital cautious.
For Canadian fintech lenders and point of sale financing platforms, it means a tighter credit cycle that will impact underwriting discipline, funding flexibility, and covenant headroom as much as origination growth. Companies that rely on institutional funding or structured facilities need clear visibility into portfolio performance and the ability to react quickly if delinquencies or losses begin to rise.
This update does not change financial infrastructure or market rules on its own, but it does highlight how quickly stress in non prime consumer lending can influence investor sentiment and capital availability across the sector.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 10, 2026 | NCFA Fintech Market Activity | Wealthtech And Consumer Finance
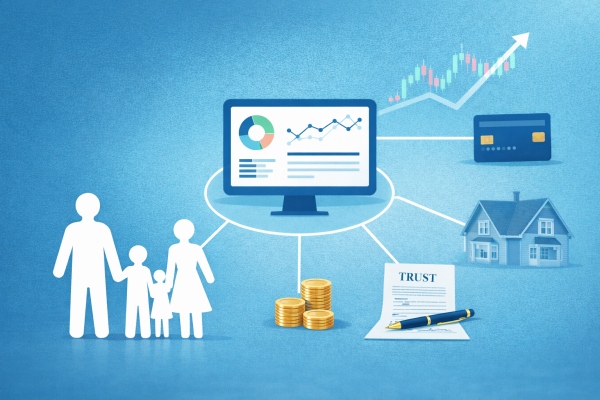
On March 4 2026, Robinhood unveiled new family finance products at its Take Flight event, adding a family investing experience, custodial and trust accounts, expanded managed investing tools, a new Platinum Card, and new Gold perks.
Vlad Tenev, CEO said:
“Robinhood will be the financial superapp for families to invest, plan, and grow wealth across generations.”
The platform continues to push further beyond retail trading and into family account oversight, wealth transfer, premium credit, and long term asset management. The new family hub is built to let households group accounts by family member, choose which accounts are visible, and assign permissions from view only access to full authority. Custodial accounts are rolling out now, while trust accounts and the family hub begin rolling out later this year.
This launch builds on an earlier NCFA analysis of Robinhood's wealthtech push and lifestyle finance strategy, but the new announcement goes further by tying family visibility, investing, credit, and wealth transfer into one customer experience.
The scale behind the launch is material. The platform reports 27.2 million funded customers, $324 billion in total platform assets, and $4.5 billion in 2025 revenue. That revenue rose 52% from 2024. Managed investing is also getting bigger. The firm says Robinhood Strategies now serves more than $1.5 billion in assets under management across more than 250,000 funded customers.
On the money side, it says there are more than 700,000 Gold Card customers with over $10 billion in annualized spend, while Robinhood Banking has more than 50,000 funded customers and over $800 million in cash deposits to date.
The premium card launch shows where the model is heading. The new invite only card carries a $695 annual fee and comes with richer travel, dining, and wellness benefits. That pricing puts the platform into a higher value segment as it tries to deepen relationships with customers whose financial lives are getting more complex.
When a platform bundles enough strategic product that can handle family account access, children’s investing, trust structures, managed portfolios, cash, and premium spending, it's getting closer to owning the main financial relationship in the household. That should raise eyebrows for banks, wealth platforms, and fintechs that still treat investing, credit, and family finance as separate product lines.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Regulation And Policy, Lending Consumer Credit And BNPL, Sustainable Finance And ESG

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026).
This is for AI first fintechs, SaaS platforms, and builders selling usage heavy products because AI cost recovery is moving out of finance spreadsheets and into the billing stack itself. This means markup, model pricing, and token usage can all be baked directly into a single workflow.
This affects crypto custody, brokerage, and compliance tooling teams, plus firms that run secondary market controls, because it pushes more of the crypto perimeter into client asset rule design while tightening where firms must look for core market mechanics requirements.
This changes the operating timetable for lenders, brokers, and claims handling firms, and it pulls more pressure onto complaint intake, identity checks, fraud controls, and customer communications. Fintechs offering claims workflow solutions, onboarding checks, and redress automation now need to map product readiness to the late March rules and the 3 to 5 month build window.
This opens an official lane that matters for remittance firms, merchant payments providers, instant payments infrastructure teams, and institutions building Canada India payment flows. Once payment system operators are invited into the file, the discussion moves closer to real operating design, not just diplomacy.
This opens a new regulated advice lane between generic guidance and individual advice. It affects banks, pension providers, wealth platforms, and fintechs building support flows, because firms now have a near term path to turn customer guidance into a permissioned product with real conduct and authorisation consequences.
This is important for issuers, dealers, custodians, and market infrastructure teams because a central bank backed trial now shows how tokenized bonds and central bank settlement money can run through an on chain workflow, which raises expectations on governance, auditability, and integration before this model can scale beyond pilots.
A major exchange operator is tying its regulated futures roadmap to crypto spot reference prices while pushing tokenized equities distribution through a large crypto customer base.
This is for banks, payment infrastructure firms, tokenization platforms, and securities settlement providers. The BOJ is linking blockchain, tokenized central bank money, and core settlement design to active pilots, sandbox work, and future upgrades to BOJ NET, which raises the bar for how seriously the market should treat settlement infrastructure moving on chain.
This raises the enforcement baseline for broker dealers and their vendors. If you create or sell onboarding, surveillance, AML, or case management tooling, expect more pressure to prove risk based controls, faster SAR decisioning, and audit ready evidence because regulators are treating gaps in thinly traded securities monitoring as a serious control failure.
This is a positive announcement for fintech vendors that sell to government, defence, banks, and critical infrastructure. AI evaluation, cybercrime response, and resilience checks start to converge across buyers.
As Canada and Australia open the door to more pension investment, investors will want simple, auditable reporting and quick due diligence, especially for payments, AI, and critical supply chain projects.
This delay ties up cash for importers and their banks. When refunds take weeks to process, treasury teams need tighter visibility into duty exposure, eligibility tracking, and cash forecasting, and that opens room for fintech tools that automate reconciliation and working capital decisions created by policy whiplash.
This could impact how payments teams operate. If merchants can query verified payments events in natural language and automate workflows on top of unified data, AI payments will run the operating layer for routing, fraud, disputes, and cost control, which raises expectations on data quality, lineage, and accountability across the payments stack.
The Fed is opening a controlled access point for a crypto linked institution inside the U.S. payments system. That sets a live precedent for how non bank and digital asset firms may be handled under account access rules, even where service scope stays tightly constrained.
This for issuers, acquirers, sponsor banks, card fintechs, and treasury teams because stablecoins are moving closer to core network settlement, not just crypto side rails. Once a global card network starts wiring a bank issued stablecoin into settlement flow, teams need a clearer view on treasury design, reconciliation, network rules, and what faster money movement looks like in practice.
This pushes stablecoins deeper into everyday card economics, not just niche crypto wallets. It matters for issuers, program managers, fintech developers, and infrastructure teams because card issuance, settlement, and reconciliation are starting to move into the same onchain operating stack at global scale.
Singapore is placing climate transition planning inside supervised financial risk management rather than limiting it to public reporting. The approach gives Canadian regulators and institutions a comparator for connecting climate data, portfolio decisions, customer engagement and governance while avoiding blunt exclusions that could restrict financing without reducing underlying risk.
Core financial infrastructure continues to move closer to programmable systems while regulators tighten the rules around how firms operate and protect customers. Stablecoins are entering card settlement, tokenized bonds are moving through central bank backed pilots, and AI usage is starting to show up directly inside billing and payments operations. At the same time, regulators are opening new product lanes and expanding oversight of crypto custody, advice models, and consumer finance practices. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 5, 2026 | NCFA Market Insight | AI And The Future Of Work

Image: Labour market impacts of AI: New measure, early evidence (Anthropic Mar 2026)
On March 5 2026, new Anthropic artificial intelligence labour market impact research | download 17 page PDF offers a more grounded way to think about AI and jobs. Most AI labour studies ask what large language models could do in theory. This one asks what workers actually do with AI now. That sounds like a small change, but it matters. Financial institutions, fintechs, and policymakers need to know where real workflow change starts, not just where capability headlines point.
The paper introduces a new measure called observed exposure. It combines occupational task data, Claude usage data, and earlier research on which tasks language models can theoretically handle. The approach tries to separate technical possibility from real use. That makes this study potentially more useful than other broad forecasts about AI replacing jobs. To be clear, at this point the research doesn't claim mass displacement has arrived. It looks instead for early pressure points that may show up before unemployment spikes.
This report matters because it focuses on real work patterns. The authors use the US O*NET task database, Anthropic Economic Index usage data, and earlier task level exposure estimates to build their measure. They also give more weight to automated and work related uses than to lighter forms of assistance. That helps the study track where AI starts to move from drafting help into actual production work.
That said, the research has real limits, and those limits matter. The usage data comes from Claude, not from the full AI economy. A bank using Microsoft, Google, OpenAI, or internal tools may show a different pattern. The measure also tracks task exposure, not direct job loss. And the authors make clear that adoption still lags capability because of legal controls, software requirements, human review, and workflow friction. That caution strengthens the paper rather than weakening it. It keeps the analysis honest.
The most striking findings is the size of the gap between capability and real usage. In STEM (ie. computer and math) occupations, earlier work suggests language models could theoretically touch 94% of tasks. Anthropic’s observed measure puts current Claude coverage in that category at just 33%. In other words, the technology frontier sits much further ahead than the adoption frontier.
That gap matters for fintech and finance because it points to where the real bottleneck sits. The next productivity jump might not come from a bigger, better, faster or smarter model alone. It might come from firms that redesign workflows, tighten controls, connect tools to internal systems, and build trust in output quality. Which operators can close the adoption gap faster than peers.
The report finds that computer programmers rank as the most exposed occupation, with 74.5% coverage. Customer service representatives follow at 70.1%, and data entry keyers come next at 67.1%. Digital, repeatable, text heavy work moves first.
What stands out for NCFA readers is that this isn't just software engineers. Financial analysts are also among the most exposed occupations in the paper’s wider discussion. That should get the attention of banks, insurers, wealth platforms, lenders, and compliance teams. A lot of value in finance comes from summarizing information, checking documents, explaining options, processing forms, and moving data from one system to another. Those are exactly the kinds of tasks that AI enters early.
Workers in the most exposed occupations earn 47% more on average than workers in the unexposed group. People with graduate degrees make up 17.4% of the most exposed group, compared with 4.5% of the unexposed group.
Early pressure is showing up in better paid, more educated, office based roles. In practice, that means AI may alter the work of analysts, developers, researchers, service teams, and operations professionals before it touches many frontline physical jobs. For financial institutions, this points to a management challenge as much as a technology one. Firms need to rethink role design, supervision, training, and quality control inside knowledge work functions.
The research does not find a growing rise in unemployment for workers in the most exposed occupations since late 2022. That is an important result because it pushes back on louder claims that AI already causes wide labour market damage.
But the report does find an early warning sign. For workers aged 22 to 25, job finding rates into highly exposed occupations fall by about 14% compared with 2022 levels. The authors stress that this result is only barely statistically significant and open to other interpretations. So something to watch and track.
This is how labour market change often starts. Not with mass layoffs. Not with an obvious cliff. It starts when firms stop hiring as many junior people because AI now handles part of the routine work those hires once learned on. That's important for banking, fintech, consulting, and other white collar sectors that depend on apprenticeship style career ladders. If entry points narrow, firms may save money in the short run while weakening their future talent pipeline.
Firms should watch three things closely to better anticipate where the real gap may open between leaders and laggards:
For fintech builders, the market needs tools that help institutions safely plug AI into live work. Audit trails, review controls, workflow routing, structured data extraction, policy checking, and role based permissions. Companies that solve those problems help close the distance between AI capability and actual business use and adoption.
Anthropic’s research is quite useful because it shows where real adoption starts, where the biggest gaps remain, and where the cracks may start to appear and proliferate.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016