




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Tech Ecosystem | June 6, 2025
Image: Freepik/travelscape
Web Summit Vancouver 2025 ran from May 27-30 2025 at the Vancouver Convention Centre attracting 15 727 attendees and with 1 108 startups from 117 countries, creating an electric atmosphere of discovery and deal making. Exhibiting startups spanned innovations in AI and machine learning, fintech and financial services, healthtech and wellness, and sustainability and cleantech.
Fintech solutions ranged from digital banking apps to blockchain payment rails, with Koho introducing a new international transfer service at the event. Founders pitched ideas, investors scouted opportunities, and conversations ranged from regulation to real-time fraud detection, confirming Canada’s growing role in global fintech innovation.
In the “Brands in Uncertain Times” session, Angus Reid of Angus Reid Group shared that nearly 50% of Canadians “vote at the cash register” by choosing brands aligned with their values. FCB Global CEO Tyler Turnbull added that Canadian consumers will pay 20-30% more for products produced and sourced in Canada, the premium on authenticity. For fintech companies, transparent fee structures and clear brand messaging are key to building consumer trust and loyalty.
AI dominated most panels, hallway discussions, and featured prominently across multiple stages. Sunny Madra, COO of Groq, announced Groq is now the exclusive inference provider for Bell Canada’s sovereign AI network, including two new data centres in British Columbia designed to bring AI processing closer to Canadian users. This new AI infrastructure will benefit fintech startups seeking access to low-latency, secure AI inference capabilities for real-time applications like fraud detection and compliance.
Sustainability and cleantech stood out alongside AI. Sessions highlighted how technology is driving environmental, social, and governance (ESG) goals, such as using AI to identify and price climate risks. Partners like OVHcloud showcased energy efficient cloud offerings, illustrating how infrastructure providers integrate ESG criteria into their services. For fintechs, embedding ESG considerations into product design and investment decisions is key for long term success. Not to mention the Competition Bureau's final rules on greenwashing that companies need to comply with.
4. Fintech Innovations and Cross-Border Payments
Financial technologies and services was one of the top represented verticals, with companies demoing solutions from digital banking apps and blockchain payment rails to regtech platforms. Toronto-based challenger bank Koho introduced its international money transfer service to over 190 countries, promising most transfers would arrive within 30 minutes during beta. By addressing opaque rates and slow settlement times, Koho’s launch shows how fintechs who listen to consumer issues can earn trust and turn these insights into new products/services that resonate with both Canadian and global markets.
5. Inclusive Entrepreneurship and Diverse Teams
44% of startups at Web Summit Vancouver were founded or co-founded by women. Beyond fintech, local firms such as Doubl, Revol Cares, and Aruna Revolution showcased solutions for women’s health and wellness.
Within financial services, fintech teams highlighted embedded credit services for underbanked populations and regtech platforms that serve diverse small-business owners. It's really diverse founding teams that drive not just inclusive entrepreneurship but solutions that resonate with underserved markets, strengthening innovation overall.
Technology is no longer judged only by what it can do, but by who it includes, what it protects, and how it earns trust. For fintechs and founders alike, this is the real edge of innovation and frontier.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Regulation | June 6, 2025
Image: Freepik
On June 5 2025, the Competition Bureau of Canada released final guidelines for greenwashing rules. The new rules apply to any business making environmental claims when selling products or promoting business activities including financial tech companies, ESG platforms, green loan providers, carbon credit startups, and any firm using green language in advertising, websites, or investor materials.
These updated guidelines reflect changes to the Competition Act which began on June 20, 2024. The law now clearly defines when green claims are allowed and what kind of evidence is needed to support them. The Bureau says they developed the final rules after reviewing over 400 public submissions, and are now in force. Now any firm that makes an environmental claim about it's product or business must be ready to prove it with fact-based evidence and proper documentation.
There are two provisions in the new Competition Act about greenwashing, (1) one about environmental benefit claims of individual products; and (2) another about environmental claims about a company and its business activities.
If a fintech makes a green claim about a product (i.e., protects the environment or reduces harm), it must be backed by suitable testing before the claim is made. Anecdotal evidence such as customer reviews or sales figures are not proper testing.
If a fintech claims that the company is environmentally responsible or heading toward net zero, then the claim must meet a reliable standard or an accepted protocol in Canada and internationally, including frameworks like ISO 14064 or GHG Protocol.
The Bureau makes it clear that companies must not exaggerate environmental benefits. Can't be vague or use 'feel good' language like 'eco-friendly' or 'sustainable' unless the claim is backed by specific evidence. For example, a product that uses 20% recycled packaging cannot advertise itself as 'environmentally neutral' unless the rest of the product has been tested to meet that standard.
Claims about future benefits, such as achieving carbon neutrality by 2030, require a clear and verifiable plan with interim targets and real progress tracking towards that goal.
There are numerous green financial products from lending products tied to home retrofits, solar energy or electric vehicles to 'low carbon' investment portfolios that will be impacted. If these products are being advertised as good for the environment or tied to climate goals then firms must now have data/documentation to support those claims or face enforcement.
The Bureau expects to see testing evidence before any green claim is made. What was the methodology used to support the green claim and is it internationally recognized and suitable in the Canadian context.
Penalties for corporations can reach up to $10 million for the first violation and $15 million for every violation thereafter. Also, if the value derived from the green claim benefit cannot be accurately measured, then the penalty can be up to 3% of the corporation's global gross revenue. The Bureau has already taken enforcement action in previous greenwashing cases, including against Keurig and Volkswagen.
Also as of June 20, 2025, individuals and private organizations can apply directly to the Competition Tribunal to challenge misleading green claims, opening the door for private sector oversight and potential legal action from investors, competitors, and consumer advocates.
There is however one safeguard for companies, which is a due diligence defence. If a fintech can show that it took reasonable steps to verify its claims and they followed recognized practices, it may help them avoid fines. Going forward, the pressure and burden is on companies to have robust compliance and documentation from engineering product development teams to marketing.
The bar is raised. For fintechs operating in Canada, green language can no longer be used for branding and promotion without properly being supported as it's a legal risk. Having said that, Canadian fintechs that can back up their green claims and properly document them will improve credibility with customers, regulators and global partners alike. Now how many of the banks will back off from their environmental claims?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Reg CF Data | June 5, 2025
Image: Freepik/rawpixel.com
On May 28, 2025, the U.S. Securities and Exchange Commission (SEC) released new data on Regulation Crowdfunding (Reg CF) as part of a broader update on capital formation and private funds. The Reg CF analysis studied regulation crowdfunding activity between 2016 and 2024 and reported that 8,492 offerings were launched by 7,134 issuers, excluding withdrawn campaigns.
But there's a data tracking issue with the SECs data. Of a total of 8,492 campaigns, only 3,869 of these crowdfunding offerings were reported as proceeds to the SEC, totaling about $1.3 billion. That means less than half of all campaigns included final results in the public record.
Even the SEC admits the numbers are incomplete in the report:
“This is likely to be a lower-bound estimate due to variance in Form C-U filing practices.”
This data gap has real consequences because it's harder for regulators, investors, and anyone interested in tracking crowdfunding capital flows, as industry evolves.
Sherwood “Woodie” Neiss, principal at Crowdfund Capital Advisors (CCA) and long time advisor to NCFA Canada, says this is a structural issue.
“The SEC’s numbers are based on what companies file, not what they actually raise. Most offerings don’t report final results, so the public sees less than half the full picture.”
To solve this problem, CCA built CCLEAR, a real time database that tracks every Reg CF campaign in the U.S. Instead of relying on incomplete filings, CCA collects live data daily from every platform and tracks/records the life of each campaign from launch to close.
Reg CF investors are putting more money into healthcare, energy, industrial and manufacturing. Sectors like tech, financial services, and real estate slowed down, while consumer categories like fashion and sports grew modestly.
Unlike the SEC who tracks capital by state, CCLEAR tracks it by postal code so it's at a more granular city level, which helps government, funders, and issuers gain deeper insights into crowdfunding capital flows and the startup ecosystem. During the reporting period, Austin, Miami, and New York City experienced growth, while San Francisco and Los Angeles saw declines.
Instead of only reporting how much a campaign raised at the end, CCLEAR tracks activity daily.
This type of platform data is important because it helps manage expectations and lawyers can better align campaign structures with investor interest.
The number of investors has gone down but the average check size is rising, signalling that a smaller group of confident investors are staying engaged:
Regulation Crowdfunding is growing fast, but the SEC only captures less than 50% of the the funding actually raised because they rely on form filings which mostly aren't filed, as their data source. Thankfully, tools like CCA's CCLEAR exist with real time tracking daily at granular levels of a campaign, so markets can understand where the capital is going, who is funding, and how best to optimize the structure of the funding rounds.
The implications of the SECs data reporting gap has implications that Canada can learn from as it reviews its own exempt market data practices. Platforms, regulators, and ecosystem leaders need better data infrastructure to best support early stage capital formation. Transparent, real time data is the foundation of market trust, policy design, and smarter investor participation, and is essential.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 3, 2025

The fintech industry in Canada is experiencing significant growth, driving a surge in demand for highly skilled professionals. This expansion necessitates innovative recruitment strategies to meet the sector's evolving needs. Specialized agencies in Toronto are pivotal in navigating this dynamic landscape.
As the fintech sector expands across Canada, companies face an unprecedented demand for talented individuals who can propel them forward. This burgeoning industry requires not only technical expertise but also innovative thinking to maintain its competitive edge. Recruitment agencies in Toronto play a crucial role in meeting these demands by sourcing top-tier talent effectively. Leveraging cutting-edge technology, these agencies facilitate connections between candidates and employers, ensuring the right fit for the intricate demands of fintech roles.
Artificial intelligence (AI) is transforming how recruitment processes operate within the fintech sector. By automating repetitive tasks, AI enables recruiters to focus on strategic decision-making and candidate engagement. This technological advancement enhances efficiency, allowing recruitment efforts to scale with the industry's rapid growth. With AI, you can expect more precise matching between job requirements and candidate skills, reducing the time and resources spent on finding suitable candidates.
Furthermore, AI-driven analytics provide valuable insights into talent acquisition trends and candidate behavior. These insights help recruitment professionals tailor their strategies to attract and retain top talent effectively. By leveraging AI, companies can streamline their hiring processes, making them more agile and responsive to market changes. For fintech companies, this means being able to quickly adapt to new technologies and methodologies that continue to emerge in this fast-evolving sector.
The integration of AI into recruitment also enhances the accuracy of candidate assessments. Automated screening processes can efficiently evaluate qualifications and experience, reducing human error and bias. This ensures a more objective selection process that focuses solely on merit and potential contribution to the company.
The competitive landscape for recruiting top executives in fintech is intensifying as more companies vie for a limited pool of qualified candidates. Specialized recruitment agencies are essential partners in this endeavor due to their deep understanding of industry nuances. These agencies possess networks and resources that significantly enhance their ability to identify and attract high-caliber professionals who may not be actively seeking new opportunities.
For you as an employer, partnering with these agencies offers access to a broader spectrum of candidates who possess the specific skills needed for success in fintech roles. The agencies' expertise allows them to quickly pinpoint candidates who align with your company's culture and strategic goals. This tailored approach is invaluable in an environment where technical prowess alone isn't enough; cultural fit is equally crucial for long-term success.
Specialized agencies provide you with strategic advice on competitive compensation packages and market trends, ensuring your offers are both attractive and realistic. Their insights help you remain competitive not just in terms of salary but also in work culture and professional development opportunities.
Recruitment agencies based in Toronto offer unique advantages when it comes to sourcing fintech talent. Their location at the heart of Canada's financial hub provides them with direct access to a vibrant pool of professionals immersed in the industry. These agencies have honed their expertise by working closely with fintech firms, gaining an intrinsic understanding of what makes an ideal candidate for this sector.
The depth of knowledge these agencies possess about industry-specific challenges enables them to craft customized recruitment strategies that meet your company's exact needs. They excel at identifying candidates who not only meet technical qualifications but also align with your organizational values and vision for growth.
The strategic positioning of these agencies allows them to stay abreast of industry developments and adapt their approaches accordingly. They continuously refine their methods based on emerging trends, ensuring they remain effective intermediaries between employers like you and potential hires.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Global Fintech Report | Jun 2, 2025
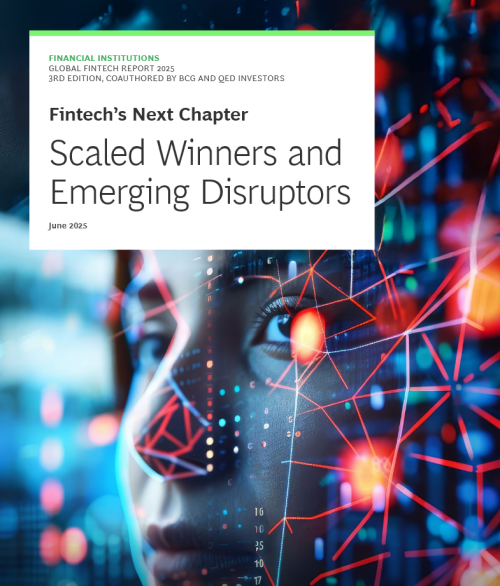
Image: Cover of Scaled Winners and Emerging Disruptors (June 2025, BCG and QED Investors)
The Boston Consulting Group (BCG) and QED Investors, just published a June 2025 report titled, "Fintech’s Next Chapter: Scaled Winners and Emerging Disruptors" (38 page PDF), highlighting that global fintech revenues rose 21% in 2024 compared to 6% for traditional financial institutions. That confirms fintech showed a strong rebound across sectors, accelerating from the prior year, after a couple of years of tightening capital markets and heightened regulatory scrutiny.
In 2024, fintechs generated $378 billion in revenue, while traditional banks and insurers earned $12.7 trillion. Fintechs have captured just 3% of this revenue, so 97% is still in the hands of incumbent financial institutions.
There are roughly 100 scaling fintechs earning over $500 million annually of which these 5 verticals dominate revenue generation:
These five sectors represent most of the $231 billion in scaled fintech revenue. Payments alone represent 55% of that total. Challenger banks and crypto platforms hold a smaller but growing share.
There are 150 global fintechs founded before 2016 that have raised over $500 million in equity and remain private. Many are waiting for improved conditions in the capital markets, such as Stripe and other scaling fintechs expecting to IPO
Fintech’s revenue share remains small across all verticals. Insurance accounts for less than 1% of fintech penetration. Deposits stand at just 2%. Lending, despite strong activity in personal loans and buy now pay later, accounts for only 3% of global lending revenues.
Agentic AI where AI powered systems are capable of logic and taking actions independently is a game changer. AI native fintechs have already gobbled up 49% of fintech equity funding yet only represent 23% of the sector.
Blockchain-based on-chain finance is also gaining traction. Tokenization of assets like bonds, private credit, and money market funds is growing at a double-digit rate. While tokenized asset volume remain under $1 trillion today, major institutions like Goldman Sachs and the European Investment Bank are piloting large-scale tokenization programs.
Private credit funds are also becoming essential to fintech lending models. With $1.7 trillion in assets under management, these funds are stepping in where traditional bank funding is constrained. The report estimates a $280 billion untapped opportunity for private credit participation in fintech-originated lending. In 2024 and early 2025, several billion-dollar forward flow deals were announced, including SoFi, Klarna, and Pagaya.
Fintech is rebounding and growing faster than traditional banks but has only unlocked 3% of global banking and insurance revenue, so the opportunity is still massive. Fintechs that can deliver sustainable growth, expand into new customer segments, and integrate new technologies like AI and tokenization will be well positioned to capture the next iteration of financial services tech.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Innovation Strategy | May 30, 2025
Image: Freepik/jannoon028
On May 31, 2025 the Economist ran an article called, "American finance always unique is now uniquely dangerous' unveiling how America’s financial system has evolved into a source of global instability. Private capital giants are creating a new class all to themselves and changing markets, powered by scale, opacity, and political uncertainty. For Canada, it's both a warning and more importantly our strategic moment. Instead of copying the American finance model, Canada can define it's own but strengthening capital independence by building trust-first finance, and accelerating high impact innovation with homegrown channels and tools.
The article explains how U.S. firms like Apollo, BlackRock, Blackstone, Citadel, and Jane Street have grown at unprecedented rates:
These firms operate at speed and scale, are highly interconnected and deeply exposed to volatility. They are providing the capital that fuels the economy, but are also increasing systemic risk. The Economist article points out that in the next crisis, investors may just wake up to a financial system they no longer recognize. Instead of looking at what this expressly means for America, let's turn our focus to what it means for Canada.
Instead of emulating what's unfolding in U.S. financial markets with a dose of more regulation, Canada can lead by building a financial model that is more open, independent, and focused on real impact and outcomes. Five areas of focus stand out:
Canada already has strong public institutions that support innovation. BDC, the Strategic Innovation Fund, NRC IRAP, and superclusters like DIGITAL are doing important work. But from seeing how the innovation economy operates first hand for years, these efforts often move in parallel, not in sync, so capital doesn't always reach the ventures that it should.
Canada needs a unified capital deployment strategy that links public funds, pension capital, credit unions, and private investors to the frontier innovations, such as AI, advanced fintech, clean energy, quantum computing, and digital infrastructure. What often seems missing is not just the capital or the infrastructure but national coordination, faster decision making, and larger bold scale.
New tools are needed, such as public-private innovation funds, industry specific capital acceleration platforms, and patient capital vehicles too that are designed to support mid to longer term commercial growth. Instead of launching more pilots, Canada must focus on coast to coast deployment frameworks and national collaboration that get more capital into the hands productive Canadian founders building the future.
Trust and transparency are two o f Canada’s greatest financial strengths but it only really matters when the rules are clear, the channels and processes are coordinated, and the government supports the program, then investors understand and are more open to participating.
Canada’s experience with equity crowdfunding is a good example of what happens when the above does not happen. Despite strong public and sector interest, fragmented provincial rules were rolled out, delaying adoption and making it difficult for platforms to operate nationally. Costs and confusion rose, and participation stalled. Even after the rules were unified under National Instrument 45-110 in 2021, much of the early momentum was lost, and it took years of slower growth to finally get wind in the sails and establish new milestones (a testament to a few dedicated and innovative entrepreneurs).
Even the best ideas need clear frameworks and national coordination to encourage public trust and participation. Everyday investors sit on the sidelines when the process is confusing or inconsistent.
This same risk applies to newer models like tokenized assets, which have the potential to bring more transparency and better tracking to private markets. These tools only work if they are supported by smart, unified policy frameworks that offer investors clarity and confidence.
Canada does not need more regulation. It needs simpler, better aligned systems that connect investors and innovators in a way that builds confidence at every level.
Canada should direct innovation capital to sectors that solve urgent national challenges. This includes enabling fintech to scale small business lending, improve insurance access, close affordable housing gaps, support clean energy transitions, and improve public service delivery by way of examples. The goal is not just economic return but national capacity building. Growth capital should help deliver long term social and economic value in Canada.
Achieving this means aligning investment programs, public procurement, and partnership models with outcomes that matter to Canadians. It also helps ensure that successful Canadian innovations are commercialized and scaled at home, not forced abroad due to lack of local support.
For innovation to scale safely and securely, Canada must invest in its own digital foundations. This includes national infrastructure for real time rails and modern payments, open banking/finance, digital identity, and interoperable data access. These systems are strategic. As global finance becomes more centralized and politicized, Canada needs open, Canadian-controlled infrastructure that supports innovation without dependency on foreign platforms or proprietary systems.
With the right digital infrastructure strategy in place, Canadian fintech and digital companies can grow on their own terms, compete globally, and deliver public value with greater trust and resilience.
Canada’s financial system should remain open to global capital but it shouldn't be overly dependent or reliant on any one market or political cycle. Diversifying capital sources, building a Canada-first tech capacity, and expanding international partnerships will help domestic innovators can grow on Canadian terms. Strategic independence is a competitive advantage.
The U.S. financial system is evolving quickly and funding innovation at scale in new ways, with new risks creating instability.
Canada should not be overly reliant on the U.S. for capital. It should focus on building a domestic model that backs Canadian innovators with capital, trust, strategic focus, and a clear national purpose. It is time to stop chasing someone else’s model and start shaping our own.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Report | May 29, 2025
Image: Freepik
On May 15, 2025, the UK government announced a new capital markets pilot called PISCES (Public Intermittent Securities and Capital Exchange System), a public market model designed to help high growth private companies raise money from investors without going fully public. Backed by the UK Treasury and the Financial Conduct Authority, PISCES offers qualifying issuers a new way to raise funds with more flexibility and less burden than a traditional stock exchange public listing, while keeping investor protections in place.
The goal is to close the funding gap for companies that have outgrown early stage venture capital but aren't yet ready or suitable for an IPO. The UK government said this new model will be tested with select scale-ups in 2025, and if successful could become a long term option that strengthens capital markets and keeps fast-growing businesses in the UK.
Key features of PISCES include:
Unlike a regular public company that remains on a stock exchange after it's initial listing, a company in the PISCES model can only raise money during specific time windows. So, they don't have to meet ongoing reporting or trading requirements in between those times. This creates more flexibility for companies that need capital but don’t want (or can’t manage) the cost and complexity of being fully public company.
Right now, Canada does not have a similar program like PISCES. Some similar options exist but they aren't the same:
The UK’s PISCES pilot is a good example of how policy and tech can work together to create smarter capital markets. It offers private companies more options for raising money at scale, while giving investors access to early-stage growth opportunities in a safe and structured way. If it means keeping more home grown Canadian scale-ups in the country then that's a good thing. With the right mix of regulatory support, infrastructure, and industry input, Canada could create its own version of PISCES to strengthen domestic capital formation and innovation. This is another one to watch.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016