




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


SME Export Program | February 5, 2026
Image: Freepik
On February 4, 2026 at 12:00 PM ET, the Trade Commissioner Service (TCS) confirmed that the 2026 to 2027 CanExport SME support program is now accepting applications until May 29 at 12:00 PM ET. This federal program provides non-repayable cost-sharing support to Canadian small-and-medium-sized enterprises (SMEs) pursuing new international markets where they have little or no existing sales.
This intake arrives as Canada emphasizes export diversification beyond traditional partners and as many growth stage companies look for practical financial support to reduce the cost and risk of entering foreign jurisdictions.
CanExport SMEs reimburses up to 50% of eligible export development costs, with a maximum contribution of $50,000 per project. The official program overview of eligible export activities shows that funding covers travel to foreign markets, participation in trade events, custom market research, legal and advisory services, and adapting marketing materials for international buyers.
For many SMEs, these early activities determine whether international expansion remains 'stuck in planning mode' or becomes a revenue stream. By sharing the cost of these steps, the program reduces the upfront burden that often delays export implementation.
Eligibility requirements for the 2026 to 2027 CanExport SMEs program has been updated to introduce higher thresholds that gear the program toward export-ready companies. Applicants must now employ at least 3 full time employees in Canada and report at least $300,000 in annual revenue in the most recent reporting year.
The update does not identify fintech or other technology sectors as priorities, but it confirms the program remains open to most business sectors that meet the revised eligibility rules, with the removal of conventional agriculture, agri food, fish, and seafood. Fintech companies that operate as for profit SMEs and pursue new global markets are eligible when their projects focus on export development activities, such as market entry research, buyer engagement, regulatory or legal preparation, and international business development. For fintechs selling software, platforms, or regulated services abroad, CanExport can support early market validation and commercial outreach, even though the program does not offer sector specific treatment.
The same update also revises target market rules. Applicants may target either the United States or other international markets within a single project, but not both, and each country now counts as one market toward the project maximum of five markets. These rules affect how companies structure export plans and select priority markets.
The CanExport SMEs applicant guide confirms that eligible applicants must operate as a for profit business legally established in Canada, employ between 3 and 500 full time employees, report between $300,000 and $100 million in annual revenue, and target markets where current sales remain limited or nonexistent.
These rules direct funding toward companies that show readiness to translate export activity into measurable commercial outcomes.
The CanExport SMEs intake gives prospective Canadian exports a defined window to secure federal support for international growth. Companies that prepare early, define clear target markets, and build detailed activity plans stand the strongest chance of approval before the May 29 deadline.
Many Canadian firms hesitate to enter new markets because of cost, uncertainty, and lack of local knowledge. CanExport directly addresses those barriers by sharing the financial burden of research, travel, legal preparation, and buyer engagement.
As Canada pushes companies to diversify trade relationships, this program offers practical support that helps exporters convert international interest into structured market entry.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Feb 5, 2026 | NCFA Fintech Market Activity | Digital Assets and Market Infrastructure
Image: Unsplash/Carlos Muza
On February 5 2026, Circle and Polymarket announced a partnership to strengthen onchain financial markets using USDC settlement infrastructure. The agreement connects USDC directly into Polymarket’s prediction market platform, allowing market participants to fund, trade, and settle positions using a regulated dollar backed digital currency rather than relying on fragmented crypto rails.
This matters because prediction markets are not just betting platforms. They function as real time price discovery engines where participants assign probabilities to real world events. When settlement moves onto stablecoin infrastructure, these markets begin to resemble financial exchanges more than niche Web3 applications.
Polymarket has grown into one of the most active prediction platforms globally, often pricing geopolitical events, elections, macroeconomic outcomes, and policy decisions faster than traditional analysts. Bringing USDC into that environment links regulated stablecoin liquidity to live market intelligence flows.
Circle positions USDC as compliant digital cash designed for payments, treasury use, and financial market settlement. This partnership places that infrastructure directly into a market where capital moves continuously based on information, not merchant payments or remittances.
For fintech builders and investors, this shows where stablecoins begin to matter beyond transfers. They start acting as the settlement layer for new types of markets that operate continuously, globally, and without traditional clearing houses.
This partnership shows the financial plumbing behind that evolution maturing in parallel.
If stablecoins become the default settlement layer for real time information markets, how long before similar infrastructure appears in capital markets, insurance pricing, and risk trading?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 5, 2026
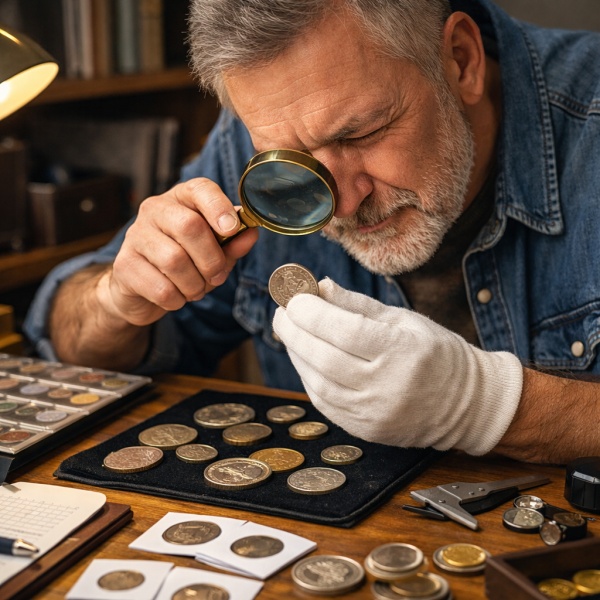
Selling rare coins or gold can feel overwhelming. You want a fair price, but the process seems complicated. This guide breaks down what you need to know to make informed decisions and get the best return on your precious metals.
Before you sell, you need to know what you have. Rare coins and gold pieces vary wildly in value. A coin's worth depends on its metal content, rarity, condition, and historical demand.
Gold coins fall into two categories: bullion and numismatic. Bullion coins like American Eagles or Canadian Maple Leafs trade close to their metal value. The price follows the spot price of gold, which changes daily based on global markets. Numismatic coins have collectible value beyond their metal content. A pre-1933 gold coin might sell for several times its melt value because collectors want it.
Rare coins without gold content can still command high prices. A 1909-S VDB penny in mint condition sells for thousands of dollars. The 1916-D Mercury dime? Collectors pay premium prices for clean examples. Condition matters tremendously in coin collecting.
When you're ready to sell, working with experienced buyers makes the difference. Austin Coin Buyers can assess your collection and provide current market valuations based on actual sales data, not outdated price guides.
Professional grading helps establish value. Third-party grading services like the Professional Coin Grading Service (PCGS) and Numismatic Guaranty Company (NGC) authenticate and grade coins on a 70-point scale. A coin graded MS-65 (Mint State 65) will sell for more than the same coin in MS-60 condition.
Grading costs money. You pay fees for submission, grading, and return shipping. For common coins worth less than $100, grading might cost more than the value increase. Save grading for coins that could be worth $500 or more. A dealer can help you decide which coins justify the expense.
Gold purity also affects value. The United States Mint produces coins in 22-karat (91.67% pure) and 24-karat (99.99% pure) gold. Jewelry often uses 14-karat (58.3% pure) or 18-karat (75% pure) gold. Buyers test gold items to verify purity before making offers.
Gold prices fluctuate based on economic factors. When inflation rises, investors buy gold as a hedge. During economic uncertainty, gold typically gains value. The spot price represents the current trading price for one troy ounce of pure gold.
Let's break it down. If gold trades at $2,000 per ounce and you have a one-ounce American Gold Eagle (91.67% pure), your coin contains about $1,833 worth of gold. Dealers typically pay 90-95% of melt value for bullion coins. You might receive $1,650-$1,740 for that coin.
Rare coins don't follow spot prices as closely. A Saint-Gaudens Double Eagle in exceptional condition might sell for $2,500 when it contains only $1,800 in gold. Collectors pay for scarcity and beauty, not just metal.
Timing your sale can affect your return. Watch gold prices over several weeks. If prices trend upward, waiting a few days might net you more money. If prices are falling, selling sooner protects your value.
You have several options for selling rare coins and gold. Each has pros and cons.
Local coin dealers offer immediate payment and face-to-face transactions. You can ask questions and get answers right away. Reputable dealers have established businesses and care about their reputation. They buy regularly and know current market prices.
Online marketplaces like eBay reach more buyers. You might get higher prices from collectors willing to bid competitively. But you'll pay listing fees, final value fees, and payment processing fees. Shipping precious metals requires insurance and tracking. Scammers exist online, both as buyers and sellers.
Auction houses work well for extremely rare or high-value items. They market to serious collectors and provide authentication services. Auctions take time, and you'll pay commission fees of 10-20%. Reserve prices protect you from low-ball sales, but they might prevent a sale if bidding stays weak.
Pawn shops buy gold and coins but usually pay the least. They need to resell at a profit and often lack specialized knowledge about rare coins. Visit pawn shops only if you need cash immediately and have no other options.
Honest dealers outnumber scammers, but problems exist. Watch for these warning signs.
Pressure tactics should send you away immediately. "This price is only good today" or "I have another buyer waiting" are manipulation techniques. Legitimate dealers know their offers are competitive and don't rush you.
Vague or confusing explanations about pricing indicate problems. A good dealer explains exactly how they calculated their offer. They'll show you the spot price, discuss premiums, and justify their buying percentage. If you don't understand the math, ask again or leave.
No physical location or unclear business information raises concerns. Check for a real address, phone number, and business license. Online reviews help, but read carefully. A few negative reviews among hundreds of positive ones is normal. Patterns of similar complaints deserve attention.
Clean hands and a clean workspace protect your coins. Dirt and oils from your fingers can damage rare coins. Never clean old coins yourself. Cleaning removes the patina that collectors value and can reduce a coin's worth by 50% or more.
Organize your items before meeting with a dealer. Group similar items together. Separate gold coins from silver coins. Put rare coins aside from common ones. This preparation shows you take the process seriously and helps the dealer work more efficiently.
Bring documentation if you have it. Receipts, previous appraisals, and certificates of authenticity all help establish value. Original packaging for modern bullion coins adds to their worth.
Know your bottom line before you start negotiations. What's the minimum price you'll accept? Having this number in mind prevents you from making emotional decisions or accepting low offers out of convenience.
Expect the dealer to examine each item carefully. They'll check dates, mint marks, and condition. For gold items, they'll test purity using acid tests or electronic testers. This process takes time, especially for large collections.
Ask questions during the evaluation. Why does this coin grade higher than that one? How did you calculate the gold content? What affects this coin's value? Good dealers enjoy sharing their knowledge.
The dealer will make an offer based on their evaluation. You can accept, decline, or negotiate. If the offer seems low, ask them to explain their reasoning. They might point out damage you didn't notice or explain current market conditions.
Get your payment in your preferred form. Cash works for smaller transactions. Checks or bank transfers suit larger sales. Some dealers offer both. Whatever you choose, get a detailed receipt listing each item sold and the price paid.
Inherited coins require extra care. You might not know what you have or what it's worth. Don't rush the process.
Sort items roughly by type. Put gold coins in one group, silver coins in another, and so forth. Look for obviously old or unusual pieces. These might have the most value.
Consider getting a second opinion on inherited collections. If one dealer offers $5,000 and another offers $8,000 for the same items, that gap tells you something. Most honest dealers will price within 10-15% of each other.
Estate sales sometimes include coins that the original owner thought were rare but aren't. The 1943 steel penny, for instance, is common despite its unusual appearance. A dealer can separate the truly rare from the merely old.
The IRS treats precious metals as collectibles. When you sell coins or gold for more than you paid, you owe capital gains tax. The collectibles tax rate maxes out at 28%, higher than the 15-20% rate for stocks.
Keep records of what you paid for items. Your cost basis reduces your taxable gain. If you inherited coins, the cost basis usually equals their value on the date of death, not what the original owner paid.
Sales over $10,000 in cash trigger reporting requirements under federal law. Dealers must file Form 8300 with the IRS. This applies to cash only, not checks or electronic transfers.
Consult a tax professional if you're selling a large collection. They can help you time sales to minimize taxes or split sales across tax years to stay in lower brackets.
Selling rare coins or gold requires research and patience. Understanding what you own, getting fair appraisals, and choosing the right buyer all affect your outcome.
Trust matters more than getting the absolute highest price. A dealer who pays 5% less but treats you fairly and honestly beats one who quotes high numbers but uses deceptive practices.
Take your time, ask questions, and don't settle for the first offer. Your rare coins and gold deserve careful attention, and you deserve fair compensation for your items.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 4, 2026 | NCFA Insights | AI, Financial Infrastructure and Identity

On February 2 2026, security firm Wiz disclosed an exposed Moltbook database tied to autonomous AI agents containing millions of API keys. Around the same time, OpenClaw (an open source framework for running locally controlled AI agents) published documentation showing how locally run AI agents can access user devices, credentials and external services.
Autonomous AI agents aren't limited to chat style tools, and are beginning to touch real infrastructure that includes identity, wallets, and payment-related APIs.
This article discusses the what the emerging agent economy looks like in practice, why it matters for fintech founders and investors, and where governance and security pressure is building first. AI agents increasingly hold credentials, maintain state over time, and interact with external systems through APIs. That mix creates a new operational reality. Code is starting to act like a user, but without the same guardrails that traditional consumer finance expects.
Early agent frameworks are moving from single session prompts into persistent software. They can store memory, maintain identity, and run tasks continuously.
In OpenClaw’s model, locally run agents can interact with files, services, and external applications using user approved permissions. These agents can coordinate with other agents, call tools, and keep operating after a user stops watching the screen.
That capability becomes financially relevant the moment an agent can access a wallet credential, a banking API token, or a payment workflow embedded inside another platform.
Fintech products already sit on top of API keys, tokens, and delegated permissions. Wallet providers, open banking connectors, payment facilitators, and embedded finance stacks often rely on shared secrets and scoped access to move data or value. AI agents introduce a new actor into that system. A human might authorize a connection once, then an agent can repeatedly execute actions across that access channel at machine speed.
If an AI agent initiates a transaction, who owns responsibility for the outcome.
If an agent uses an API credential and a vendor later mishandles logs or storage, who absorbs liability.
If an agent operates in the background, how do firms enforce consent, audit trails, and appropriate use.
The Moltbook exposure matters because the risk is suddenly tangible. An unsecured database containing API keys is not a routine bug. It shows how quickly agent networks can create large pools of credentials that become attractive targets. When an environment contains millions of agent identities, a failure in credential storage or access control can scale into massive compromise. And of course, the financial equivalent is obvious. Once agents connect to wallets, payments, or identity services, insecure key management becomes a direct financial risk.
Fintech teams already know that credential hygiene and access governance decide security outcomes. AI agents compress that timeline. Humans leak keys through mistakes. Agents and agent networks can leak keys through architecture. That is why builders should treat agent access as its own risk class, separate from standard consumer or enterprise authentication patterns.
Regulators do not yet have comprehensive frameworks for AI agents operating inside financial workflows. Even so, policy direction in adjacent areas points to where enforcement will land first. Authorities focus on accountability, auditability, and consumer harm, regardless of channel. That already shows up in digital advice and online influence. Learn how CSA and CIRO tighten expectations around digital investment advice and influence when content or workflows can affect investor behaviour at scale.
AI agents create a similar accountability gap. If an agent provides recommendations, executes actions, or routes users into products, platform operators will need evidence of controls. That will include permissioning, logging, dispute handling, and clear assignment of responsibility when something goes wrong.
If AI agents can hold credentials and execute actions through financial APIs, what controls will separate trusted automation from uncontrolled delegated access?
The agent economy is coalescing at the edge of finance. AI agents that operate with identity and persistent access can become a new layer between users and money transfers. The winners will treat governance as part of product design. They will harden credential management, build clear authorization flows, and design auditability that works when software, not a person, invokes actions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 4, 2026 | NCFA Fintech Market Activity | Regulation and Digital Assets
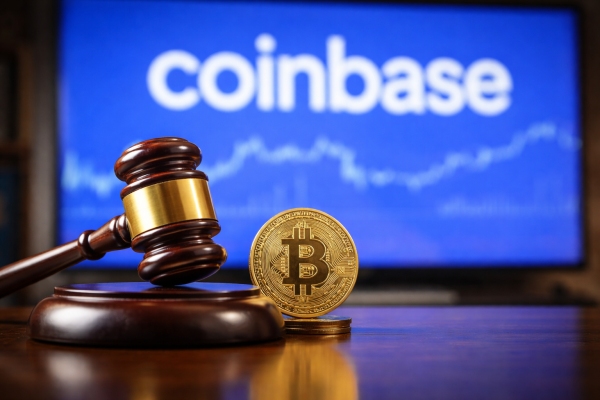
On February 3 2026, Nevada filed a civil enforcement action against Coinbase prediction markets in court alleging Coinbase offered sports-linked event contracts without a required Nevada gaming licence.
The regulator argues that the contracts available through Coinbase’s prediction markets are considered wagering activity under Nevada law and therefore requires state authorization. The filing seeks a temporary restraining order and preliminary injunction to prevent Coinbase from operating these markets in Nevada while the case proceeds.
Coinbase launched its prediction markets nationally in all 50 states in late January through a partnership with Kalshi, a derivatives exchange registered with the U.S. Commodity Futures Trading Commission. Users can trade yes or no contracts on real world outcomes, including professional sports events, directly inside the Coinbase app. NCFA has previously examined how prediction markets begin pricing geopolitical and financial outcomes across traditional and digital finance.
This case highlights a growing regulatory conflict. Coinbase maintains that prediction markets fall under federal derivatives oversight through the CFTC. Nevada’s regulator treats the same product as sports wagering that falls under state gaming law. That difference creates immediate compliance risk for fintech platforms offering event-based contracts across multiple jurisdictions.
Several other U.S. states have already taken steps to restrict or challenge similar markets tied to sports outcomes. Nevada’s action is the first to move into formal court proceedings against Coinbase’s implementation.
When prediction markets sit between derivatives law and gaming law, how should fintech platforms design licensing, governance, and market access controls across jurisdictions?
This case forces a legal definition of where and when prediction markets belong inside financial regulation and whether digital platforms can rely solely on federal derivatives oversight when states interpret the same contracts as wagering.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 3, 2026

We know the tech market is flooded with big corporate giants and SMEs surviving on their innovations and tons of new entrants trying their best to keep their heads above the water.
Entering into a pool of young and thriving businesses and making your way to a point where you’re recognized by your target audience as a tech marketing company is a big challenge in itself.
According to marketing data, viewers retain a staggering 95% of a message conveyed through video, compared to only 10% through text. Furthermore, simply placing a compelling video on your landing page can boost conversion rates by up to 80%.
Zelios animated video production company knows this intricate market well. We have been observing it since its inception and know what works and what doesn’t. We know the dos and don'ts.
Watch until the end to hear Zelios share valuable tips for growing your tech startup in this hyper-competitive market.
Setting up clearly outlined goals is important before you start recording your video. Too often, startups create content without clarity, resulting in inconsistent messaging and poor performance. You don’t just need a video, you need an impactful video!
Ask yourself:
Once you find answers to these questions, you need to know your audience by developing their personas. Figure out their primary pain points and preferred social platform they use, to help you target the right audience without wasting resources.
Over-selling doesn’t work in this market. People love to connect with brands through emotions. Your old-traditioned aggressive sales pitches aren’t going to bring any good to your startup. Your video content should focus on establishing an emotional connection and building credibility first.
A crucial tactic is to "Sell the Problem" before offering the solution. Highlight the pain point your audience experiences and validate their struggle before introducing your product as the natural answer.
A startup's unique mission and origin story can be compelling video content. Share why you started the company and what values drive your team. This vulnerability builds trust far faster than a dry feature list.

Social proof is priceless, especially for a new technology company seeking validation. Potential customers trust the experiences of their peers more than they trust your company’s sales claims.
Customers trust peer voices more than brand messages. Even simple videos of customers explaining how your product helped them can outperform high-budget ads because they feel honest and unscripted. You can also encourage your early adopters to share their experiences on platforms like TikTok or Instagram. This content is inherently authentic and often generates buzz organically.
The best tech marketing is often instructional. Your audience wants to know how your product works, why it matters to them, and what solution it offers to their problem.
Pairing education with product demos helps you provide value upfront and show exactly how your solution works. People often watch videos to learn first and buy second, so this combination is especially potent.

Video SEO is often overlooked. If the search engine algorithms are unable to find your video on the internet, how would your audience will? Here are some of the tips that would help you improve your video’s optimization.
Don’t stick to only one platform. Try different options. If you’re only posting your videos on YouTube, try making short reels and post them on different social platforms like Instagram, TikTok, and even Facebook.
Here are some actionable steps that you can take to maximize your ROI by filming one high-quality piece and adapting its format.

With each new video you produce, think about how you can reuse footage to create fresh content without starting from scratch. Social media isn’t the only platform where you need to bombard with your videos. Embed testimonial videos and product demos directly into your sales decks and pitch presentations.
You can also turn your old recorded webinars into short tips clips, or extract quotes for social graphics, or maybe edit the longer videos into mini-series. This approach helps you squeeze all the juice from your already existing content and create a new, fresher content without requiring any extra cost or time. But you have to be a little creative with it.
Video marketing is no longer optional, it is the core driver of modern startup growth. Whether you go down the path of creating memes and selling your business, or create professional videos with clear script, videography, and directions, the choice is yours depending on the dynamics of your audience and business niche.
But no matter what you do, never take the power of video production for granted.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 30, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Payments And Money Movement, Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization, Open Banking Open Finance And Data Sharing

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026)
Payment activity, API demand and recurring use increased while system performance remained stable. The figures establish an operating benchmark for countries building open banking around data access, payment initiation and commercial services. The later one billion payment milestone shows how quickly that base continued to expand.
Once a PSP can join the payments club directly, it can cut onboarding friction, tighten settlement and reconciliation, and show stronger operational maturity to banks, enterprise buyers, and regulators. Founders that treat membership readiness as an operating system will move faster when big partners demand proof. Investors should watch which PSPs turn access into volume and repeatable unit economics, not just press.
This is a planning signal for how the UK approaches AI in retail finance. Firms that sell into regulated buyers win time if they can show who owns outcomes, how models get tested, and how controls work across vendors and data flows. Teams that cannot evidence that quickly will find AI work slows down at the point of trust, not the point of build.
This matters to fintechs that sell into regulated buyers because coordination changes the buyer checklist. The winners standardize controls and reporting across spot, derivatives, custody, and settlement workflows so they do not rebuild the stack every time definitions and boundaries tighten.
This takes tokenization out of the hype lane and into build discipline. If you sell tokenized security rails to real institutions, you win deals when you answer the hard questions fast, who controls the record, how transfers stay legally effective, and where the product plugs into broker dealer, transfer agent, and clearing and settlement expectations.
This move embeds regulated stablecoin issuance directly into a global payments platform instead of leaving it at the edge. When stablecoins sit inside licensed EMI rails, settlement, liquidity management, and compliance become part of the core payments stack. Founders building wallets, FX, treasury, or cross border infrastructure should expect buyers to favor platforms that combine regulated issuance with distribution at scale.
A federal trust structure offers nationwide reach, clearer supervision, and stronger institutional credibility. Fintechs selling custody, settlement, compliance, or risk tooling should prepare for customers that operate under bank grade expectations. Investors should watch which applicants can survive the supervision burden that comes with federal status.
This pulls crypto compliance into product planning. Teams that want UK market access move faster when they convert these rule areas into workflows early, especially safeguarding, reporting, and accountable ownership across senior roles.
Payments access expands in Canada while regulators in the UK and US push firms toward clearer accountability in AI, crypto, and tokenized securities. The common thread is execution readiness. Buyers now ask who owns the record, who controls outcomes, and how a platform proves it can operate under supervision without slowing down. Fintechs that build for audit, governance, and market access early earn trust faster and avoid costly rebuilds when rules tighten around custody, settlement, and consumer outcomes. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016