




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Stablecoins | June 27, 2025
On June 24 2025, in chapter 3 of its Annual Economic Report, "The next generation monetary and financial system" (38 page PDF), the Bank for International Settlements (BIS) warns that stablecoins fail to function as real money. The report arrives just as the United States moves closer to signing the GENIUS Act into law, a federal bill that would bring stablecoin issuers under formal supervision.
The report outlines how stablecoins fail to meet the key tests of singleness, elasticity, and integrity, which defines whether a payment instrument can be accepted at face value, scale with economic needs, and operate safely in the broader financial system.
BIS Report states
“Stablecoins perform poorly when assessed against the three tests for serving as the mainstay of the monetary system,”
The BIS applies three core tests to any money-like instrument, and casts serious doubt whether private stablecoins can ever serve as a true foundation for payments or monetary exchange, even if regulated.
The BIS also says broader risks to financial stability, including potential fire sales of safe assets held in reserve and cross-border flows that could undermine monetary sovereignty in emerging markets.
The GENIUS Act has now passed the Senate with strong bipartisan support and is moving to the House for consideration but does not treat stablecoins as public money. It takes a supervisory approach while explicitly banning certain features, key provisions include:
The bill has advanced in both the House Financial Services and Senate Banking committees and has bipartisan backing. Supporters argue that clear rules are needed to protect consumers and prevent runs on poorly backed coins. But the BIS report raises a bigger question. Even if stablecoins are regulated, should they be foundational to the payment system at all?
While Canada has not yet introduced comparable legislation as the GENIUS Act in the U.S., the BIS developments will influence local debates. Stablecoins are already used by some Canadians for crypto trading, remittances, and access to foreign currency.
The Bank of Canada has shelved retail CBDC development while continuing digital currency research and scenario planning, and OSFI is developing crypto exposure guidance for regulated financial institutions.
If the US establishes a regulated market while the BIS encourages a public infrastructure model, Canadian policymakers and fintechs may need to navigate both. That includes deciding whether to integrate regulated stablecoins, develop domestic alternatives, or back a central bank issued platform.
Both public institutions and private developers are building in parallel but the debate is no longer theoretical, and Canada's choices made now will impact financial systems as they grow and evolve.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Crowdfunding | June 25, 2025
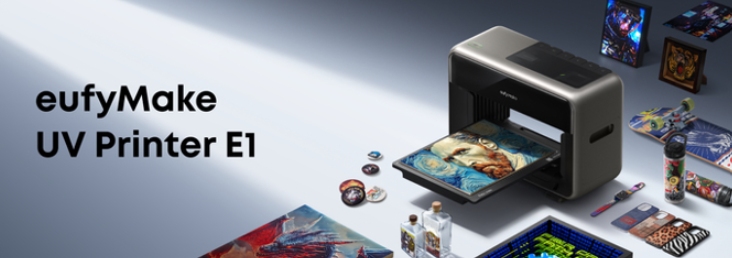
On June 24, 2025, the eufyMake E1 UV Printer officially became the highest funded project in Kickstarter history; raising over $61 million from more than 17,000 backers, surpassing the previous record of $41.7 million. The compact printer offers plug and print functionality and can print on a wide range of materials including metal, leather, and glass. Pricing at $499 helped attract broad consumer interest during its 30-day campaign window.
According to the release, the campaign launched on April 29 and exceed $10 million in the first 14 hours, and then became Kickstarter's all time funding leader in less than a month. This is a monstrous achievement and moment to celebrate for non-investment crowdfunding in 2025.
In recent years, most attention in alternative finance has shone a spotlight on equity crowdfunding, token sales, and hybrid fintech models. Yet the record breaking and live E1 crowdfunding campaign shows that reward-based crowdfunding can still raise significant funding at global scale when a product fits the market.
Kickstarter campaigns offer backers early access to physical products without offering ownership. This lowers legal and regulatory barriers, making the model especially attractive for consumer hardware, creative tools, and design-led products.
For Canadian entrepreneurs, makers, and platforms, the E1 campaign is a reminder that product-led innovation can still be funded directly by users, backers, and supporters. A strong value proposition, clear use case, and professional campaign execution with digital-first product marketing can still generate global momentum on reward-based platforms.
Canadian companies that are not yet ready or suitable for venture equity funding or tokenization may find reward crowdfunding a valuable first step to validate demand, generate working capital, and build a user base. Interested in snagging one of these incredible printers? There's 66 hours to go. Be part of a record breaking campaign: https://www.kickstarter.com/projects/ankermake/eufymake-e1-the-first-personal-3d-textured-uv-printer
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Digital Tax | June 23, 2025
Freepik - Rawpixel.com, taxes
*Update: On June 29, 2025, the federal government of Canada rescinded it's DST tax, a good faith tactic ahead of CUSMA negotiations.
As reported by CTV News, the Minister of Innovation, Science and Industry François-Philippe Champagne said on June 19, 2025 that Canada will not delay or pause the 3% Digital Service Tax (DST), even as U.S. lawmakers and Canadian business groups continue to voice strong opposition, setting the stage for further potential trade retaliation from the United States.
Canada's Digital Service Tax act passed into law in 2024 and will be retroactively applied from January 1, 2022, with initial payments due by June 30, 2025. It targets tech giants earning over €750 million globally and at least $20 million CAD in annual Canadian digital revenues from online advertising, digital marketplaces, and user data monetization.
Critics argue the DST unfairly targets American firms like Meta, Amazon, Google, Uber, and Airbnb and risks violating Canada’s commitments under the OECD/G20 Inclusive Framework and the Canada-US-Mexico Agreement (CUSMA).
On July 11, 2024, members of U.S. Congress in a bitpartisan letter, urged the Biden administration to consider punitive tariffs, if Canada proceeded unilaterally with the tax. American tech lobby groups, including the Information Technology Industry Council and the Computer and Communications Industry Association, have issued statements warning of double taxation and negative impacts on investment.
Canadian organizations including the Chamber of Commerce and the Retail Council have also raised alarm about economic consequences. They say the DST will increase consumer prices, destabilize bilateral trade, and hurt Canadian competitiveness.
Yet the federal government insists the measure is necessary to ensure fair tax treatment and close loopholes for global digital firms operating in Canada. Champagne said Canada is prepared to defend its position and stressed that domestic companies must not be disadvantaged by outdated tax systems.
NCFA recently wrote an article about the DST compounding pressure points for Canadian fintechs, already facing increased costs from Trump's tariffs. The combined regulatory and trade barriers could slow growth, raise compliance burdens, and weaken investment flows in a critical sector to Canada’s innovation strategy.
Canada is not alone. Countries including France, Italy, Spain, Austria, the United Kingdom, Turkey, and India have also enacted unilateral digital services taxes, citing similar concerns about tax fairness in the face of untaxed digital revenues.
These countries share several traits. They have large and growing digital user bases, limited ability to tax foreign digital giants under the current rules, and political pressure to rebalance domestic tax fairness. And many of these nations have grown impatient with the slow pace of OECD reform and acted independently.
Multinational firms like Google, Meta, and Amazon often avoid local corporate tax obligations by recording revenue in lower tax jurisdictions, even when earning substantial income from users in countries with no physical business presence. DST programs in these countries are their attempt to capture their share of this otherwise untaxed activity.
In contrast, countries like Germany and Japan have avoided unilateral DSTs. Despite facing the same digital tax gap, they prioritize maintaining stable trade and diplomatic relations with the United States and remain committed to resolving the issue through OECD-led multilateral reform. They fear that unilateral DSTs could provoke retaliatory tariffs or disrupt broader trade relationships. Their restraint is shaped by economic strategy, geopolitical alignment, and their deeper integration with U.S. supply chains.
By pushing forward with a DST in 2025 despite U.S. threats, Canada is one of the more assertive jurisdictions globally and at the forefront of U.S. DST activities. Its approach reflects growing domestic political pressure to tax digital activity fairly, even if it risks short-term diplomatic tension. However, it also positions Canada as a potential target for trade retaliation if a negotiated OECD solution is not reached soon.
Instead of enforcing a unilateral DST, Canada could explore alternative policy paths. One option is to delay implementation and condition it on measurable progress in OECD multilateral negotiations. This approach could defuse trade tensions while preserving Canada’s leverage. Another path is a bilateral tax agreement with the United States targeting large digital firms.
Canada could also consider expanding existing corporate tax rules to capture significant economic presence in the digital space, without relying on a standalone DST.
A final alternative is to introduce temporary digital levies that phase out automatically once an OECD framework is enacted, aligning political accountability with global reform timelines.
The digital services tax and U.S. trade threats are now intertwined, creating uncertainty for fintechs operating in or expanding into Canada. Companies should monitor policy developments closely. As geopolitical and regulatory pressures escalate, nimbleness and smart coordinated action will be key to maintaining innovation, competitiveness, and market access.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Tokenization | June 18 2025

As covered by Retuers, Coinbase is officially asking the U.S. Securities and Exchange Commission (SEC) to approve tokenized equities (or stocks), a new class of financial product. These would be blockchain representations of traditional equities, such as Apple or Tesla, designed to trade 24/7 with almost instant settlement and lower overhead. Coinbase is seeking a no-action letter or regulatory exemption from the SEC, and if they grant it, Coinbase would be the first major U.S. exchange operating with such tokenized products, evolving well beyond just a standard crypto trading exchange.
The tokenized equity model would allow retail and institutional users to access fractional ownership of blue-chip stocks via a blockchain interface and operate largely without the constraints of traditional brokerage platforms. For example transactions could take place globally, 24 hours a day, without relying on legacy clearing infrastructure. It could mean significant improvements in market efficiency, reduce settlement risk and include new financial products natively on-chain.
While Coinbase looks to break new ground in American markets, other jurisdictions are already operating. Rival exchange Kraken has launched tokenized stock trading for non-U.S. customers through its partnership with Swiss-based Backed Finance. For example, tokenized versions of Apple and Tesla stock, bAAPL and bTSLA respectively, are live pioneering examples of tokenized equities executed issued on the Solana blockchain, backed by 1:1 real shares held in custody, and tradeable with no minimum investment size and operate legally under global regulatory frameworks with blockchain flexibility, and 24/7 trading.
Europe is ahead of the curve on regulation. The EU’s MiCA framework was fully implemented as of 2024, providing legal clarity for tokenized securities across 27 member states. In Asia, Hong Kong is piloting tokenized gold, bonds, and equities under regulatory supervision. These jurisdictions are showing that comprehensive tokenization frameworks can unlock innovation while still preserving investor protection and market integrity.
Tokenized securities may require broker-dealer registration, SEC exchange approval, and compliance with the Investment Company Act. Since, Coinbase is not currently licensed as a broker-dealer, it may need a partner or entirely new structure to support these offerings legally.
There are also questions about liquidity. The World Economic Forum has identified low secondary market trading volumes and lack of standardization as persistent challenges in real-world asset tokenization.
While the tech stack can actually enforce compliance rules directly within smart contracts using standards for Real World Assets (RWA) like ERC-3643, adoption of these instruments will depend on regulators aligning globally and investors gaining trust.
If the U.S. and EU formalize tokenized security frameworks, capital will flow toward platforms offering speed, access, and interoperability, leaving slow movers behind. Companies should be exploring how to integrate tokenized equities into their product roadmaps while remaining compliant. NCFA and its members can play a leadership role in what responsible tokenized finance, launch educational initiatives, and collaborate with global infrastructure providers. At the of the day, tokenized assets are poised to become a competitive advantage or missed opportunity.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto | March 18, 2025

On June 17, 2025, a watershed moment for digital finance and crypto with the U.S. Senate passing the GENIUS Act, bipartisan 68-30 vote, establishing the country’s first federal regulatory framework for stablecoins. This legislation is the most significant digital asset policy breakthrough to date in the United States.
The GENIUS Act stands for 'Guiding and Establishing National Innovation for U.S. Stablecoins'and lays out clear rules for the issuance, required reserves, transparency, and oversight of U.S. dollar backed stablecoins. It's expected to boost financial innovation in America by providing a coherent national policy to streamline the governance patchwork created by state-to-state rules. The stablecoin market has now surpassed $260 billion in total value (up about 22% in 2025 alone), and is growing rapidly with rising institutional demand.
As reported by WSJ, Senator Cynthia Lummis (R-WY, one of the bill's key sponsors) said:
“This is the first step in establishing trust, protecting consumers, and ensuring the dollar remains the global standard for digital finance,”
The bill outlines strict guardrails for stablecoin issuers to prevent another collapse like TerraUSD while ensuring stability, liquidity, and auditability:
The GENIUS Act delivers some legal clarity to a sector long operating under ambiguous guidance from regulators.
Notably, the issuer of USDC, Circle saw its pre-IPO share price boost nearly 10% on the news, rising from $31 to over $160 as investor confidence rebounded. The company’s CEO Jeremy Allaire explained the bill as “the foundation of dollar dominance in the digital era.”
The bill is still not without some controversy as critics flagged the exclusion of President Trump from the conflict of interest restrictions - seen as politically motivated and related to the Trump family's interests and ties to private stablecoin ventures.
The bill now moves to the House of Representatives to be reconciled with the STABLE Act, and then once approved in both chambers the bill would be sent to President Trump for signing the first major federal stablecoin bill into law.
Will Canadian regulators follow with similar national standards for fiat-backed digital assets? As OSFI and FINTRAC review their guidance, Canadian fintechs operating in cross-border payments, custody, and token issuance will begin to face rising pressure to align with U.S. rules or risk falling behind in market access and credibility. The global sector is consolidating quickly and Canadian innovators must determine whether or not to build on this momentum with their own regulatory clarity.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Open Banking | June 17, 2025

Today at Toronto's Open Banking Expo, the Canadian federal government says they will introduce the long delayed open banking legislation 'at the earliest opportunity'. The Financial Consumer Agency of Canada (FCAC) responsible for implementing and regulating Open Banking in Canada confirmed that Ottawa remains committed to building the infrastructure for consumer-driven banking, despite momentum stalling after a Spring without a federal budget or any kind of legislative update.
Open banking allows Canadians to securely share their financial data with apps and services outside their traditional banks. Instead of screen scraping which is a risky process where users give third parties their login credentials for use on their behalf, open banking would give users a more control over what data is shared, with whom, and for how long.
In December 2024, Canada announced that open banking would be delayed until 2026. Now, according to the Department of Finance, the remaining parts of Canada's Open Banking Framework will be introduced as soon as possible (not a specific date or deadline). This includes the process for accrediting service providers, establishing common rules for data access, and creating a public registry.
The FCAC is preparing the groundwork by developing a public registry of accredited fintech firms and collaborating with Finance Canada to finalize operating rules, but let's be honest here. Without the final legislation, the FCAC is limited in what it can do.
While Prime Minister Mark Carney and the Liberals returned with a minority government, open banking unfortunately wasn't included in the party's platform, and given the delays following the Spring 2025 election and absence of a Spring budget, more delays were expected despite advocates remaining optimistic given the change in Canada's leadership and need to improve productivity and economic strength.
The National Crowdfunding & Fintech Association of Canada (NCFA) believes that consumer-driven finance is a key milestone for driving innovation, competition, and financial inclusion in financial services. NCFA's Executive Director/CEO, Craig Asano said:
“Consumer-driven banking is not just a policy item, it’s critical infrastructure for unlocking productivity and creating an ecosystem that works better for consumers and fintech innovators. Canada cannot afford another year of delay.”
While some fintechs and financial institutions have gone ahead and prepared for open banking the best they can ahead of final legislation, others are waiting for clarity from the Canadian government before moving forward, especially considering there have been many years of delay.
Open Banking could transform Canada's financial sector, making it easier for consumers to access improved products and services. It would also improve competition by enabling qualifying fintech firms to connect directly to consumer data in a secure and regulated way.
However, simply saying that Open Banking will be implemented 'as soon as possible' without committing to a specific date, Canada continues to fall behind other jurisdictions of its peers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Stablecoins | June 17, 2025

Image: Freepik/rawpixel.com
Retail giants Amazon and Walmart are exploring the idea of launching their own stablecoins to reduce payment processing costs and gain more control over transactions, according to a report by the Wall Street Journal. This could tip the balance toward merchant-controlled financial systems and impact how value is transferred in the digital economy.
Currently card networks like Visa and Mastercard charge merchants high fees for purchase transactions. By using stablecoins pegged to the U.S. dollar, retail companies like Amazon and Walmart could build their own payment systems, bypassing legacy rails and retain more transactional value on their platforms. However any stablecoin plans depend on whether or not the proposed Genius Act becomes law in the United States.
As reported by Reuters, stablecoins are gaining interest among corporations that want to issue or use private forms of digital cash. The goal isn't to create a new form of money, but to develop closed financial ecosystem for transactions that are faster, cheaper, and programmable than legacy payment systems used today.
Retailers aren't the only ones interested. PayPal has already launched its own stablecoin, PYUSD, which is issued through a partnership with Paxos, a licensed trust company. Amazon and Walmart could follow a similar route or choose to build in-house capabilities.
According to Crowdfund Insider, the Genius Act is currently in front of the Senate and is expected to have a floor vote on June 18 which if passed would become the first American law to set national standards for fiat-backed digital currency. Stablecoins would require 1:1 reserve backing, clear audit rules, and strong consumer protections.
The Genius Act is designed to add clarity and prevent abuse while encouraging legitimate innovation. Only regulated entities can issue stablecoins and limits will be in place for the type or size of non-financial companies that can use them. Analysts at Bernstein have warned that the Genius Act could make it “prohibitive” for retailers to issue stablecoins directly without working with financial partners.
As Business Insider explains, the bill would give federal regulators oversight of reserves, mandate asset freezes under court orders, and block big tech companies from embedding coins too deeply into their platforms. The law also prevents stablecoin issuers from tying coins to commercial loyalty programs or e-commerce activity without approval.
If Amazon and Walmart did in fact launch their own stablecoins, merchant-led payment systems could reduce friction for consumers and suppliers while creating competitive pressure on Canadian banks, fintechs, and card networks.
Global payment flows could also be affected if retailer stablecoins are used for remittances or global vendor payments. Walmart already has a fintech joint venture with Ribbit Capital in the United States to create a fintech startup Hazel (also called 'One'), and experience with blockchain patents. Amazon has explored using external stablecoins such as USDC for settlement.
Whether they issue directly or partner with licensed issuers, the genie is almost out of the bottle and moving beyond theoretical. Consider it a live business option just waiting for regulatory clarity.
Canada’s fintech ecosystem should monitor these developments closely. U.S. regulatory clarity could prompt other jurisdictions to act, and consumer expectations will grow as giant retailers redefine what payments in the near future look like.
It may create opportunities for Canadian fintechs to partner with global brands or expand the merchant-focused rails to compete with card-based infrastructure, ultimately pushing to modernize domestic payments. Stablecoins come with some real risks around consumer protection, monetary policy, and financial stability, so it's essential to get the balance right.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
