




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 11, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure

On May 8 2026, BlackRock filed SEC documents for OnChain Share structures tied to Treasury and liquidity products, expanding its push into tokenized fund infrastructure connected to stablecoin reserve management and digital cash markets. The filings outline blockchain based ownership records linked to regulated transfer agency and identity systems, showing how large asset managers are starting to integrate tokenized fund mechanics into institutional cash and collateral infrastructure.
BlackRock is preparing two tokenized money market style fund structures aimed at digital asset users.
1. The BlackRock Daily Reinvestment Stablecoin Reserve Vehicle is the cash and Treasury product. The SEC filing says the fund invests 100% of total assets in cash, Treasury bills, notes and other U.S. Treasury obligations with remaining maturities of 93 days or less, plus overnight repurchase agreements secured by Treasuries.
2. BlackRock is adding an OnChain Share class to an existing Treasury liquidity fund. The OnChain Shares are the tokenized ownership format, not a separate asset by themselves. Securitize Transfer Agent, LLC maintains the official ownership record for those shares on public blockchains, while offchain records connect wallet addresses to shareholder identity information.
Because BlackRock isn't selling speculative token exposure here. It's building regulated cash management infrastructure that can connect to blockchain based workflows. BlackRock is preparing tokenized money market funds for investors who hold cash in stablecoins rather than bank accounts. Stablecoin users need places to park digital dollars. Asset managers want the fee pool behind that cash. Tokenized Treasury funds sit between both sides.
The filing says Securitize Transfer Agent, LLC maintains the official ownership record for OnChain Shares on public blockchains used by investors. BlackRock also keeps offchain records that connect wallet addresses to shareholder identity information. It gives investors blockchain based fund records, but it keeps regulated transfer agency, identity controls, and fund administration in place. This isn't decentralized finance replacing Wall Street. It's Wall Street absorbing useful blockchain mechanics into regulated products.
Stablecoins are becoming a large digital cash market, and tokenized Treasuries give that market a yield and collateral layer. Stablecoin issuers, exchanges, custodians, market makers, wallets, and trading desks all need safer liquid assets that can move more efficiently across blockchain based systems.
Tokenized Treasury funds can serve as reserve assets, trading collateral, treasury tools, and liquidity instruments. BlackRock’s timing also follows the growth of BUIDL, its tokenized Treasury fund with Securitize (tokenized U.S. dollar institutional liquidity fund).
The market is still small compared with traditional money markets, but it is growing quickly enough to matter. RWA.xyz tracks tokenized real world asset markets, including tokenized Treasuries across public blockchains. BlackRock’s BUIDL fund has grown to roughly $2.5B in assets.
Bloomberg reported that BlackRock’s second filing relates to a digital share class tied to the roughly $6.1B BlackRock Select Treasury Based Liquidity Fund. BlackRock is effectively applying tokenized share mechanics to an existing cash management product, not only creating a new stablecoin reserve vehicle.
The first affected group is firms that hold, issue, move, or manage digital dollars, such as stablecoin issuers, exchanges, custodians, crypto prime brokers, market makers, wallet providers, and institutional treasury desks. They need liquid reserve assets, reliable collateral, fund records that can connect to wallets, and regulated products that reduce counterparty risk.
The second affected group is traditional finance including transfer agents, custodians, fund administrators, broker dealers, banks, and asset managers. If tokenized fund shares become useful collateral, these firms will need systems that can reconcile blockchain records with regulated books and records.
The winners are likely firms that control distribution, custody, transfer agency, identity, compliance, and liquidity. That is why BlackRock’s filing matters. Tokenization may look like a technology story, but the business model is about control over the digital cash stack.
If stablecoins become the payment layer and tokenized Treasuries become the reserve and collateral layer, the companies that manage those Treasury products gain a powerful position in digital finance.
The institutional version of crypto looks very different from the early pitch. The first story was about removing intermediaries. The version large institutions are building keeps many intermediaries in place. Regulated funds, known investors, transfer agents and custodians still matter. What changes is the recordkeeping and settlement infrastructure underneath. Tokenization is becoming more important because it is being rebuilt in a form large pools of capital can actually use.
Nothing else is confirmed until BlackRock files or announces it. But this does not look like a one time product test. BlackRock already has BUIDL with Securitize. It is now preparing a stablecoin reserve vehicle and OnChain Shares for another Treasury liquidity product. If demand keeps growing, more tokenized share classes, cash products, collateral tools, and stablecoin reserve products could follow.
If tokenized U.S. Treasury products become core infrastructure for stablecoins, trading platforms, treasury desks, and cross border settlement, Canadian firms may plug into U.S. dollar blockchain systems before comparable domestic options mature. That affects where liquidity forms, how products are built, who controls custody relationships, and how payments infrastructure connects to tokenized markets.
For regulators, the issue is market structure. Canada will need clear rules for custody, investor identity, redemption rights, transfer agents, operational risk, and how tokenized fund records fit with securities law.
Whether stablecoin issuers use these funds as reserve assets? Whether broker dealers and custodians accept tokenized fund shares as collateral? Whether regulators clarify how blockchain based ownership records fit with securities and custody rules?
For Canada, the practical question is execution. Firms do not need to wait for a perfect domestic model. They can start mapping where tokenized cash could affect treasury operations, settlement, collateral, custody, and reporting. The risk is that the most useful infrastructure gets built elsewhere while Canada treats the topic as a narrow crypto market story.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 8, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Regulation And Policy, Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Cybersecurity Fraud And Financial Crime

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026).
Reduced margin rules shape leverage, dealer inventory financing, and how quickly exposure can build when markets heat up. Keeping crypto funds out of reduced margin leaves higher friction on leveraged crypto fund exposure even as crypto and tokenized market infrastructure moves closer to mainstream rails.
Canada’s stablecoin framework is moving from legislation into implementation timing. Issuers, custodians, exchanges, payment firms, and banks should plan for a 2027 rulebook while watching how reserve assets, redemption rights, supervision, and payment use cases get defined. See Canada’s First FI Issued CAD Stablecoin Launches and Stablecoins Split Into Issuance And Service Layers
Claims management is moving into a tougher conduct and perimeter review. Firms using lead generation, social ads, outsourced claims workflows, or high volume complaint models need clean consent, fair pricing, clear authority, and evidence that customers understand what they are signing.
Climate disclosure is moving from delayed implementation toward formal rollback. Public companies, reporting platforms, auditors, and ESG data providers should watch the proposal text, because the next decision point is whether climate risk disclosure becomes narrower, materiality driven, or removed from SEC rule requirements.
May 6, 2026, Canada and South Korea
Stablecoin adoption won’t only depend on reserves, licences, and payment use cases. It will also depend on how issuers protect minting, burning, settlement authority, custody permissions, and administrative controls as quantum risk becomes an infrastructure planning issue.
Regional banks are looking for third party digital asset infrastructure instead of building it from scratch. For Canadian credit unions, regional banks, and bank technology providers, stablecoins and tokenized deposits are becoming a bank distribution question, not just a crypto platform product.
Tokenized securities are moving into issuer services and transfer agency. The next control point is not only trading. It is who manages shareholder records, corporate actions, voting, dividends, custody links, and settlement between public companies and investors.
This is an early bank participation signal, not a final product launch. European banks are expanding a shared euro stablecoin effort before formal updates expected later in the year. For fintechs and payment firms, the read through is practical: euro stablecoin access may develop through regulated bank networks, not only crypto native providers.
Tokenized securities are moving into DTC’s production roadmap. That changes the question from whether tokenized assets can exist to whether brokers, custodians, issuers, and trading venues can plug tokenized ownership into existing post trade infrastructure without weakening rights, controls, or settlement discipline.
MiCA is turning stablecoin issuance into regulated service infrastructure. Circle now has a clearer European pathway for custody and transfer services tied to USDC and EURC, which raises the bar for stablecoin issuers competing on compliance, distribution, and institutional access.
Canada’s real time payments window is now coming into view. Banks, PSPs, fintechs, fraud vendors, and treasury teams need to prepare for testing, phased onboarding, ISO 20022 data, instant settlement, and new fraud controls before launch.
Canada’s payment access model keeps opening beyond incumbent financial institutions. Fintechs, PSPs, banks, and payment infrastructure providers should track which firms gain a formal seat inside payment system governance because direct participation can affect product design, compliance readiness, and competitive timing around modernized payment rails.
Stablecoin settlement is moving into Canadian payment operations, not just crypto trading. Wealthsimple now has a live route to test USDC settlement with Visa Canada, while banks, PSPs, wallets, and regulators watch how on chain settlement fits inside existing card network obligations.
Stablecoin card infrastructure is moving closer to mainstream payment networks. Canadian fintechs, issuers, and payment providers should pay attention to who controls issuance, settlement, compliance, and customer access when tokenized money connects to everyday card spending.
Banks, insurers, fintechs, regtech vendors, and AI providers operating in Europe need clearer compliance planning around governance, documentation, model oversight, and content labeling requirements. The updated timeline gives firms more preparation time while confirming the EU still intends to enforce formal AI accountability rules across regulated industries.
Private credit is evolving from private market growth story to global stability watchlist. Banks, insurers, fund managers, platforms, and risk vendors should expect more scrutiny on exposure mapping, borrower quality, valuations, leverage, liquidity terms, and private ratings.
The proposal would change the disclosure rhythm for U.S. public companies. Issuers may gain lower reporting costs and more planning room, while investors, analysts, and data providers face less frequent mandated information and a bigger premium on interim signals, voluntary updates, and market surveillance.
The findings give Canadian banks, fintechs and infrastructure operators a useful test for shared identity and cloud dependencies. Strong current availability does not resolve the risk created when authentication, payments and outsourced technology depend on a limited number of providers without proven alternatives for prolonged disruptions.
It seems like we say this every week but the competitive gap between fintechs is starting to widen. While there's still opportunities it's less about product design and more about infrastructure access, regulatory positioning, distribution control, and operational execution. Fintechs aren't just launching apps faster, but are embedding themselves deeper into payment rails, compliance systems, tokenized market infrastructure, AI governed workflows, and regulated distribution channels. Canada still has room to compete, but the advantage is increasingly going to operators that can execute inside regulated systems at scale while keeping costs, trust, and customer experience under control.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 8, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization
Image: Magnific
On May 7 2026, Bitwise announced its first tokenized fund through a partnership with Superstate. Bitwise will become investment manager of the Superstate Crypto Carry Fund, which will be renamed the Bitwise Crypto Carry Fund.
The fund keeps the USCC ticker, smart contracts, and token address, with the transition expected on June 1 2026. USCC has more than $267M in assets under management and targets yield from the crypto cash and carry trade, where futures prices trade above spot prices.
Bitwise is entering tokenized funds by taking over a live onchain product instead of launching from zero. Superstate will keep operating the infrastructure layer, including tokenized issuance and digital transfer agency services through FundOS. That separates investment management from onchain fund operations, which is exactly how institutional tokenized finance may scale.
Tokenized real world assets now exceed $30B globally, while tokenized US Treasuries have surpassed $15B, with the tokenized asset market projected to reach $18.9T by 2031.
Bitwise says it has $11B in client assets, more than 70 investment products, and serves more than 5,000 private wealth teams, RIAs, family offices and institutional investors, along with 21 banks and broker dealers. That distribution is key to scaling tokenized funds beyond only crypto native buyers. They also need access to wealth, advisory, and institutional channels.
Tokenization doesn't remove traditional financial roles, but rather it rebuilds them on new rails. Fund managers, transfer agents and distribution all still matter. The difference is that settlement, ownership records, and secondary utility can now run onchain.
If US asset managers and infrastructure firms continue pairing regulated products with onchain fund administration, Canadian fund managers, exempt market platforms, dealers, and policymakers need to decide where tokenized funds fit into Canadian capital formation and investor access.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 7, 2026 | NCFA Insight | Payments And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech, Open Banking Open Finance And Data Sharing

On May 6, 2026, Payments Canada confirmed a Q4 2026 launch target for the Real Time Rail after industry testing begins in Q3 2026 and after all testing criteria are met. The Real Time Rail (RTR) isn’t only about faster payments anymore. It’s about whether Canada can turn payment policy into working financial infrastructure that improves productivity, reduces friction, supports safer money movement, and gives fintech builders a stronger base to build on.
Payments Canada owns and operates Lynx, ACSS, and modernized RTR. Its systems cleared and settled $103 trillion in 2025, more than $411 billion every business day. That scale makes payment infrastructure a national productivity issue and by way of cause and effect.
When settlement runs slowly, capital sits idle. When payment data is thin, reconciliation gets messy. When fraud controls fall behind, trust takes the hit. And when access stays too narrow, competition suffers.
Canada has talked about faster payments for years. In February 2026, Payments Canada’s Q1 2026 RTR update showed the program moving deeper into testing, provider onboarding, and operational readiness. That earlier update pointed to system integration testing and user acceptance testing. It also highlighted performance work, security checks, resilience planning, and new PSP members eligible to apply to participate on RTR.
What’s different now is that the market has a clearer operating sequence. Industry testing starts in Q3 2026. Launch targets Q4 2026, after testing criteria are met. Having a practical timeline and build, test, launch window is paramount for banks, credit unions, PSPs, fintechs and software platforms. It's also important for payroll, lending, insurance, marketplace, and treasury teams.
Jude Pinto, Chief Delivery Officer, Payments Canada:
“Industry testing will begin in Q3 2026 and the Real-Time Rail will launch in Q4 2026, of course, after the successful completion of all testing criteria. This will ensure the system remains safe, secure and resilient in a live environment.”
The Q4 launch target isn’t that far off. Companies that want to benefit from RTR need to start preparing now. Settlement operations need review. Fraud monitoring needs stress testing. Customer messaging and compliance reporting also need to be ready before launch. So do liquidity planning and partner dependencies.
For fintech operators, this is where the real work starts. Access to RTR will matter, but access alone won’t be enough. Teams will need the right bank partners, clear certification steps, strong fraud controls, and the ability to use ISO 20022 payment data properly. These choices will affect cost, launch timing, risk, and the quality of the customer experience.
RTR also lands inside a wider digital finance buildout. Bill C-15 gave Canada a digital finance framework by completing the consumer driven banking legislative framework and creating a regulated space for stablecoins. Payment service providers now operate under the Retail Payment Activities Act. Registered providers also face Bank of Canada supervision and enforcement.
That combination changes the operating environment. Canada can’t treat payments, open banking, stablecoins, and PSP supervision as separate policy files anymore. They’re starting to connect. A consumer could eventually give data consent through open banking. That same consumer could fund an account through faster payment rails. They could receive payouts in real time. Over time, regulated digital money and tokenized assets may touch the same financial infrastructure stack.
Each layer needs trust. Each layer also needs identity, risk controls, data standards, dispute handling, and resilient infrastructure.
This is where Canada’s challenge gets harder. Passing the law is only step one. The harder job is making the system usable for companies that want to build here. Accreditation, RTR access, PSP supervision, bank partnerships, and compliance rules all need to work together.
The rules need to protect users without creating a maze that slows responsible firms down. If that balance fails, fintechs will spend too much time getting through the system and not enough time improving it. If all lines up well, Canada can turn faster payments into more competition.
Payments Canada links RTR to security, financial crime, and fraud. Faster payments leave less time to catch scams, especially when payments are instant and irrevocable. Canada needs speed, but it also needs trust.
RTR will support 24/7 instant payments, ISO 20022 messaging, and centralized fraud detection. Fraud control can’t live only in compliance. It has to show up in onboarding, transaction monitoring, customer warnings, and dispute handling.
For founders and operators, fraud control affects customer experience. Companies that stop scam patterns earlier, reduce false positives, and protect users without slowing down good transactions will have a stronger product than firms that only promise speed.
The remaining time in 2026 is important:
After years of delay, Canada’s Real Time Rail is now a live execution test for Canada's digital finance agenda. The launch target gives the market something to plan around. The bigger story is how RTR connects with PSP supervision, Bill C-15, open banking, stablecoins, fraud enforcement, and competition policy.
The opportunity is real, and so is the operating burden. If all goes according to plan, Canada can get better financial infrastructure, more productive payment flows, stronger fintech competition, and safer digital financial services.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 7, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, Payments And Money Movement, Financial Inclusion And Consumer Protection
On May 7, 2026, Spendsafe announced a non binding letter of intent with 1587815 B.C. Ltd. for a proposed reverse takeover that could list Spendsafe on the TSX Venture Exchange, subject to exchange approval and other closing conditions. This isn't an IPO. It is an early public listing transaction that still needs due diligence, a definitive agreement, and corporate, regulatory, and TSXV approvals.
Important to note that a letter of intent doesn't complete a listing. It gives the market a proposed structure and a reason to watch and evaluate. For Spendsafe, the company is trying to turn youth financial education into a regulated payments product, not a standalone lesson app.
Spendsafe launched in December 2025 combines a Mastercard enabled prepaid card, parent controls, and AI enabled coaching for children and teens aged 6 to 18. Peoples Trust Company acts as issuer and Berkeley Payment Solutions acts as program manager. That gives the platform a payments stack behind the learning experience. The product's promise is turning everyday transactions into teachable moments.
That is where the model gets more interesting than another allowance card. Financial literacy often fails when it stays abstract. A youth financial education platform with card, parent dashboard, and coaching layer can connect spending, saving, chores, and money habits to real behaviour.
Smaller fintechs still need capital market access, but the IPO bar remains high. A proposed reverse takeover (RTO) can give a growth company a public listing route via merger without a traditional offering process. Public investors still need proof of product demand, disciplined governance, clear disclosure, and a credible use of capital.
For a youth finance platform, trust carries extra weight. Parents need control. Young users need safe access. Partners need compliance confidence. Regulators will care about privacy, marketing, payment oversight, and how AI coaching interacts with children and teens. A public market structure can help only if it brings better disclosure and stronger accountability.
Spendsafe also says the proposed listing could support product investment, partner integrations, and broader North American growth goals. The company isn't just raising attention around an app. It's trying to build a payments and education category that depends on distribution partners, measurable outcomes, and evidence that the product improves how families handle money.
Prior to any listing closing, Spendsafe still has to prove that young users engage, parents stay involved, partners see value, and the education layer produces results worth measuring. Public markets can fund growth, but they also expose weak assumptions fast. That’s healthy if the company can show real adoption and clean governance.
Payments infrastructure can open the door, but trust keeps it open. Can a TSXV public listing structure help Spendsafe turn youth payments, AI coaching, and financial education into a trusted Canadian growth category?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 6, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Financial Inclusion And Consumer Protection
On May 6, 2026, Canadian fintech based in Mississauga founded in 2015 RemitBee announced a collaboration with Visa Canada to add Visa Direct to its Canadian cross border payments platform. RemitBee serves more than 350,000 users and covers 190+ countries, 150+ currencies, and 200 payment systems. The value is straightforward. More Canadian users can send money abroad faster, across more payout options, with fewer delays at the last mile.
Visa Direct gives RemitBee access to real time payouts to eligible bank accounts, digital wallets, and Visa cards worldwide.
The announcement cites Statistics Canada data showing that Canadians sent more than $26.7 billion CAD in remittances abroad in 2025. That outbound flow supports families, education, healthcare, small businesses, and emergency needs across global corridors. For many users, a failed or delayed transfer isn't just an inconvenience but a cash flow problem.
RemitBee’s platform isn't just for consumer transfers. The company positions itself as a payment infrastructure hub for credit unions, regional remittance operators, and financial partners that want access through one integration. Visa Direct adds global reach, faster delivery, and established risk and security controls. That gives a Canadian fintech more credibility in a market still dominated by larger foreign platforms.
Cross border payments are at the intersection of trust, compliance, global coverage, FX transparency, fraud control, and payout reliability. A fintech can win the customer relationship only if the infrastructure works behind the scenes. Fast onboarding means little if the payout breaks. Low fees mean less if users cannot see total cost or delivery status.
Canadian fintechs looking to compete in remittances requires more than just a lower fee. Firms need trusted rails, strong compliance, clear pricing, and dependable payout coverage. They also need partners that can help them reach harder markets without rebuilding every corridor from scratch.
The collaboration also points to a wider Canadian payments issue. Canada has strong payment talent, but global money movement still depends heavily on international networks, foreign platforms, and specific global relationships. Homegrown fintechs can compete when they combine local trust with global payout reach. That’s where RemitBee’s Visa Direct integration can stand out.
For investors and operators, cross border payments are becoming an infrastructure and distribution competition. Companies that own more of the workflow can build deeper relationships with immigrants, small businesses, freelancers, and globally connected households. Conversely, firms that only represent the front end of the transfer risk losing margin and loyalty to platforms with better reach.
Can Canadian fintechs use trusted global rails and local customer relationships to win cross border money movement before larger platforms own the full remittance workflow?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 6, 2026
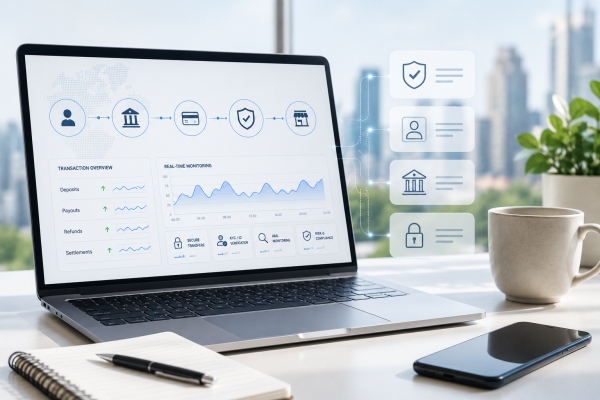
Ontario's regulated online casino market processes billions of dollars a year. Behind every deposit and withdrawal sits a stack of fintech infrastructure that rarely gets discussed outside payment-industry circles: account-to-account rails, payment facilitators, KYC verification layers, AML monitoring, and bank-connectivity protocols.
This article is not a gambling guide. It uses Ontario iGaming as a case study to show how Canadian payment methods, PSPs, and risk controls work in a live, high-volume digital environment.
Few Canadian verticals compress so many fintech challenges into a single transaction flow. An online casino deposit requires instant consumer authentication, real-time bank connectivity, merchant-risk assessment, and regulatory compliance — all within seconds.
A consumer-facing guide to casinos that support Gigadat illustrates this compression well: users see a simple cashier screen with payment options, while behind it sits a multi-layered processing chain involving banks, facilitators, compliance checks, and settlement queues.
The scale of this market reinforces its relevance for payment professionals. According to iGaming Ontario's 2024–25 annual report, the regulated market recorded $82.7 billion in total wagers and $2.9 billion in total gaming revenue across roughly 50 active operators.
Key takeaway for fintech readers: iGaming is not just a gambling story. It is one of the few Canadian digital verticals where instant payments, high-risk merchant classification, strict AML obligations, and consumer trust expectations collide in every single transaction.
Ontario online casinos generally rely on a handful of payment categories. The mix varies by operator, licensing conditions, and compliance setup, but the core options fall into recognizable groups.
Interac e-Transfer is the backbone of most Ontario casino cashier flows. According to Interac's FAQ, e-Transfer lets Canadians send money through online banking, with participating financial institutions handling the transfer through established secure banking procedures. Processing usually happens in minutes, though it can take up to 30 minutes depending on the bank or credit union.
For fintech professionals, the important distinction is this:
| What the consumer sees | What happens on the back end |
| "Pay with Interac e-Transfer" | Bank authenticates user, routes funds through Interac rails |
| Instant confirmation | Settlement may still be pending between institutions |
| Simple email or text notification | The money itself travels through secure banking channels, not via email |
Interac e-Transfer functions as a bank-account payment rail, not an e-wallet. That distinction matters for PSPs, compliance teams, and anyone building deposit flows for Canadian merchants.
Gigadat is one of several Canadian payment facilitators that sit between the consumer's bank and the merchant. Gigadat's Pay-Ins page describes its role around local online and mobile banking options, including Interac e-Transfer and Interac e-Transfer Request Money.
In practice, a facilitator like Gigadat can handle:
The consumer may never see Gigadat's name at all. Or, depending on how the operator integrates the service, Gigadat may appear alongside Interac branding in the cashier interface.
Beyond Interac and payment facilitators, Ontario casinos may accept:
Each method carries different implications for settlement speed, chargeback risk, fraud exposure, and compliance overhead.
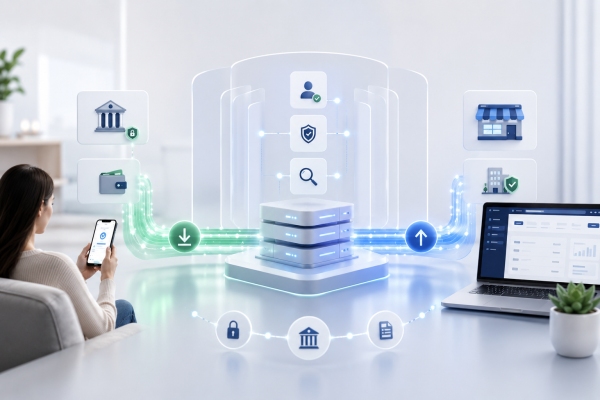
Understanding Gigadat's role requires separating the pay-in (deposit) path from the payout (withdrawal) path. The two operate differently, and the user experience can diverge significantly.
When a user deposits funds, the facilitator connects the user's bank session to the merchant's receiving account. The process typically involves:
From the user's perspective, the deposit feels instant. From the merchant's perspective, there may be settlement delays depending on the banking chain involved.
Withdrawals follow a different logic. Gigadat's Pay-Outs page explains that Interac e-Transfer payouts can let merchants send money to consumers using an email address or mobile phone number rather than collecting bank-account details.
This distinction matters for two reasons:
A common misconception: "instant withdrawal" often refers to the speed of the payment rail after the merchant releases the funds — not to the total time from withdrawal request to money in the user's account.
Consumer payment guides often collapse back-end distinctions into a simple label such as "Gigadat" or "Interac." In reality, both names can appear in the same transaction: Interac as the consumer-facing rail, Gigadat as the facilitator managing the merchant side. This layered structure is standard in Canadian digital payments but rarely visible to end users.
Fast payment UX does not remove compliance obligations. If anything, the speed of account-to-account transfers increases the pressure on operators and PSPs to build robust monitoring systems.
The regulatory landscape for Canadian PSPs shifted significantly in 2025. The Bank of Canada announced that supervision under the Retail Payment Activities Act (RPAA) came into effect on September 8, 2025, with close to 1,500 PSPs under oversight for risk-management and safeguarding obligations.
What this means in practice:
| RPAA requirement | Relevance to iGaming payments |
| Operational risk management | PSPs processing casino transactions must demonstrate controls for fraud, outages, and settlement failures |
| Safeguarding of funds | User deposits in transit must be protected, not commingled |
| Incident reporting | PSPs must report material disruptions to the Bank of Canada |
For fintech founders and investors, the RPAA framework changes the compliance baseline for any Canadian payment service — not just those serving iGaming.
On the merchant side, FINTRAC's casino guidance outlines how casino-related entities are treated under Canada's proceeds-of-crime and terrorist-financing legislation. Entities conducting and managing gaming activities carry specific reporting responsibilities.
Key obligations in this context generally include:
These requirements exist independently of the payment method used. Whether a user deposits via Interac, card, or bank transfer, the casino's AML obligations remain the same.
A deposit can arrive in seconds. A withdrawal may take days. The gap is almost never about the payment rail itself. It typically reflects:
This distinction is critical for anyone building or evaluating payment products: the rail is only one layer in the total transaction experience.
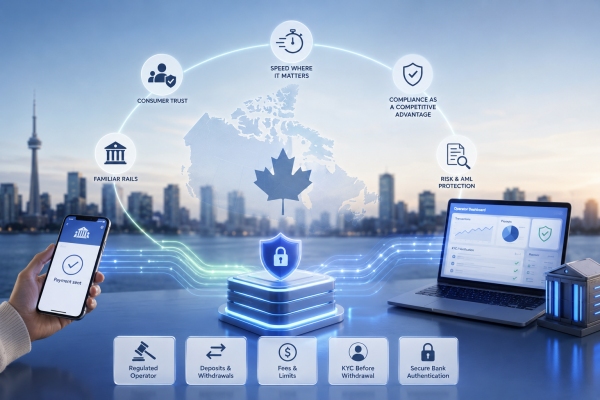
Ontario's iGaming market is a stress test for Canadian payment infrastructure. The lessons extend well beyond gambling.
Consumer trust depends on familiar rails. Interac e-Transfer succeeds in casino cashiers for the same reason it succeeds everywhere else in Canada: users recognize it, trust it, and know how it works through their own bank. Any fintech building a consumer-facing payment flow in Canada should consider how much of this familiarity it can leverage.
The pay-in/payout asymmetry is universal. Deposits tend to be instant; withdrawals tend to be slower. This pattern repeats across marketplaces, gig-economy platforms, insurance payouts, and lending products. The iGaming vertical simply makes the friction more visible because users expect fast returns.
Compliance is now a product feature, not just a cost centre. Under the RPAA supervision environment, PSPs that can demonstrate robust risk management may gain a competitive advantage over those still treating compliance as an afterthought.
For fintech founders: iGaming payments reveal the tension between speed and safety more clearly than almost any other Canadian digital vertical. The operators who handle it well offer a template for high-risk merchant processing in other sectors.
While this article focuses on infrastructure, the underlying payment lessons apply to anyone using digital payment methods in Canada — not only in casinos.
Before trusting any online payment flow, consider checking:
Ontario's iGaming market matters to fintech professionals not because of the casino content, but because of what it reveals about the state of Canadian payment infrastructure.
Account-to-account payments work. Interac e-Transfer has become the default consumer expectation for instant domestic transfers. Payment facilitators like Gigadat demonstrate how intermediaries can bridge bank rails and merchant platforms without requiring users to share sensitive financial details. The RPAA now holds PSPs to formal supervisory standards. And AML obligations ensure that fast rails do not bypass necessary safeguards.
For anyone building, investing in, or regulating Canadian fintech products, the iGaming payment stack is a compact, high-volume example of where Canadian digital payments stand today — and where they are heading next.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016