




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


March 5, 2026 | NCFA Feature | Capital Markets And Policy And Regulation
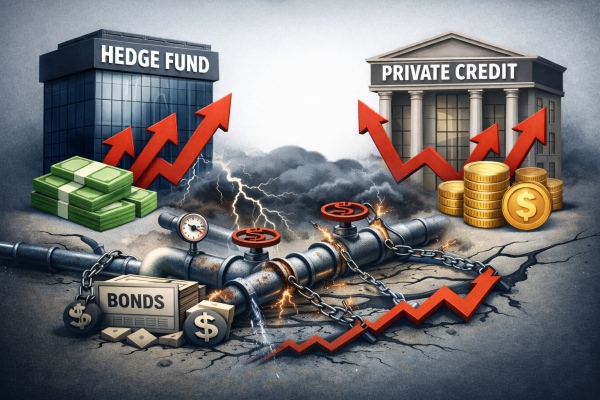
On March 4 2026, Bank of Canada Governor Tiff Macklem discussed how non bank finance can amplify stress in debt markets during remarks at the Global Risk Institute in Toronto. He pointed at two pressure points that matter for Canada right now:
Macklem puts a clear number on hedge fund demand in Canada:
"In Canada, they purchase up to 50% of Government of Canada bonds sold at auction and account for a big portion of secondary market trading.”
Hedge funds aren't just active in Canada. Similar patterns show up across many major economies. Hedge funds now hold a significant share of government debt outside central banks and large institutions. When government bond markets become unstable, the effects spread quickly. Mortgage rates, business loans, and corporate borrowing costs all move with government bond yields, so shifts in that market ripple through the entire economy.
The Bank highlights the repo market because repo borrowing funds many leveraged bond trades. A repo (repurchase agreement), works like a very short term loan. An investor borrows cash and posts government bonds as collateral, then agrees to buy those bonds back a day or a few days later.
Macklem says many hedge fund bond positions rely on this type of borrowing and are often highly leveraged. The structure makes markets sensitive to sudden changes in funding conditions.
He explains that “globally, about half have an overnight maturity. And haircuts are low zero or negative more than 80% of the time.” If lenders raise collateral requirements or reduce lending, investors may need to sell bonds quickly to reduce leverage.
When several large investors unwind positions at the same time, liquidity can vanish and prices can fall sharply. Macklem points to past episodes where this dynamic played out, including the global dash for cash at the start of the pandemic, the United Kingdom gilt crisis in 2022, and stress in the United States Treasury market in 2023.
Macklem also focuses on private credit because transparency is more difficult than in public markets:
“The opacity of private credit means investors may not have enough information about the quality of loans held in their funds.”
If defaults rise and investors rush for exits, he warns that the strain can spill into public credit markets. Canada connects to this risk because Canadian institutions invest in private credit globally, and funding links can pull stress back into the regulated system through liquidity needs and cross border channels.
The Bank of Canada is also changing how it plans to conduct its repo transactions. In a market notice, the Bank says it will join the Canadian Collateral Management Service tri party platform for its domestic repo operations by early 2027. CCMS is a market utility launched by TMX Group and Clearstream that helps participants move collateral, manage substitutions, and automate settlement for repo trades.
The Bank also says it intends to clear its repo operations through the Canadian Derivatives Clearing Corporation once TMX completes upgrades to expand central clearing services. CDCC acts as a central counterparty that guarantees settlement if one side of a trade fails.
The goal is to support stronger collateral management, reduce counterparty risk, and encourage broader use of modern repo infrastructure in Canada.
More lending and market activity now happens via non-bank firms who often use short term funding that can tighten quickly, not just traditional banks. When that happens, pressure in debt markets can build fast. Canadian institutions need better visibility into funding conditions, leverage, and collateral movement across markets. Fintech companies that help banks monitor liquidity, collateral, and repo exposures in near real time can fill an important gap.
At the same time, stronger market infrastructure matters for Canada’s competitiveness. Investors and dealers gravitate to markets that settle trades smoothly and manage collateral efficiently, especially during periods of stress.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
March 5, 2026 | CIX Summit 2026

Image courtesy of CIX, Powered by Elevate, March 25, 2026
On March 4, 2026, CIX Summit confirms the 2026 summit agenda now live and tees up the March 25 Toronto event, with NCFA participating as a community partner.
The agenda puts investor founder connection at the center of the day, with an Investor Forum built for candid capital conversations and a Founder Forum focused on fundraising and scaling. It also includes Scale Beyond Borders with Global Affairs Canada and founders sharing practical market entry experience, plus Cracking the VC Code on funding strategies for women founders and how to navigate fundraising in today’s market.
CIX also spotlights this year’s Innovator of the Year fireside chat with Wealthsimple CEO and co founder Mike Katchen
CIX also names 14 Canadian startup award winners for 2026, which helps founders and investors see who CIX is already ranking as standout teams.
CIX confirms that on March 9 at 12:00 PM EST Meeting Exchange bookings become open (must be CIX Startup passholder, format is one to one). These meetings are for startups from pre-seed to growth capital, with investor types that include incubators, accelerators, angels, venture funds, corporate venture teams, and debt providers across major tech sectors.

NCFA is sharing a 20% community partner discount on CIX Summit passes for its community. Use CIXNCFA20 for 20% off. CIX runs on March 25, 2026 in downtown Toronto. CIX publishes ticket options and event logistics on its official page for CIX Summit 2026 ticket details and March 25 venue information.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 5, 2026 | NCFA Fintech Market Insight | Digital Assets And Policy And Regulation

On January 29 2026, at the joint SEC CFTC event in Washington titled CFTC SEC Harmonization U.S. Financial Leadership in the Crypto Era.
CFTC Chair Michael S. Selig’s remarks laid out a detailed US policy direction for crypto market structure. The speech goes past broad support for innovation and points to specific rule work on tokenized collateral, perpetual derivatives, software safe harbours, retail leveraged crypto trading, and event contracts.
SEC Chair Paul S. Atkins’ remarks support the same direction from the SEC side, which is part Project Crypto.
“Fragmented regulation in an integrated market is not a safeguard for investors so much as a source of confusion among them.”
That line from Atkins defines the problem. Unclear boundaries change how firms structure products, where they launch, and how much they spend on compliance before they can scale.
“Project Crypto recognizes that crypto markets span across our agencies’ respective regulatory boundaries.”
Selig starts from the point that crypto products don't fit neatly into older lines between agencies. Clearer lines are needed to cut the cost of operating in uncertainty.
“I have directed CFTC staff to develop rules to enable the responsible deployment of additional forms of eligible tokenized collateral.”
Eligible collateral is what a trading venue accepts to back positions. It decides how much margin traders need, how fast funds move, and how safely trades settle. If the CFTC allows more tokenized assets to count as eligible collateral, more crypto trading can happen inside regulated U.S. markets, but custody and collateral movement will need tighter controls and clearer proof that assets are protected and available when they are needed.
“The CFTC will use the tools at its disposal to onshore perpetual and other novel derivative products so that they can flourish across both centralized and decentralized markets, subject to appropriate safeguards.”
Perpetuals are a popular kind of crypto futures that many platforms offer outside the U.S. If U.S. rules start allowing them in a regulated way, more trading, market making, and new product builds can move onshore. That would also make it harder for offshore exchanges to keep growing just because the U.S. has no clear legal path today.
“The CFTC will explore ways in which the agency can encourage innovation in software development and support builders as they work toward product market fit, including by assessing whether an innovation exemption may be appropriate in certain circumstances.”
This targets a hard issue in crypto regulation. Wallets, interfaces, and on chain software do not fit cleanly into rules built around centralized intermediaries. If the CFTC creates clearer room for software development and early stage testing, legal uncertainty will be reduced for teams building core infrastructure.
“As part of this harmonization effort, we will examine whether substituted compliance can achieve equivalent or better regulatory outcomes at lower costs for market participants.”
This is about cost, duplication, and speed. Overlapping requirements can turn compliance into a barrier to entry. Substituted compliance can cut repeated work where two regimes are trying to solve the same control problem.
“Within the bounds of the law and where appropriate, market participants should be able to offer multiple products through a single platform without navigating an inefficient patchwork of registrations and overlapping regulatory regimes.”
This points to a model where firms can run more of their product stack under one platform instead of splitting activity across separate legal and operational silos. That can improve operating leverage for exchanges, brokers, and infrastructure firms that want to offer more than one regulated product. Also see broader SEC direction in Atkins crypto rules testimony.
“I have directed CFTC staff to begin drafting rules clarifying when leveraged, margined, or financed retail commodity transactions in crypto may be offered off-exchange under an ‘actual delivery’ exception.”
Retail users can already get leveraged crypto in some places, but U.S. rules have left big gaps in what is clearly allowed. If the CFTC writes clearer rules, firms will know which leverage products they can offer, which ones are off limits, and what steps they must follow to stay compliant.
“I have directed CFTC staff to explore the creation of a new category of DCM registration that is tailored specifically to retail leveraged, margined, or financed crypto asset trading.”
This suggests the CFTC may create a new kind of regulated exchange category built specifically for retail leveraged crypto trading. If it does, firms will be able to design products and go to market using a clearer venue rulebook, and exchanges will compete on who can offer the best compliant access and distribution.
“First, I have directed CFTC staff to withdraw the 2024 event contracts rule proposal that would prohibit political and sports-related event contracts and the 2025 staff advisory.”
This removes a major source of uncertainty around prediction markets.
“Second, looking ahead, and in the spirit of markets that trade on expectations, I have directed CFTC staff to move forward with drafting an event contracts rulemaking.”
Withdrawing the old proposal reduces near term uncertainty, but new event contract regulations would spell out which event-based contracts are allowed, what monitoring and controls platforms must run, and how firms can build prediction style products without guessing where the line is.
These speech commitments point to a practical attempt to aggregate more products, more liquidity, and more infrastructure into regulated US channels. Tokenized collateral, perpetuals, retail leveraged crypto, and event contracts are all in the spotlight with real market share potential. Companies that can meet the bar for custody, risk controls, disclosures, and auditable operations can begin building onshore products more confidentially than they could before.
The CFTC and SEC discussion focuses on market structure, but tokenized collateral and onshore crypto venues still rely on a settlement instrument that can hold up under supervision. That is why the stablecoin perimeter matters.
On February 25, 2026, the OCC issued a notice of proposed rulemaking (See: OCC stablecoin NPRM) to implement the GENIUS Act (Guiding and Establishing National Innovation for U.S. Stablecoins Act) for payment stablecoin issuance and related activities under OCC jurisdiction, including national banks and their subsidiaries, federal savings associations and their subsidiaries, federal branches and their subsidiaries, and foreign payment stablecoin issuers, along with entities approved as federal qualified payment stablecoin issuers and certain state qualified issuers. The OCC points to a new 12 CFR 15 that covers reserve assets, redemption, risk management, audits and supervision, custody, applications and registrations, examination of foreign issuers, and a capital and operational backstop.
While the OCC moves ahead with rulemaking under the GENIUS Act, the legislative framework for crypto market structure is still contested in Washington. A Reuters report from March 5, 2026 on the crypto bill impasse in Congress describes renewed disagreement over stablecoin related customer rewards and whether they could draw deposits away from banks. The dispute shows that even as regulators move ahead with rules for trading infrastructure, tokenized collateral, and stablecoin issuance, Congress is still debating how far crypto firms should be allowed to compete with the traditional deposit system.
If the CFTC and SEC push tokenized collateral, perpetuals, and event contracts into regulated channels while the OCC pushes stablecoin issuance into a bank style rulebook, does the next U.S. advantage move to firms that can run both market structure and the cash leg under supervision?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 5, 2026
Image: Pickup truck driving in winter conditions (Unsplash/Wesley Tingey)
The popularity of pickup trucks in Canada isn't slowing down anytime soon. Some brands continue to rule the roost in the used-vehicle category, giving SUVs and other vehicle types a run for their money. When you live in a city like Calgary, Alberta, you need a vehicle that is versatile and rugged. You should be able to drive it to your office, run errands, haul equipment, or tow boats. Plus, it should be built for Calgary's weather and road conditions. Whether you have a limited budget or want a vehicle that's purely a performer, buying a used truck can be a sensible decision.
The Calgary used truck inventory is quite interesting, as you get to choose from brands like Ram, GMC, Chevrolet, and Ford. If you know what each brand stands for, finding a suitable truck for your daily needs will be easier. So, let's explore this.
This particular brand has earned a place in the used truck segment for its accessibility and durability. When exploring a credible site, you are likely to come across a Chevrolet Silverado 1500. It is well known for its lifespan. If properly maintained, a pre-owned Chevrolet Silverado 1500 can last up to 400,000 km, although actual longevity depends on maintenance and driving conditions. That means you can consider buying a Chevrolet Silverado 1500 that has run between 133,718 km and 174,948 km because it may still have significant service life remaining. Of course, other details must also be checked, such as fuel type, engine size, model year, and overall condition.
These used trucks are favourites for their comfort and performance. A pre-owned Ram 1500 with a 5.7L engine delivers power and endurance. Most Ram trucks are known for their engines, which allow them to handle even tough tasks. Nevertheless, many Ram 1500 variants feature quality interiors, luxurious materials, and much more. Since some trims also come with heated seats, it becomes easier to cope with colder Calgary weather.
You cannot ignore this brand when it comes to offering a versatile and high-performing used truck. Among many options, the Ford F-150 is particularly famous for its configurations and engine options. It is generally equipped with robust V8 or EcoBoost engines.
It shows that you can pick one that best matches your needs. For example, the V8 engines are all about raw power and performance. One made with EcoBoost engines balances power and efficiency. If one stands out for power, performance, and durability, the other promises economy and versatility.
These pickup trucks offer premium, dependable features that set them apart even in the used-vehicle category. From robust powertrain options that cater to wide-ranging performance needs to relatively roomy interiors, GMC trucks cover all the bases. In fact, GMC is also known for its advanced technologies that improve both entertainment and the driver's experience. They are ideal choices for a discerning truck buyer looking for safety, luxury, and performance.
The demand for used cars in Calgary is considerably high for various reasons. If you like a particular model or make, please don't spend too much time deliberating. Before exploring online marketplaces, define your needs and search for a truck that meets them.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 4, 2026 | NCFA Fintech Market Insight | Digital Assets And Policy And Regulation
Image: Freepik/diana.grytsku
On February 27 2026, the FCA set the application window for UK cryptoasset permission under the Financial Services and Markets Act 2000. The window opens on September 30 2026 and closes on February 28 2027. FCA webinar guidance also points to October 25 2027 as the date the new regime goes live.
This confirms the UK is moving crypto firms into the same permissioned structure used across traditional financial services (UK draft crypto rules). A firm that already operates under anti money laundering registration now faces a full authorisation process, a narrower transition path, and a higher standard on governance, controls, safeguarding, financial resources, and senior accountability.
The UK model prioritizes integration with established financial regulation. It raises the operating bar and can favour firms with stronger compliance infrastructure, clearer ownership structures, and the capital to support ongoing supervision. That can improve institutional credibility, but it also increases readiness cost and raises the threshold for smaller firms.
The EU model is different. MiCA creates a dedicated crypto rulebook, and that structure supports cross border expansion through one member state authorisation and EU passporting. One licence can open access across the single market. NCFA has already covered that operating advantage in MiCA licence unlocks EU access.
Canada has a domestic passport framework, but it's not the same as EU style passporting across sovereign countries inside a single massively connected market. CSA regulatory cooperation reduces duplication across participating provinces and territories, but Ontario does has not formally adopted the passport rule despite Canada's need to reduce duplication and regulatory burden. Ontario's passport status still emains outside MI 11-102, with Ontario using an interface and reliance model instead.
A Canadian crypto platform can use the passport process to expand across much of Canada, but of course it doesn't get the scale benefit that MiCA passporting provides across the EU with market access to 450 million. The compliance cost can still be high, while the addressable market remains much smaller. Canada also continues to raise the operating bar through supervision and custody expectations, including CIRO’s digital asset custody framework. See: NCFA’s Weekly Fintech Intelligence Jan 31-Feb 6, 2026.
Collectively this puts Canada's approach to crypto regulation closer to the UK on operating discipline than to the EU on market scale. Also worth noting varying consumer differences between UK and Canada crypto consumers.
These models now reward different business strategies. The UK offers deeper integration with traditional financial supervision and may suit firms that want institutional positioning, bank grade credibility, and a tighter regulatory perimeter.
The EU offers faster regional scale through passporting and may suit firms that need broader customer reach across multiple markets.
Canada offers a more controlled path, but one that can be slower to scale and more operationally demanding relative to market size.
For exchanges, brokerages, wallets, custody providers, and compliance firms, this is now a jurisdiction choice with direct consequences for licensing cost, expansion speed, product sequencing, and capital planning. For investors, it changes where operating leverage may be easiest to achieve. The question is not whether crypto gets regulated. The question is which regulatory architecture creates the best conditions for durable growth.
When the UK raises the authorisation bar, the EU offers passporting scale, and Canada keeps a tighter supervised path, which model attracts more builders, more capital, and more long term market share?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 4, 2026 | NCFA Fintech Market Activity | Regtech And Financial Crime Compliance
AI image robot analyzing financial data in office
On March 4 2026, UK based Vivox AI raised £1.3 million to scale AI agents built for AML, KYB, and KYC workflows inside regulated financial institutions.
Vivox AI ties the raise to current deployment claims across enterprise customers operating in more than 100 countries, including the UK, Europe, the United States, and Singapore. The release says complex compliance case processing time falls from about six hours to about 30 minutes, false positive screening alerts fall by up to 86%, and straight through processing reaches up to 50% for selected onboarding and due diligence workflows.
AML, KYC, and KYB work is repetitive, document heavy, and costly. Time per case, alert volume, and exception handling drive staffing levels and backlog risk. The goal is to target those exact cost drivers. Less time per case reduces analyst hours. Lower false positive rates reduce review load. Higher clean through processing reduces manual touch rates.
The product is described as separate task agents rather than one general AI layer. That design fits regulated workflows more closely because onboarding, due diligence, screening, and case handling can be controlled, tested, monitored, and audited as separate processes. In practice, compliance teams need faster file handling, cleaner audit trails, and fewer manual reviews that do not add risk insight.
Canada recently updated its Canada anti fraud policy and continues to raise expectations on prevention, detection, and reporting. That pushes more pressure through AML, KYC, and KYB operations while boosting financial crime compliance innovation.
Vivox AI is entering a category where established Canadian and Canada connected firms already cover adjacent parts of the stack. Trulioo identity verification supports global KYC and KYB onboarding. iComply compliance automation covers modular AML, KYC, KYB, and KYT workflows. Nasdaq Verafin financial crime controls serves financial institutions with AML, fraud, and investigation tools. Vivox AI’s stated position is narrower and more execution focused: task specific agents inside case work, screening, and due diligence workflows.
For operators key metrics such as time saved per case, false positive rates, exception rates, audit evidence quality, and post approval error rates will determine whether automation lowers cost or adds a second layer of review.
If compliance automation cuts a six hour case to 30 minutes and reduces false positives by up to 86%, does workflow design replace compliance team size as the main scaling lever?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 3, 2026 | NCFA Fintech Market Insight | Small Business Performance And Payments
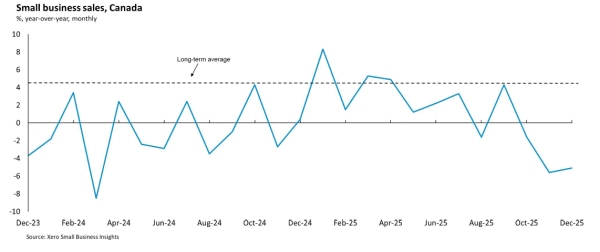
Image: Small Business Sales, Canada (Xero Small Business Insights, Canada Oct Dec 2025)
On February 26 2026, Xero released its Small Business Insights Canada Update for October to December 2025, based on aggregated and anonymized small business accounting data from its small business accounting platform, not survey responses. The dataset reflects real invoicing and payment activity captured within the Xero system. The December quarter closed with a clear revenue reversal while payment discipline strengthened. The numbers provide an operating baseline for fintech lenders, payments firms, and financial institutions serving the small business segment, as we move deeper into 2026.
Quarterly Sales Growth 2025
Q1: +5.0%
Q2: +2.8%
Q3: +2.0%
Q4: −4.1%
Q4 Monthly Breakdown
October: −1.6%
November: −5.6%
December: −5.1%
A nine percentage point swing from Q1 to Q4, with the December quarter decline the largest since September 2020. The Q4 reversal showed how fast small business demand can change. Sales moved from solid growth early in the year to a sharp contraction by December.
That kind of swing compresses reaction time. For lenders and platform providers, continuous revenue monitoring is more important than backward looking ratios. Fintechs that track live invoicing flows and cash inflows gain earlier warning signals. Banks that still rely on periodic reporting will be reactive. The risk is no longer just default, it's also speed.
During periods of weaker revenue, founders focus on cash flow and credit, but they also need to review commercial insurance coverage options as risk exposure increases.
Full Year 2025 Average: +1.4%
Long Term Average: +4.5%
A sustained three percentage point gap versus historical norms. Not a single weak month but a structural softness across the year. When growth slows, small businesses focus on managing timing. They want certainty around receivables, payables, and liquidity buffers. Expansion plans move to the background. This changes product priorities. Tools that shorten receivable cycles, automate reconciliation, and provide flexible liquidity become core operating infrastructure. Working capital solutions that assume growth acceleration may miss the mark. Fintechs that help stabilize cash flow, and not amplify growth, may align better in this cycle.
Late Payment Days
June Quarter: 11.3 days
September Quarter: 9.8 days
December Quarter: 9.7 days
Long Term Average: 11.7 days
Time To Be Paid
June Quarter: 27.7 days
September Quarter: 26.3 days
December Quarter: 26.8 days
Revenue slowed, but businesses tightened receivables management. Payment behaviour improved into year end. Settlement timing held steady despite volatility in topline growth. This means payment behaviour data may now offer stronger forward insight than topline growth alone. If a business collects faster, even during a slowdown, that tells you something about discipline, customer quality, and internal controls. Fintech lenders that weight verified payment performance can price risk more precisely.
Q4 Sales Growth By Province
British Columbia: −8.2%
Alberta: −4.0%
Ontario: −1.7%
Q4 Time To Be Paid
Ontario: 28.4 days
British Columbia: 27.5 days
Alberta: 26.6 days
Regional sales outcomes and liquidity conditions diverged materially. National averages masked local differences. The December quarter showed wide variation across provinces. Some regions contracted far more than others. That gap changes the risk profile of a portfolio. National averages smooth out reality. A lender with concentrated exposure in a weaker province carries different forward risk than one diversified across stronger regions. Regional segmentation should move from a reporting exercise to a pricing and limit setting discipline. Portfolio steering needs to reflect local operating conditions, not national headlines.
Q4 2025 showed a structural split: weaker sales, stronger collections, and widening regional differences. For fintech leaders, the opportunity is not just reacting to the decline. It's in building systems that continuously read revenue direction, payment velocity, and geographic exposure at a granular level. Firms that can master these variables in real time will support small businesses more effectively in lower growth environments.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016