




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


March 10, 2026
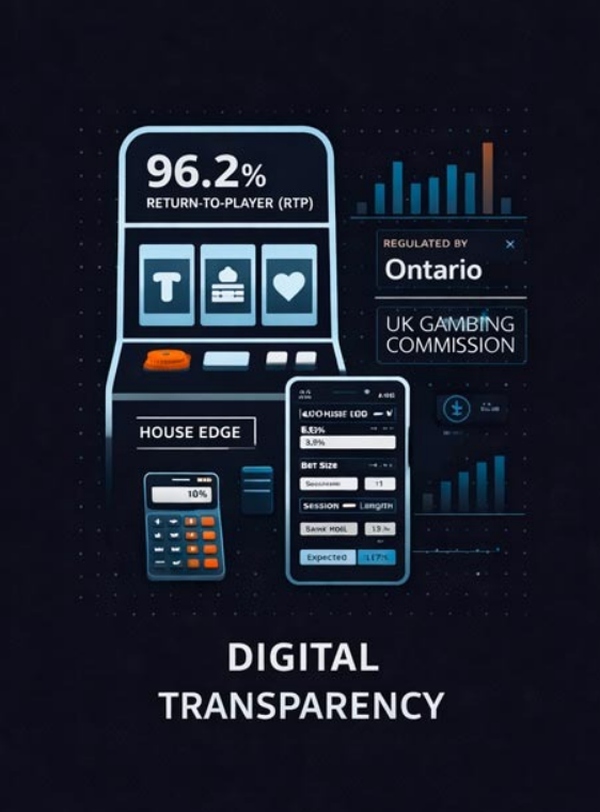
The fintech revolution has trained an entire generation of consumers to expect real-time data, clear fee structures, and algorithmic fairness from every platform that touches their money. Open banking, commission-free trading dashboards, and instant payment confirmations have established a baseline of transparency that didn't exist a decade ago. Now that same expectation is spilling into adjacent sectors, and the digital entertainment industry is finding that the old model of opaque mechanics no longer works for a consumer base raised on fintech-grade disclosure.
This shift is particularly visible across the iGaming sector, where a convergence of regulatory pressure, blockchain verification, and consumer demand has created a new class of data-transparent platforms. For fintech professionals and investors, the patterns emerging here are worth watching closely. They mirror the same transparency dynamics that reshaped banking, lending, and investment management over the past ten years, and they point toward a broader standard that will likely define consumer expectations across all digital financial services.
Before the fintech wave, consumers accepted a remarkable level of opacity in financial products. Credit card fees were buried in fine print. Investment management costs were layered across multiple disclosure documents. Currency exchange rates at banks included undisclosed markups. Fintech companies built entire businesses by simply making these costs visible.
TransferWise, now Wise, didn't invent a new foreign exchange mechanism. It made the existing markup visible and offered a lower one. Robinhood didn't create a new kind of stock trading. It eliminated commissions and showed real-time portfolio data on a mobile screen. In both cases, the competitive advantage wasn't technological sophistication but rather a commitment to showing consumers exactly what they were paying and exactly what they were getting.
According to PwC's Global Financial Services report, trust remains the single most important factor in consumer adoption of digital financial products. Yet the report also found that less than 30% of consumers globally feel they fully understand the fee structures of the financial products they use. The gap between expectation and reality is where fintech innovation continues to find its most fertile ground.
The digital entertainment space is now passing through the same transparency inflection point that banking experienced between 2015 and 2020. Regulatory bodies in Ontario, the UK, Malta, and several EU jurisdictions have moved beyond simple licensing requirements toward mandating specific mathematical disclosures. Return-to-player (RTP) percentages, variance classifications, and house edge figures are increasingly required to be published at the point of consumer interaction, not buried in terms and conditions.
Ontario's iGaming market, launched in April 2022 under the Alcohol and Gaming Commission of Ontario (AGCO), is a particularly instructive case for Canadian fintech observers. The regulatory framework requires licensed operators to display game-level RTP data and to submit their random number generators to independent auditing firms. This is functionally identical to how securities regulators require fund managers to disclose management expense ratios and historical performance data. The principle is the same: consumers making financial decisions deserve access to the quantitative parameters that determine their likely outcomes.
What makes the current moment different from previous disclosure requirements is the emergence of independent consumer tools that go beyond what regulators mandate. Platforms like gambling calculators allow users to input specific game parameters, including house edge, bet size, session length, and bankroll, to model their expected outcomes before committing funds. This is the iGaming equivalent of a mortgage amortization calculator or a compound interest simulator: a tool that translates abstract mathematical parameters into personalized, actionable projections. The fact that such tools now exist and attract meaningful traffic signals a shift in consumer behavior from passive participation to active quantitative analysis.
This consumer-side demand for calculable transparency aligns with broader fintech trends. The same user who models their mortgage payments on Ratehub, tracks their investment returns on Wealthsimple, and monitors their credit score on Borrowell now expects comparable analytical tools in every domain where money changes hands.
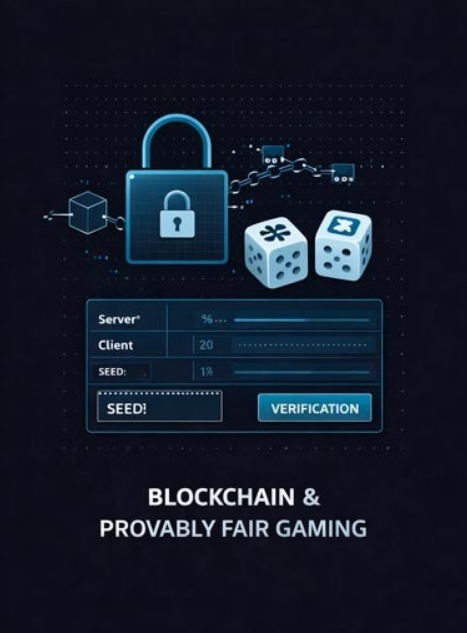
If regulatory disclosure provides the baseline, blockchain technology is building the verification layer. The concept of "provably fair" systems, where cryptographic hashing allows users to independently verify that an outcome was generated randomly and was not manipulated after their action, represents one of the most interesting applied use cases for distributed ledger technology outside of cryptocurrency itself.
The mechanism is straightforward in principle. Before a game round begins, the platform generates a server seed and provides the user with a hashed version. The user can supply their own client seed. After the round, the server seed is revealed, and the user (or any third-party auditor) can run the hash function to verify that the outcome matches the pre-committed parameters. Tampering after the fact is cryptographically impossible.
For the fintech community, provably fair systems are a practical demonstration of how blockchain can solve a real trust problem without requiring a full decentralized architecture. The platform still operates centrally. The games still run on conventional servers. But the verification layer, the part that matters most for consumer trust, uses the same cryptographic principles that secure cryptocurrency transactions. It's a pragmatic middle ground between fully centralized and fully decentralized models, and it's gaining traction faster than many pure DeFi applications.
According to the World Economic Forum's report on global fintech resilience, the ability to provide verifiable, tamper-proof records of financial transactions is one of the key value propositions driving blockchain adoption across regulated industries. The iGaming sector is proving that this value proposition translates effectively to consumer-facing products, not just institutional back-end infrastructure.
The transparency conversation extends beyond mathematics and into behavioral design. Fintech platforms have spent years developing AI-driven systems to detect fraudulent transactions, flag unusual account activity, and nudge users toward healthier financial behaviors. Wealthsimple's spending insights, for example, categorize expenditures and highlight patterns that users might not notice on their own. Banking apps send alerts when spending exceeds normal ranges.
The iGaming industry is adopting parallel approaches, partly driven by regulation and partly by competitive pressure from operators who recognize that long-term customer value depends on sustainable engagement rather than short-term extraction. Machine learning models now monitor player behavior patterns and flag indicators that correlate with problematic use: rapid increases in deposit frequency, session lengths that extend well beyond historical norms, and chasing behavior where bet sizes increase following losses.
The most sophisticated platforms use these signals to intervene proactively. Interventions range from gentle nudges, similar to the spending alerts in banking apps, to mandatory cooling-off periods and self-exclusion tools. Ontario's regulatory framework includes specific requirements for operator-initiated interventions, making this a compliance obligation rather than an optional feature.
From a fintech design perspective, this represents an important evolution. The first wave of fintech disruption was about making things easier: easier payments, easier investing, easier borrowing. The current wave increasingly focuses on making things safer, incorporating behavioral science and AI to protect users from their own cognitive biases. The iGaming sector's accelerated adoption of these tools, driven by the higher stakes involved, is generating insights and frameworks that will eventually flow back into mainstream financial product design.
Perhaps the most direct connection between fintech innovation and the digital entertainment sector is payment infrastructure. The iGaming industry's requirements for instant deposits, real-time withdrawals, multi-currency support, and robust identity verification have made it one of the most demanding use cases for modern payment systems.
Interac e-Transfer, which processes over one billion transactions annually in Canada, has become a standard payment rail for Ontario's licensed iGaming operators. The integration requirements have pushed Interac to develop faster settlement capabilities and more sophisticated fraud detection systems, improvements that benefit the entire Canadian payment ecosystem. Similarly, the industry's early adoption of cryptocurrency payment rails and stablecoin settlement layers has provided real-world transaction volume for technologies that are still largely theoretical in other financial services contexts.
For fintech startups building payment infrastructure, the digital entertainment vertical offers something valuable: high transaction volume, strong user expectations around speed and reliability, and regulatory frameworks that demand robust KYC and AML compliance. Several Canadian payment fintechs have used iGaming as an initial vertical, then expanded the infrastructure they built into adjacent sectors like e-commerce and subscription services.
Canada's approach to iGaming regulation offers a useful case study in how regulatory sandboxes can balance innovation with consumer protection. Ontario's decision to create a regulated market rather than maintaining prohibition has generated significant tax revenue, estimated at over $200 million annually, while giving regulators direct oversight of operator practices.
The regulatory model shares structural similarities with the sandbox approaches that several Canadian provincial securities regulators have adopted for fintech products. The Canadian Securities Administrators' Regulatory Sandbox, for instance, allows fintech firms to test innovative products in a live market under modified regulatory requirements. Both frameworks rest on the same principle: that a controlled, transparent regulatory environment produces better outcomes for consumers than either prohibition or a regulatory vacuum.
For the fintech ecosystem, the cross-pollination of regulatory approaches between financial services and digital entertainment is creating interesting opportunities. RegTech companies that developed AML compliance tools for banking are finding ready markets in iGaming. Identity verification firms that built their technology for fintech onboarding are applying the same infrastructure to age verification and player authentication. The regulatory convergence is driving a convergence of service providers, and Canadian companies are particularly well positioned because the country's regulatory frameworks in both sectors are relatively advanced by global standards.
The digital entertainment industry's rapid adoption of fintech principles, quantitative transparency, blockchain verification, AI-driven behavioral protection, and advanced payment infrastructure, is not a peripheral development. It is a preview of the consumer expectations that will define every sector where financial risk and digital interaction overlap.
The users driving this shift are not a niche demographic. They are the same consumers who use mobile banking, invest through digital platforms, and expect every financial interaction to come with complete data visibility. Their insistence on transparency in entertainment spending is a natural extension of the transparency they already demand from their financial service providers.
For fintech founders, investors, and ecosystem builders, the key takeaway is that transparency is no longer a differentiator. It is becoming the minimum standard for any platform that touches consumer money, regardless of the specific vertical. The tools, frameworks, and regulatory models being developed at this intersection of fintech and digital entertainment will likely define consumer financial technology's next chapter, not just in Canada, but globally.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 10, 2026 | NCFA Fintech Market Activity | Wealthtech And Consumer Finance
On March 4 2026, Robinhood unveiled new family finance products at its Take Flight event, adding a family investing experience, custodial and trust accounts, expanded managed investing tools, a new Platinum Card, and new Gold perks.
Vlad Tenev, CEO said:
“Robinhood will be the financial superapp for families to invest, plan, and grow wealth across generations.”
The platform continues to push further beyond retail trading and into family account oversight, wealth transfer, premium credit, and long term asset management. The new family hub is built to let households group accounts by family member, choose which accounts are visible, and assign permissions from view only access to full authority. Custodial accounts are rolling out now, while trust accounts and the family hub begin rolling out later this year.
This launch builds on an earlier NCFA analysis of Robinhood's wealthtech push and lifestyle finance strategy, but the new announcement goes further by tying family visibility, investing, credit, and wealth transfer into one customer experience.
The scale behind the launch is material. The platform reports 27.2 million funded customers, $324 billion in total platform assets, and $4.5 billion in 2025 revenue. That revenue rose 52% from 2024. Managed investing is also getting bigger. The firm says Robinhood Strategies now serves more than $1.5 billion in assets under management across more than 250,000 funded customers.
On the money side, it says there are more than 700,000 Gold Card customers with over $10 billion in annualized spend, while Robinhood Banking has more than 50,000 funded customers and over $800 million in cash deposits to date.
The premium card launch shows where the model is heading. The new invite only card carries a $695 annual fee and comes with richer travel, dining, and wellness benefits. That pricing puts the platform into a higher value segment as it tries to deepen relationships with customers whose financial lives are getting more complex.
When a platform bundles enough strategic product that can handle family account access, children’s investing, trust structures, managed portfolios, cash, and premium spending, it's getting closer to owning the main financial relationship in the household. That should raise eyebrows for banks, wealth platforms, and fintechs that still treat investing, credit, and family finance as separate product lines.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 9, 2026 | NCFA Fintech Market Insight | Digital Assets And Policy And Regulation

Image: Unsplash/J K
On March 9 2026, the U.S. Treasury released a report to Congress on innovative technologies to counter illicit finance involving digital assets under the GENIUS Act. Treasury says successful monthly transactions on public blockchains reached 3.8 billion in early 2025, up 96% year over year. Treasury also reviewed more than 220 public comments while preparing the report. Against that backdrop, the report goes on the record to say crypto mixers can support laundering and sanctions evasion, but they can also serve legitimate privacy needs on public blockchains.
Treasury doesn't overlook the enforcement case against cyrpto mixers, saying criminals commonly use mixing, bridging, and swapping to obscure transaction trails and frustrate investigations. Treasury links these techniques to ransomware groups, darknet markets, sanctions evasion schemes, and DPRK cyber actors. The scale of harm remains large.
Victims reported more than $9 billion in digital asset related fraud to the FBI in 2024, including $5.8 billion tied to digital asset investment schemes, up 47% from the prior year. Treasury also says DPRK cybercriminals stole at least $2.8 billion in digital assets from January 2024 to September 2025, including a $1.5 billion theft in February 2025 that Treasury describes as the largest digital asset heist to date.
The report states that lawful users may use mixers to enable financial privacy when transacting through public blockchains. Treasury gives practical examples. Individuals may want to protect sensitive information such as personal wealth, business payments, charitable donations, or consumer spending patterns from appearing on public ledgers.
That statement changes the tone of the policy debate. The question is no longer whether mixers exist only for criminals. The policy challenge is whether privacy tools can operate with sufficient accountability, recordkeeping, and supervision inside the financial system.
Treasury also notes that custodial mixers that accept and transmit value must register with FinCEN as money services businesses, maintain records, and file suspicious activity reports. When compliant, these services can provide customer identities, off chain transaction data, and behavioural information to regulators or law enforcement.
Treasury also describes how mixers interact with broader digital asset infrastructure. Stablecoins frequently appear in laundering chains when illicit actors transfer assets across blockchains or prepare to convert digital assets into fiat.
Since May 2020, Treasury says more than $37.4 billion in withdrawals from over 50 bridges were denominated in the two largest stablecoins by market capitalization. During the same period those bridges received about $1.6 billion in deposits originating from mixing services. Treasury says more than $900 million of those deposits flowed into one specific bridge that faced scrutiny for DPRK linked laundering (North Korea state-sponsored).
A large part of the report focuses on the technologies Treasury believes financial institutions should use to strengthen anti money laundering and sanctions compliance programs. Treasury highlights four priority tools: artificial intelligence, digital identity, blockchain analytics, and application programming interfaces.
Treasury cites FinCEN analysis showing about 1.6 million identity related BSA reports in 2021, equal to 42% of reports filed that year and tied to $212 billion in suspicious activity. Treasury says AI can help institutions analyze large datasets and reduce false positives, digital identity systems can strengthen customer onboarding and fraud detection, blockchain analytics tools can trace wallet activity across networks, and APIs can improve secure monitoring and information sharing.
The next evolution of digital asset infrastructure will likely reward firms at the forefront of regulatory accountability that can distinguish lawful privacy from criminal abuse, strengthen identity and monitoring controls, and provide institutions with faster and more accurate compliance tools.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 9, 2027
Image: Freepik/ArthurHidden
Susanne Klatten is the heiress to the BMW car company and the richest woman in Germany. In 2026, Bloomberg estimated her fortune at $31.3 billion.
She is one of the ten richest women in the world. Klattens owns 19.2% of BMW shares and heads the company's supervisory board. However, she is not only the owner of the family fortune, but also actively participates in the development of the business, which earns billions annually.
Her path is not the story of a businesswoman who built a huge fortune from scratch, but an example of how the responsibility and dedication of an heiress helps the business of several generations of a family to develop and grow.
Susanne Klatten was born in 1962 in Bad Homburg, Germany. Her father is German billionaire and industrialist Herbert Krupp, who saved the German car company BMW from bankruptcy in the 1960s and made it profitable again.
The Quandt family began building their wealth at the end of the 19th century. At that time, the head of the family, Emil, created a thriving textile company. His son, Günther, took over the company before World War I and, having made his fortune supplying uniforms to the German army, began engaging in mergers and acquisitions. He acquired the battery manufacturer Varta, as well as shares in BMW and Daimler-Benz.
Here you can take a break from business and work and play your favourite games - Reddogcasino.com
In building capital, as in any business, the main thing is to get started. If you don't want to start your own business, you can earn money by buying a share in someone else's. We help new Finama clients take their first step in investing with us — and immediately start making a profit. Invest with a guaranteed daily premium of 36.6% per annum on your assets.
The Quandt family has two golden rules: the family business must constantly expand, and control over it must always remain in the hands of family members. From childhood, Klatt was raised and educated with the idea that one day she would have to manage the family assets.
After earning a degree in business finance, the young Klatt honed her skills at the Young&Rubicam advertising agency in Frankfurt, where she interned from 1981 to 1983. She then continued her education, studying marketing and management at Buckingham University and earning an MBA from the IMD business school in Lausanne, Switzerland.
After her studies, Klattten worked at Dresdner Bank, the Munich branch of the consulting firm McKinsey, and Bankhaus Reuschel & Co.
In 1982, Klatt's father, Herbert Quandt, died, leaving his daughter 12.5% of BMW shares and 50.1% of shares in the chemical and pharmaceutical company Altana AG.
Under Klatt's leadership, Altana AG reached a new level and demonstrated significant growth. It entered the list of the 30 largest pharmaceutical companies in Germany. Experts praised Clatten's contribution and called her strategy for developing Altana AG effective.
In 2006, Altana AG sold its pharmaceutical business to Nycomed for €4.5 billion. This amount was paid to shareholders as dividends, and the company continued to specialise in the production of speciality chemical products.
In 2009, Klatt became the sole owner of Altana AG by buying out the remaining shares. She became deputy chair of the board with an annual turnover of just over $2.5 billion.
In 1987, Klatt began working at BMW and, after ten years with the company, joined the BMW Supervisory Board in 1997 alongside her younger brother Stefan Quandt. She played a decisive role in implementing an appropriate risk management system at BMW and was responsible for regular reporting to the Supervisory Board and representing BMW's external interests.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 8, 2026
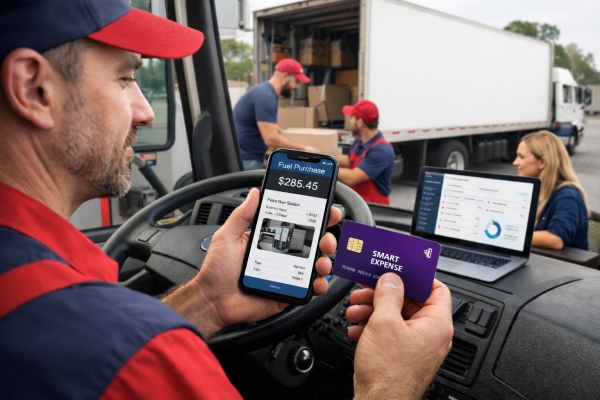
AI Image Moving company using smart expense card
Picture a typical, high-energy moving day. A fully loaded five-ton truck is navigating a tight schedule across provincial lines.
The crew is working against the clock to meet the client at the destination, but the reality of logistics sets in: the truck needs a sudden diesel top-up, there is an unexpected commercial transit fee coming up, and one of the tires desperately needs patching after picking up a nail in a residential cul-de-sac.
Historically, managing these on-the-road expenses has been a major operational headache.
To remain competitive and operationally efficient, logistics businesses need a superior system.
Enter smart expense cards for moving companies, a modern, fintech-backed solution designed to eliminate the friction of on-the-road purchasing.
Smart expense cards are a leap forward from the traditional corporate credit card. Available as both physical plastic and virtual cards (which can be stored in Apple Pay or Google Wallet), they are directly linked to a centralized, cloud-based expense management application.
Unlike old-school corporate cards issued by legacy banks, these modern financial tools do not require personal credit checks for the crew members holding them. They are not tied to the driver’s personal credit score, nor do they give the driver unfettered access to a massive corporate credit line.
Instead, these moving crew corporate cards offer dispatchers and fleet owners granular, real-time control over company funds. Every swipe, tap, or online purchase is immediately registered in the central dashboard, giving management ultimate visibility and the ability to freeze or issue cards with a single click.
Transitioning to a modern financial infrastructure provides immediate, tangible benefits to the daily operations of a local moving company.
The defining feature of smart cards is programmable spending. An owner or dispatcher can set exact daily, weekly, or even category-specific spending limits directly from their smartphone. Utilizing Merchant Category Codes (MCCs), a dispatcher can lock a card so that it strictly only works at gas stations, automotive repair shops, or hardware stores. If a crew member attempts to use the card at a restricted location, the transaction is automatically declined, completely eliminating unauthorized spending.
Lost receipts cost businesses thousands of dollars annually in unclaimed tax deductions and wasted administrative hours. Smart cards feature a "snap and upload" mechanism powered by Optical Character Recognition (OCR) technology.
When a driver purchases fuel, they immediately take a photo of the receipt using the card's companion app. The software extracts the date, merchant, tax amount, and total, instantly matching it to the transaction and categorizing it.
Moving fleets operate in unpredictable environments. If a truck breaks down in a remote area, waiting for an invoice to be approved or wiring money can cause catastrophic delays. With a smart card system, management can instantly push supplemental funds to a driver's card in seconds.
The driver pays the mechanic, and the move gets back on schedule without anyone having to leave the main office.
As a highly effective logistics petty cash alternative, these platforms eliminate manual month-end reconciliations. Smart card software syncs seamlessly through API integrations with major accounting platforms like QuickBooks Online, Xero, and Sage.
Transactions are mapped to the correct general ledger accounts in real-time, saving the back office dozens of hours of manual data entry every month.
For companies operating north of the border, choosing the right Canadian fintech for small business is crucial. Several top-rated platforms have emerged as leaders in fleet management Canada.
To understand the practical impact, consider a real-world scenario with President Movers.
A crew is tasked with driving a fully loaded five-ton truck from Vancouver to Kelowna. This route takes them across the Coquihalla Highway (Highway 5), a stretch of road known for its steep, challenging mountain grades that demand heavy fuel consumption and put immense strain on commercial vehicles.
Halfway through the journey, the truck requires a massive diesel fill-up in Hope. The driver pulls into the commercial cardlock, taps their physical smart card, and fills the tank. While the tank is filling, the driver snaps a photo of the pump receipt via the mobile app.
Later, the crew stops for a quick, pre-approved lunch in Merritt, tapping their virtual cards. Finally, they encounter an unexpected commercial vehicle scale fee.
Throughout this entire journey, the operations manager sitting at the base in Vancouver watches the expenses populate the dashboard in real-time.
There are no frantic phone calls asking for a credit card number, no out-of-pocket expenses for the crew, and no paper receipts to track down at the end of the week.
Modernizing expense management is no longer just a financial upgrade; it is an operational necessity. By replacing outdated petty cash envelopes with smart expense cards, moving companies drastically reduce stress for their crews on the road, save significant administrative costs for the business, and ultimately deliver a more reliable, uninterrupted service to the customer.
At President Movers, we embrace the latest technology behind the scenes so your move is completely seamless from start to finish. Our commitment to operational efficiency means we spend less time worrying about logistics and more time focusing on safely transporting your belongings. Planning a relocation in British Columbia? Contact us today for a free quote.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Regulation And Policy, Lending Consumer Credit And BNPL, Sustainable Finance And ESG

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026).
This is for AI first fintechs, SaaS platforms, and builders selling usage heavy products because AI cost recovery is moving out of finance spreadsheets and into the billing stack itself. This means markup, model pricing, and token usage can all be baked directly into a single workflow.
This affects crypto custody, brokerage, and compliance tooling teams, plus firms that run secondary market controls, because it pushes more of the crypto perimeter into client asset rule design while tightening where firms must look for core market mechanics requirements.
This changes the operating timetable for lenders, brokers, and claims handling firms, and it pulls more pressure onto complaint intake, identity checks, fraud controls, and customer communications. Fintechs offering claims workflow solutions, onboarding checks, and redress automation now need to map product readiness to the late March rules and the 3 to 5 month build window.
This opens an official lane that matters for remittance firms, merchant payments providers, instant payments infrastructure teams, and institutions building Canada India payment flows. Once payment system operators are invited into the file, the discussion moves closer to real operating design, not just diplomacy.
This opens a new regulated advice lane between generic guidance and individual advice. It affects banks, pension providers, wealth platforms, and fintechs building support flows, because firms now have a near term path to turn customer guidance into a permissioned product with real conduct and authorisation consequences.
This is important for issuers, dealers, custodians, and market infrastructure teams because a central bank backed trial now shows how tokenized bonds and central bank settlement money can run through an on chain workflow, which raises expectations on governance, auditability, and integration before this model can scale beyond pilots.
A major exchange operator is tying its regulated futures roadmap to crypto spot reference prices while pushing tokenized equities distribution through a large crypto customer base.
This is for banks, payment infrastructure firms, tokenization platforms, and securities settlement providers. The BOJ is linking blockchain, tokenized central bank money, and core settlement design to active pilots, sandbox work, and future upgrades to BOJ NET, which raises the bar for how seriously the market should treat settlement infrastructure moving on chain.
This raises the enforcement baseline for broker dealers and their vendors. If you create or sell onboarding, surveillance, AML, or case management tooling, expect more pressure to prove risk based controls, faster SAR decisioning, and audit ready evidence because regulators are treating gaps in thinly traded securities monitoring as a serious control failure.
This is a positive announcement for fintech vendors that sell to government, defence, banks, and critical infrastructure. AI evaluation, cybercrime response, and resilience checks start to converge across buyers.
As Canada and Australia open the door to more pension investment, investors will want simple, auditable reporting and quick due diligence, especially for payments, AI, and critical supply chain projects.
This delay ties up cash for importers and their banks. When refunds take weeks to process, treasury teams need tighter visibility into duty exposure, eligibility tracking, and cash forecasting, and that opens room for fintech tools that automate reconciliation and working capital decisions created by policy whiplash.
This could impact how payments teams operate. If merchants can query verified payments events in natural language and automate workflows on top of unified data, AI payments will run the operating layer for routing, fraud, disputes, and cost control, which raises expectations on data quality, lineage, and accountability across the payments stack.
The Fed is opening a controlled access point for a crypto linked institution inside the U.S. payments system. That sets a live precedent for how non bank and digital asset firms may be handled under account access rules, even where service scope stays tightly constrained.
This for issuers, acquirers, sponsor banks, card fintechs, and treasury teams because stablecoins are moving closer to core network settlement, not just crypto side rails. Once a global card network starts wiring a bank issued stablecoin into settlement flow, teams need a clearer view on treasury design, reconciliation, network rules, and what faster money movement looks like in practice.
This pushes stablecoins deeper into everyday card economics, not just niche crypto wallets. It matters for issuers, program managers, fintech developers, and infrastructure teams because card issuance, settlement, and reconciliation are starting to move into the same onchain operating stack at global scale.
Singapore is placing climate transition planning inside supervised financial risk management rather than limiting it to public reporting. The approach gives Canadian regulators and institutions a comparator for connecting climate data, portfolio decisions, customer engagement and governance while avoiding blunt exclusions that could restrict financing without reducing underlying risk.
Core financial infrastructure continues to move closer to programmable systems while regulators tighten the rules around how firms operate and protect customers. Stablecoins are entering card settlement, tokenized bonds are moving through central bank backed pilots, and AI usage is starting to show up directly inside billing and payments operations. At the same time, regulators are opening new product lanes and expanding oversight of crypto custody, advice models, and consumer finance practices. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 5, 2026 | NCFA Market Insight | AI And The Future Of Work

Image: Labour market impacts of AI: New measure, early evidence (Anthropic Mar 2026)
On March 5 2026, new Anthropic artificial intelligence labour market impact research | download 17 page PDF offers a more grounded way to think about AI and jobs. Most AI labour studies ask what large language models could do in theory. This one asks what workers actually do with AI now. That sounds like a small change, but it matters. Financial institutions, fintechs, and policymakers need to know where real workflow change starts, not just where capability headlines point.
The paper introduces a new measure called observed exposure. It combines occupational task data, Claude usage data, and earlier research on which tasks language models can theoretically handle. The approach tries to separate technical possibility from real use. That makes this study potentially more useful than other broad forecasts about AI replacing jobs. To be clear, at this point the research doesn't claim mass displacement has arrived. It looks instead for early pressure points that may show up before unemployment spikes.
This report matters because it focuses on real work patterns. The authors use the US O*NET task database, Anthropic Economic Index usage data, and earlier task level exposure estimates to build their measure. They also give more weight to automated and work related uses than to lighter forms of assistance. That helps the study track where AI starts to move from drafting help into actual production work.
That said, the research has real limits, and those limits matter. The usage data comes from Claude, not from the full AI economy. A bank using Microsoft, Google, OpenAI, or internal tools may show a different pattern. The measure also tracks task exposure, not direct job loss. And the authors make clear that adoption still lags capability because of legal controls, software requirements, human review, and workflow friction. That caution strengthens the paper rather than weakening it. It keeps the analysis honest.
The most striking findings is the size of the gap between capability and real usage. In STEM (ie. computer and math) occupations, earlier work suggests language models could theoretically touch 94% of tasks. Anthropic’s observed measure puts current Claude coverage in that category at just 33%. In other words, the technology frontier sits much further ahead than the adoption frontier.
That gap matters for fintech and finance because it points to where the real bottleneck sits. The next productivity jump might not come from a bigger, better, faster or smarter model alone. It might come from firms that redesign workflows, tighten controls, connect tools to internal systems, and build trust in output quality. Which operators can close the adoption gap faster than peers.
The report finds that computer programmers rank as the most exposed occupation, with 74.5% coverage. Customer service representatives follow at 70.1%, and data entry keyers come next at 67.1%. Digital, repeatable, text heavy work moves first.
What stands out for NCFA readers is that this isn't just software engineers. Financial analysts are also among the most exposed occupations in the paper’s wider discussion. That should get the attention of banks, insurers, wealth platforms, lenders, and compliance teams. A lot of value in finance comes from summarizing information, checking documents, explaining options, processing forms, and moving data from one system to another. Those are exactly the kinds of tasks that AI enters early.
Workers in the most exposed occupations earn 47% more on average than workers in the unexposed group. People with graduate degrees make up 17.4% of the most exposed group, compared with 4.5% of the unexposed group.
Early pressure is showing up in better paid, more educated, office based roles. In practice, that means AI may alter the work of analysts, developers, researchers, service teams, and operations professionals before it touches many frontline physical jobs. For financial institutions, this points to a management challenge as much as a technology one. Firms need to rethink role design, supervision, training, and quality control inside knowledge work functions.
The research does not find a growing rise in unemployment for workers in the most exposed occupations since late 2022. That is an important result because it pushes back on louder claims that AI already causes wide labour market damage.
But the report does find an early warning sign. For workers aged 22 to 25, job finding rates into highly exposed occupations fall by about 14% compared with 2022 levels. The authors stress that this result is only barely statistically significant and open to other interpretations. So something to watch and track.
This is how labour market change often starts. Not with mass layoffs. Not with an obvious cliff. It starts when firms stop hiring as many junior people because AI now handles part of the routine work those hires once learned on. That's important for banking, fintech, consulting, and other white collar sectors that depend on apprenticeship style career ladders. If entry points narrow, firms may save money in the short run while weakening their future talent pipeline.
Firms should watch three things closely to better anticipate where the real gap may open between leaders and laggards:
For fintech builders, the market needs tools that help institutions safely plug AI into live work. Audit trails, review controls, workflow routing, structured data extraction, policy checking, and role based permissions. Companies that solve those problems help close the distance between AI capability and actual business use and adoption.
Anthropic’s research is quite useful because it shows where real adoption starts, where the biggest gaps remain, and where the cracks may start to appear and proliferate.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016