




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Stablecoins | Sep 25, 2025

On September 24, 2025, Stablecorp announced a $5 million CAD strategic round led by FTP Ventures to accelerate the rollout of its Canadian dollar stablecoin, QCAD. The financing builds on $2.5M investment by Coinbase Ventures earlier this year on July 2, 2025, and arrives as policymakers in Canada and the United States sharpen oversight of stablecoin issuers.
If that wasn't enough, one day later on September 25, DeFi Technologies announced a strategic investment and commercial partnership with Stablecorp, reinforcing QCAD’s role as compliant infrastructure for cross-border settlement, digital markets, and e-commerce.
Stablecoins are becoming core payment rails globally. In Canada, the Office of the Superintendent of Financial Institutions is drafting a new framework for stablecoin issuers, while the Bank of Canada has urged PM Carney to consider establishing a federal stablecoin framework to help Canada remain competitive in digital assets which are becoming more popular.
The Retail Payments Activities Act took effect on September 8, 2025, now requiring payment service providers to register with the Bank of Canada, creating a compliance base for CAD-denominated digital money. NCFA has previously reported that Canada’s stablecoin race is entering a critical phase, with domestic fintechs pushing to compete with foreign issuers. In the United States, the GENIUS Act passed in June 2025, setting strict standards for reserves, audits, and issuer oversight.
Chainalysis estimates $2.5T in stablecoin transfers over the past year. McKinsey analysis suggests gross annual stablecoin settlement volumes now exceed $27T, pointing to rapid adoption across capital markets and payments.
QCAD is fully backed 1:1 with Canadian dollar reserves, held in an arms-length trust under independent oversight. Stablecorp provides daily transparency reports and monthly third-party attestations, addressing one of the largest concerns regulators have raised around stablecoins. This design allows QCAD to be used in trust-based use cases, such as cross-border trade settlement, on-chain foreign exchange, and tokenized asset markets.
With the Bank of Canada pausing its retail CBDC work, private CAD stablecoins structured for compliance are positioned to fill immediate demand across e-commerce, payroll, and supplier payments.
The $5 million raise was led by FTP Ventures, whose founder Fred Pye described digital dollars as the most efficient payment rail yet devised. Stablecorp also attracted participation from Coinbase Ventures, Circle Ventures, and Side Door Ventures, signaling strong institutional support.
On September 25, DeFi Technologies joined as both investor and partner, announcing plans to develop QCAD-integrated products through Valour, streamline liquidity with Stillman Digital, and build a post-quantum security roadmap with BTQ.
These steps broaden QCAD’s use cases, deepen liquidity for mint and redeem flows, and create recurring revenue streams through fees and spreads.
Kesem Frank, Stablecorp CEO:
"This is another important step in scaling QCAD for the benefit of all Canadians. It is imperative that Canada takes its place as a significant and strategic market for the growth of the digital asset economy, and our development of a trusted and compliant Canadian dollar stablecoin is a critical piece of that puzzle. Our backing by industry majors signals a shared vision for a multi-currency, easy to access, and regulated digital financial system."
Previous NCFA coverage shows how Canadian banks and fintechs are backing regulated stablecoins, and globally, large institutions such as Citi and Bank of America are preparing to issue their own stablecoins under advancing regulation. This convergence of capital and compliance shows how the stablecoin market is entering a new phase of mainstream adoption.
The combined announcements highlight how regulatory clarity and capital investment are converging around Canadian dollar stablecoins. Canada’s trade with the United States, valued at more than C$1 trillion annually, provides a strong corridor for QCAD adoption. Beyond North America, Canada is diversifying trade with partners in Europe, Asia, Africa, and Latin America, where settlement costs and delays limit competitiveness.
A compliant CAD stablecoin can lower transaction frictions and unlock new efficiencies for exporters, importers, and service providers. With domestic CBDC efforts paused, well-regulated stablecoins like QCAD are an immediate solution to modernizing Canada’s payment and settlement infrastructure.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Sep 25, 2025

Image: Freepik/wayhomestudio
In Canada’s expanding online gaming market, a new platform has appeared with a straightforward setup that includes slots and table games. OMG Canada online casino offers both, along with a welcome bonus for new users. Navigation is simple, and the lobby presents a wide slot selection plus familiar table formats.
New accounts qualify for two starting perks: a $5 signup reward just for registering, and then a 100% deposit match of up to $1,000 on the first deposit. For example, a $200 deposit adds another $200 to the balance. A $50 deposit brings $50 more, while a $500 deposit is matched with $500. The minimum qualifying deposit is $20. The funds can be used on all games, but there is a time limit of 30 days to meet the requirements.
Main points:
The “Promotions” page shows rotating campaigns for active users. These include seasonal free spin bundles, slot tournaments, and occasional social media giveaways exclusive to followers.
While there is no formal loyalty program, the steady release of new slot titles and table games provides ongoing variety.
Understanding how the welcome bonus works in practice is important before playing. Many new users are surprised by the size of the required playthrough, so this section outlines what those numbers mean in simple terms.
The welcome bonus requires 40x wagering. Example:
The site confirms the 40× rule, though it does not publicly list exact contribution percentages by game type. In general industry practice:
The games section is central to any casino review. At OMG, players can choose between classic tables, real-time live dealer sessions, and a broad range of slots from known providers. Below is a breakdown of the main categories.
The lobby includes:
Non-live versions of these games are available alongside live formats.
The live dealer section lists Blackjack, Baccarat, Roulette, and Sic Bo. These games are streamed with real dealers, and tables run daily.
The slot lobby highlights titles such as Joker’s Jewels, Joker’s Jewels Wild, Wolf Gold, Chilli Heat, Queenie, Fire 88, Diamonds are Forever, Legendary Diamonds, and Buffalo Hold and Win Extreme. Providers shown include Pragmatic Play, Booming Games, and NetGaming. Some of these games feature progressive jackpots with grand prize pools.
The site works on iOS and Android without an app. Menus adapt to small screens, and games load consistently on standard connections. Both landscape and portrait modes are supported.
The majority of games are mobile-compatible, with live dealer streams optimized for stable play on 4G connections.
Payment and withdrawal options are an important part of any online casino, since players need quick deposits and predictable processing times. At OMG, the system is designed to be simple and transparent.
Supported payment methods:
Deposits are instant. Withdrawals are usually processed within 24–48 hours. The minimum withdrawal is $10, and the maximum aggregate withdrawal per day is $9,500 according to the payment policy. The casino does not charge fees, though banks or card issuers may apply their own. Compared with other casinos, the 24–48 hour processing window is standard, while Interac and e-wallets often clear faster.
What is included in the welcome offer?
New players receive $5 on signup and a 100% deposit match up to $1,000 with a $20 minimum deposit.
How long do withdrawals take?
Withdrawals generally clear within two business days. E-wallets and Interac are faster.
Can I play on mobile?
Yes, the site works on mobile browsers without an app.
Which games contribute most to the wagering requirement?
Slots usually count 100%. Table games may count less.
Are there responsible gaming tools?
Yes, players can set deposit limits, time-out periods, or request self-exclusion.
Can I try games for free?
Many slots and some table games offer demo play without real money.
OMG Casino provides a straightforward layout, a signup reward, a deposit match bonus, and a mix of slots, table games, and live dealer options. Clear payment terms and responsible gaming tools make it a practical choice for Canadian players. Seasonal promo campaigns also provide variety throughout the year.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulation | Sep 24, 2025

Image: Freepik
On September 13, 2025, Thailand froze approximately 3 million bank accounts in a sweeping anti-scam campaign. Authorities targeted around 177,000 mule accounts linked to fraud. Wisit Wisitsora of Thailand’s Digital Economy and Society Ministry stated:
“We urge the public not to panic. The suspension is only temporary.”
Banks imposed daily transfer caps ranging from 50,000 to 200,000 baht (approx. $2164 CAD - $8657 CAD at today's forex rates) and froze flagged transactions.
Commercial banks could suspend funds for three days, with police empowered to extend freezes up to seven days. While designed to curb online fraud, many individuals and small businesses described being locked out of their only source of funds, leaving households unable to pay for food or bills.
Facing backlash, regulators introduced safeguards. Innocent users can now expect restoration within hours to one day. Banks are required to notify customers of freezes via SMS or mobile banking and to unfreeze wrongly blocked funds proactively. Officials emphasized that disputed amounts are suspended, not entire balances.
Around the world, regulators from the EU to the U.S. and Canada are grappling with similar challenges as regulators expand digital fraud controls. What the Thailand case shows is that the credibility of financial systems depends not only on the strength of anti-scam tools but also on transparent safeguards.
If freezes become a blunt instrument, they risk driving people out of regulated channels and weakening financial inclusion. For fintechs and policymakers, the global lesson learned is that fraud prevention must be paired with due process to preserve trust.
Fraud-related losses in Thailand exceed 6 billion baht annually (approx $200M CAD), but freezing millions of accounts without due process undermines trust in banking.
"The Thai case clearly shows the risk when rapidly scaled enforcement collides with consumer rights. Without transparent criteria, real-time notifications, and clear appeals, innocent users face financial harm."
Legal experts warn this could expose authorities to civil claims and property rights challenges. What if citizens turn to cash, crypto, or unregulated channels instead?
Canada faced a similar backlash during the 2022 trucker protests, when the government invoked the Emergencies Act and froze over 200 bank accounts containing nearly $8M CAD without court orders. The measures were lifted within days, but the incident triggered several knee jerk reactions and lasting debate about transparency, due process, and the role of financial institutions in enforcing emergency powers.
Similar debates are underway in other regions, such as the United States with proposals like the Fairness in Banking Act, which NCFA has examined for its consumer protection impact. The common challenge is ensuring that stronger enforcement powers don't override due process or weaken trust in financial systems.
Both the Thailand crackdown and the Canadian freeze highlight how well intentioned interventions can spiral into government overreach if consumer safeguards are weak. Independent oversight, transparent criteria, communication protocols, and effective redress mechanisms are essential.
As fintechs use AI to spot fraud, regulators need to keep rules fair and accountable. Protecting consumers while keeping trust in financial services is key to Canada’s future growth and inclusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Funding | Sep 24, 2025

Image courtesy of PRNewswire, Mycroft
On Sep 22, 2025, Toronto-based AI startup Mycroft announced that their agentic AI Security and Compliance Officer has emerged from stealth with $3.5 million USD in seed funding to accelerate product development and expand its reach. The funding round was led by Luge Capital with participation from Brightspark Ventures and Graphite Ventures, alongside existing investors Ripple Ventures, Developer Capital, Antler, BoxOne Ventures, and strategic angels.
This latest round follows a $1.2 million USD pre-seed round last September 2024, reported by BetaKit. Together, the two rounds bring Mycroft’s total funding to approximately $4.7 million USD.
The new capital will go towards product enhancements, expanded go to market initiatives, and scaling up operations. According to SecurityWeek, the platform currently offers modules for cloud security, device security, application protection, and audit preparation. The strategy is a direct response to increasing demand for automation in enterprise compliance and security, as companies face escalating compliance requirements from regulators around the globe.
Security and compliance functions have traditionally been fragmented across multiple tools, manual processes, and spreadsheets. Mycroft’s core innovation is a single AI-driven platform that acts as a Security and Compliance Officer. Behind the scenes, it is powered by no-code AI agents that handle specialized workflows such as monitoring cloud infrastructure, enforcing security policies, managing incidents, and preparing for audits. This design gives companies one platform to manage security and compliance, while multiple no-code AI agents work in the background on specialized tasks.
Mike Kim, Co-founder and CEO of Mycroft:
“Security shouldn’t be a burden. It should be a superpower. Our goal is to give every company access to enterprise grade security without needing a massive team. Mycroft’s AI agents don’t just automate tasks, they elevate the way teams operate, helping them move faster and stay protected from day one.”
Although Mycroft was in stealth mode, they have already signed more than 50 customers in its first six months. Early adopters include Superwhisper, Evolo, CoVet, Unified, Willful, Wisedocs, and Weave (YC25). The rapid uptake for enterprise grade security and compliance solutions highlight clear market need, especially among fast growing tech companies.
Karim Gillani, General Partner at Luge Capital highlights the importance of placing compliance at the center of trust:
“Security and compliance have evolved from manual back office functions to front line priorities that can shape customer experiences and brand reputation. Mycroft’s AI Security and Compliance Officer is the teammate that every company needs in order to stay safe.”
The AI security sector is increasingly crowded, with startups and established firms racing to deliver solutions in cloud protection, identity management, governance, and audit readiness. Mycroft differentiates itself by focusing on autonomous agentic AI that operates with minimal configuration and delivers end to end compliance outcomes. It offers a cost efficient alternative for startups and mid sized companies that lack large security operations teams.
By integrating modules that span from device security to regulatory audit support, Mycroft aims to give scaling companies confidence to grow while maintaining compliance.
Mycroft is well positioned to pursue sectors with heavy compliance such as fintech, healthcare, and SaaS. As regulations tighten globally, demand for solutions that can act as a virtual compliance officer is expected to grow. For more details, visit Mycroft’s official site.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Innovation | Sep 24, 2025
Image: Freepik
On September 16, 2024, Counterforce Health reported that U.S. platforms are using artificial intelligence to help patients appeal denied health insurance claims by analyzing rejection letters and generating tailored responses at scale.
The rise of AI powered tools is a growing insurtech trend where technology is being used to challenge entrenched industry practices that unfairly hurt consumers. For NCFA's community, the story raises important questions about where AI could play a similar role in our own insurance markets.
Let's look at the data to better understand the scope of the problem. In 2021, insurers on the federal HealthCare.gov marketplace denied about 17% of in network claims. These are services from doctors and hospitals already under contract with the insurer, showing that even approved providers faced a high denial rate.
Yet fewer than 0.2% of these denials were appealed, despite nearly 59% of appeals being successful when filed.
Separate research from the American Medical Association found that prior authorization denials are overturned more than 80% of the time when challenged, but only a small share of patients ever appeal.
The above figures point to a structural imbalance where insurers rely on consumers giving up. By automating appeal letters with expertly assessed supporting evidence, AI systems are changing the game.
Canada’s universal healthcare system means most core medical services are covered publicly, so denials are less about hospital visits or surgeries and more about supplemental benefits such as prescription drugs, dental care, physiotherapy, and other extended health services. Private insurers play a major role in these areas, and disputes are common.
What Canada lacks is transparent national reporting on denial and appeal rates. Unlike the U.S. system where denial data is published for marketplace insurers, Canadian insurers are not required to release such information. The limited statistics that do exist come from independent research or regulator snapshots, which highlight problems but don't provide a complete national picture. This lack of transparency creates a barrier to accountability and also an opportunity for Insurtech innovators.
Even without standardized national data, the available evidence shows that denial issues are widespread across several types of insurance:
Disability insurance denial rates are high. For example, about 60% of Canada Pension Plan disability applications are rejected, a figure that highlights the steep barriers claimants face, even if it is not directly comparable to private disability insurance.
In Quebec, 20% of critical illness and life insurance claims are denied according to the Autorité des marchés financiers. Disputes often stem from exclusions or non-disclosure clauses.
Extended health and drug benefits. Expensive specialty drugs and therapies are frequently denied as “not medically necessary” or outside policy coverage. Appeal processes can be slow and opaque.
Accident benefit disputes are frequent, especially with auto insurance in Ontario. The provincial tribunal system handles thousands of contested denials each year. AI insurtech solutions could help provinces reduce backlogs and streamline case processing.
Property insurance denials are common enough. Regulators report that property insurance denial ratios are around 16%, with most rejections tied to lack of coverage.
For fintech and Insurtech players, the opportunity spams the broader insurance ecosystem. AI could provide consumers with tools to navigate opaque processes, improve transparency, and reduce the cost of disputes.
Regulators have already outlined pan-Canadian guiding principles for responsible AI in health systems (Health Canada), establishing an innovation framework that balances fairness and accountability.
With insurance denial data so limited in Canada, new platforms that integrate appeals with data collection could simultaneously drive consumer protection and market competitiveness.
Denial data transparency can expose inefficiencies between insurers and individuals and AI solutions can help rebalance power. While Canada’s insurance system is structured differently than the U.S., denial disputes are still widespread and certainly costly in terms of time and money for stakeholders.
Fintechs and insurtech innovators should view this is a market opportunity while also protecting consumers. Canada can either wait for U.S. platforms to cross the border, or develop homegrown solutions that lead in fairness, transparency, and competitiveness.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 24, 2025
Image courtesy of Flipper AI DEX
The Open Network (TON) Telegram games leverage blockchain technology to offer decentralized, secure, and transparent gaming for all users. Beginners can enjoy simple and readily accessible gameplay by playing TON games on Telegram. These games provide you with a simple way to explore the growing world of crypto and blockchain technology powered by Telegram’s vast user base. There are several Telegram gaming products that incorporate decentralization, smart contracts, and blockchain integration. Decentralization enables game data and logic to be shared across a network of computers securely and transparently. From ensuring fairness to creating monetary reward opportunities, TON offers several benefits to gamers.
Telegram’s platform not only offers opportunities for dApps within the ecosystem, but it also introduces user-friendly in-game economies. This combination lets developers build more advanced and interactive crypto gaming applications that players can trust. As more users continue to embrace TON, you can expect to see new and innovative gaming solutions that blend entertainment with real-life monetary benefits. Here are some great reasons to play Telegram TON games as a beginner.
Telegram TON games come with minimalistic designs. They are developed with simple and engaging gameplay in mind. This makes them vital entertainment tools for beginners looking to transform their online crypto gaming experiences. For those who prefer short gaming sessions, TON could be the perfect way to escape from everyday distractions and experience fun to the max. Newcomers can utilize reliable decentralized exchanges, like Flipper DEX, to earn free crypto tokens, including NOTCOIN. You can find tutorials and guidance to level up your skills and achieve your objectives in no time.
Potential for real rewards is another huge benefit of playing Telegram TON games. Popular play-to-earn Telegram models like TON allow users to accumulate virtual financial assets by completing basic tasks like tapping and swiping. You can convert your in-game currencies into actual crypto tokens like NOT and Hamster Kombat. Another great reason to play Telegram games is their low-cost entry. Beginners can start earning money without making any initial investment. While some Telegram crypto games offer upgrades or features that users can choose to purchase, it’s worth noting that these are not always required to start.
Thanks to the built-in community and social features, Telegram TON games lets players engage with their friends or join squads to conduct missions and compete on leaderboards. If you want to add fun and a social layer to your crypto gaming experience, you should consider taking advantage of TON Telegram games. Social media referral awards help create bonuses for beginners who invite their friends to play. These are primarily designed to motivate more players to explore the expanding world of Telegram games and boost their earning potential.
TON stands out in the blockchain ecosystem due to its relatively high speed and affordable transaction fees. Whether you’re a beginner or pro, you can interact with the crypto space directly and benefit from smooth experiences in a low-risk environment. There is no doubt that TON-based wallet integration is one of the easiest entry points into web3.
Telegram TON crypto games have gained widespread popularity lately thanks to their ease of access and community-driven experiences. The remarkable success of The Open Network onboarding millions of web3 users has played a key role in enabling beginners to build their digital assets portfolios.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Stablecoin Research | Sep 23, 2025
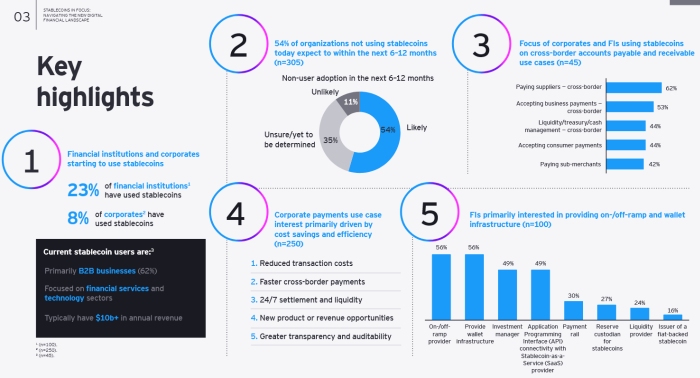
Image: Stablecoin Survey Research Highlights (EY Parthenon Sep 2025)
On September 15, 2025, EY-Parthenon released its latest stablecoin survey results, "Stablecoins: Adoption, Optimism, and Regulatory Clarity" (download 31 page PDF), covering 350 executives from corporates and financial institutions across the US, EMEA and other regions. Research takeaways confirm adoption is picking up speed, supposed by regulatory clarity by the GENIUS Act, recently signed into law.
Why is this happening? Approval of the U.S. GENIUS Act is a regulatory catalyst. Further, pilots are proving real value and corporate treasurers are under pressure to improve efficiency. The thinking is that organizations delaying adoption risk losing ground to competitors who are moving forward and benefiting from the lower cost and faster transactions of stablecoin technologies.
Why is everyone saving money by using stablecoins? The reason is straightforward. Traditional cross border payments involve multiple intermediaries, each adding fees and time. Stablecoins bypass these frictions and settles instantly, so the cost savings are structural (not incremental). For fintech providers, there's a growing opportunity to provide integration and risk management tools to help corporates adopt/use stablecoins and measure their effectiveness.
The reality is that we live and function in a global economy where delays can disrupt supply chains, so it's not surprising that corporates will adopt stablecoins for faster and more streamlined and predictable settlement solutions. This means that stablecoin adoption will likely strong and swift among B2B supplier and trade finance flows before expanding more widely into consumer payments.
In Canada, regulatory inaction is catching up with market momentum. On September 19, 2025, regulators like OSFI have warned the Prime Minister Mark Carney that Canada should accelerate federal stablecoin rules to avoid falling behind global peers. The Bank of Canada has echoed this call, saying stablecoins should be as safe and stable as the balance in your bank account. OSFI is already drafting a new framework to regulate stablecoin issuers, while domestic momentum is building as Tetra Digital Group secured $10M from Canadian banks and fintechs to launch a CAD stablecoin in 2026. Observers including investor John Ruffolo warn in his Looming Stablecoin Storm substack that without clear domestic rules, Canada risks ceding innovation, competitiveness and monetary sovereignty to jurisdictions that move faster.
Canadian corporates and fintechs need to plan not just for current global trends, but for a new local regulatory stablecoin framework. Firms are advised to engage with policymakers to create the right environment, build compliance ready infrastructure now and position for interoperability with USD pegged tokens and domestic stablecoin initiatives.Waiting could result in higher compliance costs, restricted access, and eventually a decline in market share.
Bottom line is banks understand that clients will demand stablecoin services and that failure to provide them risks their disintermediation. There's an intensifying race between traditional institutions and fintech challengers to capture stablecoin transaction flows.
Hybrid build and partner strategy. Corporates are demanding trust and compliance, while financial institutions know they cannot deliver the full stack alone. This means that partnerships between fintechs, banks and technology providers will determine how quickly stablecoin adoption scales.
Stablecoins are moving from pilot projects into enterprise strategy. Corporates see real cost savings and competitive advantage, while financial institutions are preparing to build services at scale to meet client demand. Regulation is beginning to catch up, led by the GENIUS Act in the US, but the global landscape is unbalanced while Canada’s fintech ecosystem is calling on the federal government to create and regulate a stablecoin framework to remain aligned and competitive.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016