




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 27, 2026 | NCFA Market Activity | Funding, Risk Compliance And Regtech, Banking And Credit Infrastructure
On May 20, 2026, Toronto based Quantum Bridge Technologies announced a USD $8M Series A round to expand its quantum safe cybersecurity business for financial institutions, telecom networks, governments, and defence organizations. The University of Toronto spinout says the financing brings its total funding to USD $16M.
Quantum Bridge’s DSKE technology helps organizations create, distribute, and manage symmetric keys across existing networks. The company says customers can add the system across current vendors, security layers, and network environments without replacing core infrastructure.
The timing makes sense given that NIST released its first three post quantum encryption standards in August 2024 and urged system administrators to start moving to the new standards. In Canada, the Cyber Centre’s post quantum migration roadmap gives federal departments a planning model for transitioning non classified IT systems to post quantum cryptography.
Canada has strong, award winning quantum researchers. Buyers need tools they can audit and apply to real networks at scale. Quantum Bridge is actively pitching that to the market directly, and not asking customers to wait for a future quantum event. It's selling a migration solution for institutions that already manage long lived data, critical communications, and regulated infrastructure.
That connects directly to fintech. Payments, digital identity, custody, banking APIs, cloud security, and customer data protection all rely on cryptography. Infrastructure teams are in need of cryptographic agility before regulatory pressure and vendor bottlenecks make upgrades harder.
The Series A gives Quantum Bridge more room to sell into high trust markets where procurement takes time and credibility counts. The investor group also tells a useful story. The round brings together venture capital, telecom exposure, enterprise technology, and cross border capital. That mix fits a company selling security infrastructure into finance, telecom, government, and defence.
Mattia Montagna, Co Founder and CEO, Quantum Bridge Technologies:
“National security can’t wait for perfect conditions. We build quantum-safe systems that work inside real networks today — systems designed to keep protecting sovereign communications as the threat landscape evolves. This funding means we can meet more organizations where they are, and get them protected faster.”
Quantum Bridge’s financing shows where Canadian quantum policy needs to support execution. Canada should help qualified domestic firms prove their systems inside critical sectors before global buyers define the market without us.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 26, 2026 | NCFA Insight | Payments And Market Infrastructure, Regulation And Policy, Digital Assets Blockchain And Tokenization
The Fed is proposing limited settlement accounts for eligible firms. The bigger question is whether the U.S. gives qualified fintechs a cleaner infrastructure advantage than Canada.
On May 26, 2026, the Federal Reserve published a Federal Register proposal for special purpose Payment Accounts. Legally eligible institutions could use them to clear and settle certain payment activity through Reserve Bank accounts. Comments are due by July 27, 2026 under Docket No. OP-1878.
The proposal isn't open access to the Fed. Payment Accounts would have no intraday credit, no discount window access, no interest on balances, no correspondent activity, and no respondent activity. Closing balances would generally be capped at $1B. The account would support approved payment settlement, not full banking privileges.
Jerome H. Powell, Fed Chair said:
“The proposed payment account would be tailored to support innovation by serving the clearing and settlement needs of certain eligible institutions while also mitigating material risks to the Reserve Banks and payment system.”
A Master Account gives an eligible institution direct access to Reserve Bank balances and Federal Reserve payment services. The proposed Payment Account is narrower in scope. Firms would not borrow from the Fed, earn interest, receive daylight overdrafts, or use the account as a correspondent banking platform.
The Fed is testing whether limited settlement access can exist without full banking access.
Fintechs, crypto firms, trust companies, and novel chartered institutions have pushed for Fed access because sponsor bank dependence affects cost, timing, liquidity, and settlement certainty. Banks have pushed back because wide access can raise compliance, liquidity, and regulatory arbitrage concerns.
In 2022, the Fed finalized Account Access Guidelines with a tiered review framework. The toughest review applies to institutions that are not federally insured and are not subject to federal prudential supervision at the institution or holding company level.
The 2026 proposal doesn't replace that framework. It creates a tighter account model inside the same access debate.
The proposal discusses use cases raised by commenters, including stablecoin issuer reserve operations, tokenized securities settlement in central bank money, tokenized assets, pay by bank checkout, B2B transfers, instant wages and refunds, and the U.S. dollar leg of cross border transactions.
Those use cases point to the same operating need, clean settlement. Stablecoin issuers need reliable reserve movement. Tokenization platforms need cash settlement closer to central bank money. PSPs need faster payment settlement. Pay by bank providers need lower cost routing. Cross border firms need cleaner dollar leg execution.
Today, many fintechs settle payments through sponsor banks. A fintech sends payment instructions, but the actual settlement usually happens through a commercial bank account connected to central bank rails.
Under the Fed proposal, an approved firm could potentially hold limited settlement balances directly at a Reserve Bank for approved payment activity. That could reduce some dependence on sponsor banks for specific flows.
For a stablecoin issuer, that could improve reserve movement and redemption settlement.
For a pay by bank provider, it could streamline payment routing.
For a tokenization platform, it could support settlement closer to central bank money instead of relying entirely on commercial bank ledger movement.
The proposal would not turn fintechs into banks. Firms would not receive deposit insurance, emergency liquidity, or unrestricted Fed access.
If eligible U.S. firms gain limited Reserve Bank settlement access while Canadian firms remain more dependent on bank intermediaries, U.S. fintechs could gain an operating edge in payment speed, settlement certainty, reserve movement, and cost control.
That edge is important for stablecoins, tokenized securities, pay by bank, B2B payments, cross border transfers, and embedded finance. These markets compete on speed, liquidity use, compliance reliability, and integration cost.
It could also change sponsor bank negotiations. A firm with a credible settlement alternative has more leverage than one with no alternative.
| Question | U.S. Fed Payment Account Proposal | Canada RPAA Registered PSP | Canada Payment Rail Participation |
|---|---|---|---|
| Live today? | No. Proposal only. | Yes | Yes |
| Can hold settlement balances at the central bank? | Only if final rules approve it and the firm qualifies. | No | No by participation alone. |
| Can settle some payments through a central bank account? | Would apply only to approved payment activity. | No | RTR may allow direct settlement for eligible participants that qualify for Bank of Canada settlement accounts. RPAA registration alone doesn't. |
| Still needs sponsor banks? | Yes, but dependence could fall for approved settlement flows. | Yes | Yes, in many cases. |
| Gets full banking powers? | No | No | No |
| Main benefit | Potentially cleaner settlement for stablecoins, tokenized assets, pay by bank, and cross border dollar flows. | Legal operation under Bank of Canada supervision. | Access to payment rails and network participation. |
Canada’s retail payments framework brings PSPs into Bank of Canada supervision. The PSP registry under the RPAA confirms registration status, required fees, and national security screening. Registration does not itself provide limited direct settlement access.
Payments Canada says the Real Time Rail will launch in Q4 2026 as Canada’s instant, data rich exchange and clearing and settlement payment system. RTR is expected to broaden access for eligible participants, including PSPs that meet applicable requirements.
Canada has also legislated a fiat backed stablecoin framework, with detailed rules and implementation still being developed. The framework helps define issuer obligations around reserves, redemption, governance, data security, and Bank of Canada oversight. It does not itself provide payment rail access or limited direct settlement access.
The competitive question is not whether Canada should copy the Fed. It's whether Canada can give qualified PSPs, stablecoin issuers, and tokenization firms a clear access ladder from supervision to rail participation to settlement. If U.S. firms gain a narrow Fed settlement lane while Canadian firms wait for comparable clarity, product speed, treasury efficiency, and sponsor bank leverage may tilt south.
If U.S. firms get limited central bank settlement access, what should Canada let supervised PSPs access once they meet higher standards?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 26, 2026 | NCFA Insight | Risk Compliance And Regtech, Digital Assets Blockchain And Tokenization, Payments And Money Movement

Canada’s revoked MSB registry shows where payments, crypto, FX, and money transfer compliance risk is concentrated.
On May 21, 2026, FINTRAC modeified the public revoked money services business registry, currently showing 396 revoked registrations within the broader MSB registry of 7,745 firms. These revoked registrations span multiple years, but some quick analysis shows where payments, crypto, FX, and money transfer compliance risk is concentrated.
Below we show the total number of revoked registrations (396) by revocation year:
The registry is cumulative, but 2022 and 2026 stand out with greater numbers. The 2022 spike may reflect several factors, including delayed compliance reviews, expired or inactive registrations, pandemic era business disruption, and firms failing to respond to FINTRAC requests or update operating information.
The 2026 peak shows revocations are active again, but the registry doesn't explain why each firm was removed.
Of the 151 registrations revoked in 2026:
These activity counts exceed 151 because many businesses offered multiple services under one registration. They operated across money transfer, FX, virtual currency, PSP activity, and sometimes crowdfunding or money order services at the same time. That combination can make compliance harder because one firm may need controls for several activity types at once.
Wallets, stablecoin services, remittance platforms, crypto OTC desks, merchant payout tools, and embedded finance products often cross several regulatory categories. Companies building in these areas need clearer service mapping, stronger AML controls, and faster regulatory response processes.
By Province:
By City:
The above counts simply show where revoked registrations are concentrated in the dataset. Vancouver and Toronto are also major hubs for payments, FX, crypto services, incorporation activity, and cross border commerce, so higher counts likely reflect market density as well as supervisory attention.
MSBs must keep records, verify client identity, maintain a compliance regime, report certain financial transactions, and register their business. FINTRAC can revoke registration when a business becomes ineligible, misses a clarification request deadline, fails to respond to information demands, fails to update operating information, or fails to assist the Centre.
Founders should treat MSB registration as an active regulatory relationship. Address changes, service category changes, ownership changes, agent changes, and compliance officer changes all need disciplined tracking. Compliance teams should also review whether real business activity still matches registered categories, especially where firms blend payments, crypto, FX, remittances, PSP activity, and embedded finance.
Investors should add registry hygiene, AML staffing, virtual currency exposure, PSP activity, and regulator response history to diligence checklists. Growth can hide weak compliance operations for a while, but public registries can make those weaknesses visible.
This all aligns with recent Canadian oversight changes, such as the Bank of Canada’s PSP Registry under the RPAA, new Bank of Canada guidance for PSPs, and FINTRAC’s focus on Bitcoin ATM money laundering risks.
Which crypto firm looks stronger to regulators, investors, and banking partners: one that treats compliance as paperwork, or one that builds it into the operating system?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 26, 2026

Phones are aging strangely now. A device can still work perfectly fine for everyday stuff, yet the ecosystem around it keeps changing so quickly that the phone starts feeling behind anyway. One month, it is AI features, then cloud syncing updates, then storage demands, then camera processing upgrades that somehow make older devices feel slower overnight. Modern tech culture no longer waits for hardware to completely fail before pushing consumers toward something newer. The ecosystem itself creates the pressure.
All of this completely changed consumer habits around ownership, especially in countries like Canada. Smartphones used to feel like long-term purchases people held onto without thinking much about resale timing or upgrade windows. Now there is much more attention on value retention, compatibility, software support, and ecosystem access.
The biggest difference now is that upgrades happen before frustration fully sets in. A phone may still handle texting, photos, streaming, and apps normally, yet newer releases quickly introduce features that make older models feel disconnected from where the ecosystem is heading. AI editing tools, battery optimization improvements, smarter search functions, and better cross-device syncing quietly change expectations every year.
You might decide to sell your iPhone as part of a normal tech planning instead of something you’d consider after damaging a device. Canadian consumers often pay attention to resale timing because value drops quickly once a model starts feeling outdated socially or technically. Faster ecosystems trained buyers to think ahead rather than simply waiting for a phone to stop functioning completely.
Trade-in culture removed a lot of hesitation surrounding smartphone upgrades. Older upgrade habits usually involved buying a completely new phone while the previous one sat unused somewhere inside the house afterward. Now the old device immediately becomes part of the financial conversation surrounding the next purchase.
Tech companies leaned heavily into that behaviour because it keeps consumers moving through upgrade cycles faster. Trade-in estimates appear during launch events, checkout pages, carrier promotions, and even software notifications. The process feels smoother because consumers mentally subtract the old device value before fully processing the actual cost of the new phone.
Ecosystem compatibility has become one of the biggest reasons consumers stay loyal to certain brands now. The phone itself matters, but the experience surrounding it matters even more. Messages syncing instantly across devices, earbuds switching automatically, photos appearing everywhere immediately, and passwords carrying across platforms quietly shape daily routines much more than people expect.
Once consumers get used to that convenience, switching ecosystems feels surprisingly disruptive. A slightly stronger camera or better hardware feature often matters less than keeping everything connected smoothly without interruptions. Modern tech culture depends heavily on reducing friction, and ecosystem compatibility has become one of the strongest tools companies use to keep consumers upgrading within the same environment repeatedly.
AI features accelerated upgrade conversations because they create a different kind of pressure compared to older smartphone trends. The issue is not necessarily that older devices stop working. Instead, newer software experiences increasingly depend on hardware that older phones cannot fully support.
That creates a situation where consumers feel excluded from evolving features before their current phone actually feels unusable. AI photo cleanup, live summaries, contextual assistance, advanced search tools, and smarter automation systems all push the ecosystem forward quickly. Older devices still function for basic tasks, yet they begin missing experiences that newer phones treat as standard.
Faster upgrade cycles created huge growth in refurbished tech markets because consumers no longer view slightly older smartphones the same way they once did. A phone released one or two years ago still feels modern enough for most daily routines, especially once prices drop significantly below newer flagship models.
Buying refurbished now feels practical rather than outdated because consumers understand how quickly newer hardware enters resale circulation. Constant upgrade cycles feed the secondary market with devices that still support modern apps, ecosystem syncing, strong cameras, and current software features. Some consumers chase the newest release immediately, while others intentionally stay a generation or two behind because the overall experience still feels smooth enough without paying full launch pricing every single cycle.
Modern tech decisions are increasingly built around convenience instead of raw hardware alone. Consumers pay attention to how smoothly devices connect across everyday routines because phones now sit at the center of work, entertainment, payments, navigation, messaging, storage, and smart home systems all at once. Once everything starts syncing properly, small interruptions suddenly feel much more irritating than they used to.
A device that connects cleanly with earbuds, watches, laptops, tablets, cloud systems, and payment apps creates habits people do not want to disrupt later. The smoother the ecosystem feels, the more likely consumers are to stay loyal to it during future upgrades. Convenience also supports remote workers, especially through IoT.
Storage pressure became one of the biggest reasons phones start feeling old faster than expected. Photos are larger, videos take up more space, apps hold heavier data, and cloud backups constantly run in the background. Even casual smartphone use now creates massive amounts of digital clutter compared to a few years ago.
That gradual buildup changes the experience of using older devices. Phones start struggling with available space, background processing slows down, and consumers become more aware of performance limitations tied to storage demands. Social media habits, mobile editing apps, streaming downloads, and constant photo capture all accelerated the problem. Faster-moving ecosystems pushed digital consumption upward so aggressively that many devices start feeling cramped long before the hardware itself fully ages.
Software evolution changed consumer expectations surrounding older phones completely. Years ago, a device that stayed functional for calls, messaging, and internet browsing felt acceptable for a long time. Modern ecosystems operate differently because updates continuously introduce heavier processing demands, smarter features, larger apps, and more advanced background activity.
As a result, older phones often feel slower much earlier, even when the hardware technically still works. Consumers notice delays more quickly because newer devices constantly raise expectations surrounding speed, responsiveness, camera processing, and multitasking performance. The gap between “working” and “feeling current” keeps shrinking, which pushes upgrade conversations earlier than before.
Secondary tech markets became much more active because faster ecosystems create a constant flow of relatively modern devices entering resale circulation. Consumers upgrading frequently leave behind phones that still feel perfectly usable for someone else, especially once prices drop below flagship launch levels.
Buyers increasingly treat secondary markets as practical ways to access newer ecosystems without paying premium prices immediately. At the same time, sellers recover value from devices before depreciation becomes too steep. Faster upgrade cycles basically created an entire parallel market where devices continue moving between users instead of disappearing once the original owner upgrades.
Faster-moving tech ecosystems completely changed the way consumers think about smartphones, upgrades, ownership, and resale value. Devices now function as constantly evolving parts of larger ecosystems tied to software, cloud systems, AI tools, connected devices, and daily routines that keep changing year after year.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 26, 2026 | NCFA Resource | Artificial Intelligence And Data, Risk Compliance And Regtech, Payments And Market Infrastructure
On May 15, 2026, the Bank of Canada published Integrating Non-traditional Data and AI into Central Banking. The staff paper examines how central banks use artificial intelligence and non traditional data in research, operations, payments monitoring, forecasting, and policy support.
The paper stays close to real operating problems. It focuses on data quality, model governance, human oversight, vendor risk, cybersecurity, and moving AI pilots into production.
The paper shows how central banks use non traditional data from payment transactions, earnings call transcripts, satellite images, job postings, social media, scanner data, and real time business activity. It also explains how AI supports inflation tracking, nowcasting, anomaly detection, payments monitoring, internal automation, and policy work.
One Bank of Canada automation project improved filing accuracy to 99.5% and saved about 1.25 person years of staff capacity. The paper also cites a BIS survey showing more than 90% of responding central banks are moderately or extensively discussing AI internally.
The most useful section sets out six accelerators for responsible AI adoption in central banking. They include sandbox environments, technology readiness checks, high quality data, reusable development patterns, scale planning, and risk governance. The framework also applies to regulated financial institutions that need to transition AI from experiments into controlled production, similar to broader work underway around customer due diligence controls for fintechs.
This resource is useful for fintech founders, AI governance teams, regtech providers, financial institutions, payment companies, policy teams, investors, and compliance leaders.
It is especially relevant for teams building explainable AI, payment intelligence, anomaly detection, compliance automation, model governance, and trusted workflow tools.
The strength is its operating detail and the fact that the paper doesn't treat AI as a generic productivity story. It shows why regulated financial institutions need explainability, auditability, strong data controls, and clear ownership before AI can support high stakes decisions.
The paper also points to a real market gap. Central banks may need specialized AI tools and deeper in house expertise because many commercial systems are not designed for monetary policy analysis, payments oversight, or central bank operations.
The limit is scope. This is a central banking paper, not a commercialization guide. It does not estimate vendor spending, market size, adoption timelines, or private sector demand. Its value is the framework and the operating discipline behind it.
Bank Of Canada AI And Non Traditional Data Paper (primary Bank of Canada resource)
AI Agents Enter Governed Financial Workflows (AI governance and controls)
Tokenization Starts Looking Like Financial Infrastructure (regulated financial infrastructure)
Deloitte And Stablecorp Bring QCAD To Banks (Canadian payment infrastructure)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 25, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization
On May 20, 2026, 3iQ selected Anchorage Digital as the infrastructure and custody partner for its Canadian product suite. Subject to regulatory approvals and required prospectus or offering document amendments, 3iQ intends to migrate a significant portion of assets under management across six TSX listed exchange traded products to Anchorage Digital.
3iQ is a Canadian digital asset investment manager with a regulated public product suite. Anchorage Digital became the first OCC approved national crypto bank in the U.S. Canada has qualified digital asset custodians, but not an equivalent national crypto bank structure at Anchorage’s scale. The decision puts a hard question in front of Canada’s digital asset sector. Can Canadian infrastructure win large institutional mandates when issuers need custody, settlement, staking support, and regulatory comfort at scale?
The warning is now showing up in market activity. Canada has already debated whether domestic digital asset infrastructure can compete with larger U.S. regulated platforms. That issue became more visible when Balance applied for a Canadian special purpose trust structure to build institutional digital asset custody capacity at home.
If Canada approves digital asset products but doesn't build trusted infrastructure at home, more of the work, jobs, and revenue may migrate south. In this case, 3iQ keeps the Canadian listed products while Anchorage Digital captures more of the custody and infrastructure work behind them.
That choice is commercial, not patriotic. Large issuers choose the stack that lowers operating risk and helps them launch better products. That’s the reality test Canadian infrastructure providers now face.
3iQ says Anchorage Digital lets funds settle trades from cold storage without relying on hot wallets. Its Atlas network also lets 3iQ settle directly with trading counterparties and remove extra wallet steps. It means custody now affects much more than safekeeping. It affects how funds trade, settle, manage risk, support staking, and protect investors.
The partnership is also expected to support 3iQ’s expanded staking capabilities. That raises the stakes. Staking needs more than token custody. It needs validator access, clean reporting, strong controls, and regulatory comfort. The right custody partner can give a fund more room to build. The wrong one can hold it back.
Tommaso Mancuso, President and CIO of 3iQ:
"3iQ needs infrastructure providers that meet “the highest standards for security, flexibility, and regulatory alignment.”
That is the standard Canadian infrastructure has to meet now. Canada has digital asset talent, regulated products, custody ambition, and a real institutional market. But the operating stack behind those products still needs more depth, if they want to compete. Fund issuers need platforms that can handle scale, connect cleanly to trading counterparties, support approved product features, and satisfy regulators without adding friction.
Canadian policymakers should treat this as a competitiveness warning. Product approvals aren't enough if the custody, settlement, staking, and fund operations work scales outside Canada. The goal should be to keep more trusted digital asset infrastructure, jobs, and revenue at home.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 25, 2026 | NCFA Insight | Payments And Market Infrastructure, Open Banking Open Finance And Data Sharing, Digital Assets Blockchain And Tokenization
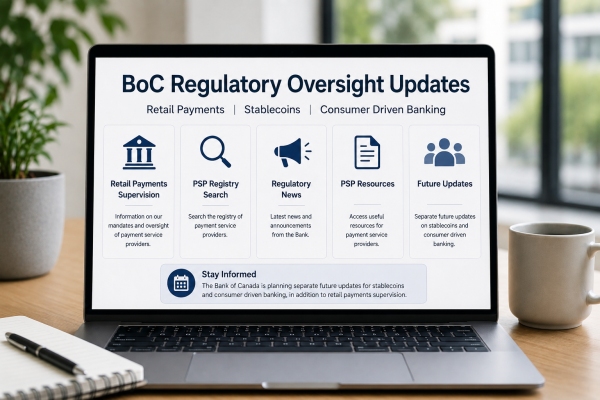
On May 25, 2026, the Bank of Canada refreshed its regulatory oversight web content and streamlined its retail payments supervision section. The update gives payment service providers a cleaner place to find key information as the Bank’s mandates expand across retail payments, stablecoins, and consumer driven banking.
The Bank says users can now more easily find information about its mandates, search the payment service provider registry, access a new regulatory news section, and browse resources for payment service providers. It's important for fintechs because RPAA supervision is evolving from policy discussion into day to day operating reality and governance.
The Bank supervises payment service providers under the Retail Payment Activities Act (NCFA covered this practical transition when the PSP registry went live under RPAA) and expects firms to meet risk management and safeguarding requirements.
In addition to retail payments supervision, the Bank of Canada also says it plans to issue separate future updates about stablecoins and consumer driven banking. It means fintechs should watch the Bank’s update streams more closely as these files progress for the latest updates and key information.
The Bank has also set up a Consumer Driven Banking Advisory Committee to provide industry perspective and advice to the Bank and the Department of Finance. The committee will focus on implementation, industry readiness, and the supervisory framework. NCFA’s open banking commercialization roadmap explains why implementation details will matter for fintech business models, data access, onboarding, and customer experience. That gives market participants a useful clue about where questions will concentrate next, such as how companies prepare, how oversight works in practice, and how consumer driven banking connects with the broader payment system.
Payment companies should use the refreshed pages as a compliance resource point. Check registry details, monitor regulatory news, review PSP resources, and make sure internal owners know where Bank updates will appear.
No new rules were announced in this email, but the Bank has made it easier to follow the official files that matter to payment companies, stablecoin operators, open banking participants. In a crowded regulatory environment, cleaner source material helps firms track changes earlier and prepare with less confusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016