




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 29, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Risk Compliance And Regtech
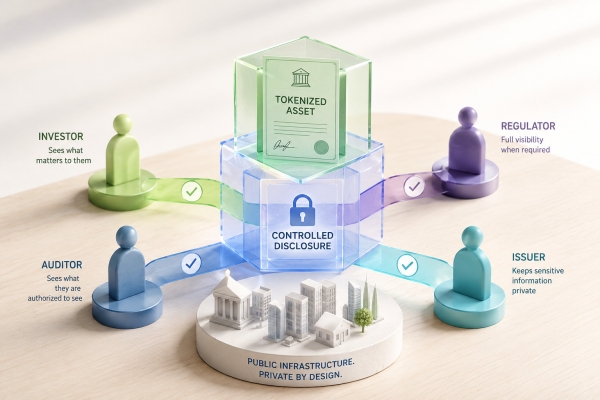
On May 27, 2026, Toronto based Polymath launched Confidential Assets on Polymesh, a protocol level privacy feature for tokenized securities and real world assets. It uses zero knowledge cryptography to keep transaction details private while preserving access for regulators, auditors, and authorized parties.
Privacy solves a practical market problem. Public blockchains can expose positions, client data, and transaction flows. Private chains can protect confidentiality, but they can also silo activity inside closed systems. Confidential Assets is Polymath aim to give regulated asset markets privacy without giving up public permissioned infrastructure.
Martin Halford, CEO, Polymath:
“The question the market has been asking is not whether assets can be tokenized -- they can. The question is whether tokenization can be done at an institutional scale, with the privacy and compliance standards that real financial infrastructure demands. Confidential Assets is our answer to that question.”
The stronger use case isn't about keeping secrets, but rather controlled disclosure. Issuers, investors, and asset managers need privacy around holdings and transfers. Yet a wide range of stakeholders from regulators to auditors, custodians, and compliance teams still need access when rules require it.
Confidential Assets is built into the Polymesh protocol, not added through a third party tool or Layer 2 solution. This allows privacy to work within the same system that handles compliance, governance, and settlement. A fund, private credit issuer, real estate platform, or broker dealer could use the feature to complete a compliant transfer without exposing position size or counterparty details to the broader market.
The ultimate goal and impact is the right mix of privacy and oversight. If Polymath gets that balance right, Confidential Assets could make Polymesh more useful for real capital markets activity, not just token issuance.
Confidential Assets is available immediately to institutions building on Polymesh. Polymath has been building regulated asset infrastructure since 2017 and contributed the ERC 1400 security token standard. Polymesh achieved SOC 2 Type 1 compliance in 2025. Polymath also says a post quantum ready version of Confidential Assets is in development for long term assets that may remain on chain for decades.
For Canadian capital markets and fintech firms, controlled disclosure is becoming core infrastructure for tokenized assets. Platforms that manage who can see what, and when, will become harder to replace in digital securities markets, over time.
Can tokenized markets reach institutional scale without protocol level privacy, or will controlled disclosure become a core requirement for regulated digital assets?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 29, 2026
Most businesses don't struggle to find digital marketing agencies. They struggle to find one that actually understands their industry, reports honestly, and ties every dollar spent back to real revenue. After reviewing dozens of Canadian agencies across service depth, client results, and transparency, a clear pattern emerged: the ones worth your budget are the ones that treat return on investment as a must-have, not a nice-to-have. This guide breaks down the top five agencies in Canada worth serious consideration heading into 2026.
The research approach for this ranking
Every agency on this list was assessed using publicly available sources: Clutch profiles, client testimonials, published case studies, award records, and official service pages. The focus stayed on agencies with a verifiable track record in digital marketing, not just strong website copy or a polished pitch deck.
-> See the full research breakdown
Picking the wrong agency doesn't just waste budget. It sets your business back months while competitors pull ahead.
The real challenge isn't finding an agency that offers services. It's finding one that genuinely understands your industry, can trace every lead back to a specific campaign, and gives you reporting you can actually trust.
Specialized agencies tend to produce better outcomes because they already know the ad platform policies, the content angles that convert, and the audience behavior patterns that matter in your space. That kind of focused experience usually shows up directly in your numbers, whether you're tracking Return on Ad Spend (ROAS), Customer Acquisition Cost (CAC), or Cost Per Lead (CPL).
The right fit doesn't just run campaigns. It moves your business forward.
Note: All data in this table is sourced from review platforms and the official websites of the listed companies.
| Company Name | Years Operating | Headquartered In | Rating |
| dNovo Group | Est. 2011 | Toronto, ON, Canada | 5/5 (Clutch) |
| Dialekta | Est. 2010 | Montreal, Toronto, and Paris | Not listed |
| Major Tom | Est. 2018 | Vancouver, British Columbia | Not listed |
| Kinex Media | Est. 2008 | Mississauga, Ontario, Canada | Not listed |
| Marvel Marketing | Est. 2014 | Calgary, AB | Not listed |
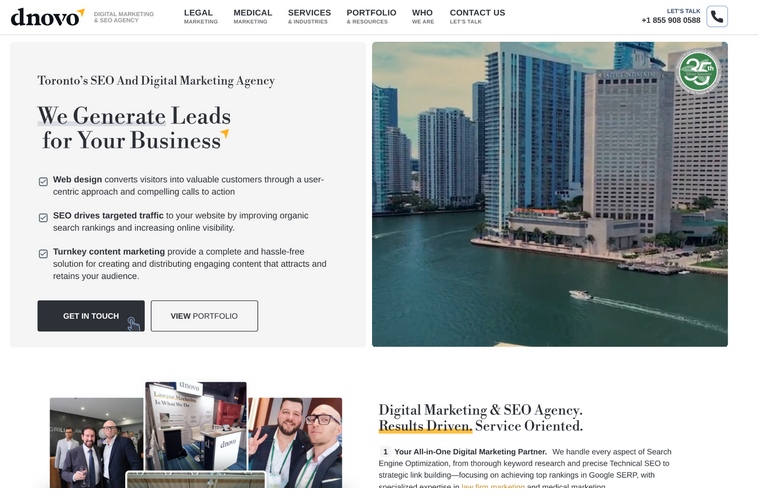
What Does dNovo Group Do?
dNovo Group is a Toronto-based boutique agency founded in 2011, built around legal and healthcare marketing. They cover SEO, Local SEO, AI Search Optimization, Google Ads, web design, and content marketing for law firms and medical practices across personal injury, criminal defense, immigration, family law, and more. What sets them apart is the fully in-house team structure. Every campaign is built and managed internally, which means accountability stays in one place and results don't get lost between vendors.
Why dNovo Group Stands Out for Digital Marketing:
The agency fills a specific gap for law firms and healthcare practices that need a marketing partner who already understands their industry's advertising restrictions and client acquisition dynamics. From what the case study data shows, that kind of sector-specific focus tends to produce results that general agencies struggle to replicate at the same pace.
Summary of Real User Reviews:
dNovo Group holds a 5/5 rating across 66 reviews on Clutch, which is honestly rare at that volume. Clients consistently point to measurable outcomes, including 150% increases in qualified leads and website visitors driven by campaigns and 180% gains in client acquisition. The recognition as a Top SEO, Top Advertising, and Top Web Design company on Clutch, plus a Netty Award nomination, backs up what the client feedback is already saying.
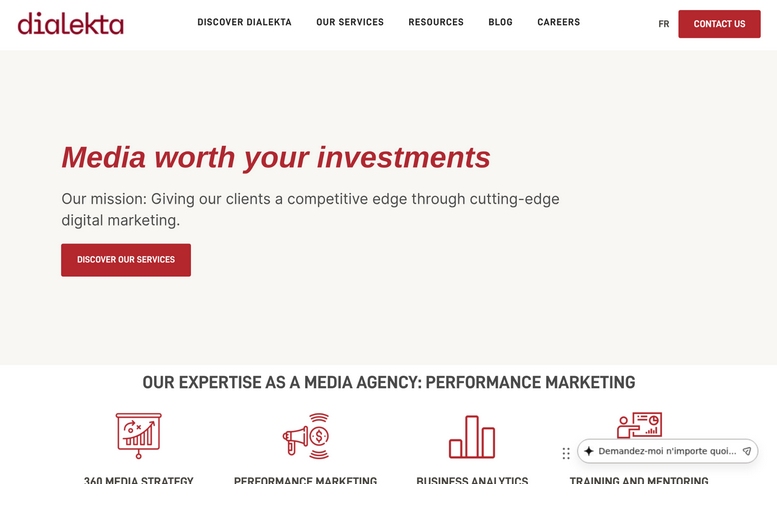
What Does Dialekta Do?
Dialekta is a Montreal-based performance marketing agency founded in 2010, and they've grown considerably since then. They cover SEM, SEO, analytics, conversion rate optimization (CRO), media planning, and business intelligence. What makes them interesting compared to others on this list is their move into traditional media in 2020 and their 2024 acquisition of Varibase, which deepened their data and loyalty marketing capabilities. They serve major Canadian brands including Vidéotron, Bell Media, Intact Insurance, and Desjardins Group (not a small client list by any measure).
Why Dialekta Stands Out for Digital Marketing:
Dialekta addresses a real challenge for mid-to-large businesses that need a single partner to connect digital and traditional media without losing performance accountability across channels. Their data activation work, built out further through the Varibase acquisition, gives clients a clearer picture of how campaigns are actually driving discovery call to signed retainer conversion, not just surface-level impressions.
Summary of Real User Reviews:
Dialekta's industry reputation carries weight, especially the Google recognition as one of six most forward-thinking companies worldwide in Search Innovation. Their client retention rates are reported as among the highest in the Canadian agency market, which suggests the results are holding up long after the initial campaign launch. Multiple Infopresse awards round out a track record that's hard to ignore for enterprise-level marketing buyers.
What Does Major Tom Do?
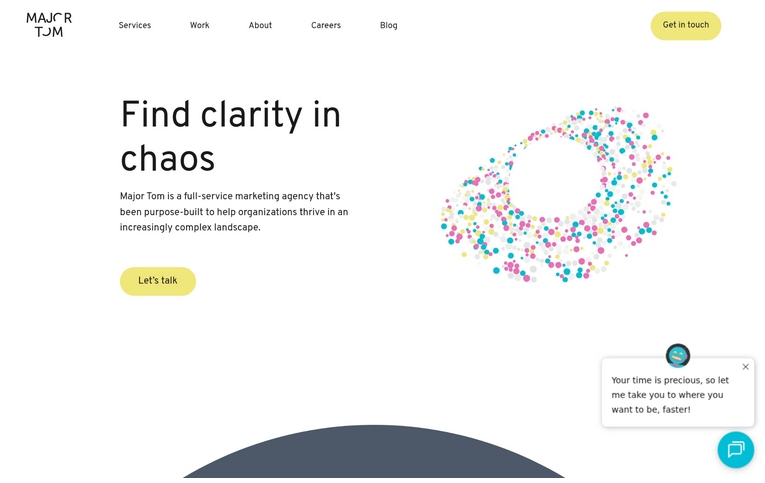
Major Tom is a Vancouver-based full-service agency formed in 2018 through the merger of 6S Marketing and Drive Digital, two respected names in Canadian digital marketing. They cover strategy consulting, web development, creative design, SEO, paid media, ecommerce, social media, content marketing, and marketing automation. Think of them as a shop that can take a brand from broad strategy all the way through to live campaign execution. Their client list includes PepsiCo, SAP, and DoorDash, which shows they can operate at serious scale.
Why Major Tom Stands Out for Digital Marketing:
The agency solves a specific problem for growing businesses that need strategy and execution under one roof, without bouncing between a consulting firm and a production agency. That merger background means their teams are genuinely skilled at both the planning side and the technical delivery, which is a combination that's harder to find than it sounds.
Summary of Real User Reviews:
Major Tom has earned recognition through the Canadian Search Awards for ecommerce work, which points to real performance in a competitive category. The combined heritage of two established agencies gives them a credibility base that newer firms can't replicate overnight. And honestly, the strength of their client portfolio across major global brands says a lot about the trust they've built with marketing buyers at scale.
What Does Kinex Media Do?
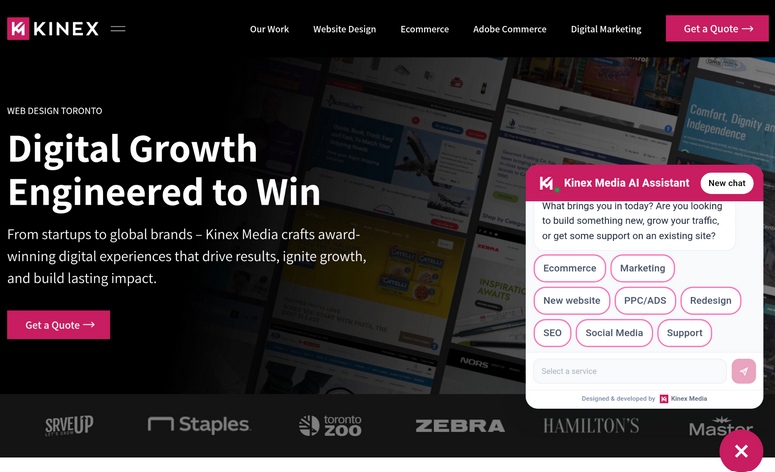
Kinex Media is a Mississauga-based agency founded in 2008, giving them over 15 years of active work in the digital space. They focus on website design and development, Magento ecommerce, SEO, SEM, and print services. What stands out about their approach is the experiment-driven model. Rather than applying a standard playbook, they test strategies on a per-client basis and adjust based on what the data shows. They've worked with more than 2,000 businesses, from early-stage startups to Fortune 500 companies (not a small range by any measure).
Why Kinex Media Stands Out for Digital Marketing:
Kinex Media addresses the frustration businesses face when agencies apply cookie-cutter strategies regardless of industry or business model. Their testing-first mindset means campaigns are shaped by actual performance signals, not assumptions carried over from a previous client in a different vertical.
Summary of Real User Reviews:
The Globe and Mail named Kinex Media one of Canada's top companies for multiple consecutive years, and they ranked #298 on The Americas' Fastest Growing Companies list in 2023. Clutch also places them among Toronto's top web design and development firms. That kind of consistent external recognition across different platforms suggests the client experience is holding up well beyond just the initial project launch.
What Does Marvel Marketing Do?
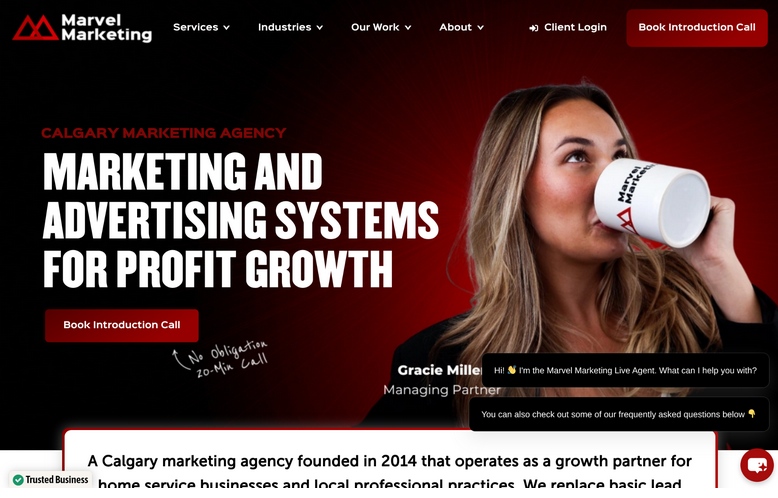
Marvel Marketing is a Calgary-based full-service agency founded in 2014, with offices in Toronto and Vancouver. They cover web design, SEO, social media marketing, PPC, content strategy, brand development, ecommerce, local SEO, and email marketing. They work across B2B, legal, real estate, automotive, franchise, trades, healthcare, and sports sectors. The thing that makes them genuinely different is their "NO RESULTS, NO PAYMENT" guarantee combined with a strict limit of three new clients per month. That kind of intentional capacity cap is rare and signals they're serious about delivering, not just scaling.
Why Marvel Marketing Stands Out for Digital Marketing:
Marvel Marketing directly addresses the anxiety businesses feel when signing long-term agency contracts without knowing if results will follow. Their human-in-the-loop execution model (no reliance on public AI models for strategic decisions) combined with SOC-2 and GDPR data compliance builds trust with clients in regulated industries who can't afford data handling mistakes.
Summary of Real User Reviews:
Detailed third-party review data for Marvel Marketing isn't as widely published as some other agencies on this list, so drawing direct comparisons is harder. That said, their model speaks for itself. The combination of a results-backed guarantee and deliberate client limits suggests a team that would rather do fewer things exceptionally well than take on volume at the expense of quality.
The starting point was a broad sweep of agencies operating across Canada, pulled from directories like Clutch, UpCity, agency-specific review platforms, and Google Business listings. The goal at this stage was building a wide longlist, not filtering yet. Agencies were flagged based on their presence in Canadian markets, the range of digital marketing services listed on their official sites, and whether they had any documented client history.
From that longlist, agencies without verifiable client results or independently published review records were set aside. The shortlisting process focused on identifying patterns across multiple signals: Were the reviews consistent? Did the agency's stated services match what clients actually described receiving? Agencies with thin public footprints or unverified claims were removed before deeper evaluation began.
Each agency's website claims were cross-referenced against third-party sources. If a firm claimed a specific award or recognition, that recognition was confirmed through the awarding organization's published records. Case study numbers (such as percentage increases in client acquisition or campaign performance improvements) were checked against what was publicly available on Clutch profiles and the agencies' own published materials. Claims that couldn't be traced to a source were discounted in the scoring.
Beyond standard service verification, each agency was assessed for its broader standing in the industry. This included award histories, mentions in recognized Canadian business publications, Google Partner or platform certifications, and any original research or published commentary the agency had produced. Recognition from credible external sources (like Google's global Search Innovation ranking for Dialekta or Globe and Mail top-company recognition for Kinex Media) added weight to an agency's overall assessment.
The final layer focused on digital marketing depth. Each agency needed dedicated, clearly defined service pages (not just a general "digital marketing" label), verified client reviews that referenced specific campaign types and measurable outcomes, and case studies that demonstrated performance across relevant channels. Agencies that only operated in one narrow service area without broader digital marketing capabilities were excluded from the final list, keeping the focus on firms that can genuinely support a business's full marketing needs.
Choosing an agency isn't just about who has the best website. The right fit depends on how well their strengths line up with what your business actually needs right now.
Here's what to look at before signing anything:
Canada has no shortage of digital marketing agencies, but the ones worth your budget share a few things in common: real industry experience, honest reporting, and results you can trace back to actual campaigns. Whether you need niche legal marketing like dNovo Group offers, enterprise-level performance work like Dialekta delivers, or a full-service setup like Major Tom provides, the best agency is the one built for your specific business stage and goals.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |

Last Updated: May 28, 2026
Status: Strengthening
Organizations: Bank of Canada, DTCC, Broadridge, NYSE, Securitize, FCA, LSEG, BIS
The answer is yes, but only in the right legal and market structure. Tokenized real world assets are becoming usable where regulators connect them to securities, custody, fund, settlement, collateral, payment, and investor protection rules. The strongest evidence is not speculative token launches. It is regulated infrastructure that can support bonds, Treasuries, funds, repo, collateral, transfer agency, and settlement.
The practical question is not whether RWAs can be tokenized. They can. NCFA has tracked this progression from experimentation to execution. Earlier evidence showed how tokenization started looking like financial infrastructure, while more recent developments show tokenization finding scale in collateral and cash. European policymakers are also advancing a roadmap for tokenized finance infrastructure, reinforcing the view that tokenization is increasingly being evaluated as market infrastructure rather than a standalone asset class.
The firms to watch are the ones building the boring middle layer. That means custody, transfer agency, collateral management, settlement links, reporting, governance, and legal certainty. RWA growth depends on trust and operating proof, not marketing.
Strategic Takeaway
Tokenized RWAs are becoming market infrastructure where legal rights, custody, settlement, collateral, and investor protections connect. The opportunity is not just putting assets on chain. It is making regulated assets easier to hold, move, finance, and reconcile inside trusted financial systems.
Click each item to expand
The Bank of Canada, Export Development Canada, RBC, TD, and RBC Investor Services completed a tokenized bond experiment using distributed ledger technology. This gives Canada a credible domestic proof point for tokenized securities infrastructure.
DTCC is preparing tokenized real world asset services for production use. This is important because DTCC sits inside regulated post trade infrastructure, not outside the system.
Broadridge’s Distributed Ledger Repo platform shows tokenization already operating in a serious institutional workflow. Repo is market plumbing tied to collateral, liquidity, and funding.
NYSE and Securitize agreed to support tokenized securities infrastructure, including standards for digital transfer agents and tokenization agents.
The UK FCA published rules and guidance for fund tokenisation, giving asset managers a practical framework for tokenized fund operations.
Project Agorá, led by the BIS with central banks and commercial banks, tests tokenized deposits and wholesale central bank money for cross border settlement. This matters because tokenized assets need a reliable cash leg.
Do you agree the evidence is strengthening?
 2
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 28, 2026 | NCFA Insight | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure

On May 26, 2026, the BIS released its 97 page Project Agorá report, detailing how a global public private prototype tested the feasibility of tokenized commercial bank deposits and wholesale central bank money for cross border payments. The report explains the project vision, who participated, what the prototype tested, what worked (or not), and what has to happen before any production system can operate at scale.
Project Agorá isn't a retail CBDC project, nor is it a stablecoin clone. It tests whether today’s correspondent banking system can use tokenized bank money and smart payment workflows to make wholesale cross border payments faster, safer, more transparent, and easier to coordinate.
Cross border payments totalled USD $195 trillion in 2024 and are projected to reach USD $320 trillion by 2032. Wholesale payments accounted for 91% of cross border payment value in 2023. These flows affect banks, PSPs, exporters, capital markets firms, treasury teams, and fintechs building around global money movement.
On May 27, 2026, the Bank of Canada joined Project Agorá, giving Canada a seat at the table and role in the next phase of testing. The Bank says the project has successfully tested the feasibility of a multi currency unified ledger that enables atomic settlement of wholesale cross border transactions.
The next phase will continue testing the prototype and examine how an Agorá type platform could operate under existing legal and regulatory frameworks, including settlement finality, anti money laundering rules, and terrorist financing rules.
Carolyn Rogers, Senior Deputy Governor, Bank of Canada:
“We know that the Canadian economy could benefit from innovation in cross-border payments. Tokenization has the potential to make these payments faster, cheaper and more efficient and secure. Project Agorá is a unique opportunity to test the technology across several jurisdictions and currencies, with the participation of private sector financial institutions.”
Project Agorá was convened by the BIS and the Institute of International Finance. It originally brought together 7 central banks and more than 40 regulated financial institutions, including banks, payment service providers, financial market infrastructures, and global payment networks.
The central bank group includes the Federal Reserve Bank of New York, Bank of England, Bank of France representing the Eurosystem, Bank of Japan, Bank of Mexico, Swiss National Bank, Bank of Korea, and now the Bank of Canada for the next phase. That makes Agorá a multi currency and multi jurisdiction test, not a single bank proof of concept.
The project keeps correspondent banking as the base model. Banks still manage customers, deposits, access, compliance, and balance sheet relationships. Central banks still control reserves and domestic policy settings. Agorá adds a shared programmable platform to coordinate the payment workflow.
The prototype uses a two layer architecture. (1) A unifying ledger records tokenized commercial bank deposits and coordinates the cross border workflow. (2) Separate jurisdictional ledgers record tokenized central bank reserves so each central bank keeps control over its own money, access rules, and policy settings.
The payment workflow has five stages. Agorá checks the payee, finds the payment route, confirms required checks, locks the needed balances, then settles the transaction. In report terms, those stages are confirmation of payee, path discovery, validation, locking, and settlement.
The order sequencing matters. Agorá checks the payment before banks lock up liquidity. It confirms the payee, route, required checks, and available balances first. Only then does settlement begin. That reduces the risk of finding a problem after money has already been committed.
 Source: Bank for International Settlements, Project Agorá, “Wholesale cross border payments today and in Project Agorá,” Figure 1.
The prototype showed that atomic settlement is achievable in a tokenized environment across the participating jurisdictions. This means that either every required balance update happens, or none of them happen. One leg of a transaction cannot settle while another fails.
The report says settlement can occur in seconds once funds or liquidity are locked. The platform is also designed to operate around the clock, which could reduce delays caused by time zones and market hours. That doesn't mean every payment becomes instant from start to finish. It means the settlement step can happen quickly after the required checks and liquidity locks are complete.
The prototype also showed that shared infrastructure doesn't require shared data by default. Participants can coordinate payment status, validation outcomes, and settlement without exposing customer data, internal risk models, or sensitive routing information to everyone on the platform.
The report identifies specific pain points in wholesale cross border payments. They include mismatched operating hours, sanctions and compliance false positives, serial processing, poor data quality, weak payment status visibility, unclear fees, liquidity pressure, settlement risk, reconciliation breaks, and client outreach.
These are practical banking problems. A false positive can stop a legitimate payment. A missing data field can trigger manual review. A payment status gap can leave banks and clients unsure where funds are stuck. A reconciliation break can create cost after settlement. Liquidity sitting in the wrong place can weaken treasury efficiency.
The report doesn't make cost reduction the main objective because many wholesale payment costs come from FX pricing and market structure. The stronger claim is narrower though. Fewer failed payments, investigations, returns, and reconciliation breaks could reduce operating drag if the model works in production.
Agorá doesn't try to centralize AML, counter terrorist financing, sanctions, fraud, or policy decisions. Each institution still performs its own checks inside its own systems. The platform coordinates only the outcomes needed to move the workflow forward.
This is important for banks who need shared infrastructure, but they don't want to expose customer information, proprietary screening logic, or internal compliance decisions to every other participant in a payment chain. Agorá uses scoped privacy and controlled information sharing so only relevant parties receive the data they need.
The result is a realistic compliance model for regulated institutions. It doesn't remove compliance work. It tries to reduce duplication, bring validations earlier in the process, and stop settlement from starting before required checks are complete.
The report’s legal analysis as tested in Agorá, found that tokenization doesn't fundamentally change the legal nature of money. Tokenized central bank reserves remain central bank reserves. Tokenized deposits remain commercial bank deposit obligations.
It suggests tokenized bank money can develop inside existing legal and regulatory frameworks instead of starting from a blank page. It also separates Agorá from private digital asset models where the legal nature of the claim can be less familiar.
The report doesn't claim every legal issue is solved however. Settlement finality is achievable across the participating jurisdictions, but production deployment would still need rulebooks, contractual frameworks, liability rules, governance, data rules, insolvency treatment, and clear legal effect across jurisdictions.
The strongest benefits are operational. Agorá could give banks better payment status visibility, earlier data checks, fewer late stage failures, faster settlement after liquidity is locked, and more predictable workflows across currencies.
Treasury teams could benefit from better liquidity coordination. Cross border payments today can require prefunding, manual investigation, and treasury allocation across time zones. Agorá’s design could reduce some of that friction by coordinating payment paths, validations, balance locks, and settlement in one workflow.
The risks are in production execution. The report says the prototype didn't prioritize production grade performance, cyber security, or liquidity saving tools. It also left FX integration and other tokenized asset classes outside scope.
A real system would need to connect with existing bank infrastructure and prove it can operate under stress. That means strong governance, resilience testing, failover, monitoring, and clear performance benchmarks.
The Bank of Canada is now involved, but commercial value depends on private sector participation. Canadian banks, PSPs, market infrastructure providers, and fintechs need a role in testing, rule design, and integration.
For fintechs, the opportunity is to build around the workflow through compliance tools, privacy technology, treasury systems, FX routing, liquidity optimization, reconciliation software, APIs, and analytics.
Agorá gives banks and central banks a regulated alternative to stablecoin settlement networks, but only if the next phase proves it can handle real value, real liquidity, and real operating rules.
If Project Agorá evolves from prototype to real value settlement, will tokenized bank deposits become the regulated answer to stablecoin driven cross border payments?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Last Updated: May 28, 2026
Status: Building
Organizations: SoFi, Department of Finance Canada, Bank of Canada, FCA, UK Government
The answer is yes, but not because stablecoins are leaving crypto behind. They are expanding from crypto market use into banking apps, remittances, reserve models, and payment policy. The test is no longer whether tokens can move on chain. The test is whether they can move money inside regulated financial systems.
The link to payment access is important. Stablecoins need banking partners, reserves, payment gateways, custody controls, and settlement routes. That connects directly to limited direct settlement access, because stablecoin utility depends on how close non bank firms can get to trusted payment and reserve infrastructure.
The firms to watch are the ones that can make stablecoins boring enough to use. That means clean reserves, clear redemption, strong compliance, distribution reach, and payment flows that solve real problems.
Strategic Takeaway
Stablecoins are expanding into payment infrastructure where they connect trusted reserves, regulated distribution, and real money movement. The strongest players may be firms that can make tokenized money useful without making users think about crypto at all.
Click each item to expand
SoFiUSD shows stablecoins moving into mainstream financial distribution. The product is positioned as a bank issued, 1:1 redeemable U.S. dollar stablecoin inside the SoFi app.
Canada’s framework gives the stablecoin infrastructure question a domestic policy base. It moves stablecoin activity toward rules for issuance, reserves, custody, redemption, governance, and oversight.
UK policy work shows regulators treating stablecoins as potential payment instruments, not only crypto assets. That means issuance, custody, reserves, and payment services are becoming connected policy questions.
Do you agree the evidence is strengthening?
1
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Last Updated: May 27, 2026
Status: Building
Organizations: Federal Reserve, Neo, Interac, Tether, Government of Georgia
The answer is moving toward yes, but through tighter gates. Regulators are not opening settlement systems to every fintech. They are testing whether some firms can reach parts of the settlement layer without becoming banks.
Canada already allows some narrower access models through Interac participation and registered payment frameworks. The next pressure point may come from real time payments, stablecoin reserve treatment, tokenized settlement, or cross border payment competition from outside Canada.
The firms to watch are not necessarily the biggest fintechs. The advantage may go to companies that can prove resilience, compliance depth, operational uptime, fraud controls, and trusted movement of funds at scale. Regulators appear more willing to test narrower infrastructure access when the activity is tightly defined and operationally mature.
Strategic Takeaway
Limited direct settlement access is becoming a middle layer between sponsor bank dependence and full banking status. That could reshape who controls payment flow, customer relationships, settlement logic, and financial infrastructure over the next few years.
Click each item to expand
The Fed proposal separates limited payment access from full banking status. It gives regulators a way to test settlement and reserve functions without granting the full benefits of a Master Account.
Neo’s Interac access gives the Canadian market a practical proof point. Direct rail participation can improve control over payment flow without turning a fintech into a full bank.
The Georgia stablecoin plan shows why this question is moving beyond traditional payment rails. Stablecoins can connect payments, remittances, programmable finance, and national digital infrastructure.
Do you agree the evidence is strengthening?
0
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 27, 2026 | NCFA Market Activity | Risk Compliance And Regtech, Banking And Credit Infrastructure, Artificial Intelligence And Data
On May 20, 2025, Montreal based Novisto announced a USD $27M Series C round led by Inovia Capital, with White Star Capital, SCOR Ventures, and Sagard participating. Novisto says the financing brings its total funding to more than USD $55M. The money comes as ESG reporting moves away from wide sustainability claims and into data controls, audit trails, and disclosure risk.
On April 23, 2025, the Canadian Securities Administrators paused mandatory climate and diversity disclosure rules, but greenwashing risk remains high Issuers gained more time on reporting. Unsupported environmental claims still carry legal and reputational risk.
The Competition Bureau’s environmental claims guidance expects businesses to back green claims with evidence. NCFA previously wrote about Canada’s updated rules for environmental claims which explains why sustainability language now needs verification records behind it. Yes, that includes many types of fintech firms, such as ESG data analytics, carbon platforms, and investor communications.
Novisto helps companies turn scattered sustainability data into usable reporting records. That means cleaner source data, clearer approvals, and stronger evidence when claims face review.
Revenue almost tripled since Novisto’s 2023 Series B. Clients also reported a 50% reduction in time spent completing reporting assessments. Enterprise buyers are still spending because ESG data now needs source records, approvals, and proof.
Novisto also points to AI powered ESG data automation and audit readiness. AI can speed up extraction, benchmarking, and disclosure mapping, but bad records still break automated reporting systems. Financial institutions already know this from credit, fraud, risk, and regulatory reporting.
Novisto plans to use the financing to expand in Europe. Sanofi used Novisto to produce one of the first 15 CSRD compliant reports released in 2025. Emirates Group is a recent customer, and S&P Global is a distribution partner.
Europe gives Canadian regtech firms a live commercial opening. Large enterprises now need systems that can defend sustainability disclosures under tighter reporting standards for boards, CFOs, auditors, regulators and investors. No more spreadsheet cleanup before every reporting cycle.
For financial institutions, OSFI’s climate risk guideline still expects federally regulated financial institutions to manage climate related risk through governance and disclosure. That keeps climate and sustainability data tied to risk controls, not just communications.
If green claims need proof now, how should Canada balance slower climate disclosure rules with tougher greenwashing enforcement so credible reporting infrastructure wins and weak ESG claims lose market trust?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016